
 SIP Trunking Services Market | 2026-2036
SIP Trunking Services Market Size, Share, and Industry Trends Forecast 2026-2036
SIP Trunking Services Market Outlook
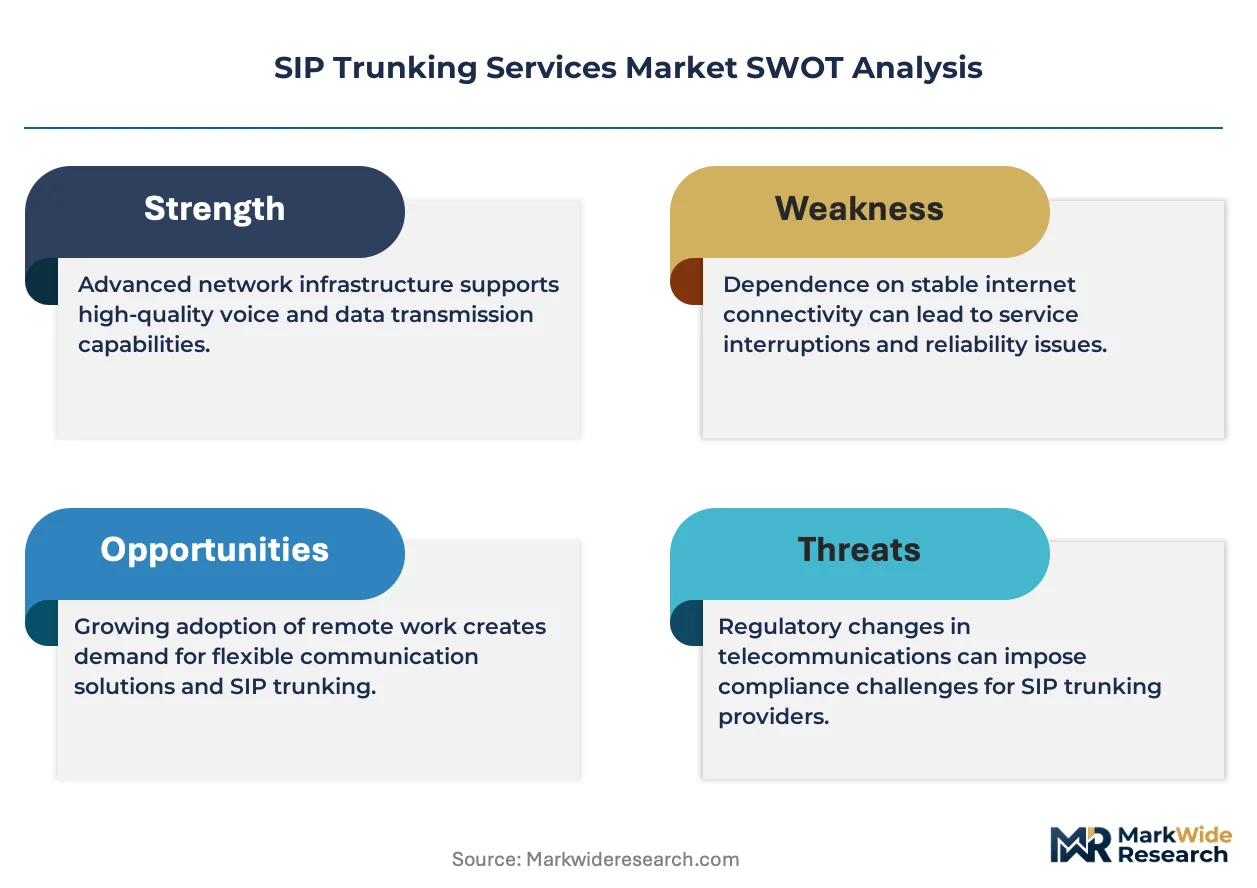
Healthcare enterprise communications is decoupling from traditional PRI circuits as hospitals and telemedicine networks demand elastic session capacity. Twilio Inc. leverages programmable APIs to embed voice routing directly into clinical workflow applications. AT&T Inc. anchors nationwide trunking through its fiber backbone and direct SS7 interconnection heritage. Verizon Communications Inc. competes on enterprise SLA density, offering geographically redundant session border controller deployments.
SIP trunking services deliver VoIP connectivity between enterprise PBX systems and public telephone networks using Session Initiation Protocol signaling, typically supporting G.711 and G.729 codecs with mean opinion score thresholds above 3.5 for toll-quality voice. These services eliminate physical copper trunk lines by routing calls over broadband internet or dedicated MPLS links. Cloud-based deployment now leads growth trajectories as multi-tenant platforms reduce capital expenditure for mid-market buyers. Voice service type still occupies the largest revenue pool, though video trunking for unified communications shows the steepest expansion curve. Large enterprises dominate current subscription volumes, yet SMEs represent the fastest-growing customer type as bundled UCaaS offerings lower entry barriers.
The FCC enforces STIR/SHAKEN attestation levels to combat illegal robocalling, compelling trunking providers to implement cryptographic call authentication or face service-blocking penalties from downstream carriers. In Europe, the EECC framework mandates all-interoperable emergency calling and number portability, directly shaping product requirements for cross-border trunking vendors. Enterprises evaluating trunking partners must now weigh compliance automation capabilities alongside per-minute pricing, as regulatory non-compliance triggers immediate carrier disconnection without appeal windows.
Market Dynamics
Enterprise migration from TDM to IP voice networks is compressing replacement cycles and forcing carriers to reprice session capacity as a commodity utility rather than a premium circuit service.
Growth Catalysts
- FCC STIR/SHAKEN Mandate:The framework compels carriers to implement cryptographic call authentication, creating upgrade revenue streams for compliant trunking providers as non-compliant vendors face service-blocking penalties.
- Healthcare Cloud Communications:Hospitals and telemedicine networks demand elastic session capacity for clinical workflow integration, replacing fixed PRI circuits with metered SIP capacity.
- G.729 Codec Efficiency:Bandwidth-optimized voice compression enables quality transmission over consumer broadband, expanding addressable markets beyond MPLS-dependent enterprises.
Market Restraints
- Last-Mile Copper Dependence:Rural enterprise locations without fiber access cannot achieve the latency thresholds required for toll-quality VoIP, constraining geographic expansion.
- Session Border Controller Concentration:Four vendors control 70% of enterprise-grade SBC deployments, creating supply risk and limiting price negotiation leverage for trunking resellers.
- EECC Emergency Calling Mandates:European carriers must maintain location-accurate emergency routing across borderless trunking, adding compliance cost layers that compress margins on cross-border services.
Strategic Opportunities
- UCaaS Bundling for SMEs:Mid-market buyers seek consolidated voice, video, and messaging subscriptions, creating attach-rate expansion for trunking providers with platform partnerships.
- Video Trunking Acceleration:Unified communications platforms are converging voice and video session management, opening higher-ARPU service tiers as enterprises consolidate vendors.
- India's Digital Communications Push:TRAI's cloud telephony guidelines are formalizing previously gray-market VoIP services, enabling licensed trunking entry into a previously restricted enterprise segment.
Industry Challenges
- SS7 Interconnection Expertise Scarcity:The talent pool fluent in legacy signaling translation to IP is aging out, forcing carriers to retain expensive specialists or risk call routing failures.
- Multi-Vendor Integration Complexity:Enterprises demand seamless handoffs between premise PBX, cloud contact center, and carrier trunking, requiring custom API development that strains professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SIP Trunking Services Market |
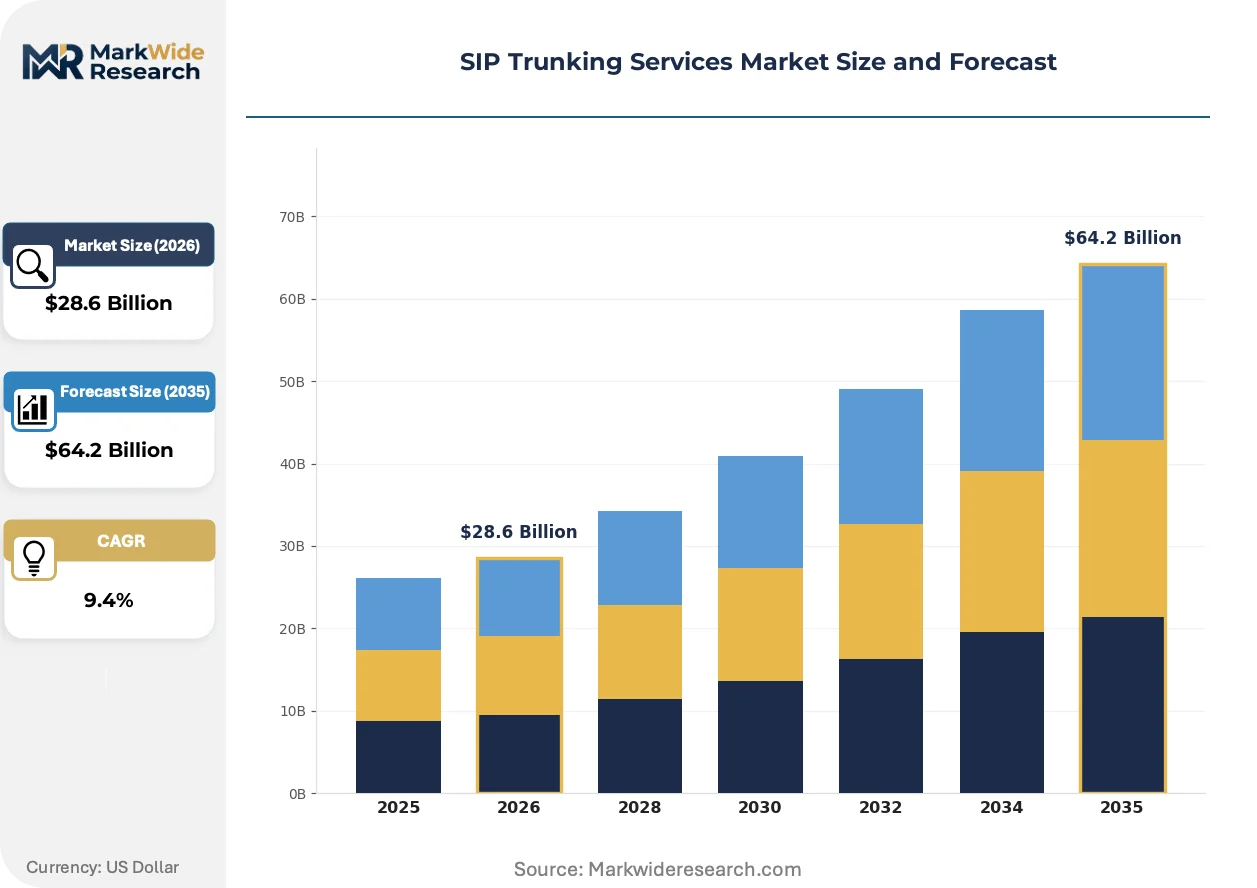
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice, Video, Fax, Data Deployment: On-Premise, Cloud-Based, Hybrid, Private Customer Type: SMEs, Large Enterprises, Government Agencies, Educational Institutions Integration Level: Full Integration, Partial Integration, Standalone, Custom Solutions |
| Companies Covered | Twilio Inc., AT&T Inc., Verizon Communications Inc., Bandwidth Inc., RingCentral, Vonage, Nextiva, 8x8, Lumen Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SIP Trunking Services Market Strategic Shifts
Programmable communications APIs are embedding voice routing directly into vertical applications, collapsing the distinction between connectivity infrastructure and software workflow layers.
Cloud-native session border controllers are overtaking appliance-based deployments in enterprise trunking architectures. Mid-market buyers prioritize auto-scaling subscription models over capital-intensive hardware procurement. This shift is compressing vendor margins while expanding addressable customer bases beyond traditional carrier-direct relationships.
The FCC's STIR/SHAKEN attestation tier system is reshaping intercarrier compensation structures. Full A-level attestation requires direct relationship documentation, forcing resellers to consolidate upstream contracts or accept B-level pricing discounts. Tier-1 carriers are responding by acquiring attestation-capable intermediaries to protect termination revenue.
Consumption-based billing models are displacing committed-use contracts in enterprise procurement. Finance teams favor opex-aligned spend that tracks actual session volumes against departmental budgets. This pattern is most visible in United States healthcare systems where telemedicine volume volatility makes fixed trunk commitments economically untenable.
SIP Trunking Services Market Segmentation
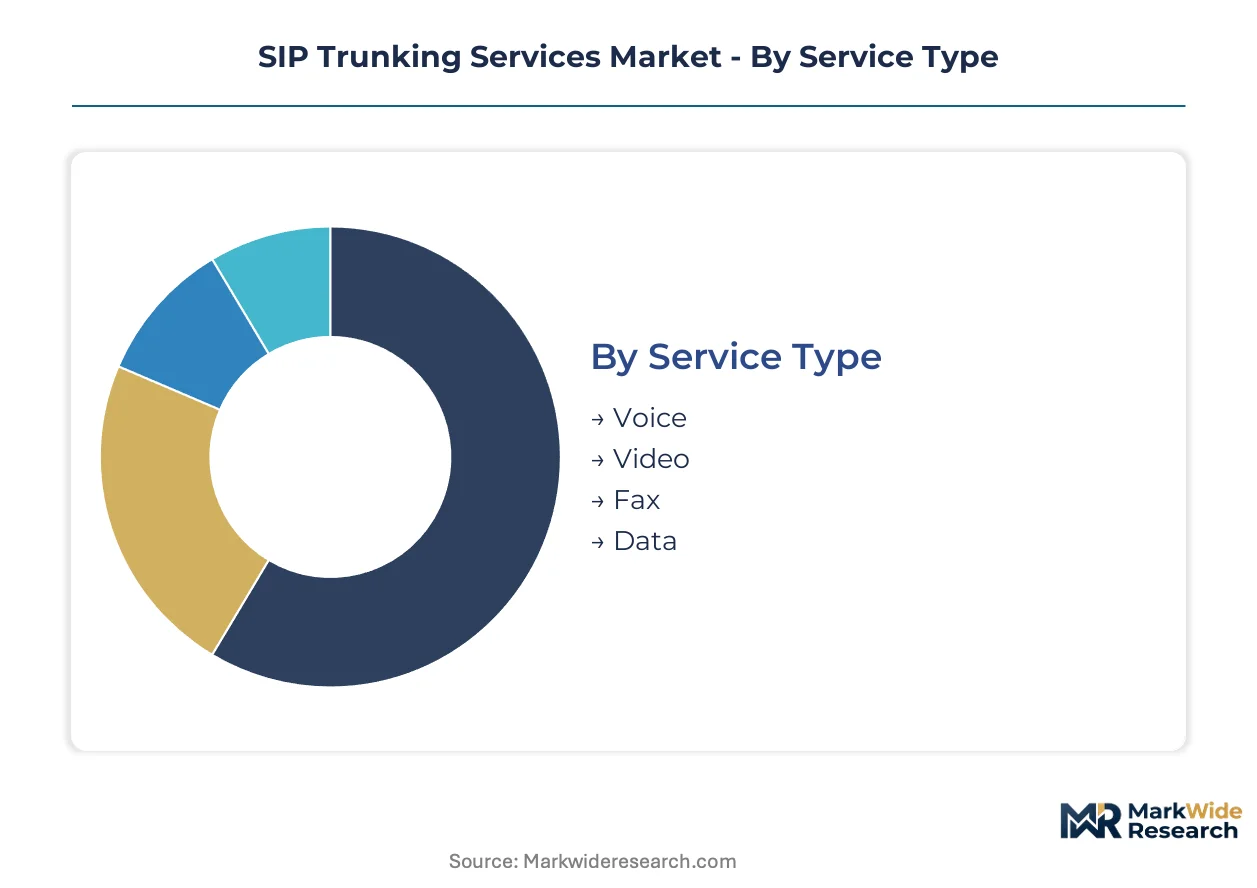
SIP trunking providers configure service architectures around four distinct axes: payload type, infrastructure location, buyer scale, and systems connectivity. Each axis creates divergent margin profiles and sales cycle dynamics that shape go-to-market investment priorities.
Service Type:
Buyers prioritize session payload based on codec requirements, bandwidth budgets, and compliance exposure for stored communications.
- Voice:G.711 and G.729 codec support dominates enterprise procurement, with mean opinion score thresholds above 3.5 defining toll-quality minimums. Healthcare systems in the United States drive elastic capacity demand as telemedicine volume volatility renders fixed PRI circuits economically untenable.
- Video:Unified communications platforms are converging voice and video session management, requiring H.264 and VP8 codec negotiation alongside SIP signaling. Large enterprises consolidate vendors around higher-ARPU service tiers that bundle HD video trunking with quality-of-service guarantees.
- Fax:T.38 protocol support maintains compliance document transmission for legal and healthcare workflows where email fails regulatory audit trails.
- Data:Session border controllers route non-voice payloads including SMS and IoT signaling traffic over shared SIP infrastructure.
Volume sits with Voice; growth tilts toward Video.
Deployment:
Infrastructure location determines capital intensity, operational control depth, and regulatory data residency obligations.
- Cloud-Based:Multi-tenant platforms with auto-scaling subscription models expand addressable markets beyond traditional carrier-direct relationships. Mid-market buyers favor opex-aligned spend that tracks actual session volumes against departmental budgets.
- On-Premise:Appliance-based session border controllers retain favor among financial services firms requiring air-gapped call routing and custom encryption modules.
- Hybrid:Split architectures route sensitive traffic through premise SBCs while bursting overflow to cloud trunks during peak demand windows.
- Private:Dedicated instance deployments satisfy government agencies with FedRAMP authorization requirements and strict data sovereignty mandates.
Revenue concentrates in Cloud-Based; margin protection favors Private.
Customer Type:
Procurement sophistication and contract structure vary sharply across buyer scale and institutional mission.
- Large Enterprises:Geographically redundant session border controller deployments with enterprise SLA density anchor carrier-direct relationships. Finance teams negotiate committed-use contracts with steep volume discounts and custom API development for premise-to-cloud handoffs.
- SMEs:Mid-market buyers seek consolidated voice, video, and messaging subscriptions through UCaaS platform partnerships that lower entry barriers. Bundled offerings create attach-rate expansion opportunities for trunking providers without direct sales force investment.
- Government Agencies:FedRAMP authorization and STIR/SHAKEN attestation compliance gate vendor selection, favoring Tier-1 carriers with direct SS7 interconnection heritage.
- Educational Institutions:K-12 districts and university systems prioritize E-Rate funding eligibility and emergency calling location accuracy across distributed campuses.
Subscription volume dominates among Large Enterprises; SME expansion climbs the fastest.
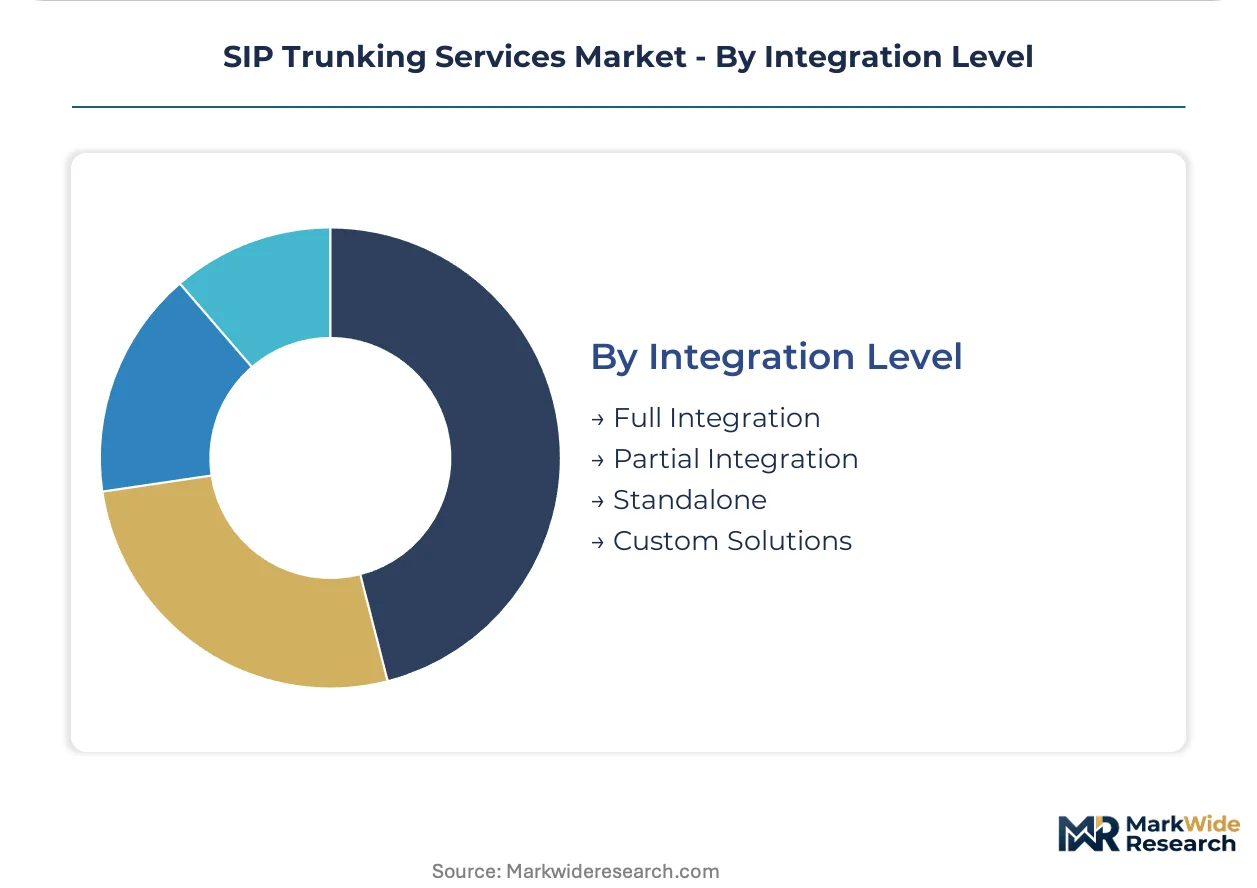
Integration Level:
Systems connectivity depth determines professional services burden and customer lifetime value trajectory.
- Full Integration:Programmable APIs embed voice routing directly into vertical applications, collapsing distinctions between connectivity infrastructure and software workflow layers. Twilio Inc. leverages this architecture for clinical workflow integration in healthcare settings.
- Partial Integration:Limited CRM or contact center connectivity satisfies buyers with standardized PBX configurations and modest customization requirements.
- Standalone:Basic SIP trunking without upstream application integration serves price-sensitive buyers migrating from legacy TDM circuits.
- Custom Solutions:Multi-vendor handoffs between premise PBX, cloud contact center, and carrier trunking demand custom API development that strains professional services capacity.
Deployment complexity peaks with Custom Solutions; scalability favors Full Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise zones in Singapore and Dubai drive telecommunications infrastructure concentration as governments deploy tax incentives for data center and carrier hotel investments. These zones attract trunking providers seeking low-latency interconnection points between Asia-Pacific and Middle Eastern markets.
United States
Healthcare systems and financial services firms demand elastic SIP capacity for telemedicine and trading floor applications. The FCC enforces STIR/SHAKEN attestation tiers that compel carriers to implement cryptographic call authentication or face downstream blocking. Northern Virginia's Ashburn corridor hosts the densest concentration of session border controllers and carrier-neutral peering facilities.
Germany
Industrial manufacturers replace legacy ISDN circuits with IP trunking for factory automation and supply chain integration. The national telecom regulator mandates all-interoperable emergency calling with location accuracy requirements under the EECC framework. Frankfurt's Mainova data center cluster anchors cross-border trunking interconnection for Central European enterprises.
United Kingdom
Legal and professional services firms require T.38 fax protocol support for compliance document transmission. Ofcom enforces number portability and emergency service routing obligations that shape product specifications for trunking vendors. London's Docklands hosts the primary carrier exchange points connecting UK enterprises to transatlantic submarine cable systems.
India
IT services exporters and domestic e-commerce platforms scale cloud contact center capacity using metered SIP trunks. TRAI's cloud telephony guidelines formalize previously gray-market VoIP services and establish licensing frameworks for enterprise trunking. Bangalore's Electronic City and Hyderabad's HITEC City concentrate software development centers driving programmable communications API demand.
SIP Trunking Services Market Competitive Environment
Top-tier vendors anchor nationwide fiber backbone deployments, while regional specialists compete on vertical-specific compliance automation. The market structures around three concentration tiers: Tier-1 carriers with direct SS7 interconnection heritage, platform-native providers with programmable API architectures, and wholesale aggregators serving reseller channels. Strategic archetypes include infrastructure-heavy incumbents, software-centric disruptors, and compliance-focused healthcare specialists. Dominant competitive moves involve acquiring attestation-capable intermediaries and forming UCaaS platform partnerships to capture SME attach-rate expansion.
Within the programmable API tier, Twilio Inc. and Bandwidth Inc. exemplify the architecture embedding voice routing directly into clinical and customer workflow applications. AT&T Inc. anchors the infrastructure-heavy archetype through nationwide fiber coverage and intergenerational signaling translation capabilities. These three entities occupy distinct positioning vectors that shape how enterprise buyers evaluate trunking partnerships against compliance automation and integration depth criteria.
| Leading Market Players |
|---|
| Twilio Inc. |
| AT&T Inc. |
| Verizon Communications Inc. |
| Bandwidth Inc. |
| RingCentral |
| Vonage |
| Nextiva |
| 8x8 |
| Lumen Technologies |
| Others |
Value Chain & Pricing Dynamics
Broadband commodity price indices cascade through SIP trunking supply chains, compressing per-minute rates as carriers pass fiber cost reductions to enterprise buyers while session border controller hardware premiums persist for compliance-intensive deployments.
Pricing Analysis
Short lead-time provisioning commands premium pricing for enterprises requiring sub-48-hour trunk activation, while spot inventory of pre-configured capacity trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates geographically redundant SBC deployments from single-point configurations and best-effort broadband trunks. Price differentiation hinges on attestation tier certification and geographic SLA density, with A-level STIR/SHAKEN compliance carrying material premiums. Margins are tightening due to wholesale commoditization of metered voice minutes. SMEs exhibit highest price sensitivity, driving bundled UCaaS procurement; financial services firms show lowest sensitivity, prioritizing FedRAMP-authorized private deployments.
Supply Chain Analysis
Reverse logistics for session border controller hardware encompasses refurbishment programs for enterprise appliance trade-ins and remanufacturing flows for carrier-grade chassis redeployment. Supply concentrates in Taiwan for semiconductor components, China for optical transceivers, and the United States for specialized signaling software. Raw material dependencies include silicon photonics chips, FPGA processors, and copper cabling for last-mile termination. Single-source vulnerability characterizes enterprise-grade SBC silicon from four dominant vendors. Distribution runs through carrier-direct channels for large enterprises and wholesale aggregators serving regional reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SIP trunking markets are becoming a vertical-integration race, with carriers acquiring programmable API platforms to capture software-layer margins previously ceded to cloud communications specialists.
For Market Incumbents: Deepen upstream control over session border controller manufacturing to reduce hardware cost exposure from concentrated silicon vendors. Consolidate attestation-capable intermediary acquisitions before Tier-1 competitors exhaust acquisition targets. Defend against platform-native disruptors by embedding programmable voice APIs into vertical workflow applications for healthcare and financial services segments.
For New Entrants and Emerging Players: The price-point gap between premium MPLS-dependent trunks and economy broadband offerings creates entry space for mid-market buyers seeking quality-of-service guarantees without carrier-direct pricing. Target India's formalizing cloud telephony segment under TRAI guidelines, where licensed trunking replaces previously gray-market VoIP. Pursue SME attach-rate expansion through UCaaS platform partnerships rather than direct sales force investment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor programmable API specialists with healthcare workflow integration capabilities in the United States, where telemedicine volume volatility sustains elastic capacity demand. Long-term viability centers on carriers with direct SS7 interconnection heritage and STIR/SHAKEN attestation infrastructure. Monitor FCC enforcement actions against non-compliant vendors as inflection indicator for consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Attestation-Capable Intermediary Acquisition | Tier-1 carriers acquire A-level attestation providers to protect termination revenue under FCC STIR/SHAKEN mandates. |
| UCaaS Platform Partnership | Trunking providers bundle voice capacity with unified communications platforms to capture SME attach-rate expansion. |
| Cloud-Native SBC Deployment | Auto-scaling subscription models displace appliance-based procurement, expanding addressable markets beyond carrier-direct relationships. |
| Vertical Workflow API Integration | Programmable voice routing embeds directly into clinical and trading floor applications, collapsing infrastructure-software boundaries. |
| Geographic Redundancy Expansion | Multi-point SBC deployments satisfy enterprise SLA density requirements in financial services and healthcare segments. |
Study Parameters
Document review covered FCC STIR/SHAKEN implementation orders, TRAI cloud telephony guidelines, EECC framework directives, and carrier tariff filings, complemented by interviews with network operations executives at Tier-1 carriers, UCaaS platform product managers, healthcare IT procurement directors, and session border controller vendor sales engineers. Secondary validation drew from SEC 10-K telecommunications disclosures, peeringDB interconnection databases, and enterprise voice spend surveys. Bottom-up trunk volume modeling and top-down carrier revenue analysis were triangulated against regulatory compliance cost estimates.
Cross-reference between historical session growth patterns and expert panel input on telemedicine adoption trajectories shaped the analytical framework across the analysis window. Segmentation dimensions modeled include service type, deployment architecture, customer scale, and integration depth, with geographic regulatory clusters treated as distinct forecast inputs. CAGRs were derived from elasticity-adjusted demand curves and carrier capacity expansion announcements. Industry-specific inputs encompassed STIR/SHAKEN attestation tier migration timelines and G.729 codec penetration rates in broadband-dependent segments.
Inputs from carrier network planning departments and UCaaS platform engineering teams were available through the study window; gaps in real-time enterprise trunk migration data introduce uncertainty bands around SME adoption velocity. Forecasts reflect assumptions regarding regulatory enforcement consistency and fiber infrastructure buildout continuity. Practitioners should monitor FCC attestation tier compliance deadlines and TRAI licensing enforcement actions for early signals of competitive restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
United Kingdom Telecom Market
Telecommunications
Egypt Telecom Market
Telecommunications
Myanmar ICT Market
Telecommunications
Mission Critical Communication (MCX) Market
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Switzerland Telecom Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
Private Branch Exchange Market
Telecommunications
Belgium ICT Market
Telecommunications
DWDM System Market
Telecommunications
Thailand Telecom Market
Telecommunications
China ICT Market
Telecommunications
TV White Space Spectrum Market
Telecommunications
Global 5G Base Station Market
Telecommunications
5G Connections Market
Telecommunications
Diameter Signaling Market