
 Vacuum Pressure Sensors Market | 2026-2036
Vacuum Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Pressure Sensors Market Analytics
Specialized distributor networks serving cleanroom equipment OEMs is reconfiguring as direct procurement from sensor manufacturers intensifies. MKS Instruments leverages in-house thin-film fabrication to sustain premium positioning in semiconductor metrology. Pfeiffer Vacuum Technology AG anchors European supply through captive vacuum gauge production. INFICON Holding AG differentiates via mass spectrometer-integrated pressure monitoring for process analytical technology.
Vacuum pressure sensors measure gas pressure below atmospheric conditions, typically spanning the rough, fine, high, and ultra-high vacuum ranges with detection thresholds reaching 10⁻¹² mbar depending on transducer architecture; these devices enable critical process control in thin-film deposition, leak detection, and cryogenic systems where atmospheric contamination risks catastrophic yield loss. Digital sensors lead product type revenue owing to Industry 4.0 retrofit cycles, while capacitive variants capture fastest growth in semiconductor etch chambers demanding radiation-hardened feedback. Electromechanical technology occupies mature margin pools in automotive brake booster testing, whereas thermal conductivity architectures dominate research laboratory installations requiring wide-range measurement without gas species dependency.
The EPA regulates vacuum pump emissions in US manufacturing through NESHAP standards, while REACH compliance in Europe restricts mercury-containing thermocouple gauges and drives solid-state substitution. Japan's METI enforces JIS standards for vacuum measurement traceability in national research facilities. Stakeholders must monitor evolving PFAS restrictions that threaten fluorocarbon-based sensor seal materials and assess alternative elastomer compatibility with ultra-high vacuum environments.
Market Dynamics
Semiconductor fabrication expansion in East Asia is concentrating vacuum pressure sensor procurement through direct OEM-manufacturer relationships, bypassing traditional distribution layers that historically served cleanroom equipment integrators.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases are accelerating replacement of mercury thermocouple gauges with solid-state capacitive sensors in European process industries.
- Advanced packaging corridors:China's semiconductor substrate facilities are scaling atomic layer deposition capacity, requiring ultra-high vacuum metrology with 10⁻¹² mbar detection thresholds.
- MEMS miniaturization:Silicon-based Pirani gauge arrays are displacing bulky glass-envelope designs in portable leak detection equipment for hydrogen fuel cell manufacturing.
Market Restraints
- Raw material concentration:High-purity alumina ceramic substrates for capacitive diaphragm sensors source predominantly from Japanese suppliers, creating single-point vulnerability.
- PFAS seal restrictions:REACH and emerging state-level prohibitions on perfluoroelastomers threaten fluorocarbon O-ring compatibility with ultra-high vacuum bake-out protocols.
- Calibration infrastructure scarcity:National metrology institutes maintain only seventeen primary vacuum standards worldwide, constraining traceability for emerging market manufacturers.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor fabrication are attracting vacuum equipment OEMs to Gujarat and Tamil Nadu, creating greenfield sensor specification windows.
- Mass spectrometer convergence:Residual gas analysis integration with pressure monitoring is enabling single-port process analytical technology in pharmaceutical lyophilization.
- Service unbundling:Predictive maintenance contracts for sensor drift correction are opening recurring revenue streams distinct from hardware replacement cycles.
Industry Challenges
- Cleanroom technician scarcity:Vacuum system calibration requires ISO Class 5 environment certification that fewer field service engineers now hold.
- Legacy protocol fragmentation:Analog 4-20 mA, DeviceNet, and emerging OPC UA architectures coexist in semiconductor fabs, complicating Industry 4.0 retrofit integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Pressure Sensors Market |
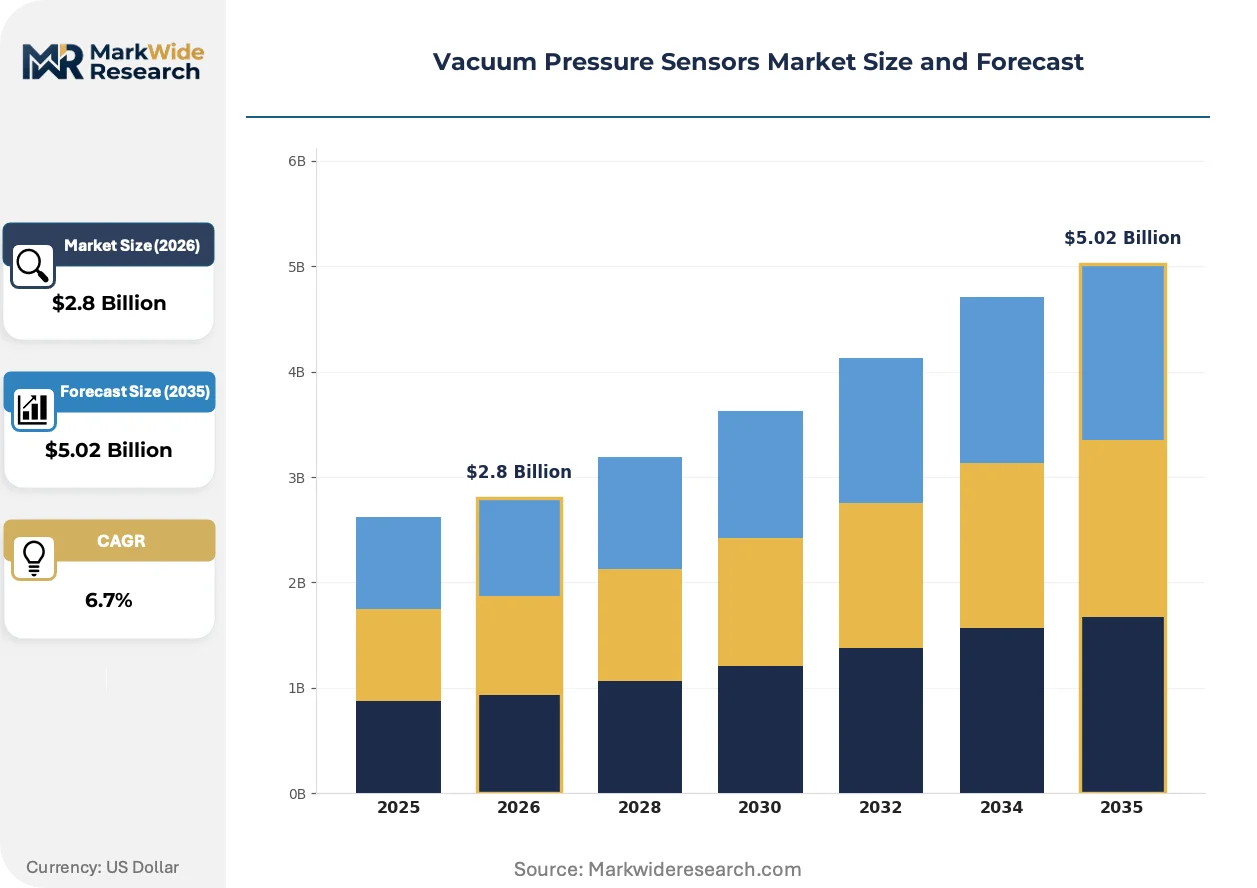
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Sensors, Digital Sensors, Capacitive Sensors, Piezoelectric Sensors Technology: Thermal Conductivity, Resistive, Optical, Electromechanical Application: Industrial Automation, Automotive Testing, Semiconductor Manufacturing, Healthcare Equipment End User: Manufacturing, Aerospace, Research Laboratories, Food Processing |
| Companies Covered | Honeywell International Inc., MKS Instruments, Inc., Pfeiffer Vacuum Technology AG, INFICON Holding AG, Edwards Vacuum, Emerson Electric Co., ABB, Amphenol Corporation, Sensata Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Pressure Sensors Market Evolving Landscape
Digital twin architectures are virtualizing sensor calibration workflows, compressing validation timelines while introducing cybersecurity exposure at the process control layer.
MEMS-based Pirani gauge arrays are virtualizing traditional thermocouple and convection gauge form factors. Semiconductor equipment OEMs in South Korea and Taiwan are specifying these solid-state replacements for etch chamber pressure interlocks. The technology is virtualizing maintenance schedules by enabling predictive drift algorithms that reduce unplanned downtime.
Japan's METI has tightened JIS Z 8751 vacuum measurement traceability requirements for national research facilities, mandating documented calibration chain custody. This policy is forcing sensor manufacturers to establish domestic service depots or partner with certified Japanese calibration laboratories. High-energy physics installations and fusion research programs represent the most affected procurement segments.
Direct procurement from sensor manufacturers is displacing specialized distributor networks that historically served cleanroom equipment integrators. Equipment OEMs in China's Yangtze River Delta are consolidating vendor lists to capture volume pricing and technical support proximity. This channel compression is most visible in flat-panel display fabrication, where BOE and CSOT have established preferred supplier frameworks bypassing regional distributors entirely.
Vacuum Pressure Sensors Market Segmentation
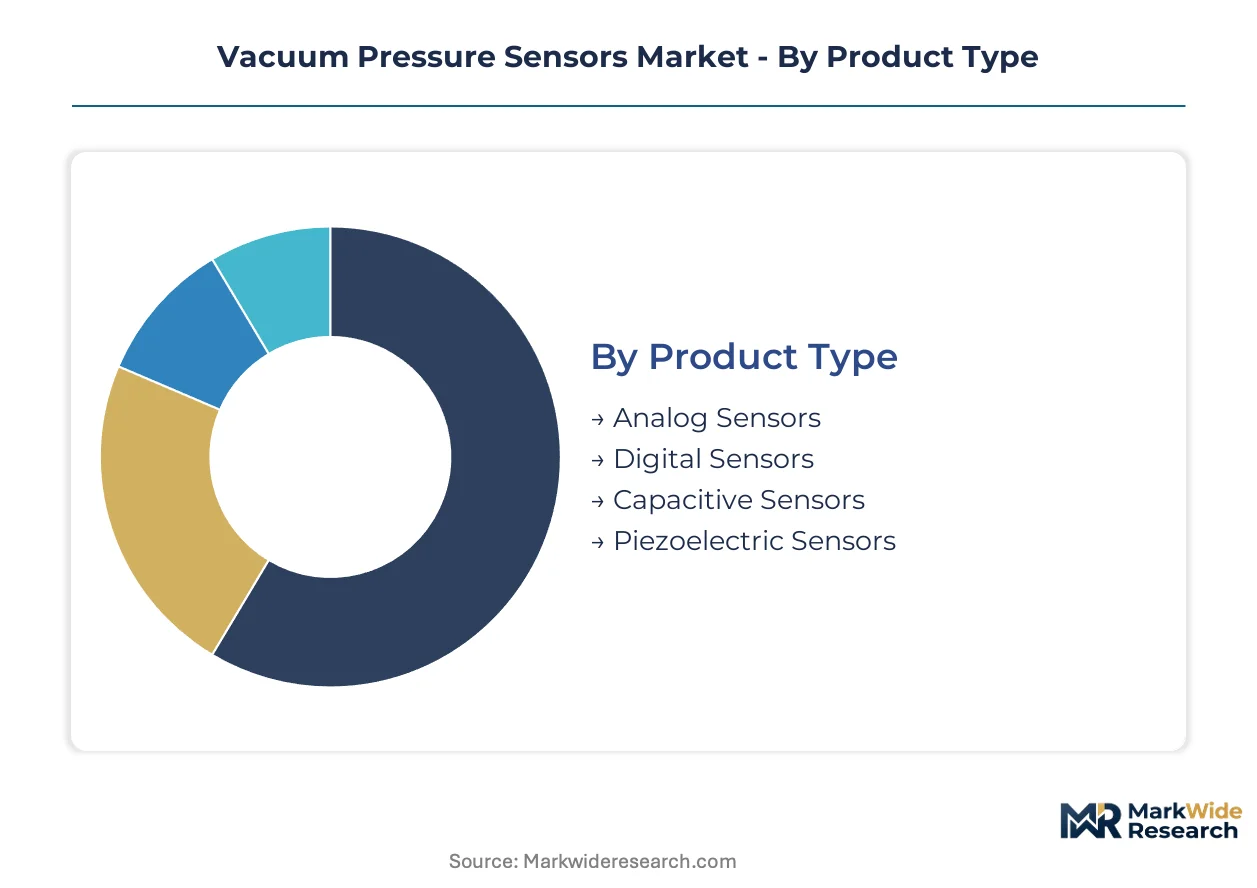
Vacuum pressure sensor procurement patterns diverge sharply across technical specifications and end-use environments. After-sales calibration intensity varies by segment, with semiconductor fabs demanding quarterly drift correction while automotive testing tolerates annual verification cycles.
Product Type:
Sensor architecture determines service contract attach rates, with solid-state designs requiring predictive maintenance algorithms and legacy analog units needing manual recalibration.
- Digital Sensors:Industry 4.0 retrofit cycles in East Asian semiconductor fabs drive specification of IO-Link and EtherCAT-compatible transducers. South Korea's memory chip clusters specify these for etch chamber pressure interlocks where real-time data logging supports predictive maintenance.
- Capacitive Sensors:Radiation-hardened diaphragm designs withstand plasma etch environments. China's advanced packaging corridors in Jiangsu and Zhejiang provinces scale atomic layer deposition capacity requiring 10⁻¹² mbar detection thresholds.
- Analog Sensors:Mature 4-20 mA output devices persist in legacy automotive brake booster testing lines where protocol migration lags.
- Piezoelectric Sensors:Quartz crystal microbalance variants serve cryogenic vacuum systems in fusion research programs.
By volume, Digital Sensors lead. By growth pace, Capacitive Sensors is ahead.
Technology:
Measurement physics dictates cost tiers and geographic supply concentration, with thermal conductivity gauges sourcing from established European specialists and MEMS-based alternatives emerging from East Asian foundries.
- Thermal Conductivity:Pirani gauge architectures dominate research laboratory installations requiring wide-range measurement without gas species dependency. Japan's METI enforces JIS Z 8751 traceability standards for national research facilities, mandating documented calibration chain custody.
- Resistive:MEMS miniaturization displaces bulky glass-envelope designs. Silicon-based Pirani arrays enable portable leak detection equipment for hydrogen fuel cell manufacturing in South Korea and Taiwan.
- Optical:Fiber-coupled Fabry-Perot interferometers serve electromagnetic interference-sensitive environments in aerospace testing.
- Electromechanical:Bourdon tube and diaphragm mechanisms occupy mature margin pools in automotive production line testing where precision requirements are relaxed.
Research Laboratories anchor volume demand for Thermal Conductivity. Resistive technology climbs the fastest as MEMS foundries scale.
Application:
End-use environment severity separates premium-specification from standard-grade procurement, with cleanroom certification requirements concentrating vendor relationships in semiconductor applications.
- Semiconductor Manufacturing:Ultra-high vacuum metrology enables thin-film deposition and etch process control. Direct OEM-manufacturer procurement bypasses traditional distribution layers in China's Yangtze River Delta flat-panel display fabrication.
- Industrial Automation:Rough vacuum monitoring supports packaging and material handling systems. EU F-Gas Regulation phase-down mandates accelerate replacement of mercury thermocouple gauges with solid-state alternatives.
- Automotive Testing:Brake booster and fuel system leak detection employs electromechanical gauges in high-volume production environments.
- Healthcare Equipment:Lyophilization and sterilization processes specify hygienic sensor designs with FDA-compliant surface finishes.
Industrial Automation ships the highest unit volumes. Semiconductor Manufacturing captures steepest expansion trajectory.
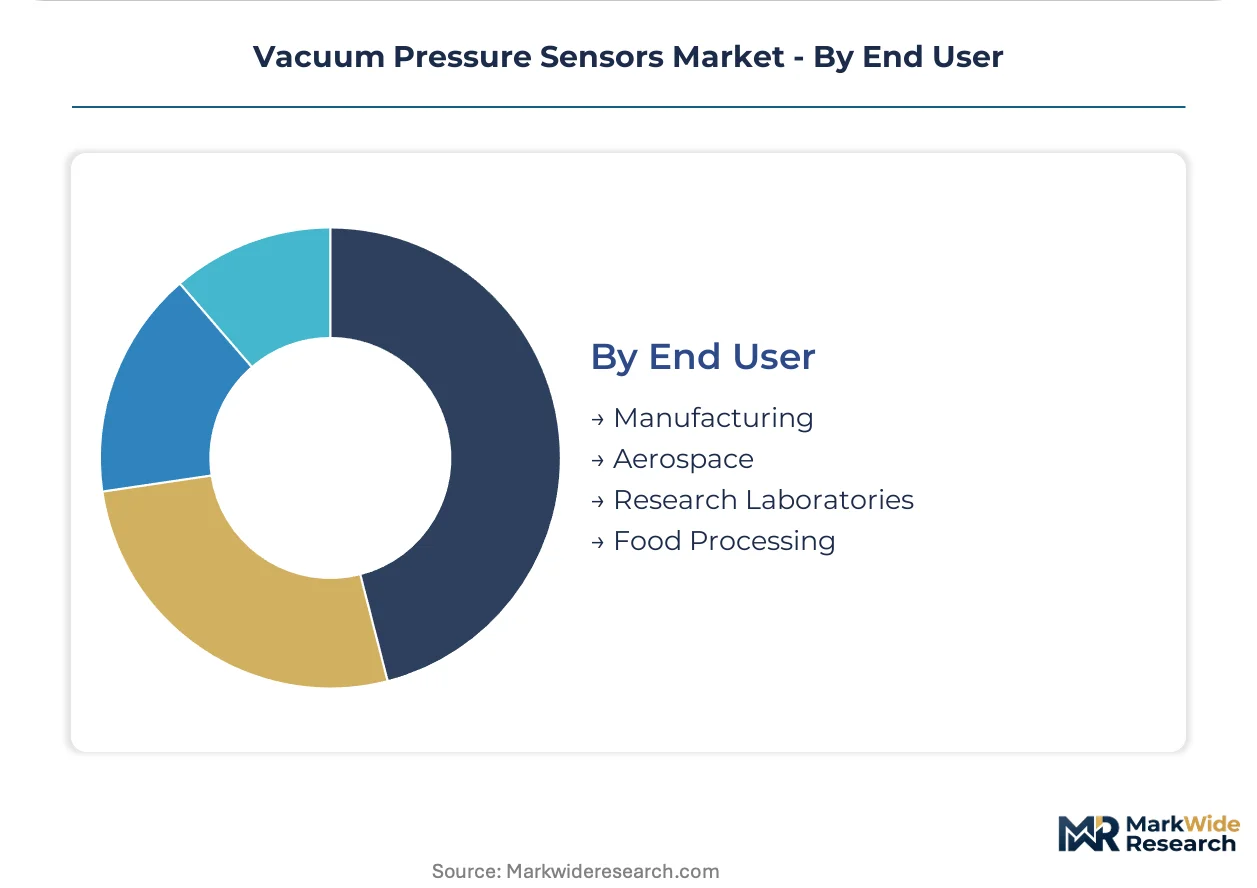
End User:
Customer technical sophistication shapes specification complexity, with aerospace and research segments demanding documented calibration traceability while food processing prioritizes washdown compatibility.
- Research Laboratories:National metrology institutes and fusion programs require primary standard traceability. Only seventeen primary vacuum standards exist worldwide, constraining emerging market manufacturer qualification.
- Manufacturing:Diverse process industries from steel degassing to polymer production create fragmented demand across vacuum ranges.
- Aerospace:Satellite thermal vacuum testing and propulsion system qualification specify radiation-tolerant designs.
- Food Processing:Modified atmosphere packaging and freeze-drying operations employ cost-optimized sensors with IP69K ingress protection.
Manufacturing leads by installed base. Research Laboratories expands most quickly as national science funding increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and German supply chains where high-purity alumina ceramic substrates command premiums, while Chinese manufacturers compete on volume in standard-grade capacitive sensors. Semiconductor fabs in East Asia drive regional demand divergence.
China
Advanced packaging corridors in Jiangsu and Zhejiang provinces scale atomic layer deposition capacity requiring 10⁻¹² mbar detection thresholds. The MIIT enforces GB standards for vacuum equipment in national research facilities. BOE and CSOT in the Yangtze River Delta have established preferred supplier frameworks that bypass regional distributors entirely.
United States
EPA NESHAP standards regulate vacuum pump emissions in manufacturing facilities across Texas and Arizona semiconductor clusters. The IRA production tax credits accelerate domestic fab construction near Phoenix and Austin. National metrology institutes in Maryland and Colorado maintain primary vacuum standards constraining traceability for emerging sensor manufacturers.
Germany
EU F-Gas Regulation phase-down mandates accelerate replacement of mercury thermocouple gauges in chemical processing plants along the Rhine corridor. ECHA REACH compliance restricts PFAS-based seal materials threatening fluorocarbon O-ring compatibility. Pfeiffer Vacuum Technology AG anchors European supply through captive vacuum gauge production in Baden-Württemberg.
Japan
METI enforces JIS Z 8751 vacuum measurement traceability requirements forcing sensor manufacturers to establish domestic service depots. High-purity alumina ceramic substrates for capacitive diaphragm sensors source predominantly from Japanese suppliers creating single-point vulnerability. Tokyo and Osaka metropolitan areas concentrate fusion research programs demanding primary standard traceability.
South Korea
Memory chip clusters in Gyeonggi Province specify digital sensors for etch chamber pressure interlocks where real-time data logging supports predictive maintenance. The MFDS regulates hygienic sensor designs for pharmaceutical lyophilization equipment. Samsung and SK Hynix fabs in the Seoul Capital Area drive direct OEM-manufacturer procurement bypassing traditional distribution layers.
Vacuum Pressure Sensors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin in radiation-hardened and ultra-high vacuum specifications. The vendor base concentrates around three strategic archetypes: captive vacuum technology houses, diversified industrial automation conglomerates, and MEMS-focused foundry services. M&A activity targets calibration service networks while capacity expansion concentrates in East Asian ceramic substrate fabrication.
Among diversified industrial conglomerates, Honeywell International Inc. and Emerson Electric Co. occupy positions spanning multiple pressure sensing technologies. MKS Instruments, Inc. exemplifies the captive fabrication archetype through in-house thin-film production for semiconductor metrology applications. INFICON Holding AG represents the analytical integration tier where mass spectrometer convergence with pressure monitoring enables single-port process analytical technology.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| MKS Instruments, Inc. |
| Pfeiffer Vacuum Technology AG |
| INFICON Holding AG |
| Edwards Vacuum |
| Emerson Electric Co. |
| ABB |
| Amphenol Corporation |
| Sensata Technologies |
| Others |
Value Network & Pricing Analysis
Jiangsu and Zhejiang provinces anchor high-purity alumina ceramic substrate fabrication for capacitive diaphragm sensors, concentrating upstream supply power in East Asian foundries and compressing margin capture for downstream integrators lacking backward integration into ceramic feedstock. Japanese suppliers command premium positioning for ultra-high vacuum-grade substrates, while Chinese manufacturers compete on volume in standard-grade capacitive sensors for industrial automation.
Pricing Analysis
Configured-to-order pricing for radiation-hardened capacitive sensors commands substantial premiums over standard digital transducers, with customization depth tied to semiconductor fab certification requirements and traceability documentation. Three-tier pricing structure across premium, standard, and economy levels separates ultra-high vacuum metrology from rough vacuum industrial units. Cost compression in standard-grade segments is intensifying because Chinese foundries are scaling MEMS Pirani gauge output. Automotive brake booster testing lines exhibit highest price sensitivity, while fusion research programs demonstrate lowest sensitivity due to primary standard traceability mandates.
Supply Chain Analysis
MEMS foundry capacity concentrates in Taiwan, South Korea, and China, with TSMC and Samsung Foundry holding dominant positions for silicon-based Pirani gauge arrays displacing legacy glass-envelope designs. High-purity alumina ceramic substrates, platinum thin-film coatings, and fluorocarbon seal materials constitute critical input dependencies. Single-source vulnerability in Japanese alumina supply threatens capacitive sensor production continuity. Distribution runs through direct OEM-manufacturer procurement channels that bypass traditional cleanroom equipment distributors in China's Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor fabrication expansion in East Asia represents an early-cycle expansion story, with atomic layer deposition capacity scaling driving specification windows for 10⁻¹² mbar detection threshold sensors before supply base consolidation hardens.
For Market Incumbents: Insulate premium positioning in radiation-hardened metrology through captive ceramic substrate supply and JIS Z 8751 calibration chain custody investments. MEMS foundry entrants from Taiwan threaten margin pools in portable leak detection equipment. Backward integration into high-purity alumina sourcing and domestic service depot establishment in Japan defend against emerging solid-state substitution.
For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu semiconductor corridors offer underpenetrated specification windows as PLI scheme incentives attract vacuum equipment OEMs to greenfield fab construction. Portable hydrogen fuel cell manufacturing leak detection equipment presents the most penetrable application segment. Partnership with domestic calibration laboratories enables rapid JIS traceability qualification without primary standard infrastructure investment.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors MEMS-based Pirani gauge specialists with foundry relationships and predictive maintenance algorithm capabilities over legacy electromechanical gauge manufacturers. Long-term viability rests on software-enabled service revenue attachment rather than hardware replacement cycles. Watch MEMS foundry capacity allocation shifts toward automotive pressure sensing as inflection indicator for vacuum sensor supply tightness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Captive alumina supply secures margin against Japanese supplier concentration risk. |
| Predictive Maintenance Algorithm Development | Sensor drift correction contracts open recurring revenue distinct from hardware cycles. |
| Domestic Calibration Depot Establishment | METI JIS Z 8751 compliance enables Japanese research facility procurement access. |
| MEMS Pirani Gauge Foundry Partnership | Silicon-based arrays displace glass-envelope designs in hydrogen fuel cell equipment. |
| Mass Spectrometer Convergence Integration | Single-port residual gas analysis enables pharmaceutical lyophilization specification. |
Research Methodology
A spread of perspectives from semiconductor fab equipment engineers, vacuum system calibration technicians, cleanroom OEM procurement managers, and ceramic substrate supply planners converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA NESHAP regulatory filings, METI JIS standard documentation, EU ECHA REACH substance restriction updates, and SEC 10-K disclosures from listed sensor manufacturers. Bottom-up unit demand modeling triangulated against top-down semiconductor capital expenditure forecasts.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product architecture, measurement physics, end-use environment severity, and customer technical sophistication. CAGRs derived from installed base turnover rates and technology substitution curves. Forecast inputs incorporated MEMS foundry capacity expansion timelines and national metrology institute primary standard accessibility constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese MEMS foundries or Indian PLI scheme beneficiaries would shift outcomes beyond modeled parameters. Quarterly review of semiconductor fab construction permits, fluorocarbon seal material regulatory restrictions, and national calibration infrastructure investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Touchless Sensing Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
Confocal Displacement Sensor Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
Quantum Sensors Market
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market