
 Synthetic Vitamin E Market | 2026-2036
Synthetic Vitamin E Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Vitamin E Market Analysis
Cosmetics and pharmaceuticals is realigning toward animal feed and food additives as the fastest-expanding demand vertical. BASF leverages its integrated isophytol-to-tocopherol chain to sustain cost leadership across European and Asian supply lines. Zhejiang Medicine anchors volume production through captive intermediates and controls pricing in bulk alpha-tocopherol exports. DSM differentiates via pharmaceutical-grade certifications and competes on high-purity specifications for prenatal and geriatric nutrition.
Synthetic vitamin E denotes chemically synthesized tocopherol compounds, primarily all-rac-alpha-tocopheryl acetate produced via condensation of trimethylhydroquinone with isophytol, yielding standardized antioxidant activity measured in international units per gram. Its primary commercial purpose centers on stabilizing lipids against oxidative rancidity in processed foods and extending shelf life in fortified animal diets. Alpha-tocopherol dominates value capture due to highest biological potency, while gamma-tocopherol exhibits faster volume growth in poultry and swine premix applications where cost efficiency outweighs IU conversion premiums. Powder formulations lead in feed milling for uniform dispersion, whereas oil concentrates retain margin pools in cosmetic serum and softgel pharmaceutical manufacturing.
EFSA establishes maximum permitted levels for tocopherol additives in foodstuffs under Regulation 1333/2008, while FDA GRAS listings govern U.S. fortification limits in dietary supplements and infant formulas. China's NMPA and GB standards enforce pharmaceutical-grade purity thresholds that determine export eligibility for API manufacturers. Japan's PMDA maintains distinct JIS-aligned specifications for tocopherol used in quasi-drug applications, creating separate qualification pathways. Stakeholders must monitor evolving feed-grade versus food-grade regulatory divergence across these jurisdictions to optimize product registration investments and avoid formulation reformulation costs.
Market Dynamics
Livestock producers across China, Brazil, and the United States are consolidating feed procurement around synthetic tocopherol acetate to combat lipid oxidation in high-energy rations, compressing demand cycles and forcing intermediate traders to absorb margin compression or exit bulk distribution entirely.
Growth Catalysts
- EFSA purity mandates:Tightening thresholds under Regulation 1333/2008 are disqualifying marginal producers and concentrating volume among certified manufacturers serving pharmaceutical and infant formula channels.
- Poultry sector expansion:Integrated broiler operations in Southeast Asia are standardizing vitamin E premix inclusion rates to reduce mortality from nutritional muscular dystrophy.
- Isophytol supply stability:Captive production of this trimethylhydroquinone precursor within integrated chemical parks has eliminated raw material bottlenecks that previously constrained tocopherol acetate output.
Market Restraints
- Acetone and petrochemical feedstock volatility:Synthetic vitamin E production depends on fossil-derived intermediates whose price swings compress manufacturing margins unpredictably.
- Chinese supply concentration:Over two-thirds of bulk all-rac-alpha-tocopherol originates from Zhejiang and Shandong province chemical clusters, creating single-geography risk for global buyers.
- Natural tocopherol substitution:Soybean-derived mixed tocopherols from oilseed processing are capturing share in clean-label food applications where synthetic provenance triggers formulation rejection.
Strategic Opportunities
- Aquaculture fortification:Salmon and shrimp feed producers in Norway and Chile are testing elevated vitamin E inclusion to reduce fillet oxidation and extend chilled distribution windows.
- REACH-registered pharmaceutical grades:ECHA compliance for active pharmaceutical ingredient status opens premium pricing tiers for prenatal and geriatric nutrition applications.
- Direct-to-mill distribution:Bypassing traditional compound feed intermediaries through containerized bulk delivery to integrated livestock operations is capturing margin previously lost to distribution layers.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA and FDA validation protocols for tocopherol acetate API status require 18-24 month documentation cycles that delay market entry.
- Feed-mill formulation integration:Synthetic vitamin E powder must achieve uniform dispersion in high-fat premixes without segregation, demanding specialized blending equipment and technician training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Vitamin E Market |
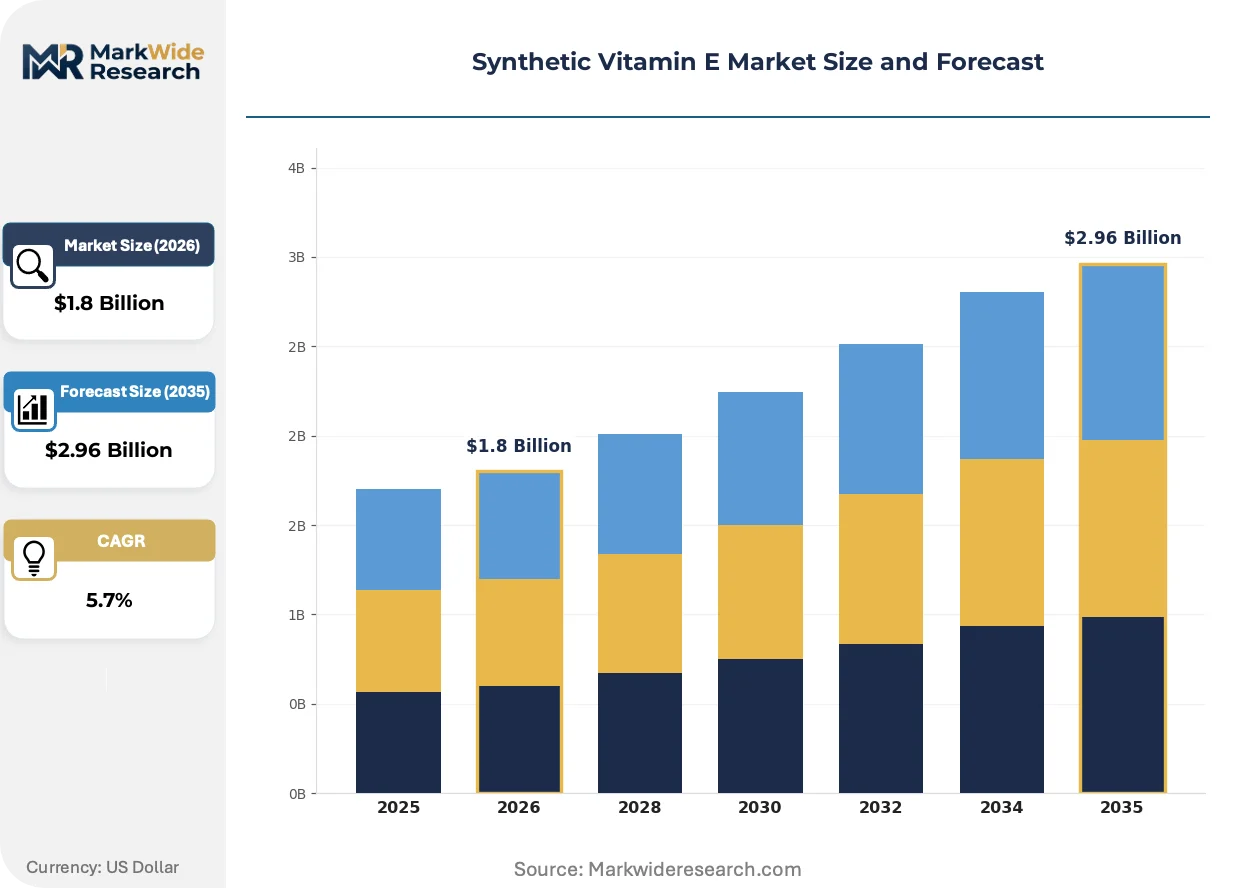
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha-Tocopherol, Beta-Tocopherol, Gamma-Tocopherol, Delta-Tocopherol Application: Cosmetics, Food Additives, Pharmaceuticals, Animal Feed Form: Oil, Powder, Emulsion, Gel End User: Manufacturers, Retailers, Distributors, Wholesalers |
| Companies Covered | Zhejiang Medicine, BASF, DSM, Adisseo, NHU, Beisha, Zhejiang Langbo, PKU HealthCare, Eisai Food & Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Vitamin E Market Emerging Trajectories
Continuous processing technology and regulatory data integrity requirements are compressing batch cycle times while elevating documentation burdens, reshaping capital deployment priorities across synthetic vitamin E manufacturing.
Flow chemistry for trimethylhydroquinone synthesis is converging with automated in-process analytical control to enable real-time purity adjustment. European and Chinese manufacturers adopting these systems have reduced solvent waste volumes substantially. This convergence is compressing the cost gap between commodity feed-grade and pharmaceutical-grade tocopherol acetate production.
REACH authorization requirements for chemical substances of very high concern are forcing reformulation reviews across cosmetic and food additive applications. ECHA's 2023-2024 dossier updates have expanded safety data requirements for tocopherol derivatives used in leave-on skin products. German and French formulators are responding by segregating supply chains between feed-grade and cosmetic-grade intermediates to prevent cross-contamination liability.
Compound feed manufacturers are consolidating procurement around annual volume contracts with fixed-price escalators rather than spot market purchases. This shift transfers inventory carrying costs to synthetic vitamin E producers while locking in offtake predictability. The pattern is most visible in Brazil and Thailand where integrated poultry and swine operations have absorbed regional trading houses into captive supply functions.
Synthetic Vitamin E Market Segmentation
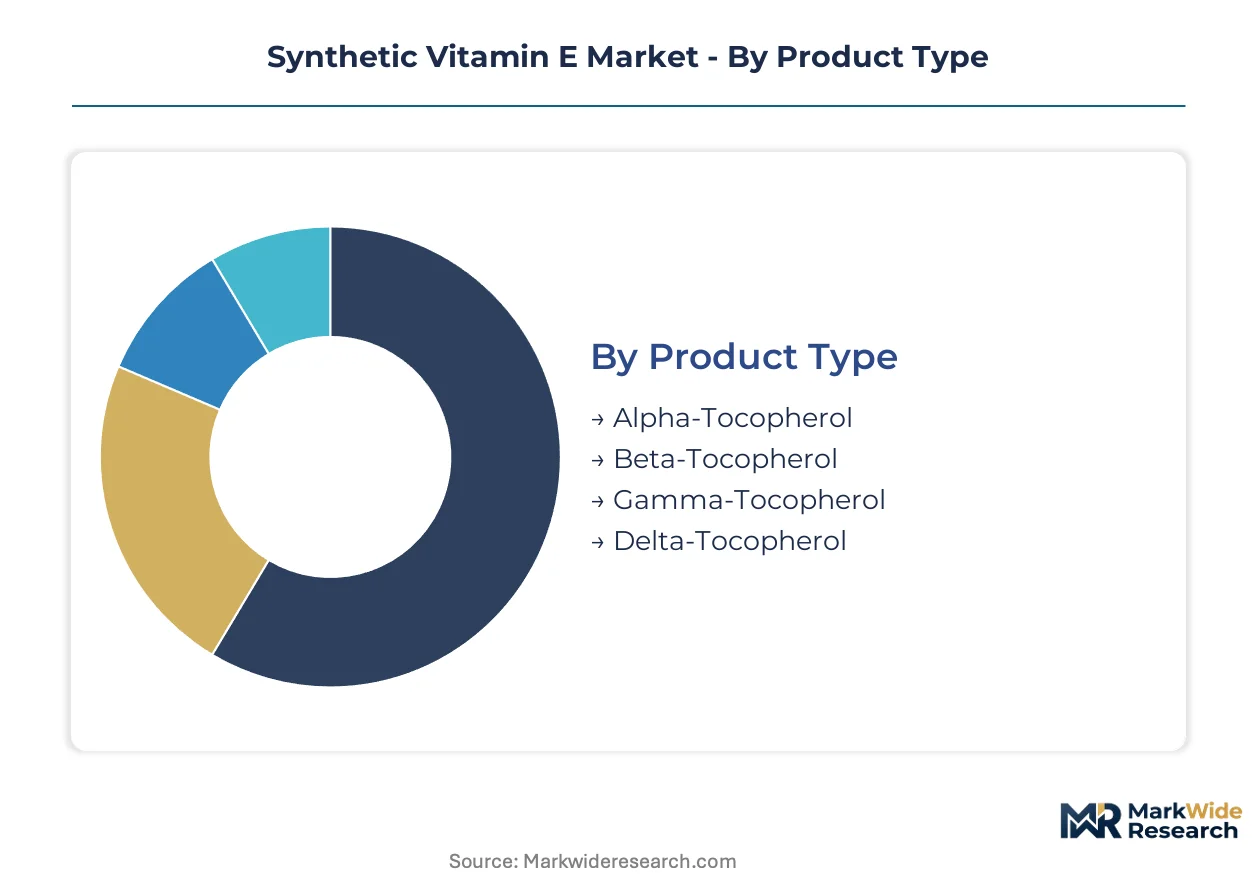
Synthetic vitamin E producers compete across distinct specification tiers where biological potency, regulatory grade, and physical form determine pricing power and customer lock-in. Segmentation reveals how integrated chemical parks and pharmaceutical certification pathways create divergent margin structures within the same molecular family.
Product Type:
Biological activity and IU conversion efficiency separate commercial tiers, with manufacturers optimizing synthesis routes toward specific tocopherol isomers based on end-use premiums.
- Alpha-Tocopherol:All-rac-alpha-tocopheryl acetate delivers the highest vitamin E biological activity per international unit, commanding premium positioning in prenatal supplements and geriatric nutrition formulations. Demand concentrates in pharmaceutical channels where EMA and FDA API certifications filter out commodity producers. Regulatory purity mandates under EFSA Regulation 1333/2008 are disqualifying non-certified manufacturers from infant formula and medical food applications.
- Gamma-Tocopherol:Faster volume expansion characterizes this isomer in poultry and swine premix applications where cost efficiency outweighs IU conversion premiums. Southeast Asian integrated broiler operations are standardizing inclusion rates to reduce mortality from nutritional muscular dystrophy, compressing procurement cycles around annual volume contracts.
- Beta-Tocopherol:Limited commercial production serves niche cosmetic antioxidant formulations requiring specific isomer ratios.
- Delta-Tocopherol:Minimal synthetic output; primarily sourced from mixed natural tocopherol streams for specialized food preservation applications.
Alpha-tocopherol leads on scale; gamma-tocopherol leads on momentum.
Application:
End-use specifications create divergent qualification barriers, with pharmaceutical and cosmetic channels demanding documentation burdens that feed-grade suppliers cannot economically absorb.
- Animal Feed:Powder formulations dominate feed milling for uniform dispersion in high-fat premixes, with Brazil and Thailand integrated livestock operations consolidating procurement around containerized bulk delivery. Compound feed manufacturers are transferring inventory carrying costs to producers through fixed-price annual contracts with volume escalators.
- Pharmaceuticals:Oil concentrates retain margin pools in softgel manufacturing where REACH-registered pharmaceutical grades open premium pricing tiers. EMA validation protocols require 18-24 month documentation cycles that delay market entry and concentrate supply among established API manufacturers.
- Cosmetics:ECHA's expanded safety data requirements for leave-on skin products are forcing German and French formulators to segregate supply chains between feed-grade and cosmetic-grade intermediates.
- Food Additives:EFSA maximum permitted levels under Regulation 1333/2008 govern fortification limits, with natural tocopherol substitution threatening synthetic share in clean-label applications.
Animal feed leads on scale; pharmaceuticals leads on margin expansion.
Form:
Physical presentation determines blending equipment requirements and shelf stability profiles, with powder and oil formats capturing distinct customer types.
- Powder:Spray-dried and adsorbed formulations achieve uniform dispersion in feed premixes without segregation, though specialized blending equipment and technician training raise switching costs for compound feed mills.
- Oil:Concentrated tocopherol acetate in vegetable oil carriers serves cosmetic serum manufacturing and pharmaceutical softgel encapsulation, requiring antioxidant protection during storage and handling.
- Emulsion:Water-dispersible formats target beverage fortification and liquid supplement applications where oil-phase incorporation is impractical.
- Gel:Thickened oil systems facilitate precise dosing in topical pharmaceutical and cosmetic formulations.
Powder leads on volume throughput; oil leads on value per kilogram.
End User:
Channel structure determines margin capture, with direct-to-mill distribution bypassing traditional trading layers that previously absorbed price volatility.
- Manufacturers:Integrated chemical parks in Zhejiang and Shandong provinces supply captive intermediates to pharmaceutical and feed-grade formulators, controlling pricing in bulk alpha-tocopherol exports.
- Distributors:Intermediate traders face margin compression or exit from bulk distribution as livestock producers consolidate procurement around synthetic tocopherol acetate.
- Retailers:Branded supplement channels demand finished dosage forms with consumer-facing certifications, accessing synthetic vitamin E through contract manufacturers rather than direct chemical sourcing.
- Wholesalers:Regional trading houses in Brazil and Thailand are being absorbed into captive supply functions of integrated poultry and swine operations.
Manufacturers lead on supply concentration; distributors face structural compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production toward jurisdictions where feed-grade tocopherol acetate faces lower compliance burdens than pharmaceutical-grade material, creating geographic specialization between bulk synthesis and high-purity finishing.
China
Integrated chemical parks in Zhejiang and Shandong provinces supply over two-thirds of global all-rac-alpha-tocopherol through captive isophytol production. NMPA pharmaceutical-grade purity thresholds determine export eligibility for API manufacturers serving prenatal nutrition channels. The Yangtze River Delta cluster anchors volume production with backward integration into trimethylhydroquinone precursors.
Germany
BASF leverages its Ludwigshafen isophytol-to-tocopherol chain to sustain cost leadership across European supply lines for feed and cosmetic applications. ECHA REACH authorization requirements for substances of very high concern force segregated supply chains between feed-grade and cosmetic-grade intermediates. The Rhine-Neckar metropolitan region concentrates pharmaceutical-grade finishing capacity under EMA validation protocols.
United States
Livestock producers in Iowa and North Carolina consolidate procurement around synthetic tocopherol acetate for high-energy poultry and swine rations. FDA GRAS listings govern fortification limits in dietary supplements and infant formulas, creating distinct registration pathways from feed-grade material. The Midwest corn-soy belt drives demand concentration for antioxidant premixes.
Brazil
Integrated broiler operations in São Paulo and Paraná standardize vitamin E premix inclusion rates to reduce mortality from nutritional muscular dystrophy. ANVISA enforcement of imported feed additive specifications affects sourcing flexibility from Asian suppliers. The southern agricultural belt absorbs regional trading houses into captive supply functions of poultry conglomerates.
Japan
PMDA maintains distinct JIS-aligned specifications for tocopherol used in quasi-drug applications, creating separate qualification pathways from pharmaceutical-grade material. Cosmetic formulators in Osaka and Tokyo face expanded safety data requirements for leave-on skin products. The Kansai region concentrates high-purity oil concentrate production for softgel manufacturing.
Synthetic Vitamin E Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade certification creating tiered barriers that commodity feed-grade suppliers cannot economically penetrate. The market structure concentrates around three to five integrated chemical groups controlling precursor supply, while regional compounders handle formulation finishing. Strategic archetypes include captive intermediate producers, certification-heavy pharmaceutical specialists, and price-competitive feed-grade bulk suppliers. Dominant competitive moves center on backward integration into isophytol and trimethylhydroquinone precursors, plus geographic expansion through direct-to-mill distribution bypassing traditional trading layers.
Within the integrated chemical group tier, Zhejiang Medicine and NHU exemplify producers with captive intermediate supply chains, while BASF occupies a position bridging European pharmaceutical certification with Asian feed-grade volume. These three anchors represent divergent strategic postures: Chinese producers leverage chemical park integration for cost leadership, while the German group combines isophytol synthesis with REACH-registered pharmaceutical grades for premium positioning in prenatal and geriatric nutrition channels.
| Leading Market Players |
|---|
| Zhejiang Medicine |
| BASF |
| DSM |
| Adisseo |
| NHU |
| Beisha |
| Zhejiang Langbo |
| PKU HealthCare |
| Eisai Food & Chemical |
| Others |
Supply Flow & Price Mechanics
Integrated livestock operations in Brazil, Thailand, and the United States concentrate procurement volumes, forcing synthetic vitamin E producers toward contract-based annual offtake agreements with fixed-price escalators that transfer inventory risk upstream.
Pricing Analysis
Distributor margins in traditional bulk trading are compressing as direct-to-mill delivery bypasses intermediate layers entirely. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and cosmetic-grade certifications drives differentiation, with EMA-validated API material commanding substantial premiums over commodity tocopherol acetate. Cost compression in feed-grade powder reflects Chinese chemical park oversupply and captive isophytol production. Compound feed manufacturers exhibit highest price sensitivity due to formula cost targets, while prenatal supplement brands absorb premium tiers with minimal volume elasticity.
Supply Chain Analysis
Container freight rates from Zhejiang and Shandong province chemical parks to Rotterdam and Santos determine landed cost competitiveness for bulk alpha-tocopherol exports. Synthesis draws from trimethylhydroquinone and isophytol precursors, with petrochemical feedstock volatility tethering margin stability to acetone and propylene markets. Single-geography concentration in China's Yangtze River Delta cluster exposes global buyers to regulatory disruption or environmental enforcement actions. Distribution runs through integrated chemical park direct sales to multinational feed compounders, supplemented by regional toll-finishing operations for pharmaceutical-grade oil concentrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA Regulation 1333/2008 purity mandates and ECHA REACH authorization requirements continuously elevate compliance investment thresholds, filtering marginal producers and concentrating returns among certified incumbents.
For Market Incumbents: Acquire captive isophytol production capacity to secure precursor supply against petrochemical feedstock volatility. BASF's Ludwigshafen integration and Zhejiang Medicine's chemical park model demonstrate how upstream control over trimethylhydroquinone synthesis defends margin structure. Pursue EMA API validation for tocopherol acetate to access prenatal nutrition premiums before documentation backlogs extend qualification timelines further.
For New Entrants and Emerging Players: Begin with aquaculture fortification in Norway and Chile, where salmon and shrimp feed producers test elevated vitamin E inclusion without established supplier relationships. Norwegian feed mills seek alternatives to incumbent sourcing for fillet oxidation control. Position as REACH-registered pharmaceutical-grade specialists targeting geriatric nutrition contract manufacturers bypassing commodity feed-grade competition entirely.
For Investors and Strategic Acquirers: Chemical conglomerates with existing isophytol infrastructure represent the most active acquirer category in this space, seeking tocopherol acetate finishing capacity to complete vertical integration. Evaluate targets through the lens of five-to-ten-year regulatory divergence between feed-grade and pharmaceutical-grade specifications. Monitor ECHA dossier updates for tocopherol derivatives as the signal indicating acceleration in cosmetic-grade safety data requirements and supply chain segregation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isophytol | BASF's Ludwigshafen chain eliminates raw material bottlenecks that previously constrained output. |
| EMA API Validation Investment | Eighteen-month documentation cycles delay market entry and concentrate supply among certified manufacturers. |
| Direct-to-Mill Distribution Expansion | Brazilian poultry conglomerates absorb regional trading houses into captive supply functions. |
| REACH-Registered Pharmaceutical Grade Registration | ECHA compliance opens premium pricing tiers for prenatal and geriatric nutrition applications. |
| Flow Chemistry Process Conversion | European and Chinese manufacturers reduce solvent waste volumes through automated in-process analytical control. |
Methodological Framework
Bottom-up animal feed and pharmaceutical formulation modeling reconciled against top-down isophytol and trimethylhydroquinone precursor tracking forms the analytical core of this study. Primary interviews with feed procurement directors at integrated livestock operations, regulatory affairs leads at tocopherol acetate API manufacturers, compound feed mill technical managers, and cosmetic formulators in Germany and France were validated against secondary sources including EFSA additive regulations, ECHA REACH dossiers, FDA GRAS listings, Chinese NMPA pharmaceutical standards, and customs trade data for tocopherol acetate HS code movements.
Input-output matrices linking precursor chemical capacity to finished tocopherol acetate output across alpha-tocopherol, gamma-tocopherol, and derivative grades were modeled over the projection horizon. Segmentation dimensions included biological potency tier, application channel, physical form, and end-user channel structure. CAGRs were derived from volume-demand elasticity against livestock production forecasts and pharmaceutical fortification trend analysis, with cross-referencing against isophytol supply expansion timelines and regulatory purity mandate implementation schedules.
Several conditions sit outside the modeled scope, including potential natural tocopherol substitution acceleration in clean-label food applications, breakthroughs in biosynthetic tocopherol production, and abrupt petrochemical feedstock price shocks beyond historical volatility bands. Forecasts reflect assumptions about regulatory stability and precursor supply continuity. Stakeholders should weight assumptions against their own operating context and regional enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
Vitamin Yeast Market
Vitamin Fortified
Calcium-Fortified Food Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Global Vitamins Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Asia-Pacific Food Fortifying Agent Market
Vitamin Fortified
Vitamin E Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market