
 Vitamin D Deficiency Treatment Market | 2026-2036
Vitamin D Deficiency Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin D Deficiency Treatment Market Outlook
Pharmaceutical-grade cholecalciferol formulations is reorganizing competitive dynamics in vitamin D deficiency treatment. Pfizer Inc. leverages its hospital formulary relationships to sustain institutional channel dominance. Abbott differentiates through integrated diagnostic-testing-to-treatment platforms that span vitamin D assay and repletion therapy. Sun Pharmaceutical Industries Ltd. anchors emerging market access through cost-engineered oral dosage manufacturing.
Vitamin D deficiency treatment encompasses therapeutic interventions restoring serum 25-hydroxyvitamin D concentrations, typically employing cholecalciferol (D3) or ergocalciferol (D2) manufactured to USP potency specifications with oil-based or micronized dry powder excipient systems for enhanced bioavailability. These therapies address metabolic bone disease, immune dysfunction, and endocrine disorders across outpatient and inpatient clinical settings. The oral delivery mode segment dominates volume consumption through pharmacy-dispensed tablets and capsules, while injectable formulations command premium pricing in hospital and clinic settings where malabsorption pathology precludes enteral administration. Liquid drops compete in pediatric and geriatric homecare channels where swallowing impairment restricts solid dosage forms.
The FDA enforces Current Good Manufacturing Practice (CGMP) regulations for dietary supplements under 21 CFR Part 111, mandating identity, purity, strength, and composition verification that shapes manufacturer quality investment and batch release protocols. The United States Pharmacopeia (USP) monographs for cholecalciferol and ergocalciferol establish analytical reference standards that determine product specification acceptability for institutional procurement. Stakeholders must monitor evolving Medicare coverage determinations for vitamin D testing and therapeutic supplementation to anticipate reimbursement-driven demand shifts.
Market Dynamics
Hospital procurement consolidation is compressing supplier margins while elevating formulary access barriers for non-integrated vitamin D therapy manufacturers. Medicare reimbursement adjustments for 25-hydroxyvitamin D testing directly cascade into prescription volume commitments across institutional channels.
Growth Catalysts
- Osteoporosis screening mandates:Medicare coverage determinations for bone density testing expand diagnostic pipelines that convert to therapeutic intervention. The United States sustains treatment volumes through this reimbursement linkage.
- 21 CFR Part 111 enforcement:FDA's tightened CGMP verification for dietary supplement potency creates competitive separation between pharmaceutical-grade and commodity vitamin D suppliers. Quality investment becomes a market access prerequisite.
- Micronized dry powder excipients:Enhanced bioavailability formulations expand addressable populations with malabsorption syndromes. Hospital pharmacy committees prioritize these technologies for formulary inclusion.
Market Restraints
- Cholecalciferol API concentration:Active pharmaceutical ingredient supply concentrates among Chinese and Indian manufacturers, creating single-source vulnerability for Western formulation facilities.
- USP monograph compliance costs:Analytical reference standard verification imposes fixed cost burdens that disproportionately constrain mid-tier manufacturers without captive laboratory infrastructure.
- Over-the-counter substitution:Unregulated dietary supplement channels erode prescription therapy adherence among cost-sensitive patient populations with mild deficiency states.
Strategic Opportunities
- Pediatric liquid formulation gaps:Swallowing-impaired geriatric and infant populations remain underserved by solid-dosage-dominated portfolios. Homecare channel expansion targets this white space.
- Integrated diagnostic-therapy platforms:Convergence of vitamin D assay instrumentation with repletion therapy protocols creates bundled procurement appeal for hospital laboratory-pharmacy alliances.
- Injectable malabsorption segments:Bariatric surgery and inflammatory bowel disease populations require parenteral administration routes that command premium positioning.
Industry Challenges
- Analytical chemistry talent scarcity:USP-compliant potency verification requires specialized chromatography expertise that outpaces educational pipeline output.
- Batch release timeline compression:CGMP documentation requirements extend quality control cycles, constraining just-in-time inventory models demanded by hospital procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin D Deficiency Treatment Market |
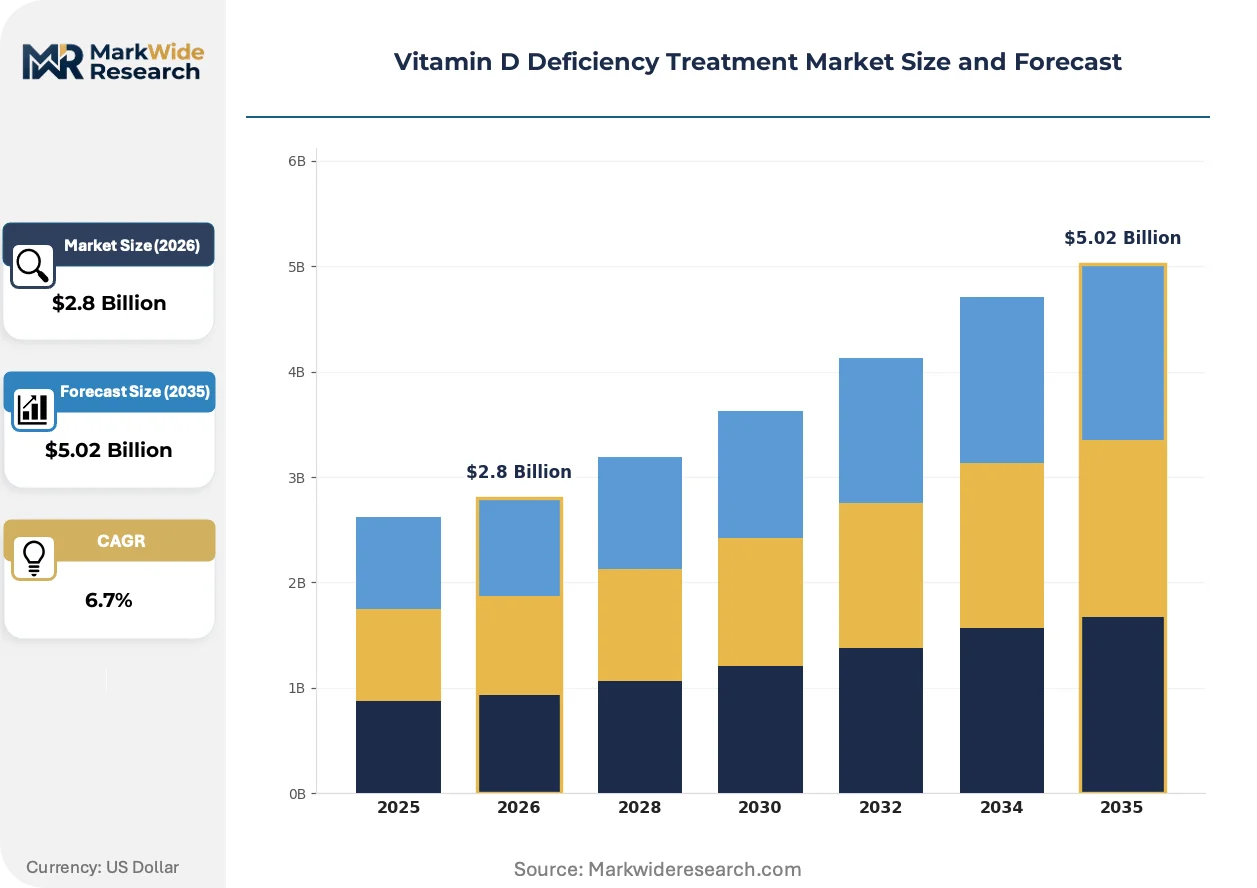
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Liquid Drops, Injections Delivery Mode: Oral, Injectable, Transdermal, Sublingual Age Group: Children, Adults, Seniors, Pregnant Women End User: Clinics, Hospitals, Pharmacies, Homecare |
| Companies Covered | Pfizer Inc., Abbott, Merck & Co., Inc., Sanofi, Novartis International AG, GSK plc, Bayer AG, Sun Pharmaceutical Industries Ltd., Cadila Healthcare Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin D Deficiency Treatment Market Strategic Shifts
Micronization technology and oil-based excipient engineering are fragmenting the vitamin D therapy landscape into performance-tiered segments. Formulation science now determines competitive positioning as much as manufacturing scale.
Liposomal encapsulation technology is bifurcating the oral vitamin D segment into standard and enhanced bioavailability tiers. Gastroenterology practices increasingly specify liposomal formulations for patients with celiac disease, Crohn's disease, and post-bariatric surgical anatomy. This technology is compressing market share for conventional oil-based softgels in specialty clinics while expanding total addressable volume through improved efficacy claims.
EMA's tightened pharmacovigilance requirements for high-dose vitamin D products are extending post-market surveillance obligations across European markets. Manufacturers must now maintain active safety databases for ergocalciferol and cholecalciferol products exceeding 10,000 IU per unit dose. Hospital pharmacies in Germany and France are responding by consolidating purchases among suppliers with established risk management systems.
Hospital formulary committees are consolidating vendor relationships around integrated testing-to-treatment protocols. Independent vitamin D assay manufacturers face displacement as pharmaceutical suppliers bundle diagnostic platforms with therapeutic contracts. This concentration is most visible in United States academic medical centers where laboratory-pharmacy integration initiatives accelerate procurement rationalization.
Vitamin D Deficiency Treatment Market Segmentation
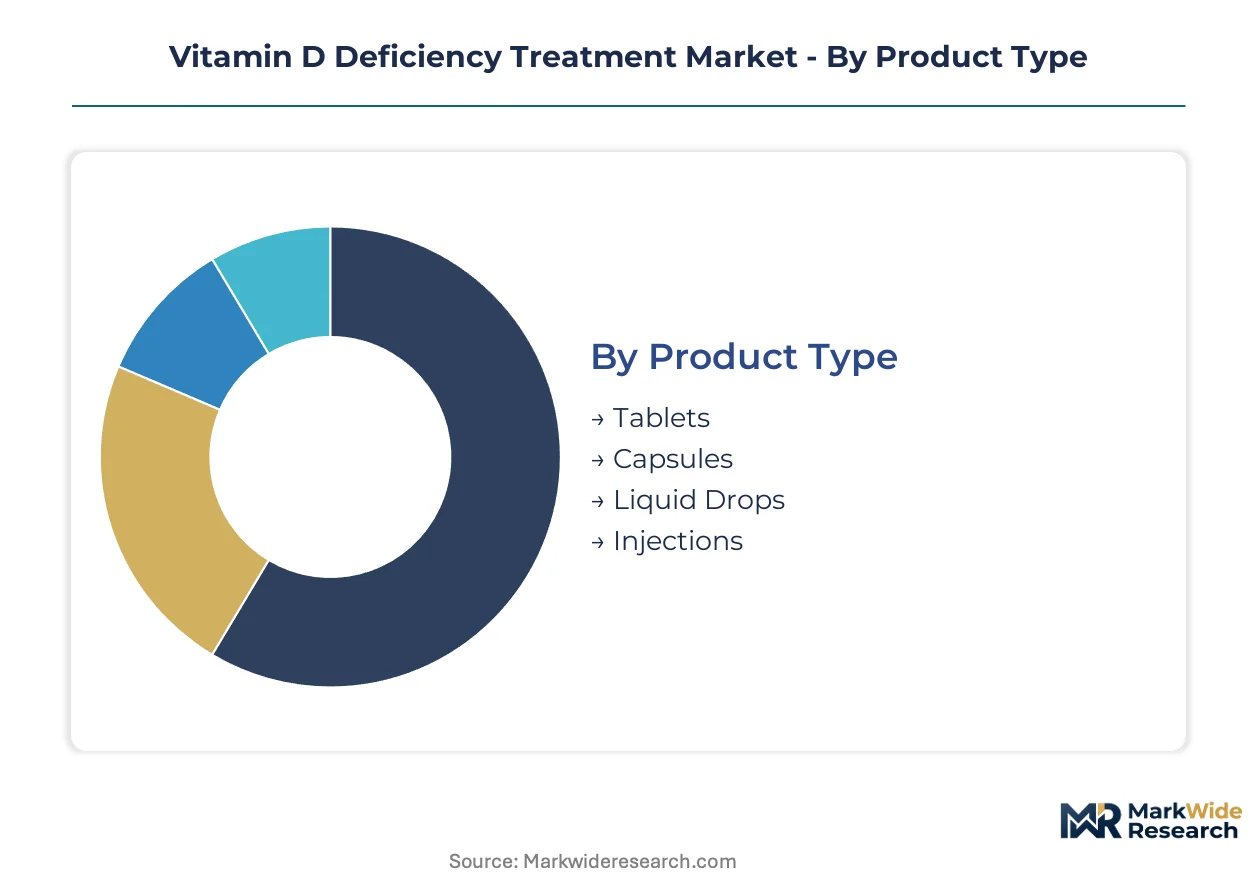
Segmentation in vitamin D deficiency treatment reveals how formulation technology, patient physiology, and care setting economics fragment demand. Each dimension carries distinct procurement patterns and reimbursement dependencies that shape manufacturer portfolio priorities.
Product Type:
Tablets and capsules dominate domestic pharmacy dispensing in the United States and Western Europe, while liquid drops and injectables concentrate in export-led emerging market channels where cold-chain infrastructure and swallowing impairment prevalence create differentiated demand profiles.
- Tablets:Compressed cholecalciferol with micronized dry powder excipients enables USP-compliant potency verification at scale. Hospital formularies in the United States prioritize these for osteoporosis protocol adherence, though Medicare reimbursement compression constrains premium pricing.
- Capsules:Oil-based softgel formulations deliver enhanced bioavailability for populations with malabsorption syndromes. Demand concentrates in Germany and France where EMA pharmacovigilance requirements for high-dose units favor established manufacturers with active safety databases.
- Liquid Drops:Pediatric and geriatric homecare channels in India and Brazil drive volume; FSSAI and ANVISA registration pathways determine market access speed.
- Injections:Parenteral ergocalciferol serves bariatric surgery and inflammatory bowel disease segments; procurement concentrates in United States academic medical centers with integrated pharmacy-laboratory alliances.
Tablets hold the largest share; momentum sits with liquid drops.
Delivery Mode:
Cost tier stratification separates premium bioenhanced routes from commodity oral administration, with injectable and transdermal formulations commanding hospital procurement premiums while oral dominates volume economics.
- Oral:Tablets, capsules, and liquid drops collectively capture pharmacy-dispensed volume across all geographies. The United States sustains the highest per-capita consumption through Medicare-linked osteoporosis screening pipelines.
- Injectable:Intramuscular cholecalciferol addresses severe deficiency in malabsorption pathology. Hospital pharmacy committees in France and Germany consolidate purchases among suppliers with EMA-compliant risk management systems.
- Transdermal:Emerging patch technology targets homecare adherence improvement; regulatory validation remains incomplete across major markets.
- Sublingual:Rapid-absorption sprays compete in pediatric and geriatric niches where swallowing impairment restricts solid dosage forms; distribution concentrates in United Kingdom and Australian pharmacy chains.
Oral administration commands volume leadership; injectable routes are gaining share fastest in institutional channels.
Age Group:
Application severity and reimbursement linkage determine segment economics, with senior populations driving prescription volume through Medicare coverage while pediatric and pregnancy segments rely on out-of-pocket or supplemental insurance.
- Seniors:Medicare reimbursement for osteoporosis-related vitamin D testing sustains treatment volumes in the United States; this population generates the highest prescription intensity per capita.
- Adults:Occupational health screening and wellness program inclusion expand addressable population in employer-sponsored insurance markets, particularly in Germany and Japan.
- Children:Pediatric liquid formulation gaps persist across swallowing-impaired infant populations; homecare channel expansion targets this white space in India and Brazil.
- Pregnant Women:Prenatal protocol inclusion varies by national guideline; the United Kingdom and Australia maintain the most systematic supplementation recommendations.
Seniors generate the highest absolute volume; pediatric applications show the steepest expansion trajectory as formulation innovation addresses unmet need.
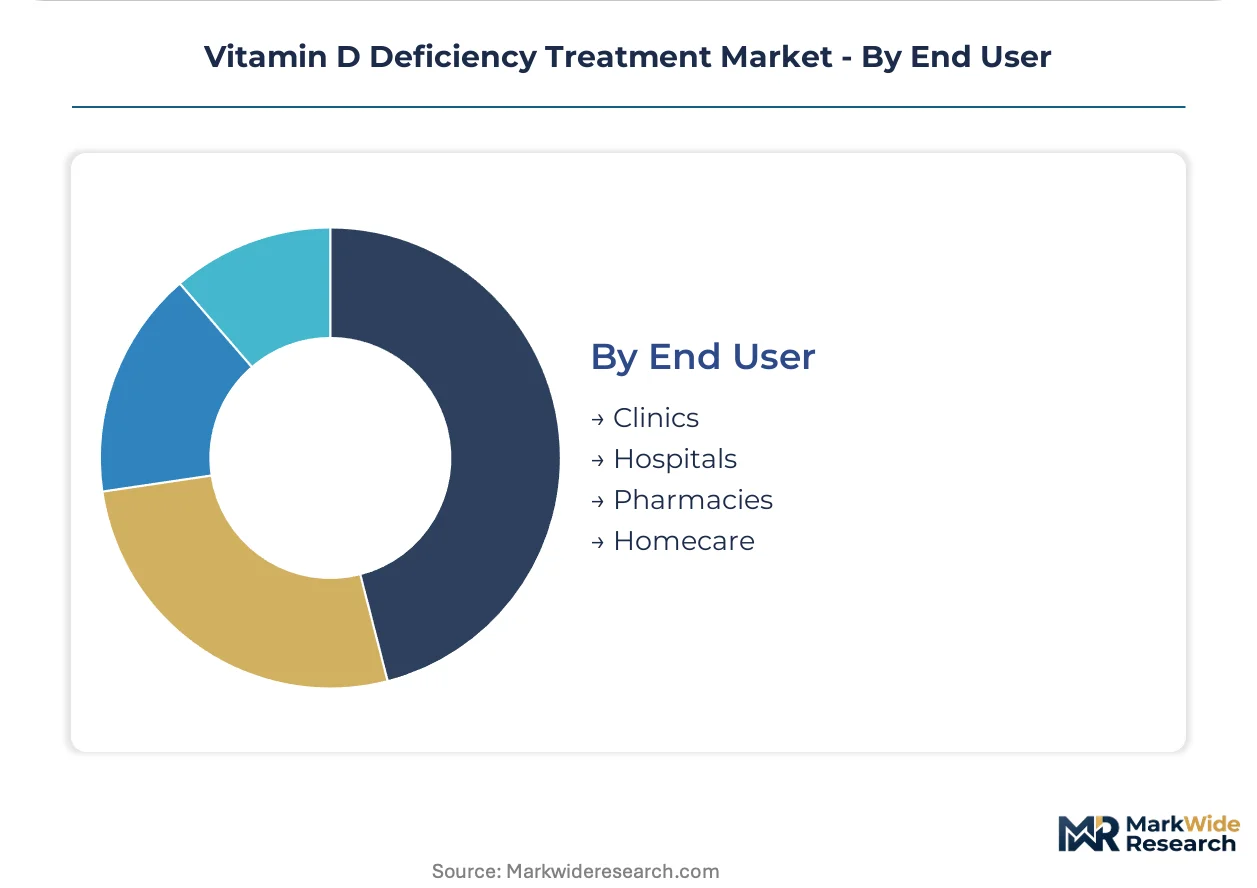
End User:
Customer type concentration creates divergent margin structures, with hospitals extracting procurement efficiencies through formulary consolidation while homecare channels reward formulation convenience premiums.
- Hospitals:Procurement consolidation compresses supplier margins while elevating formulary access barriers; integrated diagnostic-testing-to-treatment platforms dominate United States academic medical center contracting.
- Clinics:Specialty gastroenterology and endocrinology practices specify liposomal formulations for celiac disease and post-bariatric surgical populations in Germany and France.
- Pharmacies:Retail dispensing faces over-the-counter substitution pressure from unregulated dietary supplement channels, particularly in cost-sensitive patient populations with mild deficiency states.
- Homecare:Swallowing-impaired geriatric and infant populations drive liquid drop and sublingual spray demand; direct-to-patient distribution models expand in United Kingdom and Australian markets.
Hospitals anchor institutional revenue; homecare channels are expanding most quickly as aging-in-place preferences reshape care delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of cholecalciferol API concentrate in Chinese and Indian manufacturing clusters, while formulation and packaging gravitate toward United States and European pharmaceutical hubs. Import dependency for active pharmaceutical ingredients shapes procurement security calculations across Western markets.
United States
Medicare reimbursement for osteoporosis-related vitamin D testing sustains prescription volumes through diagnostic-to-treatment conversion pipelines. FDA's 21 CFR Part 111 enforcement tightens potency verification standards for dietary supplements, creating quality-tier separation. Hospital procurement consolidation in academic medical centers favors integrated diagnostic-therapy platform suppliers.
Germany
EMA pharmacovigilance requirements for high-dose vitamin D products extend post-market surveillance obligations beyond 10,000 IU unit doses. Hospital pharmacies in Berlin and Munich consolidate purchases among suppliers with established risk management systems. Specialty gastroenterology practices specify liposomal formulations for celiac disease populations.
India
Cost-engineered oral dosage manufacturing anchors emerging market access strategies for domestic and export channels. FSSAI registration pathways determine market access speed for liquid drop formulations targeting pediatric populations. Mumbai and Ahmedabad pharmaceutical clusters specialize in micronized dry powder excipient production.
China
Cholecalciferol API manufacturing concentration creates single-source vulnerability for Western formulation facilities. NMPA oversight of pharmaceutical-grade vitamin D production shapes export quality tiering. Zhejiang and Jiangsu provinces host active pharmaceutical ingredient synthesis operations serving global formulation networks.
Brazil
ANVISA registration requirements govern liquid drop and injectable vitamin D product entry into Latin America's largest pharmaceutical market. Pediatric and geriatric homecare channels in São Paulo and Rio de Janeiro drive demand for swallowing-impaired formulations. Import dependency on Indian and Chinese API constrains local manufacturing scale.
Vitamin D Deficiency Treatment Market Competitive Environment
Concentration sits with diversified pharmaceutical conglomerates possessing hospital formulary relationships and integrated diagnostic capabilities. Three to five multinational corporations command institutional channel dominance through bundled procurement contracts. The competitive terrain separates into pharmaceutical-grade manufacturers, commodity dietary supplement suppliers, and diagnostic-therapy integrators. Consolidation through formulary access agreements and strategic partnerships defines current competitive dynamics.
Among hospital-centric pharmaceutical suppliers, Pfizer Inc. and Abbott exemplify the integrated platform archetype spanning vitamin D assay instrumentation through repletion therapy protocols. Sun Pharmaceutical Industries Ltd. occupies a position within the cost-engineered manufacturing tier serving emerging market volume channels. These three anchors represent distinct strategic postures: formulary relationship leverage, diagnostic-therapy convergence, and emerging market cost optimization.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Abbott |
| Merck & Co., Inc. |
| Sanofi |
| Novartis International AG |
| GSK plc |
| Bayer AG |
| Sun Pharmaceutical Industries Ltd. |
| Cadila Healthcare Ltd. |
| Others |
Value Chain & Pricing Dynamics
FDA's 21 CFR Part 111 Current Good Manufacturing Practice enforcement gates both supplier qualification and price tier differentiation in vitamin D therapy markets. Pharmaceutical-grade manufacturers absorb analytical chemistry and batch documentation costs that commodity dietary supplement channels bypass, creating a certification-driven pricing wedge between institutional and retail segments.
Pricing Analysis
Hospital procurement departments anchor contract-based long-term offtake structures that compress margins through formulary consolidation. Price differentiation hinges on USP monograph compliance tier and integrated diagnostic-testing bundling, with academic medical centers least sensitive and retail pharmacies most exposed to over-the-counter substitution. Pricing pressure intensifies in tablet and capsule tiers as Medicare reimbursement compression cascades through institutional channels.
Supply Chain Analysis
China and India anchor cholecalciferol active pharmaceutical ingredient synthesis, while the United States and Germany concentrate formulation and packaging operations. Western facilities draw from Asian API sources for oil-based excipients and micronized dry powder inputs. Single-source vulnerability concentrates in Zhejiang and Jiangsu province manufacturing clusters. Distribution runs through hospital GPO contracts, wholesale pharmacy networks, and direct-to-patient homecare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vitamin D deficiency treatment sits at the intersection of Medicare reimbursement expansion and liposomal bioavailability disruption, with formulation science now displacing manufacturing scale as the primary value driver. This technological inflection creates asymmetric opportunity across stakeholder positions.
For Market Incumbents: Secure hospital formulary relationships through integrated diagnostic-therapy platform bundling before laboratory-pharmacy consolidation completes. Invest in USP-compliant micronized dry powder capacity to defend against liposomal formulation entrants targeting malabsorption segments. Counter over-the-counter erosion by emphasizing prescription-grade potency verification in osteoporosis protocol adherence programs.
For New Entrants and Emerging Players: Lead with pediatric liquid formulation gaps in India and Brazil where FSSAI and ANVISA registration pathways remain navigable. Target homecare channels for swallowing-impaired geriatric populations in the United Kingdom and Australia through sublingual spray distribution partnerships. Differentiate through liposomal encapsulation technology for celiac and post-bariatric surgical populations in German and French specialty clinics.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates seeking to divest non-core vitamin D assets amid portfolio rationalization. Mid-tier manufacturers with captive USP laboratory infrastructure but limited formulary access represent consolidation candidates. Watch EMA pharmacovigilance database expansion for high-dose products as a signal of regulatory barrier elevation favoring established risk management systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Diagnostic-Therapy Platform | Abbott's convergence of vitamin D assay instrumentation with repletion protocols captures hospital laboratory-pharmacy procurement rationalization. |
| Liposomal Encapsulation Scale-Up | Bioavailability enhancement for celiac and Crohn's disease populations commands premium positioning in German gastroenterology practices. |
| Pediatric Liquid Formulation Registration | FSSAI and ANVISA pathway navigation unlocks swallowing-impaired infant segments in Mumbai and São Paulo homecare channels. |
| USP Monograph Compliance Investment | Analytical reference standard verification separates pharmaceutical-grade suppliers from commodity dietary supplement erosion. |
| Injectable Malabsorption Segment Focus | Parenteral ergocalciferol addresses bariatric surgery populations with premium pricing in United States academic medical centers. |
Study Parameters
Desk research of FDA 21 CFR Part 111 guidance documents, USP monograph specifications, and Medicare coverage determinations preceded structured interviews with hospital formulary directors, pharmaceutical procurement managers, regulatory affairs leads, and clinical laboratory directors. Secondary validation drew from CMS reimbursement databases, EMA pharmacovigilance filings, and hospital GPO contract disclosures. Bottom-up prescription volume modeling triangulated against top-down market sizing across pharmaceutical-grade and dietary supplement channels.
Variance decomposition across product type, delivery mode, age group, and end user segments shaped analytical framework construction over the projection horizon. CAGRs derived from Medicare-linked osteoporosis screening pipeline conversion rates, EMA high-dose surveillance expansion timelines, and liposomal formulation adoption curves in malabsorption indications. Modeled inputs incorporated batch release timeline compression effects and analytical chemistry talent scarcity constraints.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement for vitamin D testing or accelerated FDA CGMP enforcement would require recalibration. Forecasts reflect assumptions regarding hospital procurement consolidation velocity and liposomal bioavailability clinical validation. Recalibration cycles align with material shifts in Medicare coverage determinations and EMA pharmacovigilance database thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Mediterranean Mood and Stress Support Complexes Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Eye Care Supplements Market
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Sleep Aid Supplements Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Detox Products Market
Dietary Supplements
Soft Gel Capsule Market