
 Eye Care Supplements Market | 2026-2036
Eye Care Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Care Supplements Market Analysis
Subscription bundling of lutein-zeaxanthin combinations with omega-3 softgels is pivoting how consumers purchase eye care regimens. Bausch & Lomb leverages its ophthalmic heritage to anchor clinical credibility in practitioner-recommended channels. Kemin Industries, Inc. specializes in FloraGLO lutein sourcing, sustaining vertical control from marigold cultivation to finished ingredient. Nordic Naturals competes on purity certification, differentiating its marine omega-3 supply for ocular formulations.
Eye care supplements comprise orally administered nutraceuticals containing carotenoids, essential fatty acids, and antioxidant vitamins formulated to support retinal function and mitigate age-related oxidative stress. Standardized lutein extracts at 10-20mg doses and triglyceride-form omega-3 oils at 1,000mg+ EPA/DHA concentrations represent the primary bioactive specifications. Softgel delivery dominates ingredient stability requirements, while gummies are capturing fastest growth among younger computer users seeking palatable daily compliance. Online retail channels concentrate margin pools through subscription economics, though pharmacies retain authority for senior-directed therapeutic positioning.
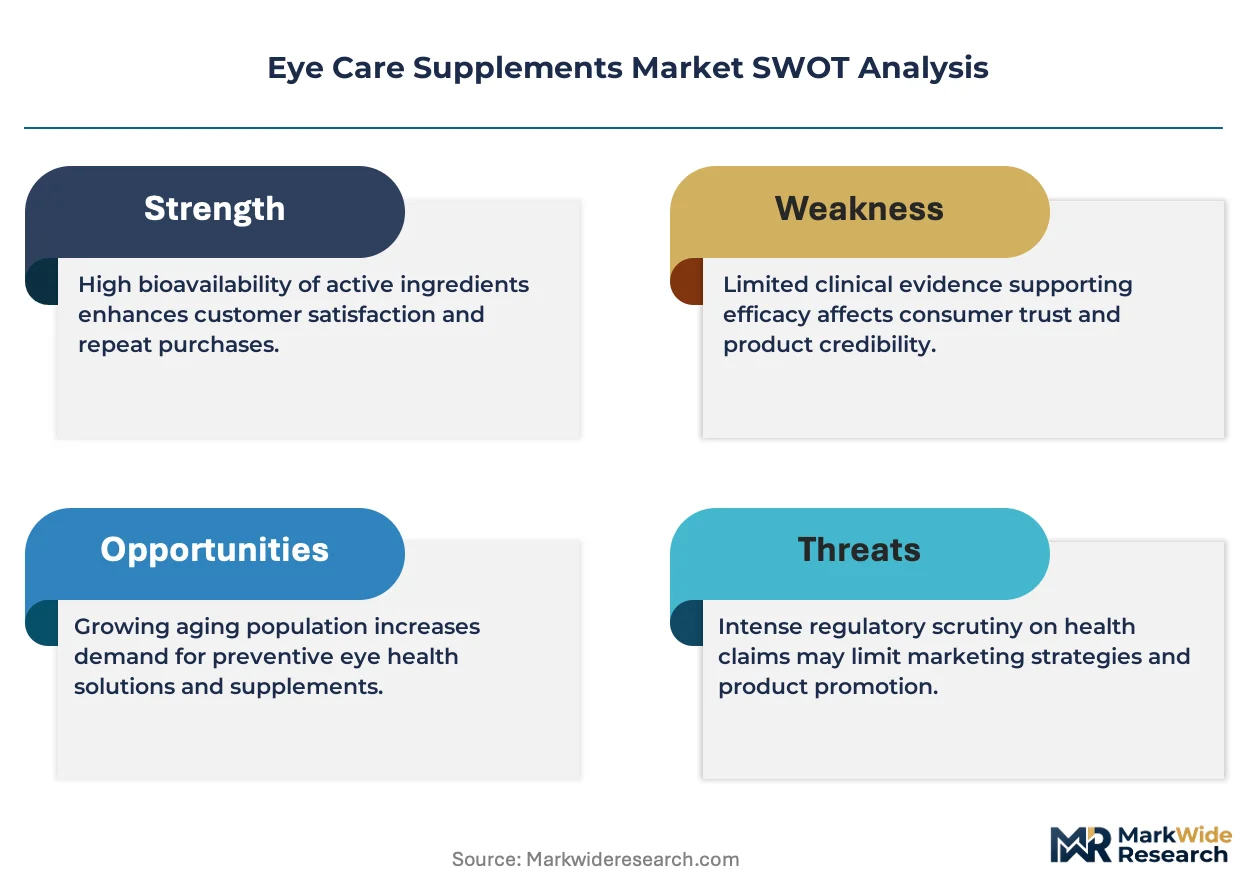
The FDA's NDI notification process and cGMP enforcement shape formulation compliance costs for US market entry, while the EFSA's health claims regulation restricts promotional language for European eye health positioning. FSSAI's recent nutraceutical labeling amendments in India are elevating import documentation burdens for cross-border e-commerce sellers. Stakeholders must monitor evolving substantiation requirements for structure-function claims as regulatory scrutiny intensifies across major demand centers.
Market Dynamics
Subscription bundling economics are compressing customer acquisition costs while concentrating margin pools in direct-to-consumer channels, fundamentally altering how lutein-zeaxanthin formulations reach end-users.
Growth Catalysts
- Aging Demographics in Germany and Japan:Expanding senior populations are amplifying demand for macular health formulations targeting age-related oxidative stress.
- FDA's NDI Notification Pathway:Tightening quality thresholds for imported formulations are elevating compliance barriers that favor established domestic manufacturers.
- Softgel Delivery Innovation:Advanced encapsulation technology is improving bioactive stability for carotenoid and omega-3 combinations, extending shelf life and efficacy claims.
Market Restraints
- Marigold Supply Concentration:Vertical control over FloraGLO lutein sourcing by dominant cultivators creates input dependency risk for secondary formulators.
- EFSA Health Claims Restriction:European promotional limitations on eye health positioning constrain marketing differentiation and consumer education efforts.
- Triglyceride-Form Omega-3 Cost Premium:Purity certification requirements for marine-derived EPA/DHA oils inflate raw material costs relative to ethyl ester alternatives.
Strategic Opportunities
- India's FSSAI Labeling Amendments:Elevated import documentation burdens for cross-border e-commerce create first-mover advantage for compliant domestic assemblers.
- Gummy Format Expansion:Palatable delivery systems targeting younger computer users represent underpenetrated compliance-driven demand.
- Practitioner-Recommended Channel Development:Clinical credibility anchoring through ophthalmic heritage positioning opens professional endorsement revenue streams.
Industry Challenges
- cGMP Enforcement Intensity:FDA facility inspections and documentation requirements are extending certification timelines for new market entrants.
- Structure-Function Claim Substantiation:Evidentiary demands for retinal support positioning require costly clinical validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Care Supplements Market |
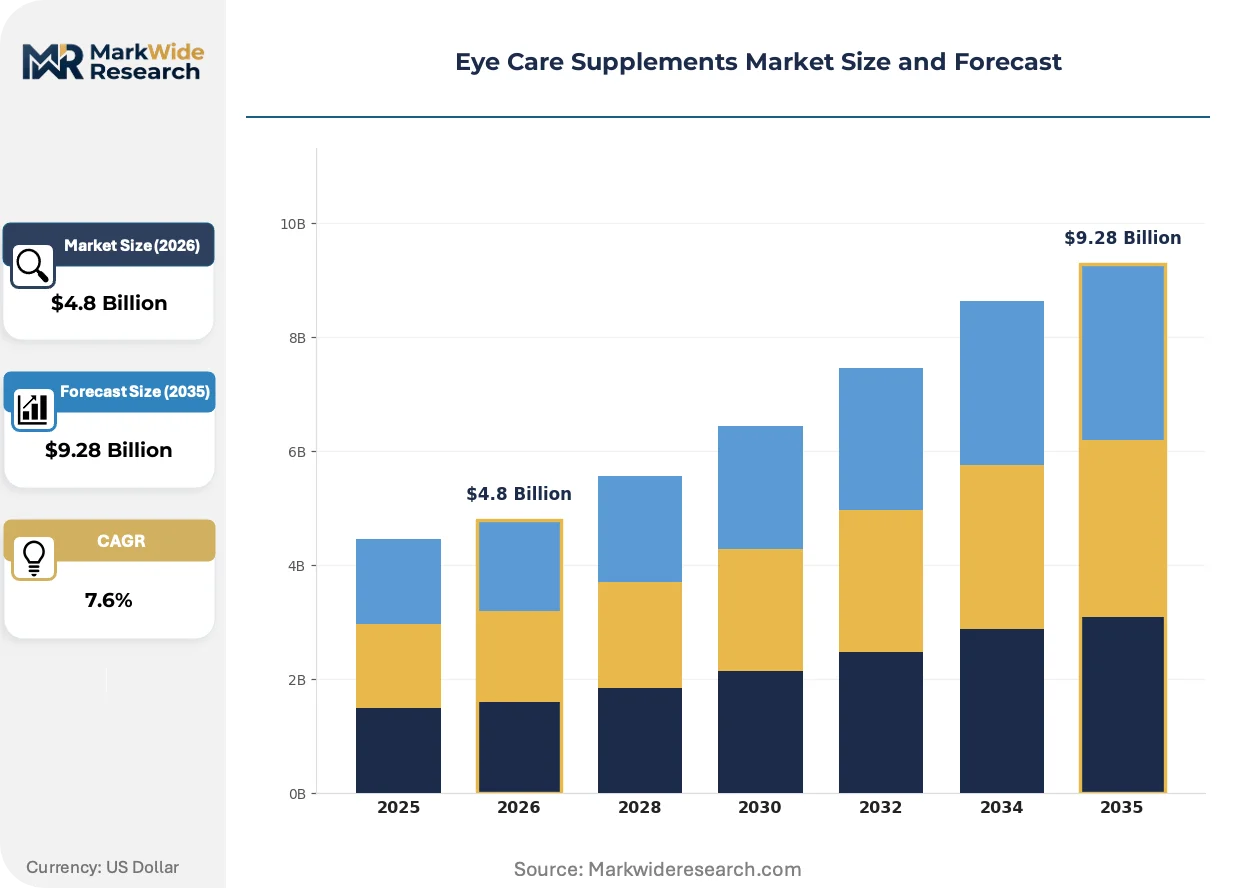
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softgels, Tablets, Gummies, Powders Ingredient Type: Lutein, Zeaxanthin, Omega-3, Vitamin A Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores Target Audience: Adults, Seniors, Athletes, Computer Users |
| Companies Covered | Bausch & Lomb, Vitabiotics Ltd., Amway International, The Nature's Bounty Co., ZeaVision LLC, Kemin Industries, Inc., Pfizer Inc., Nutrivein, Nordic Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Care Supplements Market Emerging Trajectories
Formulation science and channel economics are converging to reshape competitive positioning, with delivery technology and regulatory navigation emerging as primary differentiation vectors.
Liposomal encapsulation technology is rewriting absorption benchmarks for fat-soluble carotenoids. Bioavailability-focused formulators are adopting phospholipid-based delivery systems at accelerated pace. This innovation is compressing the efficacy gap between standard softgels and premium-positioned clinical-grade products.
EFSA's evolving health claims substantiation framework is tightening evidentiary standards for antioxidant eye health positioning. European manufacturers are reallocating R&D budgets toward clinical trial investments. Premium-tier brands with existing study portfolios are capturing shelf space as compliance costs exclude smaller competitors.
Computer users under forty are driving gummy format preference as daily compliance behavior shifts toward palatability. Direct-to-consumer subscription platforms are displacing pharmacy-centric replenishment for this demographic. Urban India and Southeast Asian metropolitan markets exhibit the strongest velocity for this channel transition.
Eye Care Supplements Market Segmentation
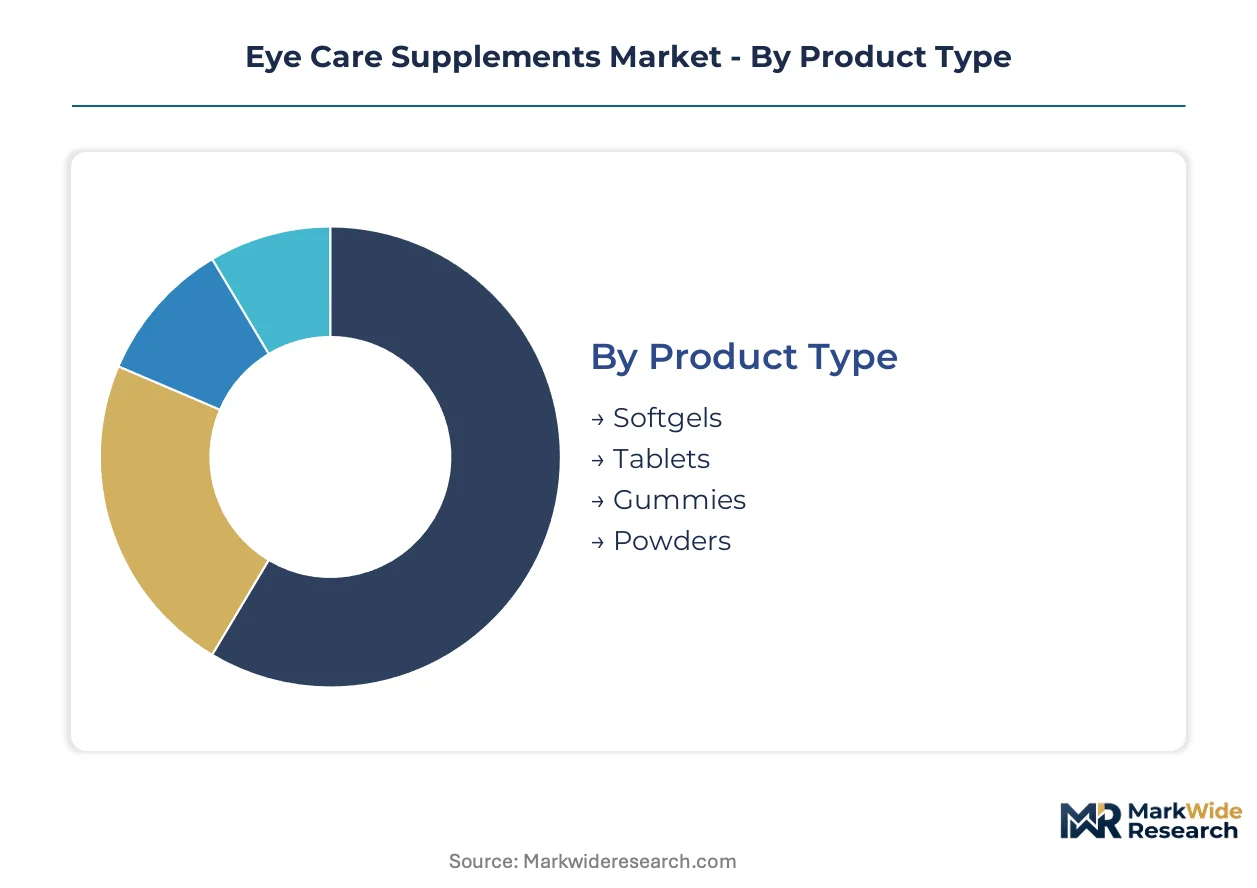
Delivery format and ingredient specification drive fundamentally different margin structures in eye care supplements. Channel selection determines whether brands compete on clinical credibility or subscription convenience economics.
Product Type:
Volume concentration favors shelf-stable formats, while premium positioning clusters around bioavailability-enhanced delivery systems.
- Softgels:Gelatin or vegetable-based shells encapsulate oil-soluble carotenoids and omega-3 fatty acids in oxygen-barrier packaging. Demand concentrates among seniors in Germany and Japan seeking practitioner-validated macular health regimens, with FDA cGMP compliance requirements elevating manufacturing barriers for new entrants.
- Gummies:Pectin or gelatin matrices suspend active ingredients in palatable chewable formats with sugar or sugar-free alternatives. Computer users under forty in urban India and Southeast Asian metropolitan markets drive fastest adoption, displacing pharmacy-centric replenishment through direct-to-consumer subscription platforms.
- Tablets:Compressed powder matrices deliver lutein and zeaxanthin in cost-efficient solid dose formats.
- Powders:Bulk active ingredients enable customizable dosing and beverage integration for performance-oriented consumers.
Mature deployment sits with Softgels. Newer deployment is concentrated in Gummies.
Ingredient Type:
Marigold-derived carotenoids anchor volume, while marine omega-3 oils command purity certification premiums.
- Lutein:Marigold flower extracts standardized to 10-20mg doses target retinal pigment density maintenance. FloraGLO sourcing from Kemin Industries sustains vertical control from cultivation to finished ingredient, creating input dependency risk for secondary formulators lacking captive supply.
- Omega-3:Triglyceride-form EPA/DHA oils at 1,000mg+ concentrations support ocular surface and retinal vascular health. Nordic Naturals competes on purity certification, differentiating marine-derived supply against ethyl ester alternatives with inferior bioavailability profiles.
- Zeaxanthin:Carotenoid isomer concentrated in macula center complements lutein in combination formulations.
- Vitamin A:Retinol and beta-carotene variants address night vision support and corneal maintenance.
Established clinical validation sits with Lutein. Steepest expansion trajectory belongs to Omega-3.
Distribution Channel:
Margin pool concentration follows customer acquisition cost differentials between subscription bundling and professional endorsement channels.
- Online Retail:Direct-to-consumer platforms leverage subscription economics to reduce customer acquisition costs for repeat lutein-zeaxanthin purchases. EFSA health claims restrictions constrain European promotional language, while FSSAI labeling amendments in India elevate import documentation burdens for cross-border sellers.
- Pharmacies:Brick-and-mortar dispensaries retain authority for senior-directed therapeutic positioning through practitioner recommendation networks. Bausch & Lomb leverages ophthalmic heritage to anchor clinical credibility in these channels.
- Supermarkets:Mass retail placement captures impulse and convenience-driven purchases with limited clinical consultation.
- Health Stores:Specialty retailers serve enthusiast consumers seeking premium-positioned or practitioner-exclusive formulations.
Traditional volume concentration sits with Pharmacies. Channel transition momentum favors Online Retail.
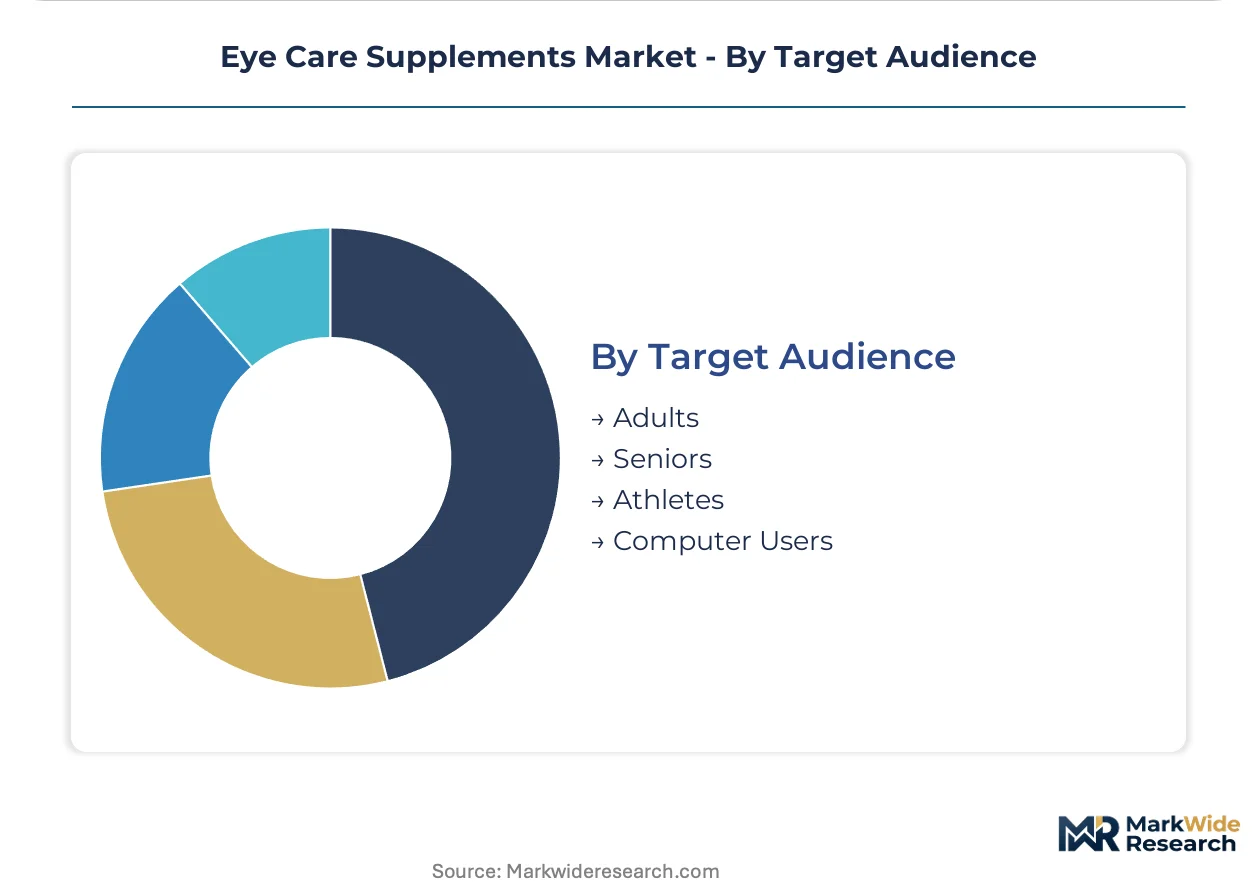
Target Audience:
Age-related oxidative stress positioning dominates premium tier, while screen-time mitigation opens compliance-driven younger segments.
- Seniors:Consumers over sixty-five seeking age-related macular degeneration prevention represent the core reimbursed and practitioner-recommended demand base. Aging demographics in Germany and Japan amplify this segment's expansion.
- Computer Users:Younger professionals experiencing digital eye strain drive gummy format preference and subscription bundling adoption. Palatability requirements reshape daily compliance behavior away from traditional softgel regimens.
- Adults:General wellness seekers pursue preventive ocular health maintenance without specific pathology targeting.
- Athletes:Performance-oriented consumers prioritize visual acuity and reaction time optimization for competitive advantage.
Established therapeutic positioning sits with Seniors. Gaining share fastest is Computer Users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Jebel Ali concentrate supplement distribution for Middle Eastern markets, while India's Special Economic Zones in Hyderabad and Pune attract contract manufacturing investment for export-oriented nutraceutical production.
United States
Senior populations in Florida and Arizona drive practitioner-recommended macular health formulations. FDA cGMP enforcement and NDI notification requirements elevate compliance barriers for imported products. The Research Triangle in North Carolina hosts clinical trial infrastructure supporting structure-function claim substantiation.
Germany
Aging demographics in Bavaria and Baden-Württemberg expand the consumer base for lutein-zeaxanthin combinations. EFSA health claims restrictions constrain promotional language for antioxidant eye health positioning. Frankfurt's logistics cluster serves as the primary distribution hub for Central European markets.
Japan
Consumers over sixty-five in Tokyo and Osaka metropolitan areas sustain demand for functional eye health foods. METI's Foods with Function Claims system provides a regulatory pathway distinct from pharmaceutical oversight. Kanto region manufacturing facilities specialize in softgel encapsulation technology for carotenoid stability.
India
Urban professionals in Mumbai and Bengaluru experiencing digital eye strain drive gummy format adoption through direct-to-consumer channels. FSSAI's nutraceutical labeling amendments elevate import documentation burdens for cross-border e-commerce sellers. Hyderabad's pharmaceutical corridor attracts contract manufacturing investment for export-oriented production.
China
Screen-time mitigation demand among younger consumers in Shanghai and Shenzhen accelerates palatable delivery format preference. NMPA's health food registration requirements shape formulation compliance costs for domestic and imported products. The Yangtze River Delta cluster concentrates contract manufacturing capacity for omega-3 softgel production.
Eye Care Supplements Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and channel dimensions. The vendor base organizes around three strategic archetypes: ophthalmic heritage brands leveraging clinical credibility, ingredient technology specialists controlling upstream supply, and direct-to-consumer platforms optimizing subscription economics. Consolidation pressure intensifies as regulatory compliance costs exclude smaller formulators. Dominant competitive moves include backward integration into marigold cultivation and strategic partnerships with practitioner recommendation networks.
Within the ophthalmic heritage tier, Bausch & Lomb and Pfizer Inc. exemplify clinical credibility anchoring through professional channel development. Kemin Industries, Inc. occupies a position representing upstream control over FloraGLO lutein sourcing from cultivation through finished ingredient. Nordic Naturals sits within the purity certification specialist archetype, differentiating marine omega-3 supply for ocular formulations. These three companies collectively illustrate how vertical control, clinical endorsement, and quality certification serve as alternative vectors for competitive differentiation.
| Leading Market Players |
|---|
| Bausch & Lomb |
| Vitabiotics Ltd. |
| Amway International |
| The Nature's Bounty Co. |
| ZeaVision LLC |
| Kemin Industries, Inc. |
| Pfizer Inc. |
| Nutrivein |
| Nordic Naturals |
| Others |
Supply Flow & Price Mechanics
Marigold cultivation costs in India and China cascade through lutein extract pricing tiers, with FloraGLO-certified premiums separating practitioner-recommended formulations from mass-market alternatives. FDA cGMP compliance investments and triglyceride-form omega-3 purity certifications concentrate margin capture among vertically integrated manufacturers while compressing secondary formulator economics.
Pricing Analysis
Cost-down pressure on standard softgel tiers accelerates because ethyl ester omega-3 alternatives undercut triglyceride-form premiums despite inferior bioavailability profiles. Three-tier pricing structure across premium, standard, and economy levels separates Nordic Naturals-certified marine oils from private-label imports and domestic Indian assemblers. Price differentiation rests on EFSA health claims substantiation investment and subscription bundling volume discounts. Computer users under forty exhibit lowest price sensitivity for palatable gummy formats, while pharmacy-directed seniors prioritize clinical credibility over unit cost.
Supply Chain Analysis
India's FSSAI labeling amendments and China's NMPA health food registration requirements are reshaping sourcing patterns toward compliant domestic assemblers. Marigold flower cultivation concentrates in India, China, and Mexico, with Kemin Industries maintaining captive FloraGLO supply from seed to finished extract. Raw material dependencies include phospholipid encapsulation agents, gelatin or pectin matrix materials, and oxygen-barrier packaging films. Single-source vulnerability sits with concentrated FloraGLO licensing. Distribution runs through direct-to-consumer subscription platforms and practitioner-recommended pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liposomal encapsulation technology is displacing standard softgel absorption benchmarks, compressing the efficacy gap between premium clinical-grade and mass-market formulations. This transition rewards manufacturers with phospholipid delivery system capabilities while threatening legacy softgel specialists.
For Market Incumbents: Deepen backward integration into marigold cultivation or captive phospholipid sourcing to defend input cost position against Kemin Industries' vertical control. Secure FDA structure-function claim substantiation through clinical trial investment before EFSA evidentiary thresholds tighten further. Channel control through practitioner recommendation networks anchors pricing power against direct-to-consumer subscription erosion. For New Entrants and Emerging Players: The gap between Nordic Naturals-certified premium omega-3 and economy ethyl ester alternatives offers white-space entry for mid-tier triglyceride-form positioning. Target urban India and Southeast Asian metropolitan markets where FSSAI compliance burdens exclude cross-border sellers. Pursue gummy format specialization for computer users under forty through direct-to-consumer subscription platforms with palatability-first formulation. For Investors and Strategic Acquirers: Consolidation of marigold cultivation assets beneath three dominant processors is the leading indicator that upstream supply control will determine long-term formulation economics. Five-to-ten-year viability favors acquiring ingredient technology specialists with existing clinical trial portfolios over brand-dependent marketers. Watch for FDA warning letters on structure-function claims as the signal for regulatory-driven margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Marigold Cultivation | Kemin Industries' FloraGLO model demonstrates captive supply control from seed to extract. |
| Liposomal Encapsulation Technology Adoption | Phospholipid delivery systems rewrite bioavailability benchmarks for carotenoid absorption. |
| Direct-to-Consumer Subscription Platform Launch | Urban India and Southeast Asian markets exhibit strongest channel transition velocity. |
| Practitioner Recommendation Network Partnership | Bausch & Lomb leverages ophthalmic heritage to anchor clinical credibility in pharmacy channels. |
| EFSA Health Claims Substantiation Investment | Clinical trial portfolios capture shelf space as compliance costs exclude smaller European competitors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with formulation scientists, nutraceutical procurement managers, ophthalmology clinic administrators, and direct-to-consumer platform operators. FDA NDI notification databases, EFSA health claims registers, FSSAI labeling amendment records, and METI Foods with Function Claims submissions provided regulatory trajectory inputs. Bottom-up channel volume estimates and top-down macroeconomic demand drivers were cross-validated through triangulation.
Data-stream reconciliation across shipment volumes, ingredient pricing indices, and channel sell-through patterns informed the analytical framework. Segmentation dimensions modeled include delivery format, ingredient specification, distribution channel, and target audience demographics across the projection horizon. CAGRs were derived from normalized growth rate convergence between demand-side demographic projections and supply-side capacity expansion timelines. Forecast inputs incorporated marigold harvest yield variability and omega-3 marine source sustainability constraints.
Inputs from regulatory databases and trade customs were available through the study window; gaps in real-time subscription platform transaction data introduce uncertainty bands around direct-to-consumer channel estimates. Forecasts reflect documented assumptions regarding EFSA substantiation timeline delays and FSSAI enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Non-Hormonal Steroid Modulators Market
Dietary Supplements
Serotonin Supplement Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Pet Allergy Immune Supplements Market
Dietary Supplements
Global Beauty Supplements Market
Dietary Supplements
Magnesium Glycinate Market
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Concentrated Angelica Pills Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Soft Gel Capsule Market