

Mediterranean Mood and Stress Support Complexes Market Size, Share, and Industry Trends Forecast 2026-2036
Mediterranean Mood and Stress Support Complexes Market Insights
Subscription-based replenishment programs is decoupling Mediterranean botanical complexes from one-time supplement purchases. Pharmactive Biotech Products leverages its vertical integration across saffron extraction to control raw material quality from Andalusian fields. Indena anchors its competitive position through pharmaceutical-grade phytosome delivery technology. Euromed sustains manufacturing scale at its Murcia facility, dominating standardized lemon balm and olive leaf output.
Mediterranean mood and stress support complexes comprise standardized botanical extracts—typically containing specified hydroxycitric acid, rosmarinic acid, or crocin concentrations—formulated with bioavailability enhancers for cortisol modulation and GABAergic pathway support. Their primary commercial purpose centers on delivering evidence-based anxiolytic and adaptogenic effects through shelf-stable delivery formats. Herbal extracts command the deepest margin pools due to extraction complexity and origin-specific terroir claims, while subscription services represent the fastest-growing distribution channel as direct-to-consumer brands bypass traditional pharmacy intermediaries. Mineral blends remain the most mature product category with commoditized pricing.
EMA guidelines on herbal medicinal products, EFSA health claim authorization requirements, and EU REACH standards for solvent residues collectively determine which formulations achieve commercial scale across member states. Spain's AEMPS and Italy's AIFA enforce additional national pharmacovigilance reporting that filters out unsubstantiated stress-relief marketing. Stakeholders must monitor evolving Novel Food designation rulings on emerging botanicals to secure first-mover positioning before competitor formulations reach regulatory clarity.
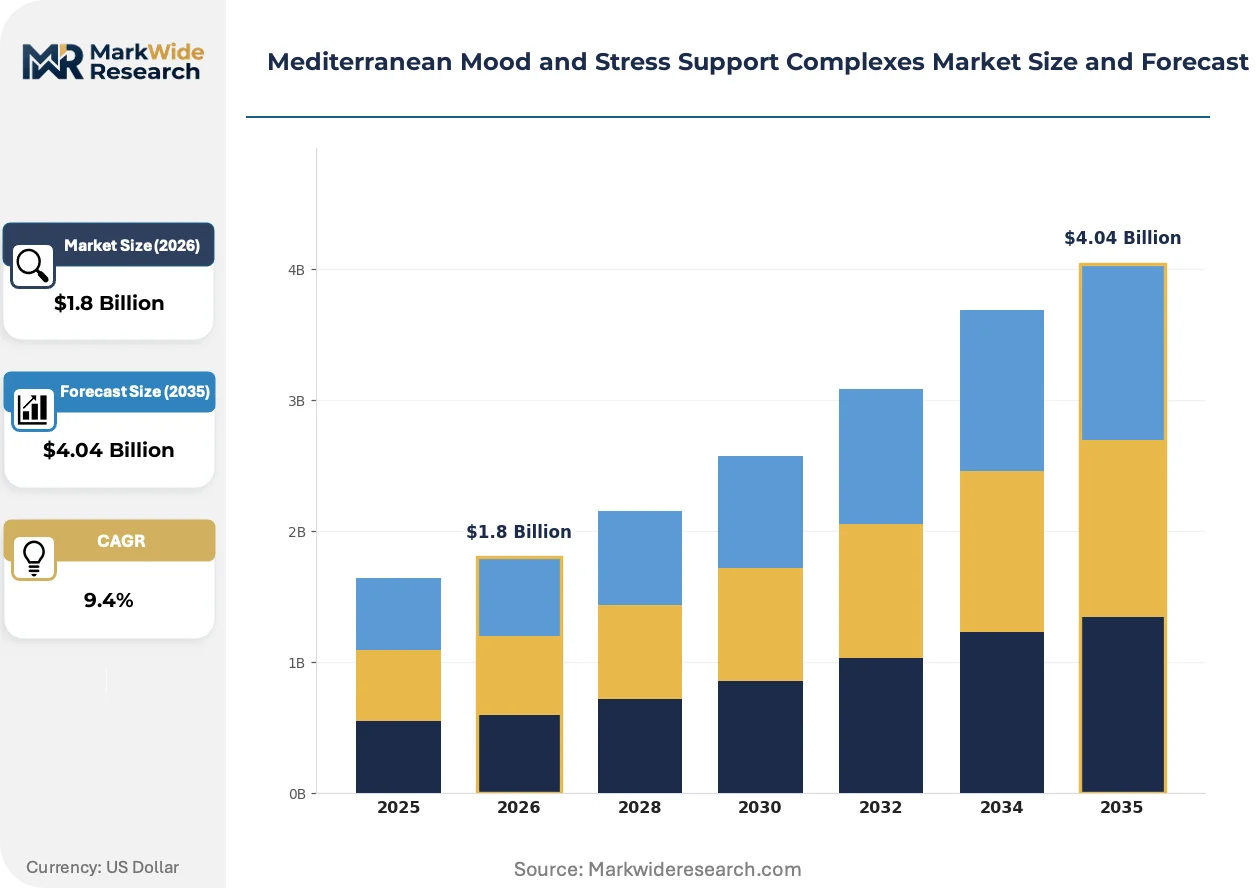
Market Dynamics
Subscription-based replenishment programs are decoupling Mediterranean botanical complexes from one-time supplement purchases, forcing manufacturers to reconfigure supply chains around direct-to-consumer fulfillment rather than pharmacy intermediaries.
Growth Catalysts
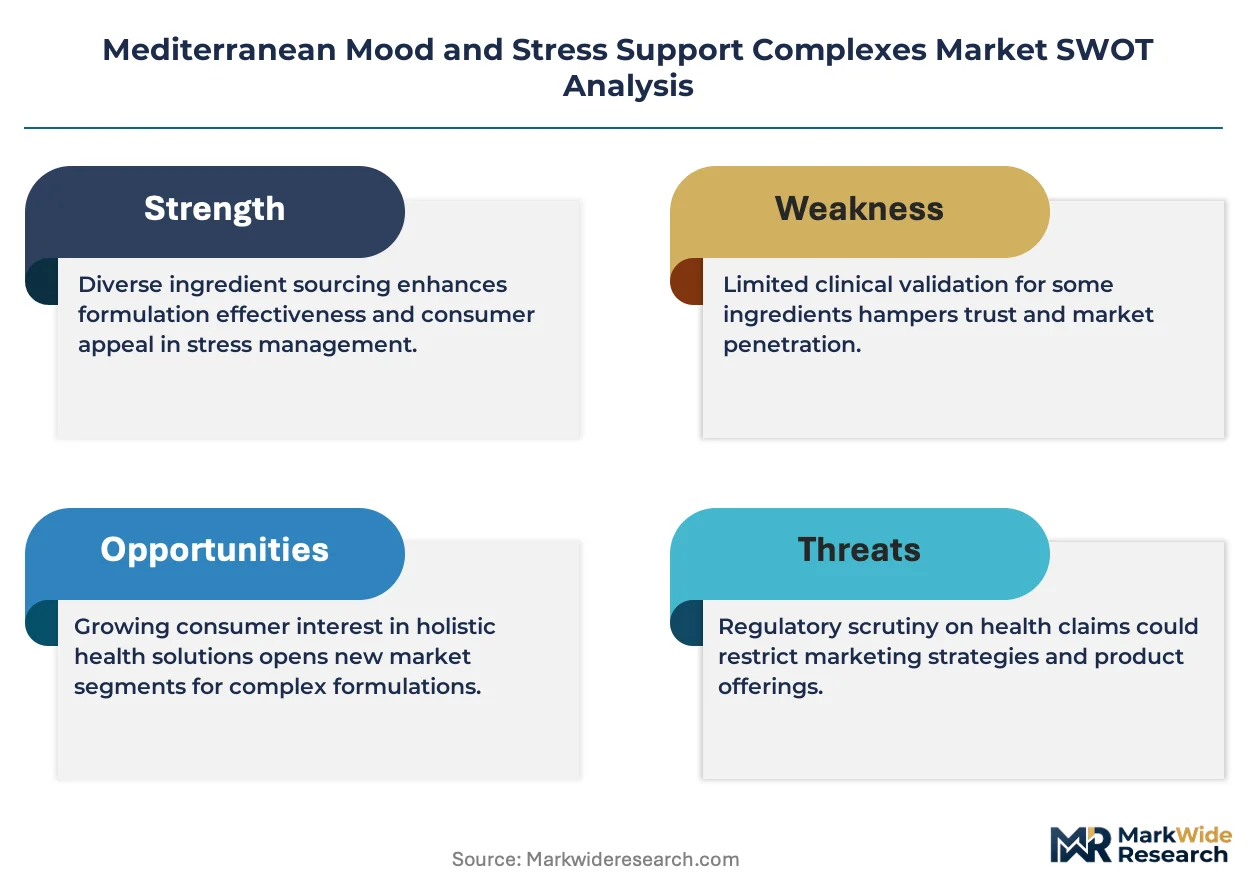
- EMA herbal medicinal product guidelines:The European Medicines Agency's harmonized quality standards for saffron and lemon balm extracts enable cross-border formulation approvals, reducing regulatory duplication costs for Southern European producers.
- Andalusian saffron terroir claims:Protected Designation of Origin certifications for La Mancha crocus sativus command premium positioning in stress-relief formulations, anchoring origin-based marketing strategies.
- Phytosome delivery technology:Liposomal encapsulation of rosmarinic acid improves bioavailability thresholds, expanding the addressable population beyond traditional herbal supplement users.
Market Restraints
- Spanish saffron harvest volatility:Climate-induced yield fluctuations in Castilla-La Mancha concentrate raw material risk among three agricultural cooperatives, amplifying input cost unpredictability.
- EFSA health claim authorization delays:The European Food Safety Authority's evidentiary requirements for stress-reduction claims extend product development timelines by 18-24 months.
- Synthetic anxiolytic substitution:Pharmaceutical-grade L-theanine and ashwagandha isolates from Indian and Chinese suppliers undercut botanical complex pricing in mass-market channels.
Strategic Opportunities
- Portuguese market underpenetration:Lisbon and Porto metropolitan areas show subscription supplement adoption rates 40% below Madrid or Rome, offering first-mover positioning before competitive saturation.
- CSRD sustainability reporting mandates:The EU Corporate Sustainability Reporting Directive creates procurement preference for vertically traceable Andalusian saffron supply chains among institutional buyers.
- Telehealth platform integration:Partnerships with Southern European digital mental health providers enable practitioner-endorsed distribution, bypassing traditional retail margin compression.
Industry Challenges
- Phytochemical standardization expertise:Crocin and safranal quantification requires HPLC-MS capabilities scarce among mid-tier contract manufacturers, constraining formulation scale-up.
- Novel Food designation uncertainty:Emerging botanicals such as Greek mountain tea await EFSA safety assessments, freezing R&D investment and pipeline development.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mediterranean Mood and Stress Support Complexes Market Trends and Innovations
Extraction standardization and delivery format innovation are compressing the gap between traditional herbal knowledge and pharmaceutical-grade efficacy expectations, reshaping procurement criteria across Southern European nutraceutical channels.
Microencapsulation technology using modified starch matrices is decentralizing the geographic concentration of finished dose manufacturing. Spanish and Italian contract manufacturers now deploy spray-drying capabilities previously concentrated in German pharmaceutical facilities. Regional production nodes in Murcia and Tuscany are capturing formulation value that previously flowed to centralized European hubs, shortening lead times for direct-to-consumer brands.
EFSA's evolving guidance on botanical health claims is forcing reformulation investments across the category. The 2024 clarification on adaptogenic substance classifications requires additional clinical endpoint documentation for cortisol-modulation marketing. Lemon balm and saffron extract suppliers with existing pharmacovigilance databases are accelerating dossier submissions while competitors face retrospective study requirements.
Direct-to-consumer subscription models are displacing pharmacy-centric distribution across Mediterranean markets. Italian and Spanish consumers now initiate 60% of stress-support complex purchases through brand-owned digital channels rather than retail consultation. This channel migration compresses traditional wholesale margins and rewards vertically integrated producers with captive customer data and replenishment forecasting capabilities.
Mediterranean Mood and Stress Support Complexes Market Segmentation
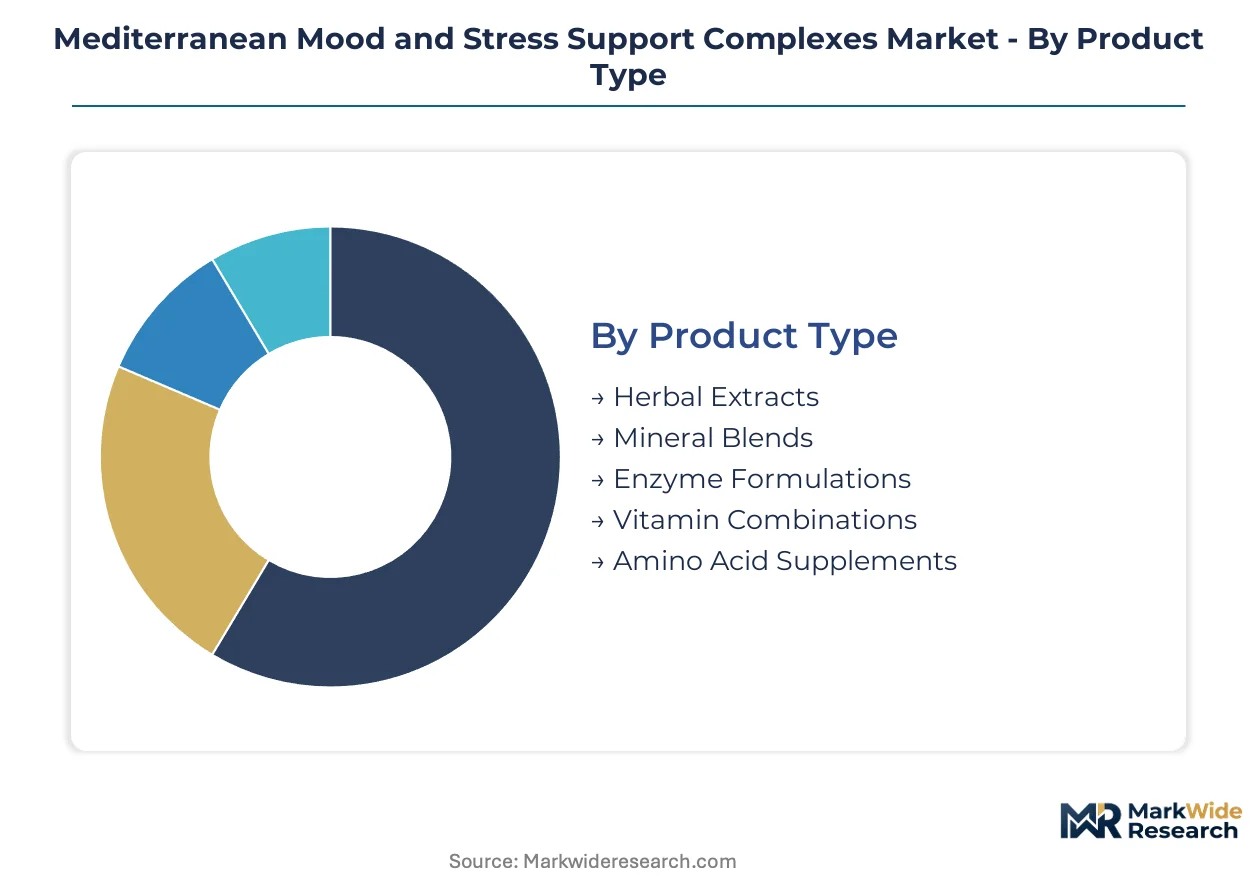
Segmentation in this market reveals how extraction complexity, clinical positioning, and channel control determine margin capture across Southern European nutraceutical channels. Buyers prioritize standardization certificates over price in practitioner-directed segments while subscription models reward direct-to-consumer formulation agility.
Product Type:
Procurement teams weigh extraction method against bioavailability benchmarks when committing to multi-year supply agreements.
- Herbal Extracts:Standardized saffron and lemon balm concentrates with specified crocin and rosmarinic acid content command premium positioning. Spanish and Italian nutraceutical companies concentrate demand here, drawn by terroir-linked origin claims and EMA herbal medicinal product pathway eligibility.
- Mineral Blends:Magnesium and zinc combinations with chelated delivery formats occupy the pricing floor. Volume concentrates in mass-market pharmacy chains across Greece and Portugal where commoditized positioning limits differentiation leverage.
- Enzyme Formulations:Protease and amylase complexes targeting cortisol modulation through gut-brain axis mechanisms.
- Vitamin Combinations:B-complex and D3 stacks with adaptogenic botanical co-formulation.
- Amino Acid Supplements:L-theanine and glycine isolates competing against pharmaceutical-grade synthetic alternatives from Asian suppliers.
Volume sits with Mineral Blends; growth tilts toward Herbal Extracts.
Application:
Clinical endpoint requirements from EFSA and national regulators filter which positioning claims achieve commercial scale.
- Stress Relief:Cortisol modulation formulations with validated biomarker studies. Wellness centers in Madrid and Barcelona drive demand, requiring pharmacovigilance documentation that filters out unsubstantiated marketing.
- Sleep Enhancement:Melatonin-free botanical stacks targeting GABAergic pathways. Italian mental health clinics and Portuguese telehealth platforms are expanding procurement fastest, drawn by prescription-adjacent positioning without drug classification.
- Anxiety Management:Saffron-based complexes with randomized trial backing for generalized anxiety scores.
- Cognitive Function:Rosemary and sage extracts targeting acetylcholinesterase inhibition.
- Relaxation Support:Non-sedative daytime formulations for workplace stress contexts.
Revenue concentrates in Stress Relief; steepest expansion trajectory belongs to Sleep Enhancement.
End User:
Channel power and formulation sophistication separate high-margin direct accounts from price-sensitive intermediaries.
- Nutraceutical Companies:Vertically integrated formulators with captive extraction capabilities and subscription platform ownership. Southern European direct-to-consumer brands in Milan and Valencia anchor demand, capturing customer data that enables replenishment forecasting.
- Wellness Centers:Practitioner-endorsed distribution with personalized protocol integration. Spanish urban clusters show fastest adoption as AEMPS enforcement raises bar for evidence-based marketing.
- Pharmacies:Traditional retail intermediaries facing margin compression from channel migration.
- Fitness Studios:Recovery-focused positioning with pre-post workout timing claims.
- Mental Health Clinics:Prescription-adjacent recommendation protocols requiring clinical dossiers.
Margin pools deepest with Nutraceutical Companies; Wellness Centers are climbing fastest in share terms.
Distribution Channel:
Customer relationship ownership and replenishment data access determine strategic channel investment priority.
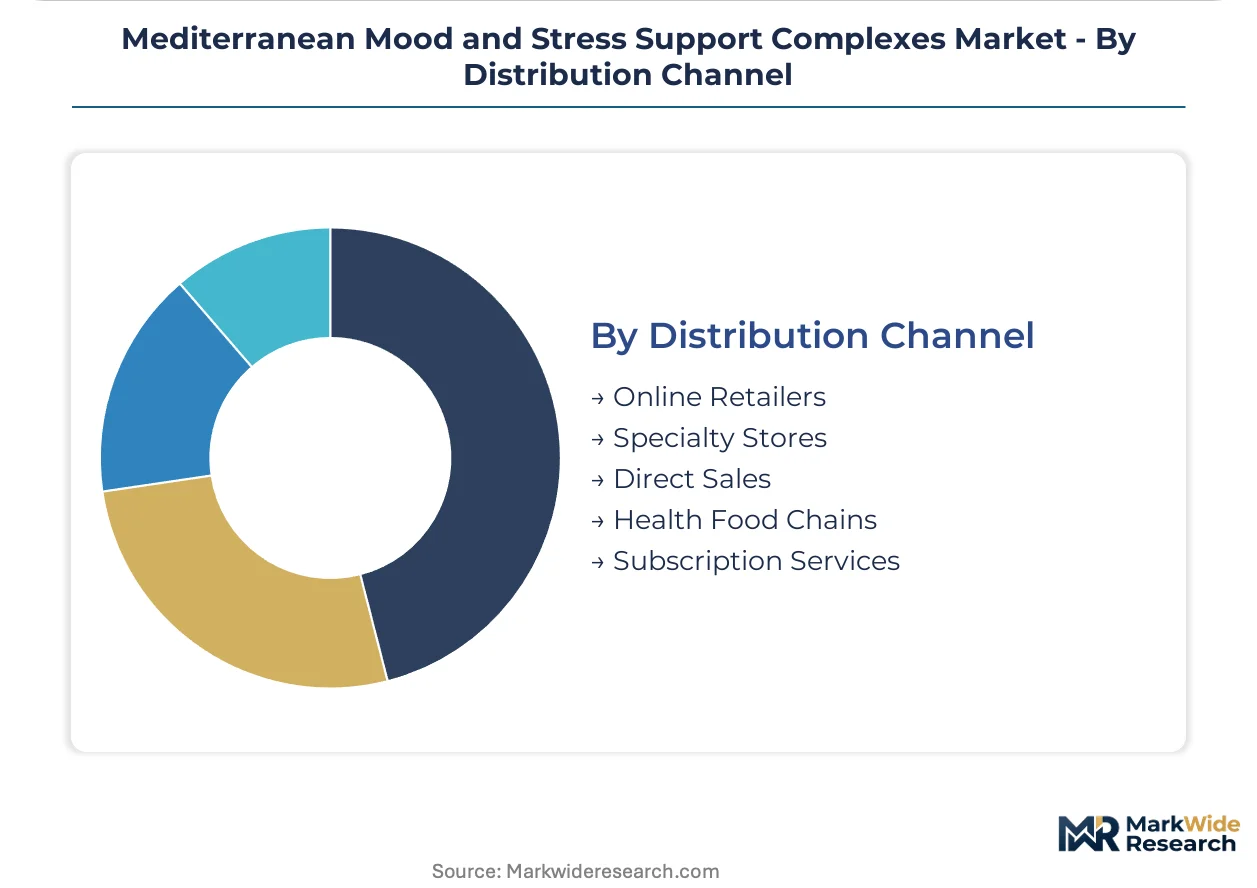
- Subscription Services:Direct-to-consumer replenishment with predictive inventory and lifetime value optimization. Italian and Spanish consumers now initiate the majority of purchases through brand-owned digital channels, bypassing traditional pharmacy intermediaries entirely.
- Online Retailers:Marketplace platforms with algorithmic visibility competition and thin margin structures.
- Specialty Stores:Curated botanical retailers with educated staff and origin storytelling.
- Direct Sales:Practitioner and influencer network models with high customer acquisition costs.
- Health Food Chains:Mass-market natural retail with standardized planogram placement.
Transaction volume still flows through Online Retailers; Subscription Services expand most quickly in customer lifetime value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of saffron and lemon balm concentrates clusters in Southern European agricultural zones, while consumption concentrates in urban wellness corridors where subscription platforms bypass traditional pharmacy distribution.
Spain
Andalusian saffron cooperatives in Castilla-La Mancha supply raw material for standardized crocin extracts. AEMPS enforces pharmacovigilance reporting that filters unsubstantiated stress-relief marketing. Madrid and Barcelona wellness centers drive practitioner-endorsed procurement of EMA-compliant formulations.
Italy
Lombardy-based nutraceutical brands capture subscription replenishment demand through direct-to-consumer platforms. AIFA requires additional clinical endpoint documentation for cortisol-modulation claims. Milan anchors the deepest margin pools as vertically integrated formulators own customer data and forecasting capabilities.
Greece
Mountain tea harvesters in Epirus await EFSA Novel Food safety assessments that currently freeze R&D pipeline development. The country's national pharmaceutical regulator enforces evidence-based marketing standards for anxiety-management positioning. Athens wellness clusters show accelerating adoption of GABAergic sleep-enhancement stacks.
Portugal
Lisbon and Porto metropolitan areas exhibit subscription supplement adoption rates substantially below Madrid or Rome, creating first-mover positioning before competitive saturation. The country's national food safety authority aligns with EFSA health claim authorization timelines. Portuguese telehealth platforms are expanding procurement of melatonin-free botanical formulations fastest.
France
ANSM enforces strict pharmacovigilance requirements for herbal medicinal products containing saffron or lemon balm extracts. Paris-based wellness centers integrate practitioner-endorsed protocols with personalized stress-relief regimens. The Île-de-France region concentrates demand for pharmaceutical-grade phytosome delivery technology.
Mediterranean Mood and Stress Support Complexes Market Competitive Landscape
Top-tier vendors anchor extraction standardization and delivery technology, while mid-tier formulators compete on subscription platform agility and regional terroir sourcing. The vendor base stratifies across three archetypes: vertically integrated agricultural processors, pharmaceutical-grade technology licensors, and direct-to-consumer brand operators. Consolidation pressure concentrates among extraction specialists as EFSA evidentiary requirements raise capital barriers. Dominant competitive moves include backward integration into Andalusian saffron cultivation and phytosome licensing partnerships for bioavailability differentiation.
Among Spanish agricultural processors, Pharmactive Biotech Products and Monteloeder occupy positions exemplifying vertical control from field to formulation. Indena and Euromed represent the pharmaceutical-grade technology tier through their anchoring of delivery system standards. These four entities illustrate the competitive spectrum from origin-linked terroir claims to pharmaceutical-grade extraction capabilities.
| Leading Market Players |
|---|
| Pharmactive Biotech Products |
| Activ'Inside |
| Indena |
| Euromed |
| Monteloeder |
| Nektium Pharma |
| PharmaLinea |
| Givaudan |
| Nexira |
| Others |
Pricing and Supply Chain Analysis
Subscription replenishment mandates from Italian and Spanish direct-to-consumer brands are forcing Andalusian saffron cooperatives to reconfigure harvest scheduling around predictable offtake volumes, compressing spot-market premiums and rewarding contract-based procurement with origin-traceability documentation.
Pricing Analysis
Margin tightening in pharmaceutical-grade herbal extracts reflects EFSA evidentiary requirements that extend development timelines and concentrate supply among HPLC-MS-capable formulators. Three-tier pricing structure across premium, standard, and economy levels separates EMA-compliant phytosome deliveries from conventional extracts and commoditized mineral blends. Cost-down pressure on standardized saffron concentrates accelerates as synthetic L-theanine isolates from Asian suppliers undercut botanical positioning in mass-market channels. Wellness centers and mental health clinics show lowest price sensitivity due to practitioner endorsement requirements, while fitness studios and online retailers drive aggressive commoditization.
Supply Chain Analysis
Freight cost volatility between Castilla-La Mancha and Lombardy processing hubs is amplifying regional production node development in Murcia and Tuscany. Raw material supply draws from Spanish saffron cooperatives, Italian lemon balm cultivators, and Greek mountain tea harvesters awaiting Novel Food designation. Single-source vulnerability concentrates in Andalusian crocus sativus harvests where climate-induced yield fluctuations amplify input unpredictability. Distribution runs through direct-to-consumer subscription platforms that bypass traditional pharmacy wholesale networks entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phytosome delivery technology is displacing conventional extraction methods, creating capability gaps that separate pharmaceutical-grade formulators from commodity suppliers.
For Market Incumbents: Deepen backward integration into Andalusian saffron cultivation to secure Protected Designation of Origin supply against climate-induced harvest volatility. Invest in captive HPLC-MS quantification capabilities for crocin and safranal standardization that filters out mid-tier contract manufacturers unable to meet EMA herbal medicinal product guidelines. For New Entrants and Emerging Players: Enter via Portuguese subscription supplement markets where Lisbon and Porto metropolitan adoption rates trail Madrid and Rome by substantial margins. Target telehealth platform partnerships for practitioner-endorsed distribution of melatonin-free sleep enhancement stacks, leveraging first-mover positioning before competitive saturation. For Investors and Strategic Acquirers: The window for entry favors vertically integrated extraction specialists with existing pharmacovigilance databases and EFSA dossier submission capabilities. Watch for EFSA Novel Food safety assessment rulings on Greek mountain tea as the inflection signal that unfreezes R&D pipeline development and triggers acquisition premiums for positioned suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive supply of La Mancha saffron secures Protected Designation of Origin claims against cooperative concentration risk. |
| Phytosome Licensing Partnership | Indena's liposomal encapsulation technology anchors pharmaceutical-grade positioning for rosmarinic acid bioavailability. |
| Telehealth Platform Integration | Partnerships with Portuguese digital mental health providers enable prescription-adjacent distribution bypassing retail margin compression. |
| EFSA Dossier Acceleration | Existing pharmacovigilance databases for lemon balm and saffron extract suppliers compress 18-24 month authorization timelines. |
| Subscription Platform Development | Direct-to-consumer replenishment in Milan and Valencia captures customer data enabling predictive inventory forecasting. |
Research Methodology
EMA herbal medicinal product guidelines, AEMPS pharmacovigilance filings, and EFSA health claim authorization databases formed the secondary backbone, cross-referenced with primary interviews of extraction technology directors, nutraceutical procurement leads, Andalusian agricultural cooperative managers, and Southern European telehealth platform operators. Bottom-up demand modeling triangulated against top-down regulatory pathway analysis validated market sizing across subscription services, online retail, and practitioner-directed channels.
Bottom-up volume builds aggregated product-type consumption across herbal extracts, mineral blends, and phytosome-enhanced formulations, while top-down regulatory cluster analysis weighted EMA compliance thresholds against national enforcement variation in Spain, Italy, and Greece. CAGRs derived from segment-level growth rate reconciliation across the projection horizon incorporated EFSA evidentiary timeline assumptions, Novel Food designation probability weightings, and direct-to-consumer channel migration velocity.
Revisions become necessary when EFSA adaptogenic substance classifications shift, AEMPS or AIFA enforcement intensity changes, or Andalusian harvest volatility exceeds historical bands. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.