
 Herbal Medicine Market | 2026-2036
Herbal Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Medicine Market Intelligence
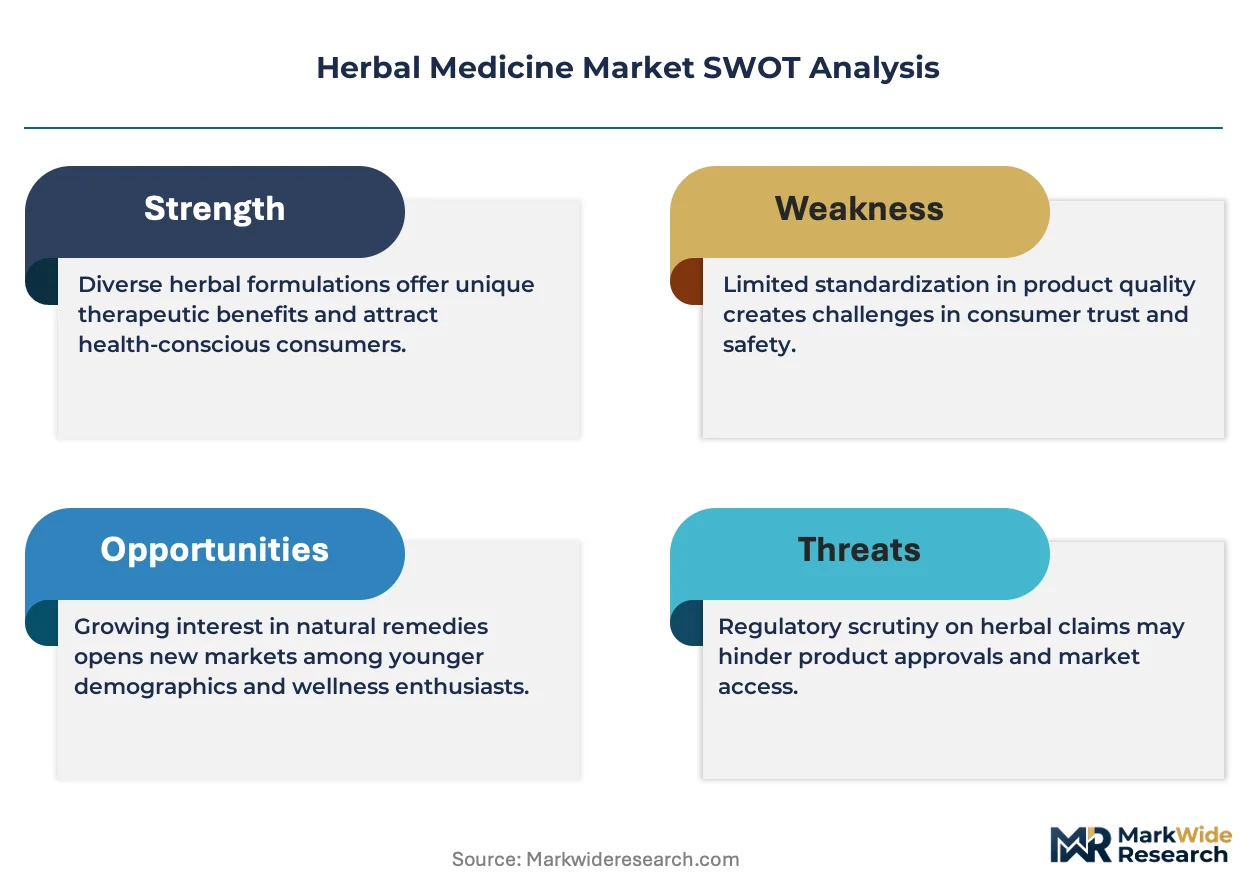
Preventive healthcare is pivoting toward botanical interventions as chronic disease management costs pressure conventional pharmaceutical budgets. Dabur Limited leverages its Ayurvedic heritage to anchor supply chains across South Asian and Middle Eastern distribution networks. Himalaya Global Holdings Ltd. competes through tablet and capsule standardization that appeals to pharmacy channels in regulated markets. Bionorica SE specializes in clinically validated phytopharmaceuticals, particularly for respiratory and urological indications, sustaining premium positioning in German and Austrian prescription segments.
Herbal medicine comprises plant-derived preparations containing bioactive compounds extracted through aqueous, alcoholic, or supercritical CO2 methods, standardized to marker compound concentrations for batch consistency. These formulations serve therapeutic, prophylactic, and wellness maintenance functions across digestive, respiratory, dermatological, and immunological applications. Herbal supplements occupy the largest volume position due to over-the-counter accessibility and direct-to-consumer channel growth, while phytopharmaceuticals capture concentrated margin pools where prescription status and clinical validation support reimbursement. Ayurvedic medicines represent the fastest-expanding category as India's PLI scheme for pharmaceutical manufacturing incentivizes export-oriented capacity and as diaspora populations in North America and Europe drive cross-border demand.
FDA dietary supplement regulations under DSHEA govern U.S. market entry without pre-market approval, creating lower barriers than pharmaceutical pathways but restricting disease claims. EMA's Committee on Herbal Medicinal Products enforces monograph-based registration across EU member states, while China's NMPA integrates traditional Chinese medicine materia medica into national pharmacopeia standards. India's CDSCO and AYUSH ministry jointly oversee Ayurvedic, Siddha, and Unani product licensing, with BIS quality standards increasingly shaping export competitiveness. Stakeholders must monitor evolving pharmacovigilance requirements and DNA barcoding mandates as authentication technologies reshape supply chain accountability and consumer trust frameworks.
Market Dynamics
DNA barcoding mandates are compressing authentication timelines across herbal supply chains, forcing processors to rebuild traceability infrastructure or exit contract manufacturing relationships with European pharmacy chains.
Growth Catalysts
- EU Traditional Herbal Medicines Directive:Streamlined monograph-based registration accelerates product entry across Germany, France, and Italy, consolidating pharmacy shelf access for validated phytopharmaceuticals.
- Preventive care pivot:Wellness centers in California and Bavaria expand herbal therapy portfolios as employer-sponsored health plans seek alternatives to chronic disease pharmaceutical management.
- India's PLI scheme:Export-oriented Ayurvedic manufacturing capacity attracts diaspora-driven demand from North American and Middle Eastern distribution networks.
Market Restraints
- Raw material volatility:Wild-harvested Rhodiola rosea and Withania somnifera root stocks face climate-driven yield compression in Himalayan and Altai sourcing regions.
- Extraction technology concentration:Supercritical CO2 equipment suppliers cluster in Germany and Switzerland, creating capex bottlenecks for mid-scale processors in emerging markets.
- DSHEA claim restrictions:FDA regulations block disease-specific marketing for dietary supplements, limiting pharmacy channel penetration against prescription phytopharmaceuticals.
Strategic Opportunities
- Saudi Arabia wellness tourism:MOHAP licensing frameworks for traditional medicine clinics create first-mover positioning for integrated Ayurvedic-TCM service providers.
- Hospital formulary integration:Oncology supportive care protocols in German university hospitals increasingly specify clinically validated herbal adjuvants.
- Blockchain-IoT convergence:Immutable batch records combined with real-time cultivation sensors enable premium pricing for traceable botanical provenance.
Industry Challenges
- Pharmacognosy expertise scarcity:Botanical identification and marker compound analysis skills concentrate in aging European and Japanese specialist cohorts.
- EMA quality dossier timelines:Well-established use documentation requirements extend registration cycles to 18-24 months for non-monograph botanicals.
- Legacy ERP integration:Seed-to-shelf traceability platforms require reconfiguration of inventory management systems at multi-brand Ayurvedic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Medicine Market |
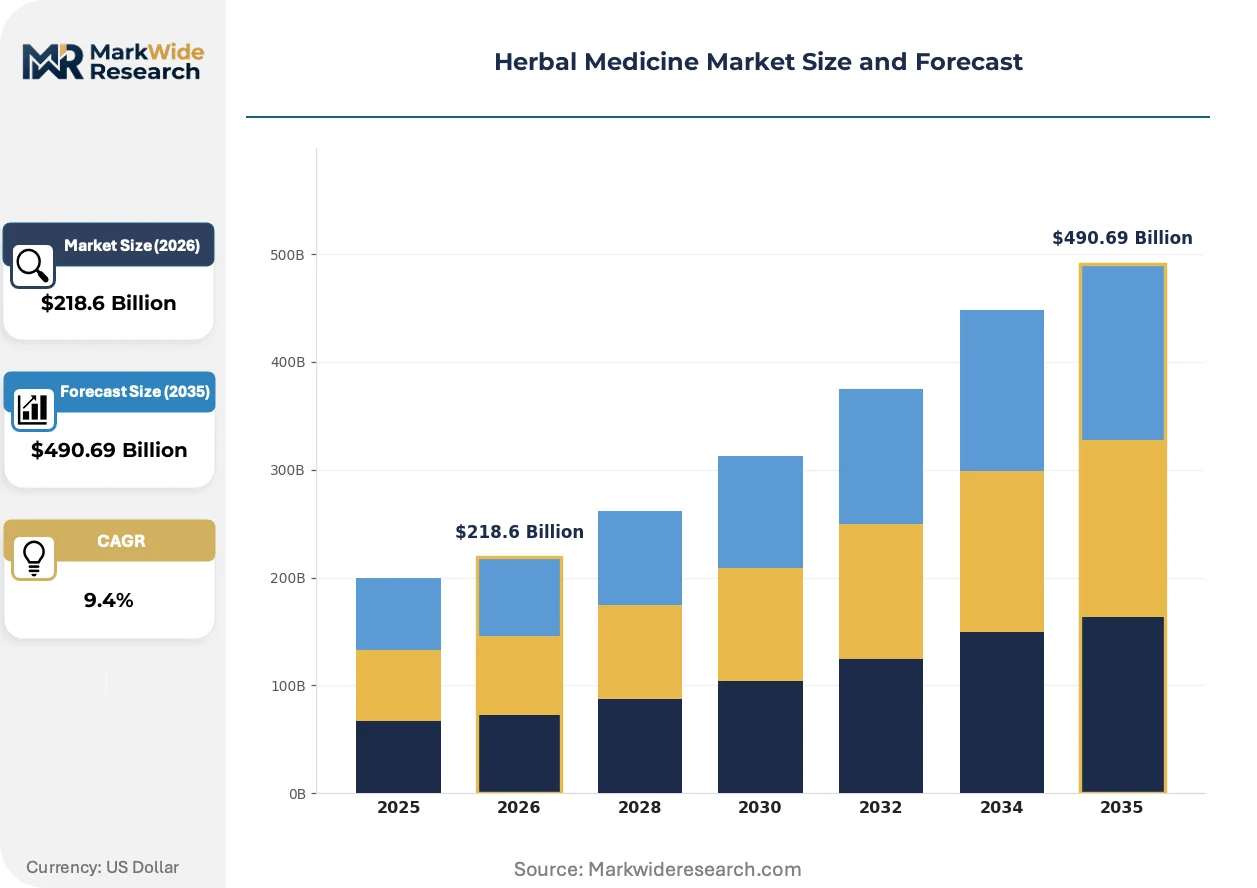
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $490.69 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Supplements, Phytopharmaceuticals, Traditional Remedies, Ayurvedic Medicines, Chinese Herbal Extracts Application: Digestive Disorders, Respiratory Conditions, Skin Treatments, Immune Support, Stress Relief End User: Health Clinics, Wellness Centers, Home Users, Herbalists, Alternative Medicine Practitioners Formulation: Capsules, Tablets, Powders, Teas, Topical Ointments |
| Companies Covered | Herbalife Nutrition, Weleda, Blackmores Limited, Patanjali Ayurved Limited, Bionorica SE, Dabur Limited, Tsumura, Nutraceutical Corporation, Himalaya Global Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Medicine Market Strategic Shifts & Innovations
Authentication technologies and extraction precision are compressing quality variance between artisanal and industrial herbal production, reshaping procurement criteria for institutional buyers.
Supercritical CO2 extraction is integrating with inline chromatographic monitoring to enable real-time marker compound standardization. German phytopharmaceutical manufacturers deploy these systems to meet EMA batch consistency requirements. The technology is integrating quality assurance directly into processing workflows, reducing post-production testing delays.
China's NMPA has embedded traditional Chinese medicine materia medica into national pharmacopeia standards with mandatory heavy metal and pesticide residue limits. Domestic manufacturers face facility upgrade costs to meet GMP-TCM certification. Export-oriented processors in Zhejiang and Yunnan provinces accelerate EU-GMP parallel compliance to maintain German and Dutch contract manufacturing relationships.
Direct-to-consumer subscription models displace pharmacy retail for standardized herbal supplements in US and UK metropolitan markets. Millennials and Gen Z cohorts prioritize convenience and educational content over pharmacist consultation. Subscription churn rates concentrate in sleep and stress categories where efficacy perception drives retention more than price.
Herbal Medicine Market Segmentation
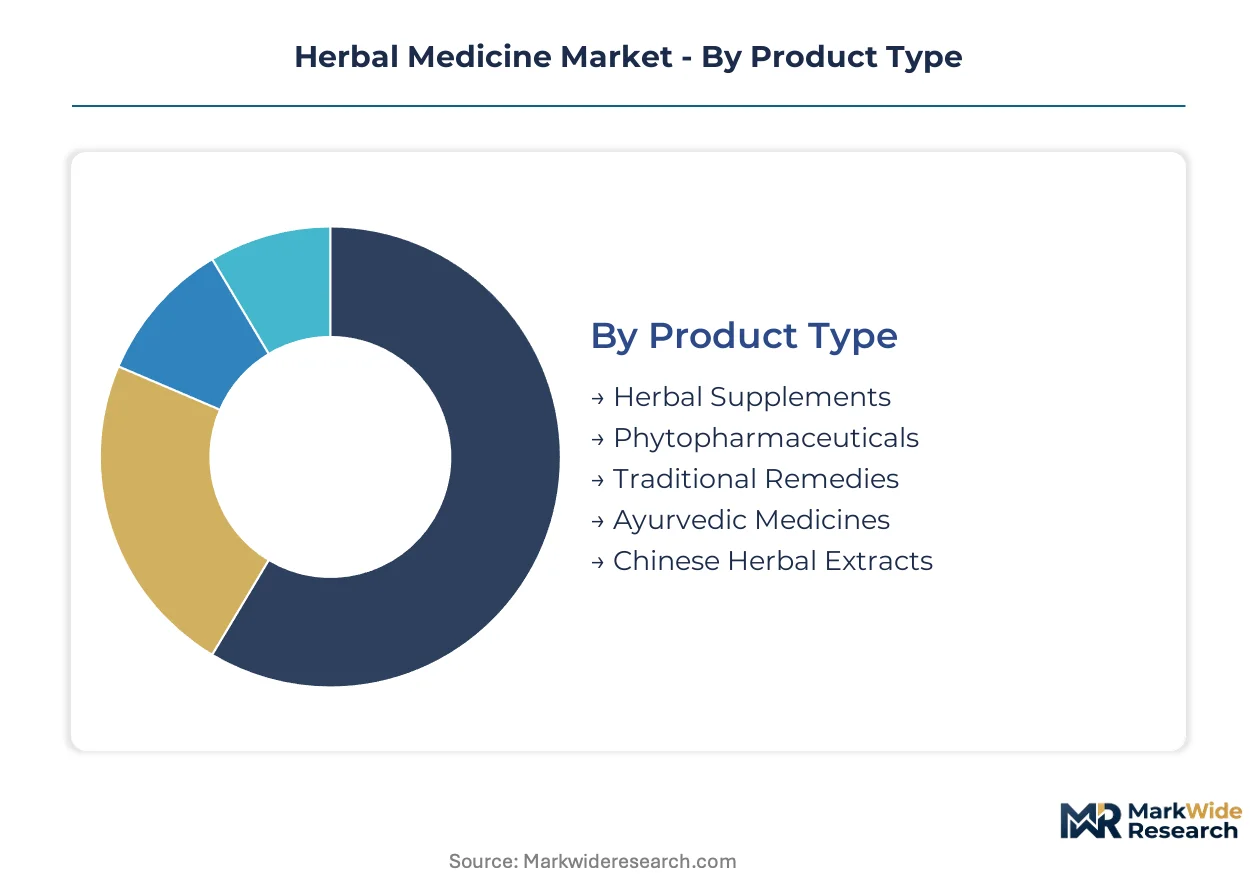
Segmentation in herbal medicine reflects divergent regulatory pathways and extraction sophistication levels. Product type determines reimbursement eligibility and manufacturing compliance burden. Application focus shapes clinical validation requirements and channel access.
Product Type:
Extraction technology and standardization protocols create tiered quality boundaries across product categories.
- Herbal Supplements:Aqueous and ethanolic extracts formulated to dietary supplement specifications with marker compound disclosure on labeling. Direct-to-consumer channels in California and New York metropolitan areas concentrate demand as subscription models displace pharmacy retail for standardized formulations.
- Phytopharmaceuticals:Clinically validated botanical preparations manufactured to pharmaceutical GMP standards with batch-specific certificate of analysis. German and Austrian prescription segments anchor demand where EMA monograph compliance enables reimbursement integration for respiratory and urological indications.
- Traditional Remedies:Whole-plant or crude preparations following ethnopharmacological preparation methods without standardized extraction.
- Ayurvedic Medicines:Dosha-specific formulations from classical texts processed through traditional decoction, fermentation, or calcination methods.
- Chinese Herbal Extracts:Concentrated preparations from materia medica entries with heavy metal and pesticide residue testing per NMPA pharmacopeia standards.
Mature deployment sits with Herbal Supplements. Newer deployment is concentrated in Phytopharmaceuticals.
Application:
Clinical evidence depth and endpoint measurability determine institutional procurement priority.
- Digestive Disorders:Demulcent and carminative preparations targeting functional dyspepsia and irritable bowel syndrome with enteric-coated delivery systems. German health clinics specify clinically validated Iberogast formulations for functional gastrointestinal complaints.
- Respiratory Conditions:Expectorant and bronchospasmolytic botanicals standardized to mucolytic active markers. Bavarian wellness centers integrate thyme and ivy leaf extracts into employer-sponsored preventive care protocols for seasonal respiratory maintenance.
- Skin Treatments:Topical anti-inflammatory and wound-healing preparations with percutaneous absorption optimization.
- Immune Support:Adaptogenic and immunomodulatory formulations for subclinical immune enhancement.
- Stress Relief:Anxiolytic botanicals targeting HPA axis modulation with cortisol biomarker correlation.
Volume concentration favors Digestive Disorders. Steepest expansion trajectory appears in Stress Relief.
End User:
Credential requirements and liability frameworks segment service delivery models.
- Health Clinics:Medical facilities integrating evidence-based botanical adjuvants into conventional treatment protocols with pharmacovigilance documentation.
- Wellness Centers:Preventive care facilities in California and Bavaria expanding herbal therapy portfolios under employer-sponsored health plans.
- Home Users:Self-directed consumers purchasing through direct-to-consumer subscription channels with educational content dependency.
- Herbalists:Practitioners with formal botanical medicine training prescribing custom compounded preparations.
- Alternative Medicine Practitioners:Acupuncturists, naturopaths, and Ayurvedic physicians with scope-of-practice variations by jurisdiction.
Procurement scale clusters with Health Clinics. Fastest channel growth concentrates in Wellness Centers.
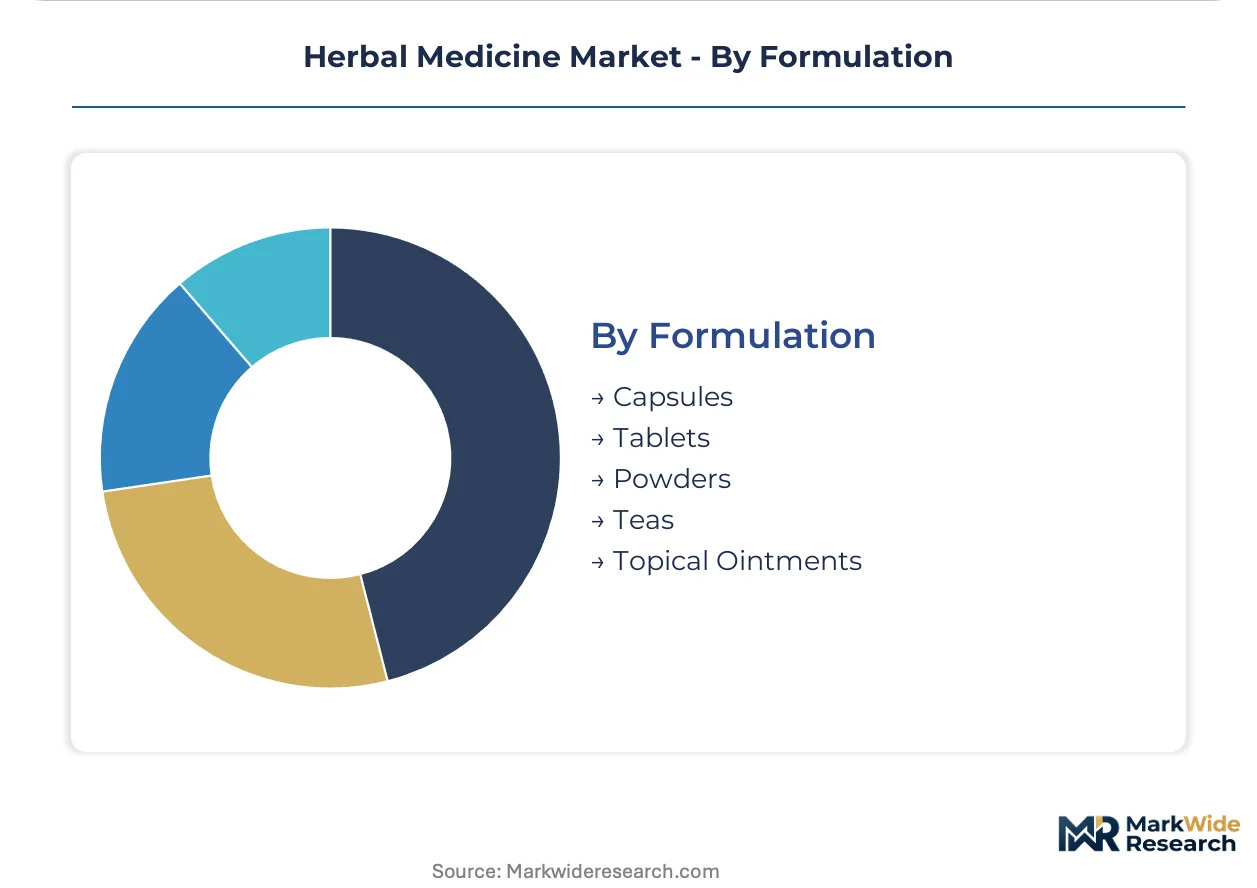
Formulation:
Stability engineering and bioavailability optimization drive dosage form selection.
- Capsules:Powdered extract or whole herb encapsulation with enteric coating for acid-labile compounds.
- Tablets:Compressed formulations with standardized disintegration profiles appealing to German and Dutch pharmacy channels.
- Powders:Bulk botanical material or extract for compounding and traditional preparation flexibility.
- Teas:Infusion or decoction preparations with immediate release kinetics and ritual consumption patterns.
- Topical Ointments:Lipophilic extract delivery through occlusive or semi-occlusive bases for dermatological application.
Manufacturing maturity centers on Tablets. Innovation investment flows toward Capsules with enhanced bioavailability coatings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's pharmaceutical special economic zones concentrate Ayurvedic extract processing capacity serving export markets. These tax-advantaged enclaves attract contract manufacturers seeking EU-GMP certification for European pharmacy distribution.
Germany
Phytotherapy reimbursement integration drives pharmacy demand for clinically validated botanicals. EMA monograph compliance enables prescription status for respiratory and urological indications. Bavarian wellness centers in Munich and Nuremberg expand employer-sponsored herbal therapy protocols.
India
Ayurvedic manufacturing scales under PLI scheme incentives targeting export-oriented capacity. CDSCO and AYUSH ministry joint licensing streamlines product registration for domestic and international markets. Gujarat and Karnataka clusters concentrate supercritical CO2 extraction infrastructure for European contract supply.
United States
Direct-to-consumer subscription models displace pharmacy retail in California and New York metropolitan markets. FDA DSHEA regulations block disease claims but enable rapid dietary supplement market entry. Los Angeles and San Francisco wellness centers integrate herbal protocols into employer preventive care benefits.
China
Traditional Chinese medicine materia medica standardization accelerates under NMPA pharmacopeia integration. Heavy metal and pesticide residue limits force facility upgrades among Zhejiang and Yunnan processors. Export-oriented manufacturers pursue EU-GMP parallel certification to maintain German and Dutch contract relationships.
Saudi Arabia
Wellness tourism investments under Vision 2030 create licensing demand for traditional medicine clinics. MOHAP frameworks enable integrated Ayurvedic-TCM service provider positioning. Riyadh and Jeddah medical cities attract first-mover operators establishing preventive care botanical protocols.
Herbal Medicine Market Key Industry Players
Top-tier vendors anchor premium phytopharmaceutical tiers, while mid-scale Ayurvedic processors compete on export capacity. Market structure fragments across standardized extract suppliers, classical preparation manufacturers, and clinically validated drug developers. Three archetypes dominate: heritage Ayurvedic houses with integrated supply chains, German phytopharmaceutical specialists with EMA monograph portfolios, and direct-to-consumer supplement brands with subscription distribution. Competitive moves concentrate on backward integration into cultivation networks and technology licensing for extraction standardization.
Within the heritage Ayurvedic tier, Dabur Limited and Patanjali Ayurved Limited occupy positions shaped by subcontinental distribution density and diaspora market access. Among clinically validated specialists, Bionorica SE exemplifies the German prescription-phytopharmaceutical archetype with EMA-aligned registration strategies. Himalaya Global Holdings Ltd. represents the tablet-standardization vector appealing to regulated pharmacy channels across multiple geographies.
| Leading Market Players |
|---|
| Herbalife Nutrition |
| Weleda |
| Blackmores Limited |
| Patanjali Ayurved Limited |
| Bionorica SE |
| Dabur Limited |
| Tsumura |
| Nutraceutical Corporation |
| Himalaya Global Holdings Ltd. |
| Others |
Cost & Logistics Intelligence
Backward integration into Himalayan and Altai cultivation networks anchors supply security for German phytopharmaceutical manufacturers while simultaneously underwriting premium pricing power in EMA-monograph-compliant prescription segments. This upstream control over wild-harvested Rhodiola rosea and Withania somnifera stocks insulates validated botanical processors from raw material volatility that compresses margins for spot-market-dependent competitors.
Pricing Analysis
Short lead-time premiums command substantial markups in European pharmacy channels where EMA registration timelines stretch 18-24 months for non-monograph botanicals. Three-tier pricing structure across premium, standard, and economy levels separates clinically validated phytopharmaceuticals with batch-specific certificates of analysis from dietary supplement specifications and crude traditional preparations. Pricing pressure stems from supercritical CO2 equipment concentration in Germany and Switzerland that elevates capex barriers for mid-scale processors. Contract manufacturing buyers in regulated markets exhibit lowest price sensitivity, while direct-to-consumer subscription segments face churn-driven discounting.
Supply Chain Analysis
Dual-sourcing requirements from European pharmacy chains mandate multi-supplier qualification for wild-harvested root stocks across India, China, and Russia. Supply chains draw from aqueous and ethanolic extraction infrastructure in Gujarat's special economic zones, supercritical CO2 processing clusters in southern Germany, and traditional decoction facilities in Kerala. Single-source vulnerability concentrates in Altai region Rhodiola harvesting where climate-driven yield compression threatens contract fulfillment. Distribution runs through pharmacy wholesale networks in Germany and Austria, direct-to-consumer platforms in California and New York, and wellness center procurement in Bavaria and Riyadh.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as players pursue captive cultivation networks to secure authenticated raw material streams against DNA barcoding mandates and climate volatility.
For Market Incumbents: Anticipate margin compression from India's PLI-scheme-subsidized Ayurvedic exporters by deepening backward integration into certified organic cultivation in Madhya Pradesh and Rajasthan. Lock in EMA monograph expansions for respiratory and urological indications before quality dossier timelines extend further. Channel control through exclusive pharmacy distribution agreements in Germany and Austria remains the priority defensive lever against subscription-model disintermediation. For New Entrants and Emerging Players: Capture white-space positioning in Saudi Arabia's wellness tourism corridor where MOHAP licensing frameworks for traditional medicine clinics remain underdeveloped. Target employer-sponsored preventive care protocols in Bavarian and Californian wellness centers where herbal therapy portfolio expansion outpaces qualified service provider supply. A direct-to-consumer educational content strategy anchored to cortisol biomarker correlation for stress relief formulations offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by German phytopharmaceutical specialists seeking EMA-aligned registration portfolios or heritage Ayurvedic houses pursuing diaspora market access. Long-term viability hinges on traceability technology integration rather than classical preparation heritage alone. The signal to watch is blockchain-IoT convergence adoption rates among institutional buyers as premium pricing enabler for provenance-verified botanicals.| Strategic Initiative | Industry Significance |
|---|---|
| DNA Barcoding Infrastructure Deployment | EMA authentication mandates compress supplier qualification timelines for European pharmacy contracts. |
| Supercritical CO2 Capacity Expansion | Inline chromatographic monitoring integration enables real-time marker compound standardization for batch consistency. |
| EU-GMP Parallel Certification | Zhejiang and Yunnan processors secure German and Dutch contract manufacturing relationships against NMPA pharmacopeia alignment. |
| Subscription Model Platform Launch | Millennial and Gen Z cohorts in US and UK metropolitan markets prioritize convenience over pharmacist consultation. |
| Blockhain-IoT Traceability Integration | Immutable batch records combined with cultivation sensors enable premium pricing for authenticated provenance claims. |
Research Approach
Multi-period observation of EMA registration timelines, PLI scheme capacity utilization, and DNA barcoding mandate implementation anchored the trend analysis, supplemented by interviews with phytopharmaceutical regulatory affairs leads, Ayurvedic manufacturing plant managers, German pharmacy procurement directors, wellness center protocol designers, and CDSCO licensing officers. Secondary validation incorporated EMA herbal monograph databases, AYUSH ministry export statistics, FDA DSHEA enforcement actions, and NMPA pharmacopeia revision records. Bottom-up extraction capacity modeling triangulated against top-down preventive care expenditure projections.
Input-output matrices mapped product type, application focus, and end-user channel dimensions across the analysis window, with CAGRs derived from segmented growth rate reconciliation against aggregate market boundary conditions. Dosha-specific formulation complexity, marker compound standardization tiers, and reimbursement integration depth served as herbal medicine-specific forecast modifiers alongside regulatory pathway velocity assumptions.
The model holds under sustained EMA monograph expansion and stable PLI scheme continuity; deviation in wild-harvested yield compression severity or pharmacognosy expertise attrition rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Pet Allergy Immune Supplements Market
Dietary Supplements
Pediatric Supplements Market
Dietary Supplements
Global Oral Electrolyte Solutions Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Vitamin D Deficiency Treatment Market
Dietary Supplements
Non-Hormonal Steroid Modulators Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Sleep Aid Supplements Market
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Cold Remedies Market