
 Global Vitamin D Therapy Market | 2026-2036
Global Vitamin D Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vitamin D Therapy Market Foresight
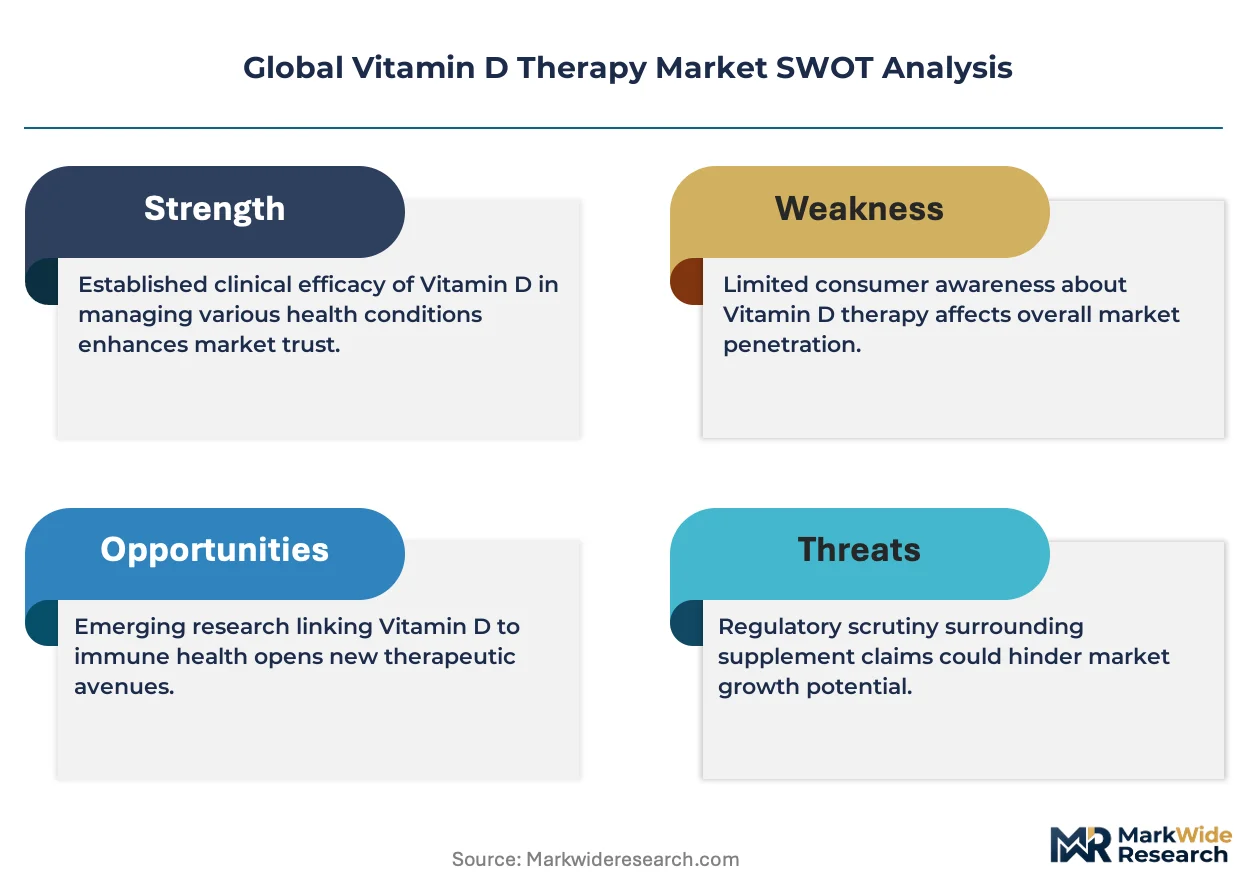
Multi-source API procurement is pivoting toward captive manufacturing among top vitamin D therapy suppliers. DSM-Firmenich leverages backward integration into sheep wool lanolin and algae-derived D3 precursors to secure raw material continuity. Abbott Laboratories anchors its position through hospital formulary contracts and point-of-care diagnostic bundling with supplementation protocols. Pfizer Inc. competes primarily in the injectable calcitriol segment, where cold-chain logistics and oncology-nephrology co-prescribing create specialized entry barriers.
Vitamin D therapy encompasses the clinical administration of secosteroid compounds—primarily cholecalciferol, ergocalciferol, and bioactivated calcitriol—to correct deficiency states and manage metabolic bone disease. Manufacturing relies on ultraviolet B irradiation of 7-dehydrocholesterol or ergosterol precursors, followed by molecular distillation to achieve pharmaceutical-grade purity exceeding 99.5%. Oral tablets dominate volume consumption due to decades of established reimbursement pathways and patient familiarity, though calcifediol capsules are gaining share in malabsorption populations where hepatic 25-hydroxylation is impaired. Injectable solutions command premium positioning in nephrology and critical care settings where rapid correction of hypocalcemia is required.
FDA cGMP enforcement and EMA's revised MDR requirements for active pharmaceutical ingredients are elevating documentation burdens for imported vitamin D raw materials. India's CDSCO has tightened stability-testing protocols for fixed-dose combinations containing vitamin D and calcium salts, affecting export eligibility for domestic manufacturers. WHO prequalification standards for essential medicines are becoming a de facto filter for tender participation in low-income country procurement. Stakeholders must monitor evolving pharmacovigilance signal detection around hypercalcemia risk in combination products, as regulatory divergence between major jurisdictions could fragment formulation strategies.
Market Dynamics
Backward integration into sheep wool lanolin and algae-derived precursors is compressing API supply chains, forcing formulation manufacturers to secure captive raw material streams or face margin erosion from spot market volatility.
Growth Catalysts
- Prophylactic hospital protocols:Post-surgical recovery units in Germany and the United States now mandate preoperative vitamin D screening, embedding supplementation into standard perioperative care pathways.
- EMA MDR alignment:The European Medicines Agency's revised Medical Device Regulation creates harmonized quality benchmarks that accelerate cross-border formulary approvals for combination therapies.
- Malabsorption-targeted calcifediol:Hepatic impairment populations drive demand for 25-hydroxylated formulations that bypass first-pass metabolism, opening reimbursement carve-outs in nephrology and bariatric surgery.
Market Restraints
- Lanolin supply concentration:Over 70% of pharmaceutical-grade 7-dehydrocholesterol originates from Australian and New Zealand sheep wool processing, exposing manufacturers to agricultural commodity cycles.
- FDA cGMP documentation burdens:The agency's intensified enforcement of current Good Manufacturing Practice for imported APIs extends qualification timelines for Indian and Chinese raw material suppliers.
- Calcium-vitamin D substitution:Generic fixed-dose combinations commoditize at retail pharmacy tiers, compressing branded oral tablet pricing power.
Strategic Opportunities
- Brazilian statuary expansion:ANVISA's updated pharmaceutical equivalence pathways for bioactivated vitamin D analogs reduce registration barriers for calcitriol injectables in Latin America's largest market.
- Point-of-care diagnostic bundling:Hospital procurement committees increasingly source 25(OH)D testing platforms alongside therapeutic protocols, creating integrated vendor relationships.
- Algae-derived D3 scale-up:Photosynthetic fermentation of ergosterol precursors offers vegan-certified alternatives to animal-sourced cholecalciferol for European nutraceutical channels.
Industry Challenges
- Pharmacovigilance signal management:Hypercalcemia risk detection in combination products demands enhanced post-market surveillance infrastructure across divergent FDA-EMA reporting standards.
- Cold-chain injectable logistics:Calcitriol ampoules require 2-8°C distribution integrity through oncology-nephrology co-prescribing networks, elevating last-mile complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vitamin D Therapy Market |
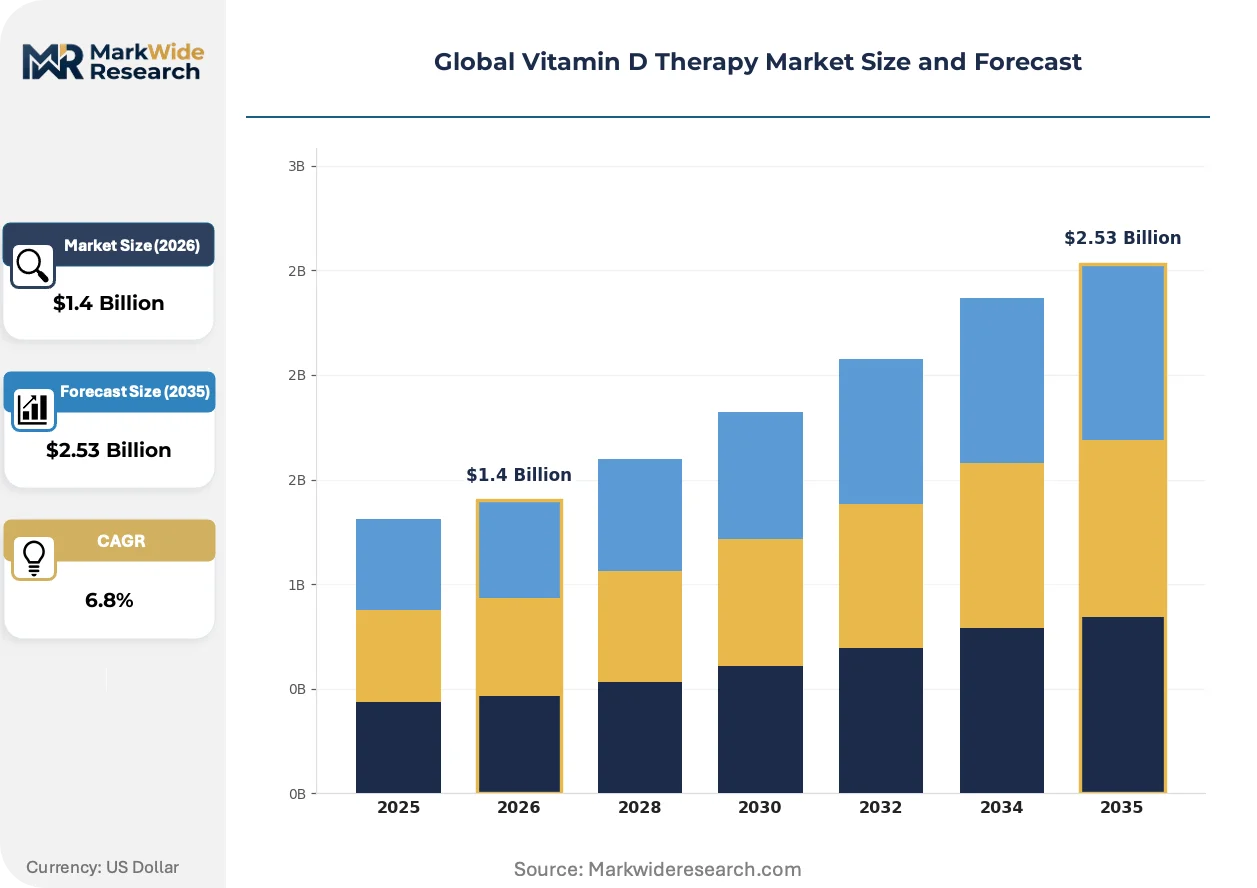
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cholecalciferol, Ergocalciferol, Calcifediol, Calcitriol Application: Osteoporosis Management, Rickets Treatment, Immune Support, Muscle Weakness Therapy End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Home Healthcare Providers Delivery Mode: Oral Tablets, Injectable Solutions, Capsules, Topical Preparations |
| Companies Covered | Merck & Co., Inc., DSM-Firmenich, Abbott Laboratories, Cadila Healthcare Ltd., Alkem Laboratories Ltd., Pfizer Inc., Sanofi, Ortho Molecular Products, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vitamin D Therapy Market Shifts & Advancements
Bioprocess engineering and regulatory harmonization are compressing traditional manufacturing timelines while diagnostic-therapeutic integration reconfigures procurement relationships between hospitals and suppliers.
Microencapsulation technology using lipid-based spray-drying matrices is modularizing oral vitamin D stability profiles, enabling ambient-temperature distribution in tropical climates. Nigerian and Indonesian health ministries now specify these formulations for national immunization program adjuvants. The structural consequence is displacement of gelatin-softgel formats in institutional procurement.
CDSCO's tightened stability-testing protocols for vitamin D-calcium fixed-dose combinations now mandate six-zone climatic zone data for export eligibility. Indian contract manufacturers face capital expenditure requirements for upgraded stability chambers. The injectable calcitriol segment absorbs disproportionate compliance costs due to its narrower therapeutic index.
Hospital formulary committees increasingly unbundle diagnostic testing from therapeutic procurement, reversing decades of bundled rebate structures. Nephrology departments in France and Japan now separately negotiate 25(OH)D immunoassay contracts from calcifediol supply agreements. This disintermediation exposes standalone pharmaceutical suppliers to direct price benchmarking against diagnostic platform vendors.
Global Vitamin D Therapy Market Segmentation
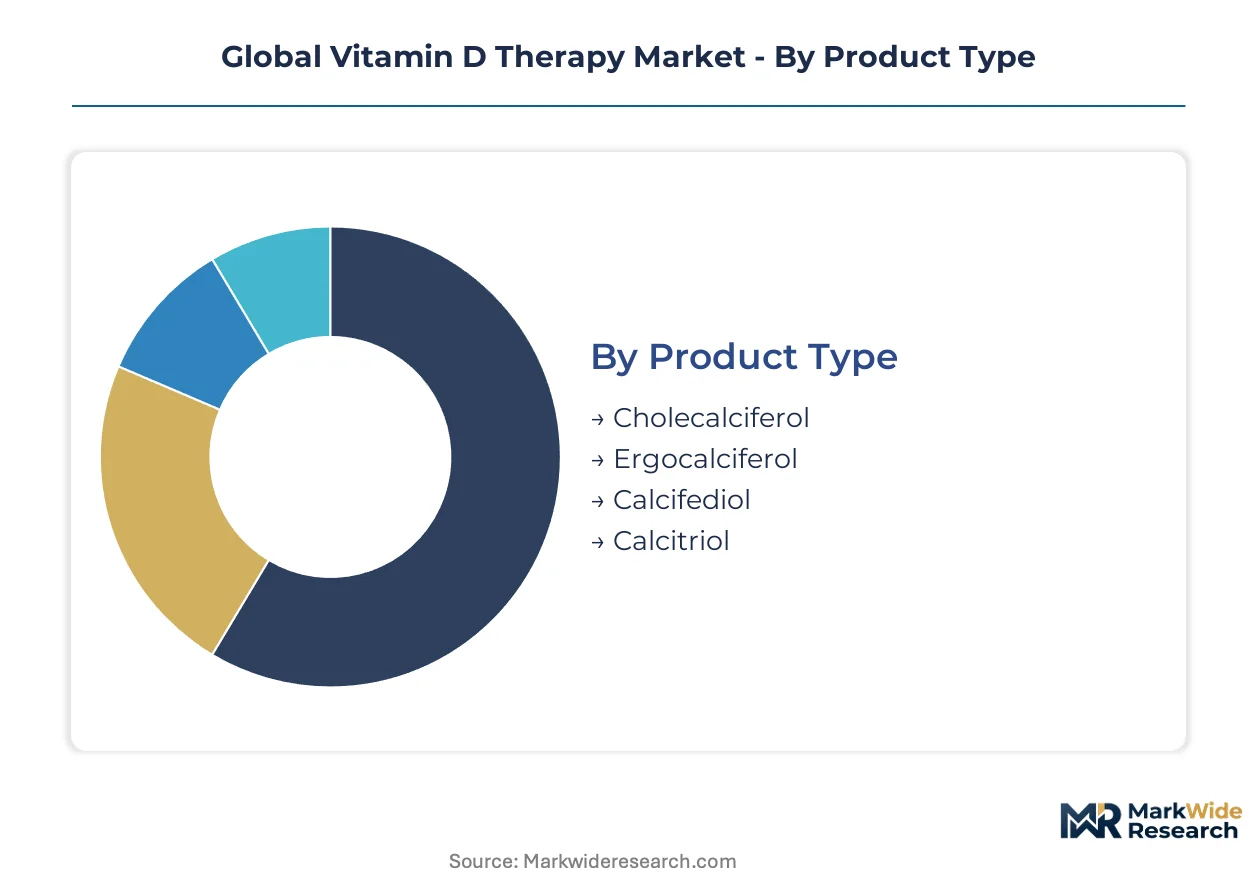
Vitamin D therapy segmentation reveals divergent capital requirements across manufacturing modalities. API synthesis demands heavy fixed-asset deployment, while formulation and distribution layers operate with greater variable cost flexibility.
Product Type:
Capital intensity peaks at the bioactivation stage, where synthetic chemistry infrastructure separates commodity producers from specialty manufacturers.
- Cholecalciferol:Ultraviolet B irradiation of 7-dehydrocholesterol derived from sheep wool lanolin remains the dominant production pathway. German and Australian manufacturers absorb the bulk of installed capacity due to backward integration into wool processing cooperatives.
- Calcitriol:Synthetic hydroxylation of calcifediol precursors requires multi-step pharmaceutical-grade reactors with narrow temperature tolerances. Oncology-nephrology co-prescribing in France and Japan drives demand for this bioactivated form where rapid hypocalcemia correction is clinically mandated.
- Ergocalciferol:Fungal ergosterol irradiation serves vegan-certified nutraceutical channels, particularly in European markets with strict animal-source labeling requirements.
- Calcifediol:25-hydroxylated intermediate formulations bypass hepatic metabolism, finding reimbursement carve-outs in bariatric surgery and malabsorption populations.
Cholecalciferol absorbs the bulk of installed capacity; calcitriol is expanding most quickly.
Application:
Reimbursement pathway maturity determines margin structure, with established therapeutic indications commanding predictable pricing versus emerging prophylactic uses.
- Osteoporosis Management:Longitudinal bone mineral density monitoring protocols embed vitamin D supplementation into standard care pathways. German statutory health insurance reimbursement for deficiency screening has broadened access to therapeutic intervention.
- Rickets Treatment:Pediatric endocrinology units in Nigeria and Indonesia specify microencapsulated formulations for national immunization program adjuvants, displacing traditional gelatin-softgel formats in institutional procurement.
- Immune Support:Post-surgical recovery units across North American hospitals now mandate preoperative vitamin D screening, embedding supplementation into perioperative care.
- Muscle Weakness Therapy:Geriatric rehabilitation facilities utilize serum 25(OH)D testing platforms alongside therapeutic protocols, creating integrated diagnostic-therapeutic vendor relationships.
Osteoporosis management commands the deepest reimbursement infrastructure; immune support applications are climbing the fastest.
End User:
Procurement sophistication varies sharply, with consolidated hospital systems leveraging formulary contracts against fragmented home healthcare channels.
- Hospitals:Formulary committees unbundle diagnostic testing from therapeutic procurement, separately negotiating 25(OH)D immunoassay contracts from calcifediol supply agreements.
- Specialty Clinics:Nephrology and endocrinology practices in Japan and France maintain direct purchasing relationships with calcitriol injectable suppliers.
- Diagnostic Laboratories:Point-of-care testing platforms increasingly source alongside supplementation protocols, reversing decades of bundled rebate structures.
- Home Healthcare Providers:Retail pharmacy tiers commoditize generic fixed-dose combinations, compressing branded oral tablet pricing power.
Hospitals concentrate the highest procurement volumes; specialty clinics are gaining share fastest.
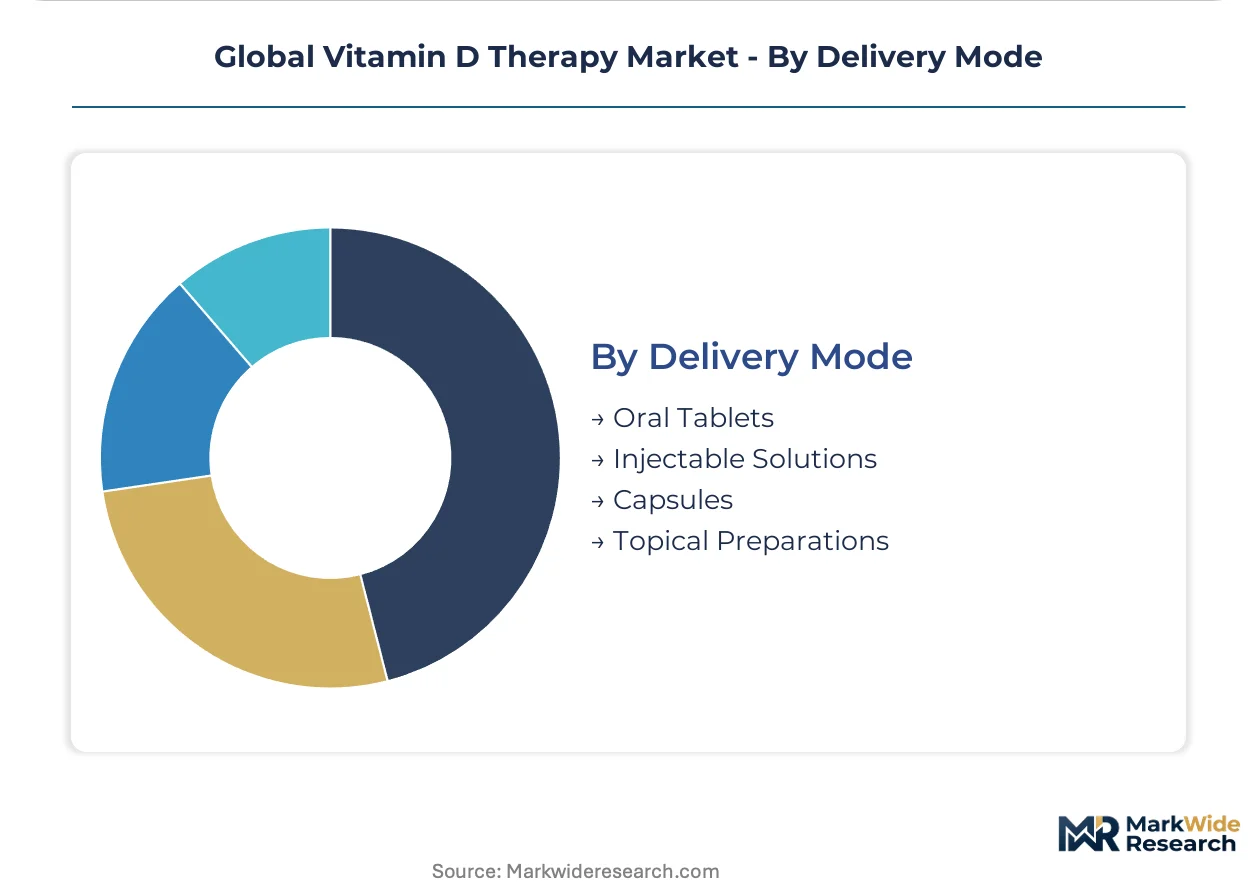
Delivery Mode:
Cold-chain infrastructure requirements create tiered distribution economics, with ambient-stable formats reaching broader geographic penetration.
- Oral Tablets:Decades of established reimbursement pathways and patient familiarity sustain volume dominance, though generic substitution pressures margins.
- Injectable Solutions:Calcitriol ampoules require 2-8°C distribution integrity through oncology-nephrology networks, elevating last-mile complexity and premium positioning.
- Capsules:Lipid-based spray-dried matrices enable ambient-temperature distribution in tropical climates, specified by Nigerian and Indonesian health ministries.
- Topical Preparations:Transdermal delivery remains niche, primarily utilized in dermatology settings where gastrointestinal absorption is compromised.
Oral tablets retain the widest installed base; capsules are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian and New Zealand sheep wool processing cooperatives supply over 70 percent of pharmaceutical-grade 7-dehydrocholesterol precursors, anchoring raw material continuity for vitamin D manufacturers worldwide. This agricultural concentration shapes manufacturing investment patterns across downstream formulation hubs.
United States
Post-surgical recovery units mandate preoperative vitamin D screening, embedding supplementation into standard perioperative care pathways. FDA intensified cGMP enforcement for imported APIs, extending qualification timelines for raw material suppliers. Hospital formulary committees in the Northeast and Midwest unbundle diagnostic testing from therapeutic procurement, reversing decades of bundled rebate structures.
Germany
Statutory health insurance reimbursement for deficiency screening has broadened patient access to therapeutic intervention. EMA's revised Medical Device Regulation creates harmonized quality benchmarks that accelerate cross-border formulary approvals. Bavarian and North Rhine-Westphalian manufacturing clusters absorb the bulk of European installed capacity through backward integration into wool processing cooperatives.
Japan
Nephrology departments separately negotiate 25(OH)D immunoassay contracts from calcifediol supply agreements, exposing standalone pharmaceutical suppliers to direct price benchmarking. PMDA maintains stringent stability requirements for bioactivated vitamin D analogs. The Kanto and Kansai regions concentrate specialty clinic purchasing relationships with injectable calcitriol suppliers.
India
CDSCO tightened stability-testing protocols for vitamin D-calcium fixed-dose combinations, mandating six-zone climatic zone data for export eligibility. Domestic contract manufacturers face capital expenditure requirements for upgraded stability chambers. Gujarat and Maharashtra host the primary export-oriented formulation facilities serving African and Southeast Asian tender markets.
Brazil
ANVISA's updated pharmaceutical equivalence pathways for bioactivated vitamin D analogs reduce registration barriers for calcitriol injectables. The São Paulo and Rio de Janeiro metropolitan areas concentrate hospital procurement volume for oncology-nephrology co-prescribing networks. Brazilian health ministry tenders increasingly specify WHO prequalification standards as a de facto filter for essential medicines procurement.
Global Vitamin D Therapy Market Competitive Landscape
Global majors compete with regional champions across manufacturing modality and distribution reach, creating a tiered structure where scale-driven API producers coexist with formulation specialists and diagnostic-therapeutic integrators. The market fragments across three strategic archetypes: backward-integrated precursors suppliers, hospital formulary contract holders, and injectable calcitriol specialists serving narrow therapeutic index segments. Dominant competitive moves include captive raw material stream acquisition and point-of-care diagnostic bundling with supplementation protocols.
Among the backward-integrated tier, DSM-Firmenich exemplifies upstream control over sheep wool lanolin and algae-derived D3 precursors. Abbott Laboratories anchors the hospital formulary contract archetype through diagnostic-therapeutic integration. Pfizer Inc. occupies a position within the injectable calcitriol specialist segment where cold-chain logistics create specialized entry barriers.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| DSM-Firmenich |
| Abbott Laboratories |
| Cadila Healthcare Ltd. |
| Alkem Laboratories Ltd. |
| Pfizer Inc. |
| Sanofi |
| Ortho Molecular Products |
| GlaxoSmithKline |
| Others |
Supply & Pricing Matrix
Family-owned Australian and New Zealand wool processing cooperatives anchor raw material ownership patterns, compressing spot market liquidity for pharmaceutical-grade 7-dehydrocholesterol while sustaining premium pricing power through captive supply arrangements.
Pricing Analysis
Warranty and stability-guarantee bundling separates branded calcifediol formulations from unbundled generic oral tablets, with three-tier pricing structure across premium, standard, and economy levels determined by certification grade and cold-chain service inclusion. Price differentiation hinges on FDA cGMP documentation completeness and WHO prequalification status. Pricing pressure stems from Indian CDSCO-mandated six-zone stability testing that elevates compliance costs for fixed-dose combinations. Retail pharmacy tiers exhibit highest price sensitivity; oncology-nephrology co-prescribing networks show lowest sensitivity due to therapeutic index constraints.
Supply Chain Analysis
Regional distribution centers in Bavaria, North Rhine-Westphalia, and Gujarat operate hub-and-spoke patterns for temperature-sensitive calcitriol ampoules. Geographic supply concentrates in Australia, New Zealand, and Germany. Raw material flows draw from sheep wool lanolin, algae-derived ergosterol precursors, and synthetic 7-dehydrocholesterol. Single-source vulnerability from Australian wool cooperative concentration elevates agricultural commodity cycle exposure. Distribution runs through hospital formulary direct contracts and specialty clinic purchasing relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lanolin precursor scarcity props pricing discipline, as Australian wool cooperative capacity constraints limit raw material expansion regardless of downstream formulation demand.
For Market Incumbents: Acquire algae-derived D3 fermentation assets to diversify precursor sourcing beyond wool-dependent supply. Secure captive stability-testing infrastructure to preempt CDSCO export eligibility disruptions. Defensive consolidation should target diagnostic platform vendors before hospital procurement committees complete unbundling of testing from therapeutic supply agreements.
For New Entrants and Emerging Players: Launch via Brazilian ANVISA pharmaceutical equivalence pathways for calcitriol injectables, where reduced registration barriers create accessible entry. White-space targets include vegan-certified ergocalciferol for European nutraceutical channels and microencapsulated formats for Nigerian and Indonesian national immunization programs. Direct-to-specialty-clinic distribution bypasses consolidated hospital formulary gatekeeping.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Indian contract manufacturers with upgraded six-zone stability chambers in Gujarat and Maharashtra. Long-term viability over the mid-decade window rests on WHO prequalification filter compliance for low-income country tender participation. Watch FDA-EMA pharmacovigilance divergence on hypercalcemia signal detection as inflection indicator for formulation strategy fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Algae-Derived Precursors | DSM-Firmenich's photosynthetic fermentation secures vegan-certified supply continuity for European nutraceutical channels. |
| Point-of-Care Diagnostic Bundling | Abbott Laboratories anchors hospital formulary contracts through integrated 25(OH)D testing platform partnerships. |
| Injectable Calcitriol Cold-Chain Infrastructure | Pfizer Inc.'s oncology-nephrology network specialization creates distribution barriers against commodity entrants. |
| ANVISA Pharmaceutical Equivalence Registration | Reduced calcitriol injectable barriers unlock Brazilian hospital procurement volume in São Paulo metropolitan clusters. |
| Microencapsulation Spray-Drying Scale-Up | Ambient-stable lipid matrices displace gelatin-softgel formats in Nigerian and Indonesian institutional tenders. |
Research Methodology
Multi-period observation of hospital formulary contract structures, CDSCO export eligibility patterns, and EMA MDR alignment timelines anchored the trend analysis, supplemented by interviews with pharmaceutical manufacturing executives, regulatory affairs leads, hospital procurement managers, and nephrology formulary directors. Secondary validation drew from FDA cGMP enforcement records, EMA Medical Device Regulation submissions, WHO prequalification listings, and Australian wool cooperative production disclosures. Bottom-up capacity modeling triangulated against top-down therapeutic demand projections across patient population segments.
Segment-weighting applied product type, application indication, end-user procurement sophistication, and delivery mode cold-chain requirements across the projection horizon. CAGRs derived from installed capacity expansion rates, reimbursement pathway maturation curves, and diagnostic-therapeutic integration penetration. Industry-specific inputs incorporated lanolin precursor supply elasticity and stability-testing capital expenditure cycles.
Regulatory divergence between FDA and EMA pharmacovigilance standards, Australian agricultural commodity price volatility, and hospital procurement unbundling velocity are the dominant revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Medicinal Mushroom Powder Market
Dietary Supplements
Womens Health and Beauty Supplements Market
Dietary Supplements
Detox Products Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Hair Supplements Market
Dietary Supplements
Eye Care Supplements Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Mediterranean Mood and Stress Support Complexes Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Folic Acid Tablets Market
Dietary Supplements
Glucosamine Salt Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Immune Health Supplements Market