
 Androgens and Anabolic Steroids Market | 2026-2036
Androgens and Anabolic Steroids Market Size, Share, and Industry Trends Forecast 2026-2036
Androgens and Anabolic Steroids Market Outlook
FDA scheduling under the Controlled Substances Act is rebalancing the cost-of-entry calculus for new market participants, forcing manufacturers to absorb compliance overhead that smaller entrants cannot shoulder. Teva Pharmaceutical Industries leverages its vertically integrated generic manufacturing network to sustain cost advantages across testosterone injectables. Bayer AG anchors its position through specialty urology and endocrinology channel relationships. Pfizer Inc. differentiates via hospital and institutional procurement contracts that limit formulary access for competitors.
Androgens and anabolic steroids comprise synthetic derivatives of testosterone and related hormones, formulated as C19-steroid compounds with anabolic-androgenic ratios calibrated for therapeutic or performance applications; these agents function by binding androgen receptors to stimulate protein synthesis and erythropoiesis. Injection delivery dominates clinical settings due to pharmacokinetic reliability and dosing precision, while topical and transdermal formats expand in outpatient men's health protocols where patient convenience drives adherence. Testosterone products occupy the largest revenue pool given their established reimbursement and broad hypogonadism labeling, whereas nandrolone and stanozolol concentrate in narrower hematology and cachexia indications with tighter prescriber bases.
The US Drug Enforcement Administration, FDA, and state-level pharmacy boards collectively shape market access through controlled-substance scheduling, manufacturing quota allocations, and prescription monitoring program mandates that constrain diversion risk. EMA and national European regulators enforce pharmacovigilance requirements and manufacturing standards through the centralized authorization procedure and good manufacturing practice inspections. Stakeholders must monitor evolving scheduling proposals and import restriction enforcement, as regulatory tightening in one jurisdiction typically triggers parallel compliance investments across multinational supply chains.
Market Dynamics
FDA scheduling under the Controlled Substances Act is compressing manufacturing quota allocations for testosterone derivatives, forcing API suppliers to consolidate batch production around fewer GMP-certified facilities. This regulatory density is reshaping competitive entry economics across the value chain.
Growth Catalysts
- TRT clinic network expansion:Specialty men's health clinics in the United States are scaling patient intake protocols for hypogonadism diagnosis, creating pull-through demand for injectable testosterone formulations with established reimbursement pathways.
- REACH compliance harmonization:European manufacturers achieving EMA centralized authorization are leveraging mutual recognition procedures to accelerate national market access across Germany, France, and Italy.
- Long-acting ester innovation:Sustained-release testosterone undecanoate formulations are reducing injection frequency from weekly to quarterly intervals, improving adherence metrics in outpatient protocols.
Market Restraints
- API supply concentration:Bulk testosterone raw material production clusters in Chinese pharmaceutical manufacturing zones, exposing formulators to import restriction volatility and customs inspection delays.
- DEA quota rigidity:Annual manufacturing quotas for Schedule III controlled substances cap production volumes regardless of demand signals, creating allocation bottlenecks during supply disruptions.
- Transdermal substitution pressure:Non-steroidal selective androgen receptor modulators in early-stage development threaten to displace traditional anabolic steroids in muscle-wasting indications.
Strategic Opportunities
- Subcutaneous micro-needle delivery:Needle-phobic patient segments are driving demand for alternative administration routes that reduce injection anxiety and enable self-administration training.
- Compounding pharmacy carve-outs:FDA 503B outsourcing facility regulations create a compliance pathway for customized testosterone formulations serving niche dosing requirements outside standard SKUs.
- Aging male demographics in Japan:METI-supported longevity initiatives are expanding endocrinology screening coverage, opening reimbursement negotiations for testosterone replacement in sarcopenia protocols.
Industry Challenges
- Controlled-substance logistics certification:Cold chain handlers must maintain DEA reverse distributor licensing and state-level controlled substance permits, constraining 3PL partner selection.
- Multi-jurisdiction serialization:Product traceability requirements diverge between FDA DSCSA compliance and EU Falsified Medicines Directive mandates, forcing parallel packaging line investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Androgens and Anabolic Steroids Market |
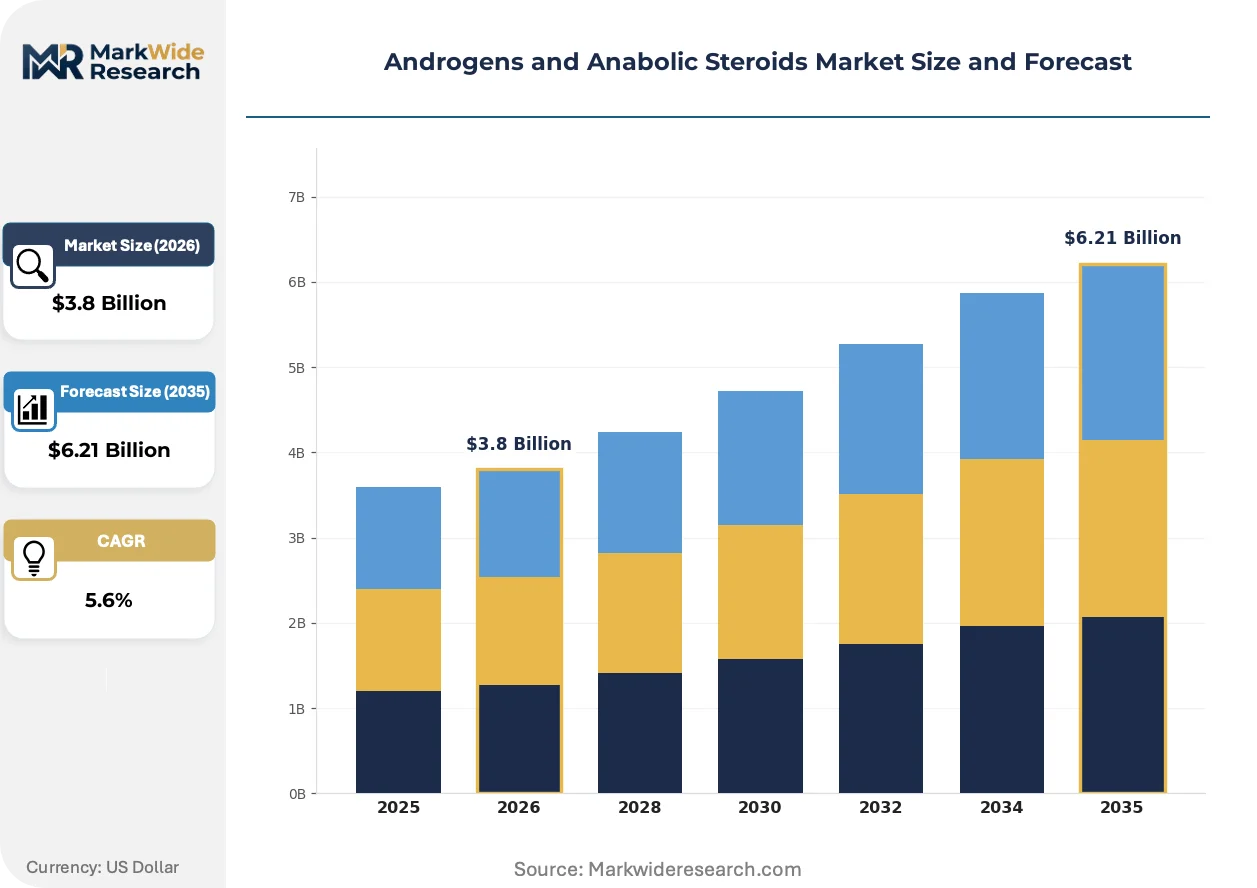
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Testosterone, Nandrolone, Stanozolol, Methandrostenolone Delivery Mode: Injection, Oral, Topical, Transdermal End User: Athletes, Bodybuilders, Clinics, Hospitals Regulatory Status: Prescription, Over-the-Counter, Controlled Substance, Unregulated |
| Companies Covered | Teva Pharmaceutical Industries, Bayer AG, Pfizer Inc., Viatris Inc., Sun Pharmaceutical Industries, AbbVie Inc., Cipla Ltd., Hikma Pharmaceuticals, Endo International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Androgens and Anabolic Steroids Market Strategic Shifts
Formulation science and patient-centric delivery mechanisms are displacing conventional intramuscular protocols across outpatient settings. These shifts are compressing the gap between clinical efficacy benchmarks and consumer convenience expectations.
Subcutaneous testosterone autoinjector systems are absorbing market share from traditional vial-and-syringe formats in North American men's health clinics. Endocrinology practices in Texas and Florida are piloting these devices for home administration protocols. The technology is absorbing training costs previously borne by clinic staff while reducing patient drop-off rates between appointments.
EMA pharmacovigilance periodic safety update report requirements are tightening signal detection obligations for androgen products across European markets. Manufacturers must now submit cumulative safety data every six months rather than annually. France and Germany have responded by centralizing adverse event reporting through national health technology assessment bodies.
Direct-to-patient pharmacy fulfillment is fragmenting traditional specialty pharmacy distribution for maintenance testosterone therapies. Telehealth platforms are capturing prescription flow that previously routed through urology clinic dispensaries. This channel shift is most visible in suburban United States markets where clinic density remains low but broadband penetration supports remote consultation models.
Androgens and Anabolic Steroids Market Segmentation
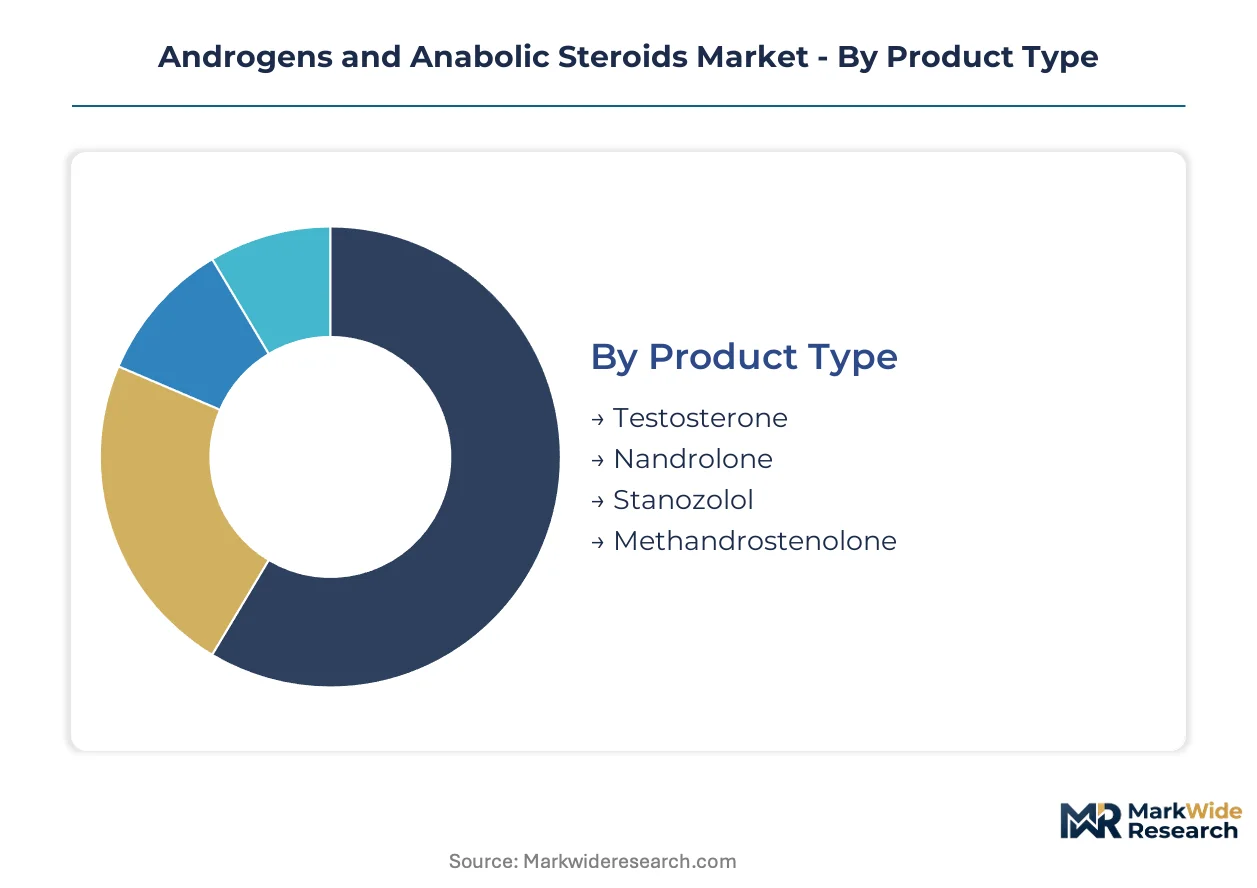
Androgens and anabolic steroids fragment across four distinct taxonomies that reshape capital allocation and compliance burden. Product chemistry determines manufacturing facility certification requirements. Delivery mode dictates distribution infrastructure investments. End-user concentration governs channel strategy. Regulatory status imposes scheduling and quota constraints that filter competitive entry.
Product Type:
Testosterone derivatives demand the heaviest upfront capital commitment due to controlled-substance manufacturing quotas and dedicated GMP facility requirements.
- Testosterone:Synthetic C19-steroid hormone formulated as enanthate, cypionate, or undecanoate esters for hypogonadism therapy. Demand concentrates in United States specialty men's health clinics and TRT networks, pulled by expanding diagnostic protocols and established Medicare reimbursement codes.
- Nandrolone:19-nortestosterone derivative with enhanced anabolic-to-androgenic ratio calibrated for anemia and cachexia indications. European hematology centers in Germany and France anchor prescription volume, constrained by EMA pharmacovigilance reporting obligations and narrow prescriber bases.
- Stanozolol:Dihydrotestosterone derivative with reduced androgenic activity for hereditary angioedema protocols.
- Methandrostenolone:17-alpha-alkylated oral compound with hepatotoxicity profile limiting clinical use to short-term corticosteroid-sparing applications.
Most installed capacity flows through Testosterone. Expansion is steepest in Nandrolone as European hematology protocols broaden eligibility criteria.
Delivery Mode:
Route of administration segments by patient adherence economics and cold chain infrastructure intensity, with self-administration formats commanding premium positioning.
- Injection:Intramuscular and subcutaneous depot formulations delivering pharmacokinetic precision through oil-based ester suspensions. United States outpatient clinics and home nursing services drive volume, supported by DEA-registered 503B compounding facilities for customized dosing.
- Oral:17-alpha-alkylated tablets bypassing first-pass metabolism through structural modification. Convenience-focused segments in telehealth-prescribed maintenance protocols absorb share, though hepatotoxicity surveillance limits chronic use.
- Topical:Gels and solutions applied to shoulder or upper arm skin with variable absorption rates.
- Transdermal:Patches delivering sustained release through stratum corneum permeation.
Injection retains the largest revenue pool. Transdermal patches are gaining share fastest among needle-averse patient cohorts seeking clinic-avoidant protocols.
End User:
Customer concentration splits between institutional procurement with formulary gatekeeping and direct-pay segments with price elasticity.
- Clinics:Specialty men's health and urology practices with in-house dispensaries or captive pharmacy relationships. United States suburban markets with low hospital density concentrate demand, served by direct-to-patient fulfillment models.
- Hospitals:Institutional procurement through group purchasing organizations with tiered rebate structures. Academic medical centers anchor volume for nandrolone and stanozolol in hematology and pediatric rheumatology protocols.
- Athletes:Regulated sports medicine programs with therapeutic use exemption frameworks.
- Bodybuilders:Non-therapeutic demand segments operating outside prescription channels.
Clinics process the highest prescription volume. Hospital procurement is expanding most quickly as integrated delivery networks centralize endocrinology services.
Regulatory Status:
Scheduling tier determines manufacturing quota access, distribution licensing burden, and prescriber authentication requirements.
- Controlled Substance:Schedule III classification under US Controlled Substances Act and equivalent European narcotics frameworks. DEA quota allocations and EMA manufacturing authorizations constrain supply elasticity, favoring incumbents with established compliance infrastructure.
- Prescription:Non-scheduled pharmaceutical status requiring licensed prescriber authorization without quota limitations.
- Over-the-Counter:Deregulated status permitting retail pharmacy dispensing without prescription.
- Unregulated:Jurisdictions lacking pharmaceutical classification or enforcement capacity.
Controlled Substance status captures the dominant revenue share. Prescription-tier positioning is climbing the fastest as regulatory harmonization spreads across Asia-Pacific markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized endocrinology workforces in Germany, Japan, and the United States anchor clinical trial infrastructure and regulatory science capacity for androgen therapies. These talent concentrations shape where manufacturers locate pharmacovigilance operations and where new formulations first reach commercial scale.
United States
TRT clinic networks in Texas and Florida drive outpatient testosterone volume through direct-to-patient fulfillment models. FDA Schedule III quotas administered by the DEA cap annual manufacturing volumes regardless of demand signals. Compounders in suburban Arizona and Nevada operate 503B outsourcing facilities serving niche dosing protocols outside standard commercial SKUs.
Germany
EMA centralized authorization procedures in Frankfurt accelerate mutual recognition across France, Italy, and Benelux markets for testosterone undecanoate formulations. Germany's national health technology assessment body consolidates adverse event reporting from hematology centers prescribing nandrolone. Manufacturing clusters in Bavaria and North Rhine-Westphalia host GMP-certified API finishing operations for European distribution.
Japan
METI-supported longevity initiatives expand endocrinology screening coverage for sarcopenia protocols in aging male populations. PMDA reviews of testosterone replacement therapies prioritize adherence metrics from quarterly injection formulations. Tokyo and Osaka academic medical centers anchor prescription volume for anabolic steroid applications in cachexia and anemia indications.
India
CDSCO manufacturing facility inspections in Gujarat and Maharashtra certify bulk testosterone API production for export markets. Domestic demand concentrates in Mumbai and Delhi specialty clinics serving therapeutic hypogonadism protocols. Indian pharmaceutical exporters navigate dual compliance burdens from FDA import alerts and EU REACH chemical registration requirements.
United Kingdom
MHRA post-Brexit recognition agreements preserve EMA centralized authorization pathways for testosterone products entering British markets. London teaching hospitals maintain therapeutic use exemption frameworks for regulated sports medicine applications. Regional endocrinology networks in Manchester and Birmingham consolidate prescribing data for national safety signal monitoring.
Androgens and Anabolic Steroids Market Competitive Environment
The competitive structure tilts toward vertically integrated generic manufacturers with captive API supply and established controlled-substance compliance infrastructure. Three archetypes dominate: multinational pharmaceutical conglomerates with hospital procurement contracts, mid-cap specialty generics firms with urology channel relationships, and emerging market exporters with cost-positioned bulk manufacturing. Consolidation through manufacturing quota acquisitions and 503B compounding facility partnerships represents the dominant competitive dynamic as regulatory density raises barriers for new entrants.
Among Israel-based generic specialists, Teva Pharmaceutical Industries exemplifies the vertically integrated archetype with in-house testosterone API production and DEA-registered distribution networks. German conglomerate Bayer AG anchors the specialty pharmaceutical tier through established urology and endocrinology prescriber relationships across European markets. Pfizer Inc. represents the institutional procurement archetype, leveraging hospital group purchasing organization contracts to limit competitor formulary access in United States academic medical centers.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Bayer AG |
| Pfizer Inc. |
| Viatris Inc. |
| Sun Pharmaceutical Industries |
| AbbVie Inc. |
| Cipla Ltd. |
| Hikma Pharmaceuticals |
| Endo International plc |
| Others |
Value Chain & Pricing Dynamics
Captive API production in Indian and Chinese pharmaceutical zones anchors cost positioning for testosterone formulators, creating pricing power that outsourced competitors cannot replicate without DEA-registered facility investments. This backward integration into bulk steroid synthesis separates incumbent cost structures from new entrant economics across North American and European markets.
Pricing Analysis
Bundled clinic-and-pharmacy service packages command premiums over unbundled prescription fulfillment, with Texas and Florida TRT networks capturing margin through captive dispensing relationships. Three-tier pricing structure across premium autoinjector, standard vial-and-syringe, and economy compounded formulations reflects DEA quota scarcity and GMP certification grade. Pricing pressure stems from telehealth platforms disintermediating traditional urology channels, compressing margins in suburban markets with low clinic density. Price-sensitive self-pay patients in direct-to-consumer segments drive demand for 503B compounded alternatives, while insured populations through hospital GPO contracts show lower elasticity.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled Schedule III products require DEA-registered reverse distributor licensing, constraining 3PL partner selection to specialists with controlled-substance handling credentials. Bulk testosterone API production concentrates in Gujarat and Maharashtra, India, and select Chinese pharmaceutical manufacturing zones, with formulators drawing from these clusters for GMP-certified finishing operations. Supply chain risk centers on FDA import alert volatility and customs inspection delays for API shipments. Distribution runs through DEA-registered specialty pharmacy networks and direct-to-patient fulfillment platforms, with cold chain integrity monitored through DSCSA serialization mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in subcutaneous delivery formats and 503B compounding carve-outs, where premium positioning and regulatory arbitrage respectively offset API cost pressures. Long-acting ester innovation reduces patient churn and extends lifetime value per account.
For Market Incumbents: Anchor formulary position through hospital GPO contract renewals that limit competitor access in academic medical centers. Deepen backward integration into testosterone API production to insulate against Indian import restriction volatility. Acquire 503B outsourcing facility licenses to capture niche dosing demand outside standard commercial SKUs. Defend against SARM substitution threats by emphasizing established reimbursement codes and long-term safety databases in hypogonadism protocols.
For New Entrants and Emerging Players: FDA 503B outsourcing facility regulations in the United States open a window for customized testosterone formulations serving micro-dosing and allergen-free patient segments. Target suburban markets with low urology clinic density but high broadband penetration for telehealth-integrated pharmacy fulfillment. Enter through subcutaneous autoinjector technology licensing to bypass incumbent vial-and-syringe manufacturing scale advantages. Focus initial commercialization on needle-phobic patient cohorts seeking clinic-avoidant protocols.
For Investors and Strategic Acquirers: Roll-up economics work for DEA-registered 503B compounding facilities because manufacturing quota scarcity and controlled-substance licensing create natural scarcity value for compliant assets. Prioritize targets with established reverse distributor relationships and cold chain certification infrastructure. Monitor EMA pharmacovigilance signal detection outcomes for testosterone products as an inflection indicator for European regulatory tightening that would redirect investment toward US-centric assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Autoinjector Development | Needle-phobic patient capture in Texas and Florida outpatient clinics reduces staff training burden. |
| 503B Outsourcing Facility Licensing | DEA-registered compounding carve-outs enable customized dosing outside standard commercial testosterone SKUs. |
| API Backward Integration | In-house testosterone synthesis insulates formulators from Indian import alert volatility and customs delays. |
| Telehealth Platform Partnership | Direct-to-patient fulfillment models capture prescription flow from suburban markets with low clinic density. |
| Long-Acting Ester Formulation Investment | Quarterly injection intervals improve adherence metrics and extend patient lifetime value in maintenance protocols. |
Study Parameters
Multiple input streams — regulatory filing analysis, pharmaceutical trade data, and clinical protocol documentation — were reconciled through bottom-up and top-down triangulation. Primary interviews with drug development executives, regulatory affairs leads at testosterone manufacturers, formulary directors at hospital GPOs, and 503B compounding facility operators informed demand-side assumptions. Secondary validation drew from FDA ANDA filings, DEA manufacturing quota publications, EMA centralized authorization decisions, and ClinicalTrials.gov protocol registries. Supply-side modeling incorporated CDSCO facility inspection records and Indian pharmaceutical export customs data.
Data-stream reconciliation across these sources produced volume and value estimates across the projection horizon. Segmentation dimensions modeled include product chemistry class, delivery mode, end-user concentration, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical prescription volume trajectories and reimbursement code expansion patterns. Forecast inputs incorporated DEA quota allocation rigidity, EMA pharmacovigilance reporting frequency changes, and METI-supported screening coverage expansion in Japan.
Revisions become necessary when DEA scheduling proposals tighten, EMA safety signals trigger label restrictions, or SARM clinical trial readouts demonstrate non-inferiority to testosterone in muscle-wasting indications. Practitioners should monitor FDA import alert patterns for Indian API facilities and PMDA reimbursement negotiation outcomes for sarcopenia protocols as early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Glucosamine Supplements Market
Dietary Supplements
Postpartum Health Supplements Market
Dietary Supplements
Menopause Supplement Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Vitamin D Deficiency Treatment Market
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Eye Care Supplements Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Magnesium Glycinate Market
Dietary Supplements
Nootropic Products Market
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Non-Hormonal Steroid Modulators Market
Dietary Supplements
Medicated Confectionery Market
Dietary Supplements
Soft Gel Capsule Market