
 Immune Health Supplements Market | 2026-2036
Immune Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Immune Health Supplements Market Intelligence
Capital-intensity divergence between contract manufacturers and branded formulators is rotating competitive advantage toward companies with in-house clinical validation infrastructure. Glanbia plc leverages its integrated dairy-derived ingredient platform to control whey protein and colostrum supply chains for immune formulations. Abbott Laboratories anchors its position through pediatric and adult nutrition science credibility, extending from medical channels into consumer wellness. NOW Foods competes on manufacturing scale and transparent sourcing, sustaining price accessibility across vitamin and mineral immune blends.
Immune health supplements comprise orally administered nutritional products containing bioactive compounds—vitamins C and D, zinc, selenium, Lactobacillus and Bifidobacterium probiotic strains, and botanical extracts such as echinacea and elderberry—formulated to modulate innate and adaptive immune responses through micronutrient repletion, gut-associated lymphoid tissue stimulation, or antioxidant pathways. Probiotics and herbal extracts command expanding shelf space as consumers seek alternatives to synthetic vitamin dominance, while gummies and liquid formats capture share from traditional pills among children and senior end users who prioritize palatability and swallowing ease.
FDA enforcement of Current Good Manufacturing Practice regulations and DSHEA-compliant structure-function claims shapes product development timelines and marketing language for US-market entrants. The European Food Safety Authority's health claims authorization process under Regulation EC 1924/2006 creates a stricter gatekeeping environment for probiotic and botanical immune claims across EU member states. Stakeholders must monitor emerging microbiome sequencing evidence standards and adapt substantiation portfolios before regulatory bodies tighten clinical threshold requirements for immune-specific marketing.
Market Dynamics
The FDA's intensified DSHEA enforcement and EFSA's tightening health claims standards are forcing manufacturers to rebuild substantiation infrastructure around clinical trial portfolios rather than traditional observational studies.
Growth Catalysts
- Preventive wellness prioritization:Aging demographics in Germany, Japan, and the United States are redirecting healthcare spending toward micronutrient repletion protocols before chronic disease onset.
- DSHEA structure-function claim pathways:The FDA's clarified enforcement discretion allows compliant firms to market immune support benefits while competitors face warning letter delays.
- Microbiome sequencing advances:Shotgun metagenomics is validating strain-specific probiotic mechanisms, enabling differentiated positioning against generic Lactobacillus blends.
Market Restraints
- Colostrum and whey protein input volatility:Dairy commodity price swings in New Zealand and Ireland transmit directly to margin compression for immune formulations dependent on these bioactive fractions.
- EFSA health claims authorization backlog:The European regulator's stringent Article 13.5 and 14 evidentiary requirements block market entry for botanical immune products lacking proprietary human intervention data.
- Synthetic vitamin substitution threat:Pharmaceutical-grade ascorbic acid and cholecalciferol from Chinese chemical manufacturers undercuts fermented or plant-derived alternatives on cost.
Strategic Opportunities
- Pediatric gummy format penetration:Palatability-driven delivery systems capture caregiver willingness to pay premium prices for compliant child dosing in the United States and United Kingdom.
- Subscription direct-to-consumer channels:Recurring revenue models bypass pharmacy retail margin extraction while building adherence data assets for future personalized nutrition pivots.
- Postbiotic and paraprobiotic formulations:Heat-killed bacterial lysates and cell wall fragments circumvent cold-chain logistics constraints while opening structure-function claim flexibility under evolving regulatory frameworks.
Industry Challenges
- Clinical trialist scarcity:Qualified investigators capable of executing GI-immune endpoint studies are concentrated among contract research organizations with 12-18 month queue backlogs.
- CGMP remediation capex burdens:FDA 483 observations for allergen cross-contamination or stability testing deficiencies force mid-tier manufacturers into facility upgrades exceeding available credit facilities.
- Strain-specific IP fragmentation:Proprietary probiotic deposits at culture collections trigger licensing disputes when formulators source ostensibly generic strains with undocumented phenotypic variations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immune Health Supplements Market |
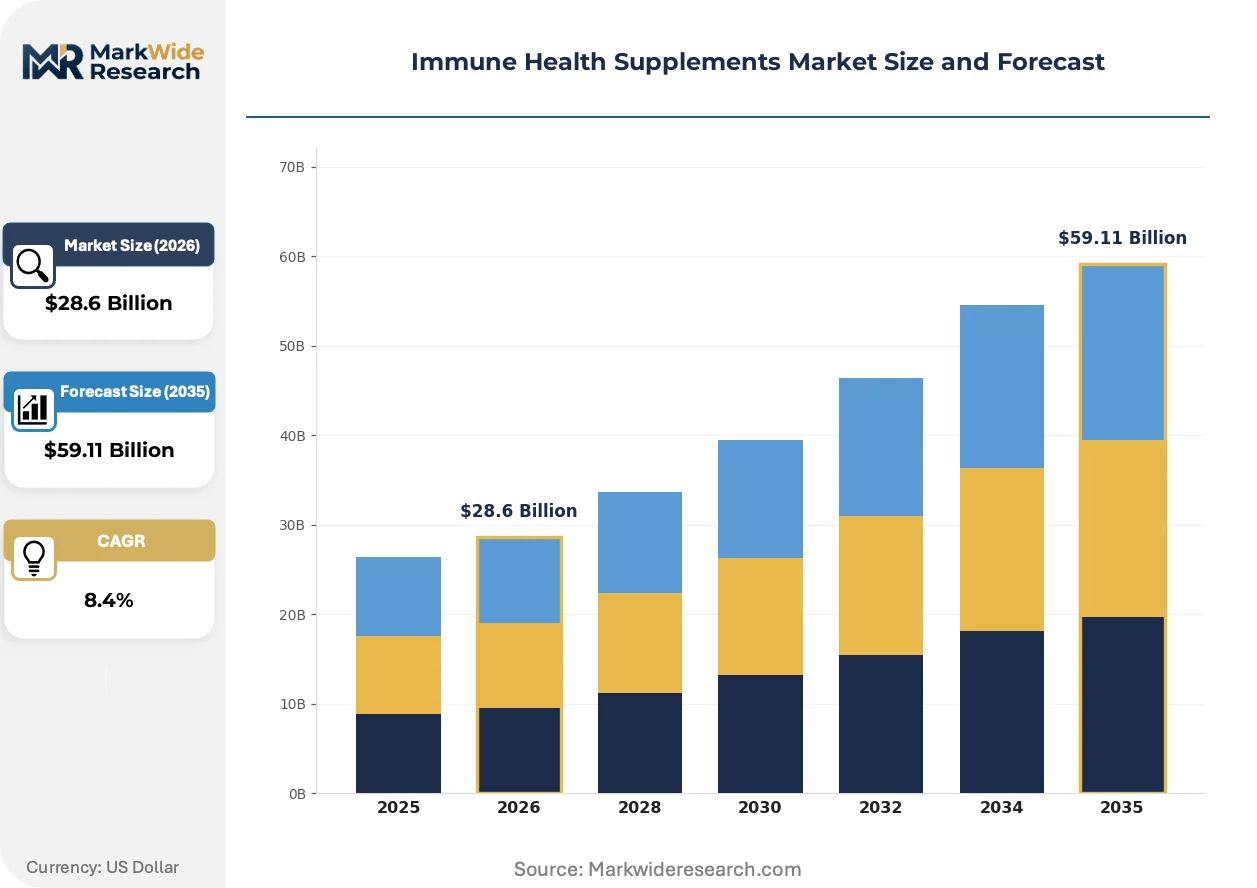
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Probiotics, Herbal Extracts, Minerals Form: Pills, Powder, Gummies, Liquid End User: Adults, Children, Seniors, Athletes Distribution Channel: Online, Retail Stores, Pharmacies, Health Food Shops |
| Companies Covered | Amway Corp, Bayer AG, NOW Foods, Nature's Bounty Co., Herbalife Nutrition Ltd., Glanbia plc, Abbott Laboratories, Pfizer Inc., Himalaya Global Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immune Health Supplements Market Strategic Shifts & Innovations
Delivery technology convergence with microbiome science is collapsing the traditional separation between format innovation and mechanistic substantiation, forcing simultaneous investment in both axes.
Liposomal encapsulation technology is supplanting standard tablet and softgel formats for fat-soluble vitamins D3, K2, and astaxanthin in immune formulations. Functional medicine practitioners and high-compliance senior consumers are driving adoption at 15-20% annual volume expansion in North American specialty channels. This shift is compressing shelf space for conventional excipient-heavy tablets while rewarding manufacturers with in-house liposome production capabilities.
EFSA's 2024 updated guidance on gut health and immune function claims under Regulation EC 1924/2006 is narrowing acceptable probiotic study endpoints to pathogen-specific challenge models. The industrial consequence is a bifurcation between firms funding expensive human infection trials and those retreating to vague digestive wellness positioning. German and Dutch probiotic specialists with existing influenza challenge data are consolidating market access advantages while Italian botanical formulators pivot toward stress-sleep-immunity hybrid claims.
Subscription auto-replenishment is displacing pharmacy and mass retail impulse purchasing for baseline immune SKUs. Millennial and Gen X households in the United States and Australia are consolidating brand relationships through direct-to-consumer platforms that bundle personalized microbiome testing with quarterly supplement shipments. This channel shift is most visible among urban professional segments with employer-sponsored HSA/FSA benefits covering preventive wellness expenditures.
Immune Health Supplements Market Segmentation
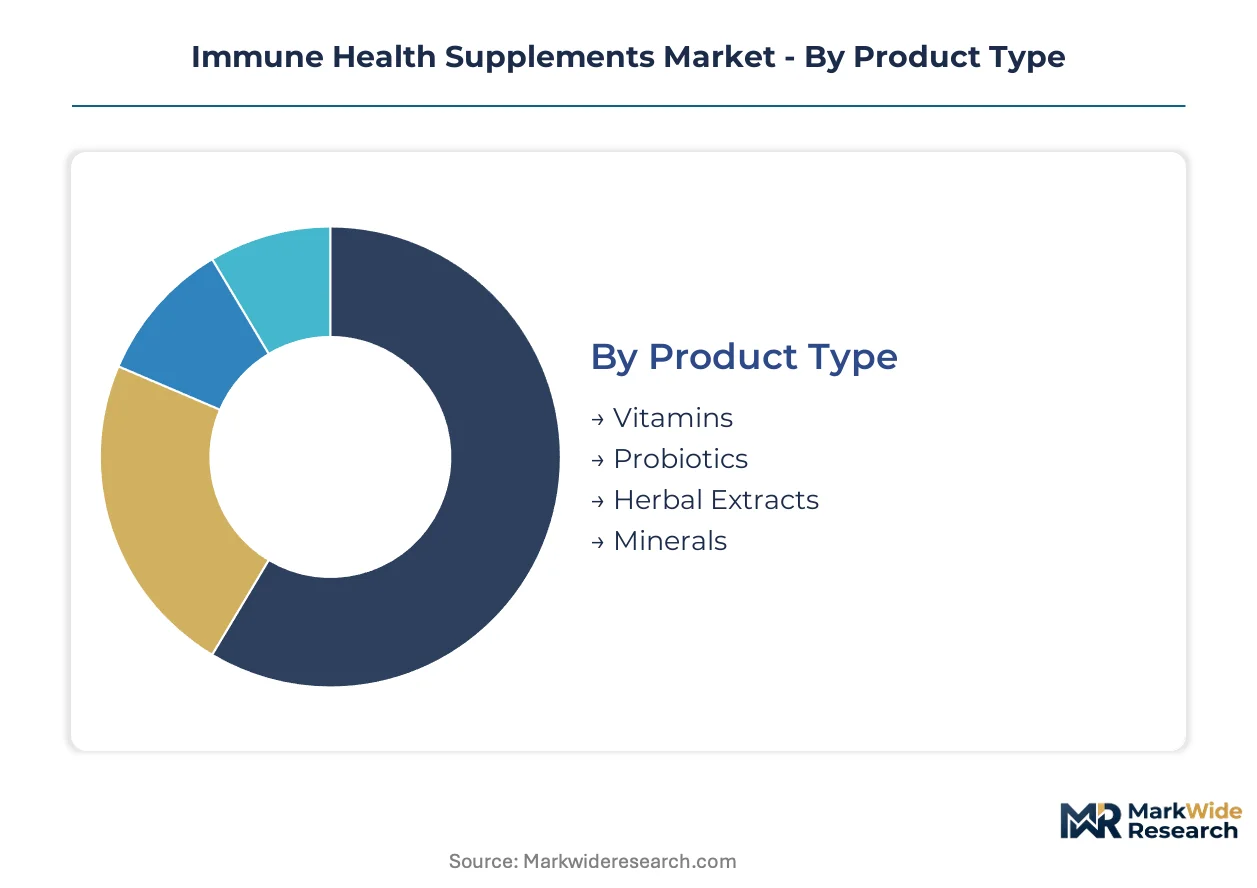
Immune health supplements fragment across four intersecting dimensions that determine formulation complexity, regulatory pathway, and margin structure. Product chemistry and delivery format decisions cascade through distribution economics and end-user compliance patterns.
Product Type:
Synthetic vitamin commoditization exerts the strongest substitution pressure on mineral and standard vitamin segments, while probiotics and botanicals defend differentiation through strain-specific IP and extraction standardization.
- Vitamins:Ascorbic acid, cholecalciferol, and tocopherol formulations dominate unit volumes but face margin compression from pharmaceutical-grade Chinese manufacturing. Adult daily supplementation in the United States and Germany sustains baseline demand despite price erosion.
- Probiotics:Live Lactobacillus and Bifidobacterium cultures, plus emerging postbiotic lysates, command premium positioning through microbiome sequencing substantiation. German and Dutch specialists with human challenge trial data capture shelf space advantages under EFSA's tightened gut-immune claim standards.
- Herbal Extracts:Echinacea, elderberry, and andrographis preparations face EFSA Article 13.5 authorization backlogs that block EU market entry without proprietary intervention studies.
- Minerals:Zinc picolinate, selenium yeast, and chelated iron formulations compete on bioavailability claims with limited clinical differentiation.
Vitamins retain volume leadership; probiotics hold the steepest expansion curve.
Form:
Palatability requirements and swallowing physiology segment the market across age demographics, with pediatric and senior compliance driving format innovation investment.
- Pills:Standard tablets and hard-shell capsules maintain cost leadership for price-sensitive adult segments in pharmacy and mass retail channels. Compressed margins from excipient-heavy manufacturing limit differentiation opportunity.
- Powder:Bulk micronutrient blends serve athletic end users and functional medicine practitioners seeking dose customization. Mixing convenience and transportability sustain niche positioning in United States specialty nutrition channels.
- Gummies:Gelatin and pectin-based chewable matrices capture caregiver willingness to pay premiums for child-compliant dosing in US and UK households. Sugar content and stability testing burdens complicate formulation.
- Liquid:Liposomal suspensions and emulsified fat-soluble vitamins address senior swallowing difficulty and absorption concerns. Liposome production capabilities concentrate competitive advantage among integrated manufacturers.
Pills dominate absolute unit shipments; gummies gain share fastest among format innovations.
End User:
Preventive wellness prioritization intensity varies sharply across life stages and activity levels, concentrating R&D investment toward aging and performance segments.
- Adults:Working-age consumers aged 25-54 drive baseline replenishment demand through subscription auto-replenishment models. Employer HSA/FSA benefit coverage in the United States accelerates direct-to-consumer channel migration.
- Children:Caregiver-mediated purchasing prioritizes palatable formats and clean-label positioning over clinical substantiation depth. Pediatric dosing precision requirements complicate formulation relative to adult equivalents.
- Seniors:Adults 65+ redirect pharmaceutical spending toward preventive protocols, prioritizing bioavailability-enhanced formats and medical channel credibility. Swallowing difficulty and polypharmacy interactions shape product selection.
- Athletes:Competitive and recreational performers seek immune resilience under training load stress, driving demand for NSF Certified for Sport and Informed Sport third-party testing protocols.
Adults constitute the largest addressable base; seniors expand most quickly as aging demographics intensify preventive spending.
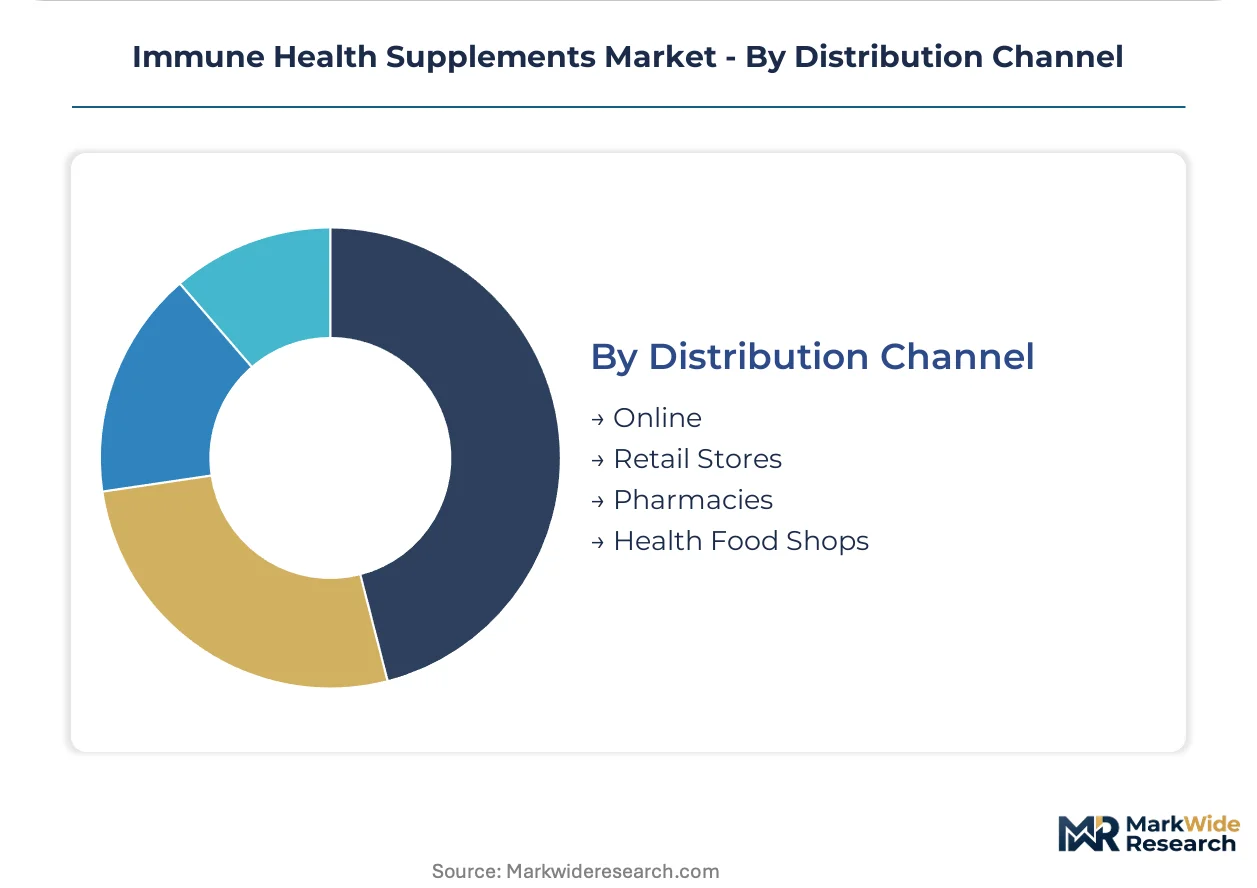
Distribution Channel:
Channel selection determines margin extraction, customer data capture, and regulatory compliance burden simultaneously.
- Online:Direct-to-consumer platforms and marketplace aggregators consolidate millennial and Gen X purchasing through subscription bundling and microbiome test integration. Recurring revenue models bypass pharmacy retail margin extraction.
- Retail Stores:Mass merchandisers and grocery chains sustain impulse purchasing for baseline vitamin SKUs with limited differentiation. Shelf space fees and promotional spending compress net margins for branded formulators.
- Pharmacies:Chain and independent drugstores leverage pharmacist recommendation authority for condition-specific immune positioning. DSHEA structure-function claim compliance requirements shape product assortment.
- Health Food Shops:Specialty retailers emphasize transparent sourcing, non-GMO verification, and practitioner-grade potency for high-compliance consumer segments. Limited geographic footprint constrains volume scaling.
Pharmacies retain the highest trust conversion rates; online channels climb fastest as subscription models consolidate purchasing behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German benchmarks by approximately 40% for clinically substantiated probiotic SKUs, while Chinese contract manufacturers capture volume leadership through pharmaceutical-grade synthetic vitamin exports. This asymmetry shapes regional investment allocation and regulatory compliance priorities.
United States
Employer-sponsored HSA/FSA benefits and direct-to-consumer subscription penetration drive premium pricing for bioavailability-enhanced formats. FDA DSHEA enforcement under 21 CFR 101.93 shapes structure-function claim language and substantiation requirements. The Greater Boston corridor hosts microbiome sequencing specialists supplying strain-specific validation data to branded formulators.
Germany
Aging demographics redirect pharmaceutical spending toward preventive micronutrient protocols before chronic disease onset. EFSA Regulation EC 1924/2006 Article 13.5 authorization requirements block market entry for botanical immune products lacking proprietary human intervention data. Bavaria-based probiotic specialists leverage existing influenza challenge trial portfolios to defend shelf space under tightened gut-immune claim standards.
China
Domestic demand for immune supplements concentrates in tier-one cities among middle-class households with rising preventive wellness awareness. NMPA dietary supplement registration under Food Safety Law Article 76 requires formula and label pre-approval for imported products. Zhejiang and Jiangsu provinces host pharmaceutical-grade ascorbic acid and cholecalciferol manufacturers supplying cost-competitive inputs to global formulators.
Japan
Functional Foods for Specified Health Uses (FOSHU) and Foods with Function Claims (FFC) systems create dual pathways for immune-positioned products with varying evidentiary thresholds. METI industrial policy supports postbiotic and paraprobiotic R&D through regional cluster initiatives. The Kanto region around Tokyo concentrates finished goods manufacturing and retail pharmacy distribution infrastructure.
Australia
TGA Listed Medicine registration requirements and complementary medicine advertising restrictions shape product development timelines for both domestic and export-oriented formulators. Employer wellness program subsidies and private health insurance rebate eligibility accelerate direct-to-consumer channel migration in Sydney and Melbourne metro areas. Queensland hosts botanical extraction specialists supplying standardized echinacea and elderberry concentrates.
Immune Health Supplements Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated dairy processors and pharmaceutical-grade chemical manufacturers occupying opposing ends of the value chain. The vendor base organizes around three strategic groupings: clinical validation specialists with in-house trial infrastructure, contract manufacturers with CGMP-scale production assets, and ingredient platform owners with captive supply chains. Consolidation pressure concentrates among mid-tier branded formulators lacking either proprietary strain IP or liposome production capabilities. Dominant competitive moves include backward integration into bioactive ingredient supply and geographic licensing partnerships for EFSA-compliant claim substantiation.
Among publicly traded nutrition specialists, Glanbia plc anchors the ingredient platform archetype through integrated dairy-derived supply chain control, while Abbott Laboratories exemplifies clinical credibility extension from medical channels into consumer wellness. NOW Foods occupies a position within the manufacturing scale tier, competing on transparent sourcing and price accessibility across standard vitamin and mineral blends. These three entities collectively represent the structural segmentation between upstream supply control, medical channel authority, and manufacturing scale efficiency.
| Leading Market Players |
|---|
| Amway Corp |
| Bayer AG |
| NOW Foods |
| Nature's Bounty Co. |
| Herbalife Nutrition Ltd. |
| Glanbia plc |
| Abbott Laboratories |
| Pfizer Inc. |
| Himalaya Global Holdings Ltd. |
| Others |
Cost & Logistics Intelligence
Contract manufacturing scale economies in Zhejiang and Jiangsu provinces compress price floors for pharmaceutical-grade ascorbic acid and cholecalciferol while simultaneously concentrating upstream supply control among Chinese chemical producers. This scale asymmetry forces branded formulators to absorb margin volatility or invest in backward integration into dairy-derived bioactives.
Pricing Analysis
The customization-premium spread separates liposomal liquid formulations from standard tablet equivalents by a substantial margin multiple. Three-tier pricing structure across premium, standard, and economy levels reflects bioavailability certification tiers and cold-chain logistics requirements. Cost compression in synthetic vitamin segments stems from Chinese pharmaceutical-grade manufacturing scale. Price-sensitive mass retail buyers in pharmacy channels contrast with premium-tolerant direct-to-consumer subscribers seeking personalized microbiome bundles.
Supply Chain Analysis
Strait of Hormuz transit exposure underwrites energy cost volatility for liposomal encapsulation production facilities dependent on Middle Eastern solvent feedstocks. Raw material sourcing draws from New Zealand and Irish dairy herds for colostrum fractions, Chinese chemical manufacturers for synthetic vitamins, and Queensland botanical extraction specialists for standardized herbal concentrates. Single-source vulnerability concentrates in pharmaceutical-grade probiotic culture collections. Distribution runs through direct-to-consumer subscription platforms, pharmacy retail networks, and mass merchandiser channels with divergent margin extraction profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbiome sequencing validation standards are reshaping competitive entry barriers faster than regulatory bodies can harmonize claim substantiation thresholds. This technological inflection compresses timelines for clinical trial infrastructure investment.
For Market Incumbents: Fortify proprietary strain IP portfolios through exclusive culture collection deposits and influenza challenge trial data accumulation. Deepen backward integration into dairy-derived bioactive supply chains to insulate margin structures from New Zealand commodity price swings. Defend shelf space advantages under EFSA's tightened gut-immune claim standards by accelerating postbiotic formulation pipelines. For New Entrants and Emerging Players: Anchor in pediatric gummy format segments where palatability-driven caregiver willingness to pay premiums offsets formulation complexity costs. Target senior swallowing-difficulty applications with liposomal liquid alternatives bypassing established tablet incumbents. Pursue direct-to-consumer subscription launch with bundled microbiome testing to capture recurring revenue before pharmacy retail consolidation accelerates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clinical validation specialists with in-house GI-immune endpoint capabilities over pure manufacturing scale assets. Long-term viability rests on strain-specific mechanistic substantiation rather than generic probiotic positioning. Acquisition target archetype: German or Dutch probiotic specialists with existing human challenge trial portfolios. Watch EFSA's evolving guidance on postbiotic structure-function claims as the inflection signal for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Infrastructure Investment | Human challenge trial capabilities unlock EFSA gut-immune claim authorization under Regulation EC 1924/2006. |
| Backward Integration into Dairy Bioactives | Captive colostrum and whey protein supply insulates margin compression from New Zealand commodity volatility. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models bypass pharmacy retail margin extraction while building adherence data assets. |
| Postbiotic Formulation Pipeline | Heat-killed bacterial lysates circumvent cold-chain logistics while opening structure-function claim flexibility. |
| Liposome Production Capability Acquisition | In-house encapsulation technology captures 15-20% annual volume expansion in North American specialty channels. |
Research Approach
Desk research of FDA warning letter databases, EFSA Article 13.5 authorization registers, and ClinicalTrials.gov immune endpoint studies preceded structured interviews with probiotic R&D directors, contract manufacturing quality leads, and pharmacy category buyers. Secondary validation drew from customs import records for pharmaceutical-grade vitamin inputs, SEC 10-K filings for publicly traded nutrition specialists, and Nielsen retail audit data for format-level channel dynamics. Bottom-up SKU-level demand modeling triangulated against top-down demographic spending projections.
Variance decomposition across the analysis window allocated forecast sensitivity to aging demographic penetration rates, EFSA claim authorization timelines, and dairy commodity price elasticity. Segmentation dimensions modeled include product chemistry, delivery format, end-user life stage, and distribution channel structure. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns with regulatory inflection adjustments. Industry-specific inputs incorporated microbiome sequencing cost decline trajectories and employer HSA/FSA benefit expansion assumptions.
Decision-makers should treat outputs as directional under sustained FDA DSHEA enforcement posture and EFSA evidentiary tightening assumptions; material deviation in regulatory timelines or dairy supply shocks would warrant model refresh. Practitioners should keep alternative scenarios live as postbiotic claim substantiation standards and Chinese synthetic vitamin export policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Lifestyle-Related Disease Supplements Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Glucosamine Salt Market
Dietary Supplements
Nootropic Products Market
Dietary Supplements
Folic Acid Tablets Market
Dietary Supplements
Canine Weight Loss Drugs Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Melatonin Sleep Supplements Market