
 Testosterone Injectable Market | 2026-2036
Testosterone Injectable Market Size, Share, and Industry Trends Forecast 2026-2036
Testosterone Injectable Market Analytics
Pre-filled syringe bundling with patient monitoring services is hardening as the preferred commercial configuration. AbbVie Inc. anchors its position through integrated patient support programs that pair drug delivery with compliance tracking. Pfizer Inc. competes via manufacturing scale across multiple ester formulations. Eli Lilly & Company differentiates through specialty channel relationships with urology and endocrinology practices.
Testosterone injectables are sterile oil-based solutions of testosterone esters, typically formulated in sesame or cottonseed oil at concentrations of 100–250 mg/mL for intramuscular or subcutaneous administration, designed to restore physiologic testosterone levels in hypogonadal patients. Testosterone Cypionate dominates prescription volumes in North American markets due to longer half-life and established reimbursement. The Home Care delivery mode captures the fastest expansion as self-administration protocols gain clinical acceptance, while Specialized Centers retain premium pricing through supervised loading regimens.
FDA REMS requirements and DEA Schedule III controls govern testosterone injectable distribution, prescribing, and pharmacy fulfillment in the United States. The EMA's pharmacovigilance framework and national health technology assessments across Europe shape market access and pricing negotiations. Stakeholders must monitor evolving cardiovascular safety labeling and telehealth prescribing rule changes that could alter patient acquisition economics and channel mix.
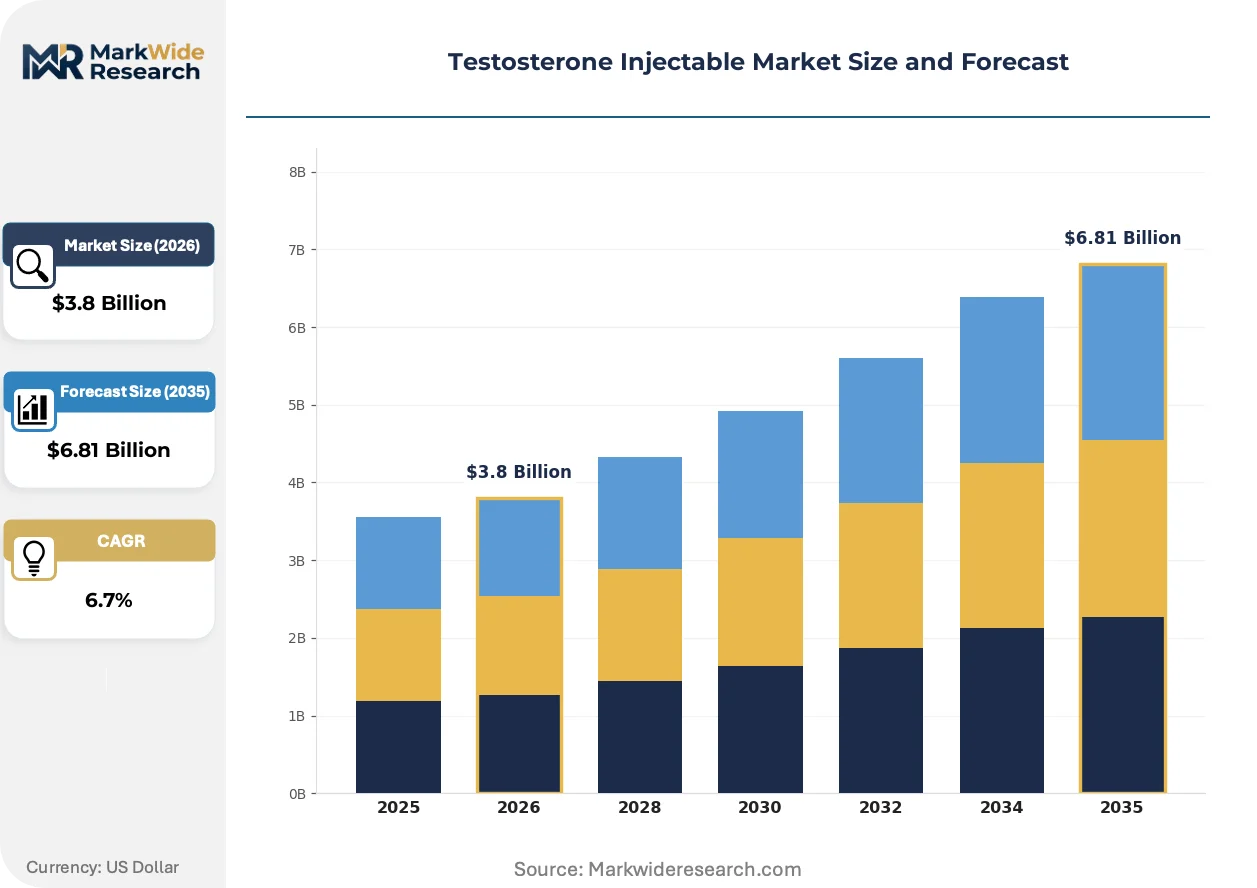
Market Dynamics
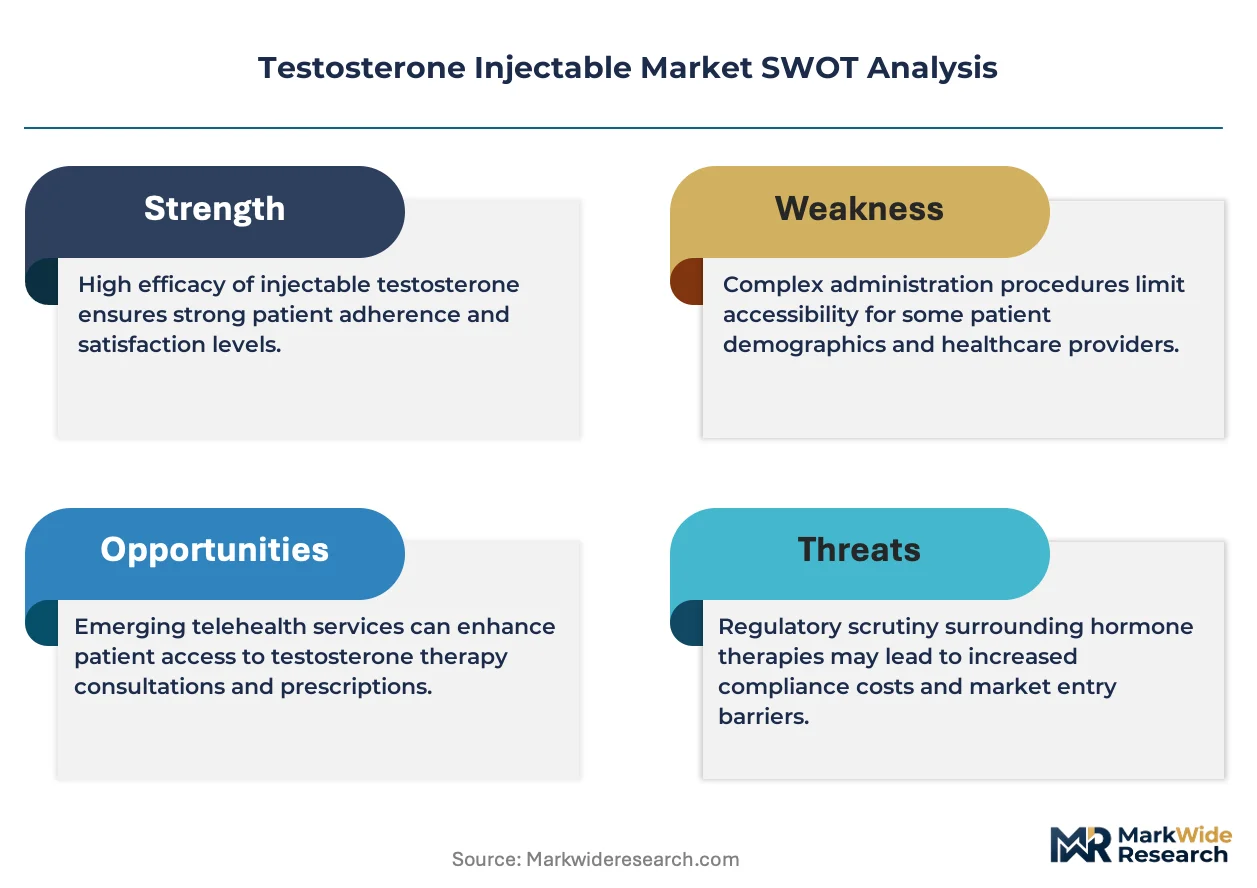
FDA REMS protocols and DEA Schedule III controls are compressing prescribing flexibility while telehealth platforms simultaneously expand patient access, creating a structural tension between clinical oversight and consumer convenience that vendors must navigate through integrated service models.
Growth Catalysts
- Telehealth prescribing liberalization:Direct-to-patient platforms bypass traditional clinic gatekeeping, shortening patient acquisition cycles and reducing geographic barriers to hormone therapy initiation.
- Men's health clinic expansion:Specialized outpatient networks normalize testosterone deficiency screening, converting latent demand into diagnosed, treated patient volumes.
- Self-administration protocols:Subcutaneous injection techniques reduce dependency on healthcare facilities, enabling home care delivery modes that improve adherence and lower total cost of care.
Market Restraints
- API supply concentration:Testosterone ester active pharmaceutical ingredients concentrate among a limited set of contract manufacturers, exposing formulations to single-source disruption risk.
- Cardiovascular safety labeling:FDA-mandated warnings on thromboembolic and cardiovascular events constrain prescriber enthusiasm and complicate patient informed consent processes.
- Compounding pharmacy substitution:503B outsourcing facilities and state-licensed compounders offer customized ester blends at price points that erode branded injectable volumes.
Strategic Opportunities
- Bioidentical pellet integration:Convergence of injectable protocols with implantable testosterone pellets creates combination therapy protocols that extend dosing intervals and reduce injection frequency.
- Digital therapeutics bundling:Pairing drug delivery with smartphone-based symptom tracking and telemedicine follow-up differentiates commoditized formulations through outcomes documentation.
- Veterans Health Administration penetration:Underpenetrated access within federal healthcare systems offers volume contracts with standardized formularies and centralized procurement.
Industry Challenges
- Specialty pharmacy credentialing:DEA registration and state-level controlled substance licensing create multi-month onboarding timelines that delay product availability in new distribution channels.
- Cold chain integrity maintenance:Oil-based formulations require temperature-controlled logistics that complicate direct-to-patient shipping and increase last-mile fulfillment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testosterone Injectable Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Testosterone Cypionate, Testosterone Enanthate, Testosterone Decanoate, Testosterone Propionate Delivery Mode: Intramuscular, Subcutaneous, Depot Injection, Bolus Injection End User: Clinics, Hospitals, Home Care, Specialized Centers Therapy Area: Hormone Replacement, Hypogonadism, Bodybuilding, Infertility |
| Companies Covered | AbbVie Inc., Endo Pharmaceuticals Inc., Pfizer Inc., Bayer AG, Eli Lilly & Company, Teva Pharmaceutical Industries Ltd., Novartis AG, Amneal Pharmaceuticals Inc., Halozyme Therapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testosterone Injectable Market Evolving Landscape
Pre-filled delivery systems and connected health infrastructure are converging to transform testosterone replacement from episodic prescription fulfillment into continuous therapeutic management. This evolution favors vendors with capabilities spanning device manufacturing, data analytics, and clinical service integration.
Autoinjector platforms with integrated needle-safety mechanisms are consolidating patient preference around single-use, pre-assembled delivery systems. Urology practices and endocrinology clinics are standardizing on these devices to reduce training burden and minimize injection-site complications. The technology is consolidating demand away from traditional vial-and-syringe configurations toward premium-priced, compliance-optimized formats that capture higher margins per prescription.
The FDA's Risk Evaluation and Mitigation Strategy for testosterone products is tightening prescriber certification requirements and patient monitoring obligations. This regulatory pressure is elevating the importance of pharmacy-based patient support programs that document adherence and adverse events. Specialty pharmacies with REMS-compliant infrastructure are capturing disproportionate dispensing volume as prescriber offices outsource compliance burden.
Subscription-based replenishment models are displacing traditional 30-day retail pharmacy transactions. Direct-to-consumer platforms and men's health telemedicine services are locking patients into automated delivery schedules that reduce switching and improve lifetime value metrics. This pattern is most visible in United States markets where cash-pay patients prioritize convenience over insurance-mediated cost optimization.
Testosterone Injectable Market Segmentation
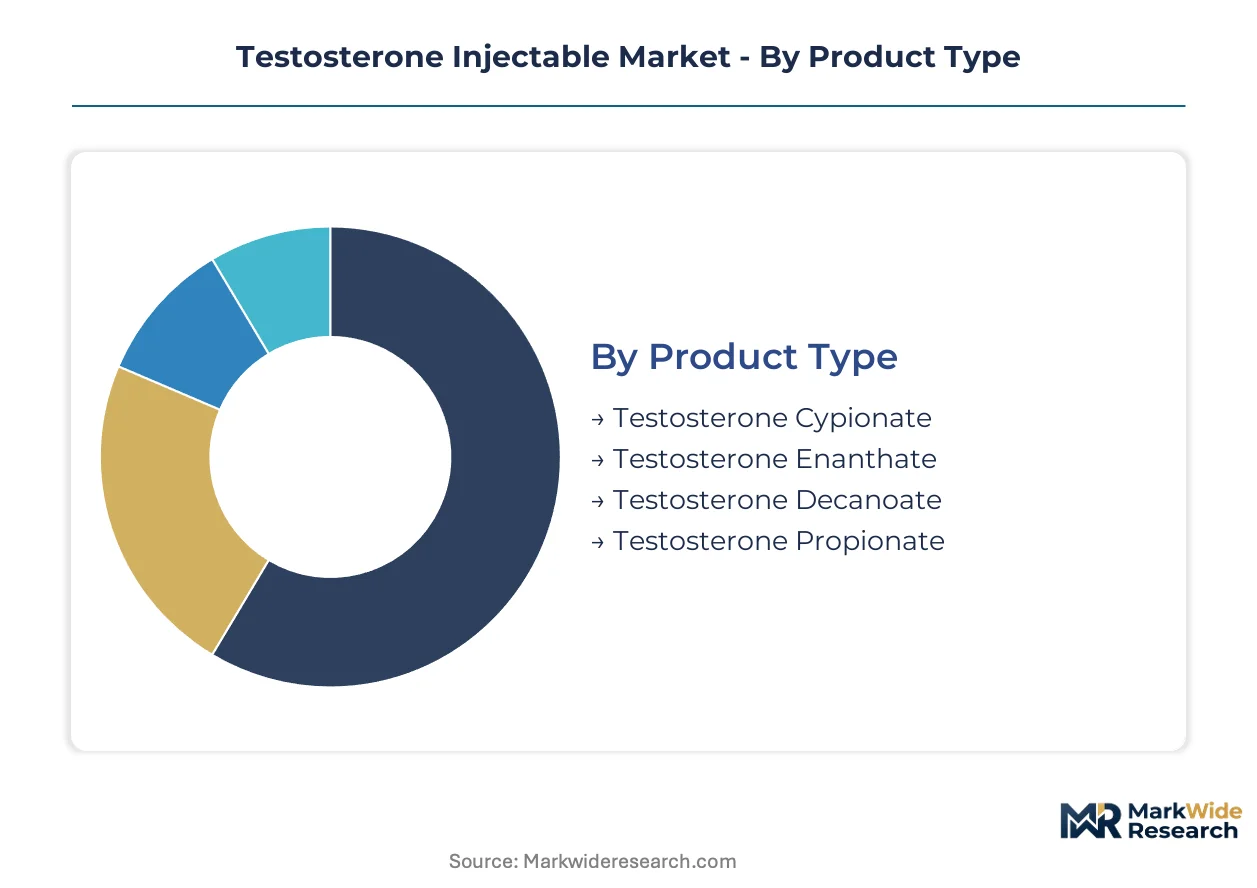
Testosterone injectable formulations fragment across ester chemistry, administration routes, and care settings. Supply concentration in API manufacturing and distribution channel credentialing create divergent margin profiles across these segments.
Product Type:
API contract manufacturers concentrate testosterone ester production among a limited supplier base, exposing formulation availability to single-source disruption risk.
- Testosterone Cypionate:Formulated as a sterile oil-based solution in cottonseed oil at 100–200 mg/mL concentrations. Demand concentrates in United States markets where established reimbursement codes and longer half-life properties drive prescriber preference, though cardiovascular safety labeling constrains enthusiasm.
- Testosterone Enanthate:Delivered in sesame oil vehicles at comparable concentrations with slightly shorter pharmacokinetic profiles. European markets favor this ester due to EMA pharmacovigilance alignment and national health technology assessment familiarity, creating geographic segmentation against cypionate dominance.
- Testosterone Decanoate:Long-acting ester enabling extended dosing intervals through depot formation.
- Testosterone Propionate:Short-acting formulation requiring more frequent administration cycles.
Today's leader: Testosterone Cypionate. Tomorrow's challenger: Testosterone Enanthate.
Delivery Mode:
Patient acquisition economics shift dramatically based on whether administration requires clinical supervision or permits self-management.
- Intramuscular:Deep gluteal or deltoid injection technique using 1–1.5 inch needles. Specialized Centers and hospital settings concentrate demand here, with supervised loading regimens commanding premium pricing through prescriber oversight.
- Subcutaneous:Abdominal or thigh administration using shorter needles with reduced tissue trauma. Home Care delivery mode is climbing the fastest as telehealth platforms validate patient self-administration protocols and reduce facility dependency.
- Depot Injection:Sustained-release formulation designed for extended intervals between doses.
- Bolus Injection:Single-dose rapid delivery for acute correction protocols.
Facility-based administration retains margin. Patient-directed delivery gains volume.
End User:
Channel mix determines compliance infrastructure requirements and REMS documentation obligations.
- Home Care:Self-administration protocols paired with connected health monitoring. United States direct-to-consumer telehealth platforms are expanding most quickly here, bypassing traditional clinic gatekeeping through automated replenishment models.
- Specialized Centers:Urology and endocrinology practices with integrated patient support programs. These settings concentrate premium-priced pre-filled autoinjector adoption and capture higher margins per prescription through compliance tracking services.
- Clinics:Outpatient men's health networks normalizing testosterone deficiency screening.
- Hospitals:Acute care settings managing severe hypogonadism or pre-surgical optimization.
Institutional credentialing slows entry. Direct-to-patient models compress acquisition cycles.
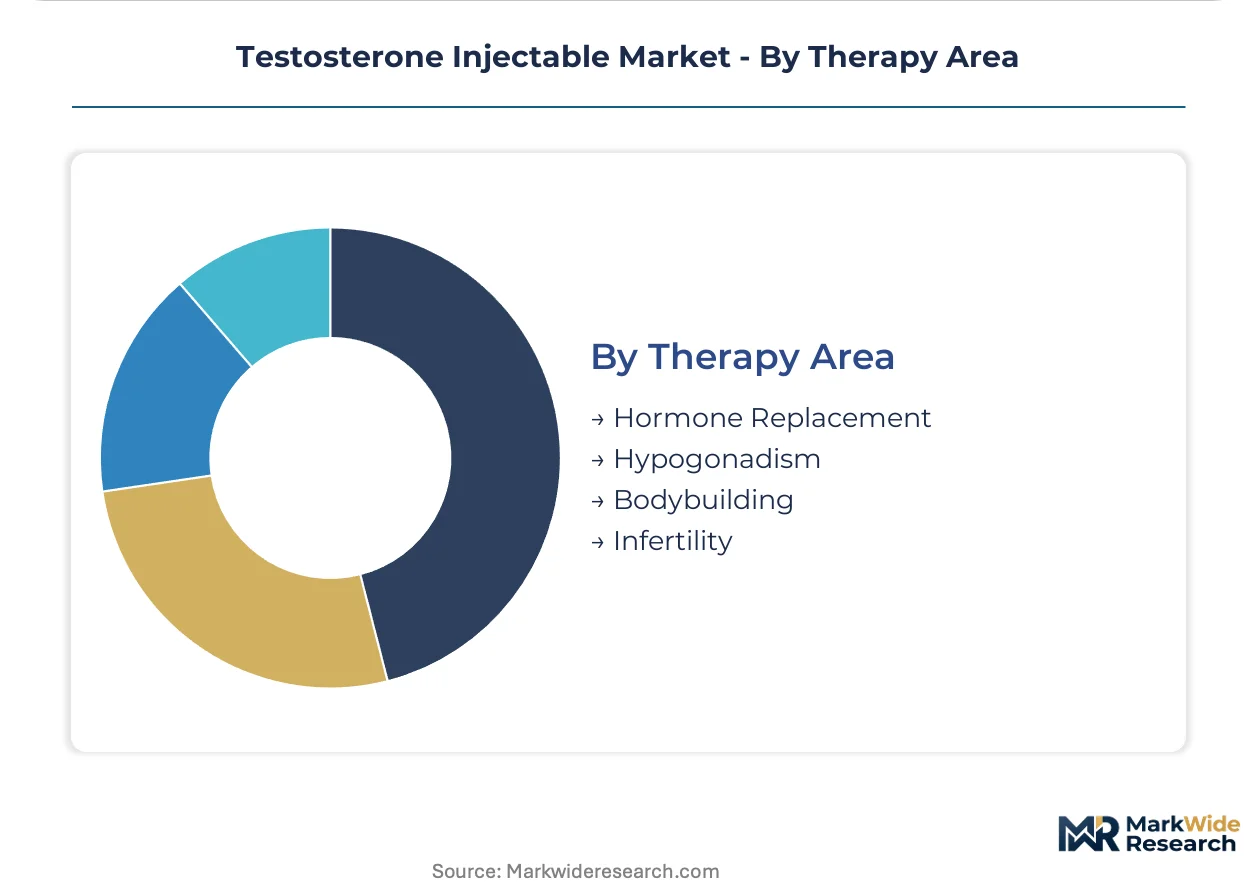
Therapy Area:
Regulatory scrutiny intensity varies sharply across indication types, shaping prescriber liability exposure.
- Hypogonadism:Medically diagnosed testosterone deficiency with established diagnostic criteria. FDA REMS protocols and DEA Schedule III controls concentrate here, elevating pharmacy-based patient support program importance for documentation compliance.
- Hormone Replacement:Broader therapeutic category spanning age-related decline and post-surgical intervention. Men's health clinic expansion is converting latent demand into diagnosed volumes fastest in this segment.
- Bodybuilding:Off-label use for muscle anabolism with elevated regulatory enforcement risk.
- Infertility:Spermatogenesis suppression protocols requiring specialized endocrinology oversight.
Clinical indications anchor legitimacy. Lifestyle applications attract scrutiny.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The testosterone injectable industry traces its commercial origins to mid-20th century pharmaceutical development in the United States, where synthetic ester formulations first achieved regulatory approval and established the therapeutic protocols that now govern hormone replacement therapy worldwide.
United States
Men's health clinic networks in Florida and Texas drive diagnostic volume expansion, converting latent demand into treated hypogonadism cases. FDA REMS protocols and DEA Schedule III controls shape prescribing patterns through mandatory prescriber certification and patient monitoring obligations. Telehealth platforms based in California and New York compress patient acquisition cycles through direct-to-consumer subscription models that bypass traditional clinic gatekeeping.
Germany
EMA pharmacovigilance frameworks align prescriber behavior with centralized safety monitoring requirements for androgen therapies. The Federal Institute for Drugs and Medical Devices (BfArM) enforces national health technology assessments that influence reimbursement negotiations for testosterone formulations. Pharmaceutical manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia concentrate API production and sterile formulation capabilities for European distribution.
United Kingdom
Specialist endocrinology practices in London and the Southeast normalize testosterone deficiency screening through integrated men's health services. The Medicines and Healthcare products Regulatory Agency (MHRA) maintains pharmacovigilance reporting systems that track cardiovascular safety signals across prescribing populations. Regional prescribing variation between NHS trusts creates formulary access disparities that favor established ester formulations with proven cost-effectiveness profiles.
Canada
Provincial health authority formularies in Ontario and Quebec determine reimbursement eligibility for testosterone replacement therapies through centralized drug benefit programs. Health Canada maintains post-market surveillance requirements that align with FDA cardiovascular safety labeling developments. Specialty pharmacy networks in British Columbia and Alberta develop cold-chain distribution infrastructure for oil-based injectable formulations.
Australia
The Therapeutic Goods Administration (TGA) regulates testosterone products as Schedule 4 controlled substances, restricting prescribing to authorized medical practitioners. Men's health clinics in Sydney and Melbourne expand diagnostic capacity through dedicated andrology services. Compounding pharmacy oversight in New South Wales and Victoria creates regulatory friction with standardized pharmaceutical formulations.
Testosterone Injectable Market Competitive Landscape
The competitive structure tilts toward integrated pharmaceutical conglomerates with established hormone therapy portfolios. Market concentration reflects high regulatory barriers to entry and the capital requirements for REMS-compliant distribution infrastructure. Three archetypes dominate: vertically integrated majors controlling API-through-dispensing value chains, specialty pharmaceutical firms concentrating on urology channel relationships, and generic manufacturers competing on price through abbreviated new drug applications. Consolidation through acquisition of men's health platform companies and expansion of specialty pharmacy credentialing networks represent the primary competitive vectors.
Within the integrated pharmaceutical tier, AbbVie Inc. and Pfizer Inc. occupy positions that exemplify divergent strategic approaches to the testosterone injectable segment. AbbVie anchors its market presence through patient support program infrastructure that bundles drug delivery with compliance documentation services. Pfizer sits within the manufacturing scale archetype, leveraging multi-site production capabilities across ester formulation types. Eli Lilly & Company represents the specialty channel relationship model, concentrating prescriber access through urology and endocrinology practice networks rather than broad primary care penetration.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Endo Pharmaceuticals Inc. |
| Pfizer Inc. |
| Bayer AG |
| Eli Lilly & Company |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Amneal Pharmaceuticals Inc. |
| Halozyme Therapeutics Inc. |
| Others |
Value Network & Pricing Analysis
Men's health telehealth platforms and direct-to-consumer subscription services concentrate demand around automated replenishment models that compress patient acquisition costs while elevating lifetime value metrics. This buyer-archetype consolidation enables vendors to deploy subscription-based pricing that locks in adherence and reduces switching behavior.
Pricing Analysis
Three-tier pricing structure across premium autoinjector formats, standard pre-filled syringes, and economy vial-and-syringe configurations dominates the testosterone injectable landscape. Premium differentiation rests on REMS-compliant patient support programs and connected health monitoring, while standard tiers compete on pharmacy network density. Cost compression in the economy segment is intensifying because 503B compounding facilities undercut branded formulations with customized ester blends. Cash-pay patients in direct-to-consumer channels show lowest price sensitivity, whereas insured patients optimizing copayments drive volume toward generic alternatives.
Supply Chain Analysis
Specialty pharmacy channels with DEA Schedule III credentialing and cold-chain infrastructure handle the majority of testosterone injectable distribution. API manufacturing concentrates in the United States, Germany, and India, with sterile formulation capabilities clustering in North Rhine-Westphalia and Baden-Württemberg. Testosterone ester synthesis draws from soybean and cottonseed oil feedstocks, with sesame oil vehicles anchoring European enanthate production. Single-source vulnerability in contract manufacturing for long-acting esters exposes formulations to disruption. Distribution runs through REMS-compliant specialty pharmacies that document prescriber certification and patient monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Testosterone injectable markets present geographic-arbitrage opportunities between the United States, where cash-pay telehealth subscriptions bypass insurance friction, and European markets, where centralized health technology assessments compress reimbursement rates but guarantee volume.
For Market Incumbents: Hedge against compounding pharmacy substitution by deepening integration into patient support programs that document REMS compliance and cardiovascular safety monitoring. Secure captive supply of testosterone ester APIs through backward integration into contract manufacturing relationships. Channel control through specialty pharmacy credentialing networks represents the critical defensive lever against generic erosion. For New Entrants and Emerging Players: Capture underpenetrated access within the Veterans Health Administration and other federal procurement systems that prioritize standardized formularies and centralized purchasing. Veterans Health Administration penetration offers the most penetrable white-space target, with volume contracts that reduce customer acquisition expenditure. A direct-to-patient telehealth platform paired with automated replenishment logistics provides the optimal go-to-market angle. For Investors and Strategic Acquirers: Specialty pharmaceutical firms with urology channel relationships are the most active acquirer in this space, consolidating men's health platform companies to capture prescriber access. Long-term viability hinges on regulatory navigation capabilities spanning FDA REMS protocols and DEA controlled substance frameworks. Watch for cardiovascular safety labeling revisions as the critical inflection signal that could reshape prescriber enthusiasm and patient informed consent economics.| Strategic Initiative | Industry Significance |
|---|---|
| REMS-Compliant Patient Support Program | Specialty pharmacies with documentation infrastructure capture disproportionate dispensing volume from prescriber offices outsourcing compliance burden. |
| Autoinjector Platform Development | Integrated needle-safety mechanisms consolidate patient preference and command premium pricing through reduced injection-site complications. |
| Telehealth Platform Acquisition | Direct-to-consumer subscription models compress patient acquisition cycles and lock in automated replenishment schedules. |
| API Manufacturing Scale-Up | Multi-site production capabilities across testosterone ester formulations reduce single-source disruption exposure. |
| Digital Therapeutics Bundling | Smartphone-based symptom tracking paired with drug delivery differentiates commoditized formulations through outcomes documentation. |
Research Methodology
Direct dialogue with specialty pharmacy operations directors, men's health clinic medical directors, regulatory affairs leads at pharmaceutical manufacturers, and urology practice administrators anchored the qualitative foundation of this study. Secondary validation drew from FDA REMS documentation, DEA controlled substance distribution reports, EMA pharmacovigilance assessments, and hospital formulary databases. Bottom-up prescription volume modeling and top-down market sizing triangulated demand estimates across the analysis window.
Bottom-up demand modeling segmented the market by ester chemistry, administration route, and care setting, while top-down validation cross-referenced against pharmaceutical manufacturer revenue disclosures and specialty pharmacy dispensing data. CAGRs were derived from prescription trend analysis and patient population expansion projections. Modeled inputs included telehealth platform penetration rates, men's health clinic network expansion, and self-administration protocol adoption curves.
Regulatory enforcement shifts, cardiovascular safety labeling revisions, and telehealth prescribing rule changes are the dominant revision risks to forecast assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Hair Supplements Market
Dietary Supplements
Nausea Relief Chews Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Sleep Aid Supplements Market
Dietary Supplements
Eye Care Supplements Market
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Vitamin D Deficiency Treatment Market
Dietary Supplements
Concentrated Angelica Pills Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Medicinal Mushroom Powder Market