
 Bone and Joint Health Supplements Market | 2026-2036
Bone and Joint Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Bone and Joint Health Supplements Market Intelligence
Direct-to-consumer online retail is reconfiguring how bone and joint health supplements reach end users, bypassing traditional pharmacy gatekeepers. GSK-Pfizer leverages its pharmaceutical heritage to anchor credibility in clinical positioning. Herbalife International of America, Inc. competes through personalized nutrition coaching bundled with supplement sales. Bayer AG extends its consumer health footprint by dominating pharmacy shelf space across multiple continents.
Bone and joint health supplements comprise bioactive compounds—glucosamine sulfate, chondroitin sulfate, collagen peptides, and omega-3 fatty acids—formulated to support cartilage integrity, reduce inflammatory markers, and maintain skeletal mineral density in aging or physically stressed populations. Standardized extraction and enzymatic hydrolysis processes determine bioavailability and therapeutic consistency. Glucosamine and chondroitin formulations occupy the mature core of the product portfolio, while collagen segments attract premium positioning due to expanding sports nutrition crossover demand. Gummies and powders within the form dimension outpace tablets in growth velocity as younger demographics and convenience-seeking seniors reshape consumption habits.
The FDA oversees New Dietary Ingredient notifications and Good Manufacturing Practice compliance, while EFSA evaluates permitted health claims under the EU Nutrition and Health Claims Regulation, collectively raising barriers for unsubstantiated joint health assertions. Japan's Consumer Affairs Agency enforces strict functional food labeling through FOSHU and FFC frameworks, shaping export-ready formulation strategies. Stakeholders must monitor evolving pharmacovigilance requirements and substantiation standards as regulators tighten the evidentiary threshold for structural health claims.
Market Dynamics
Regulatory substantiation requirements are compressing formulation timelines as FDA New Dietary Ingredient notifications and EFSA health claim assessments demand clinical evidence packages that smaller manufacturers cannot assemble.
Growth Catalysts
- Germany's aging demographic:The senior population expansion creates concentrated demand for cartilage-support formulations and mineral density maintenance products.
- Enzymatic hydrolysis advances:Improved collagen peptide bioavailability is unlocking sports nutrition crossover applications among younger consumer segments.
- FOSHU framework evolution:Japan's Consumer Affairs Agency functional food labeling system is incentivizing export-ready substantiation investments by international suppliers.
Market Restraints
- Marine collagen supply volatility:Wild-caught fish stock fluctuations and aquaculture disease outbreaks create input cost instability for premium peptide sourcing.
- Clinical trial cost inflation:EFSA's tightening evidentiary standards for joint structure claims now require multi-site human studies that consume 18-24 month development budgets.
- Chondroitin sulfate purity verification:Bovine and porcine sourcing complexity complies with religious dietary restrictions and traceability mandates across Middle Eastern and Southeast Asian import markets.
Strategic Opportunities
- Vietnam pharmacy modernization:Government healthcare infrastructure investments are expanding organized retail channels for premium supplement distribution beyond traditional informal markets.
- Direct-to-consumer subscription models:Personalized dosing algorithms paired with automated replenishment are capturing lifetime value from osteoarthritis management protocols.
- CSRD-aligned sustainability claims:The EU Corporate Sustainability Reporting Directive creates competitive differentiation for marine collagen suppliers with certified traceable supply chains.
Industry Challenges
- Pharmacovigilance talent scarcity:Qualified adverse event reporting specialists command premium compensation as FDA and EMA post-market surveillance requirements intensify.
- Cross-border label harmonization:Divergent permissible health claim language between FDA structure-function rules and EFSA Article 13.1 approvals forces territory-specific packaging runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone and Joint Health Supplements Market |
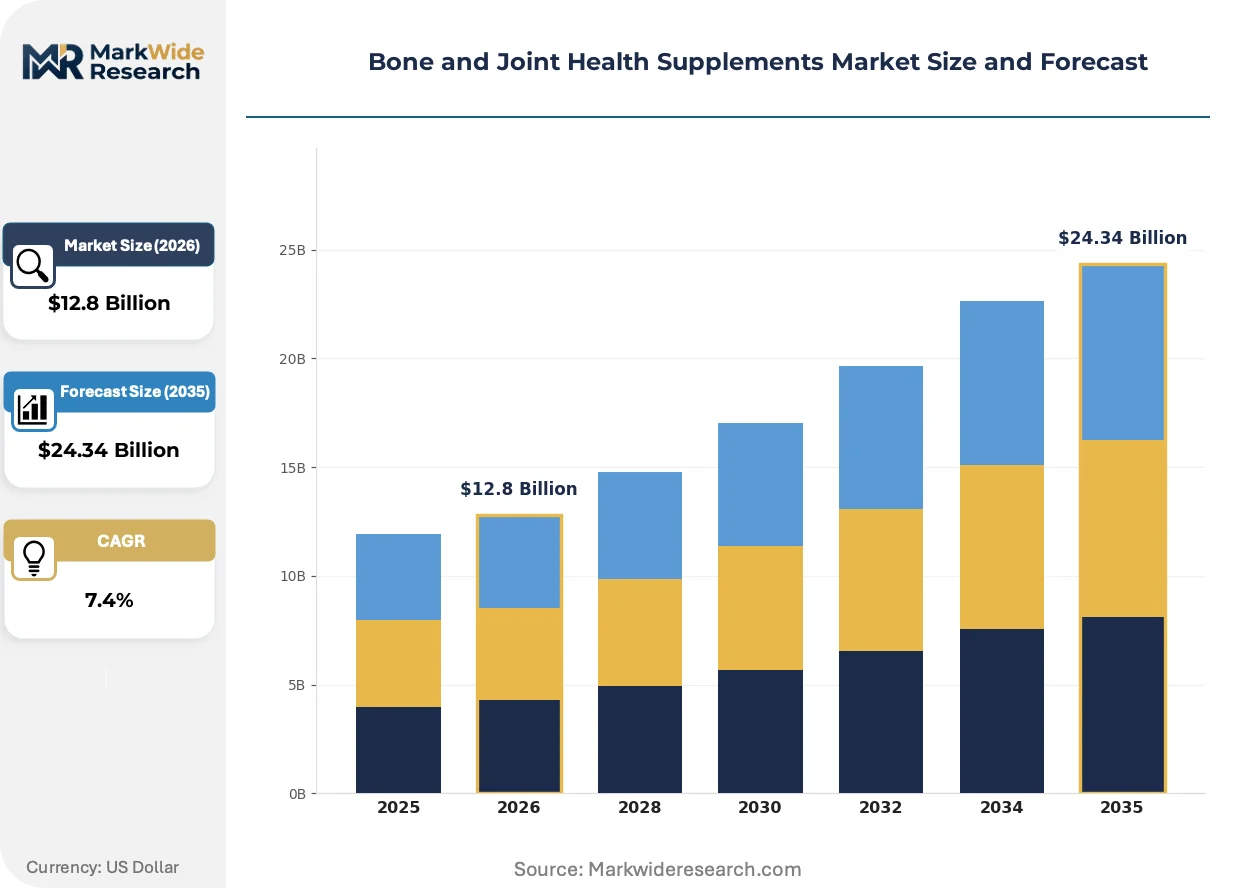
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.34 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucosamine, Chondroitin, Omega-3 Fatty Acids, Collagen Form: Capsules, Tablets, Powders, Gummies End User: Adults, Seniors, Athletes, Patients Distribution Channel: Pharmacies, Online Retail, Supermarkets, Health Stores |
| Companies Covered | GSK-Pfizer, Herbalife International of America, Inc., Nature's Bounty, Nature Made, By-Health Co., Ltd., Bayer AG, GNC Holdings, Schiff Nutrition International, Amway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone and Joint Health Supplements Market Strategic Shifts & Innovations
Formulation science and distribution architecture are undergoing parallel transformation as bioavailability engineering meets channel disintermediation. These shifts are compressing traditional value capture points and rewarding evidence-based positioning.
Microencapsulation technology is digitizing nutrient delivery precision by embedding glucosamine and chondroitin in lipid matrices that bypass gastric degradation. Sports nutrition brands and geriatric-focused startups are adopting these systems at accelerated procurement cycles. The technology is digitizing therapeutic consistency expectations and collapsing batch-to-batch variation tolerance among quality-conscious buyers.
EFSA's evolving Article 13.1 health claim assessments are disqualifying generic joint comfort assertions from product labels across EU member states. Manufacturers must now commission proprietary human intervention studies to retain permissible marketing language. Collagen peptide and undenatured type II collagen categories face the steepest compliance recalibration as existing dossiers fail revised evidentiary thresholds.
Subscription-based replenishment models are displacing pharmacy counter purchasing among convenience-seeking seniors and digitally native athletes. Direct-to-consumer platforms capture purchase data that enables personalized stacking recommendations and dosage optimization. This behavioral pivot is most pronounced in United States metropolitan markets where same-day delivery infrastructure supports adherence-dependent chronic condition management protocols.
Bone and Joint Health Supplements Market Segmentation
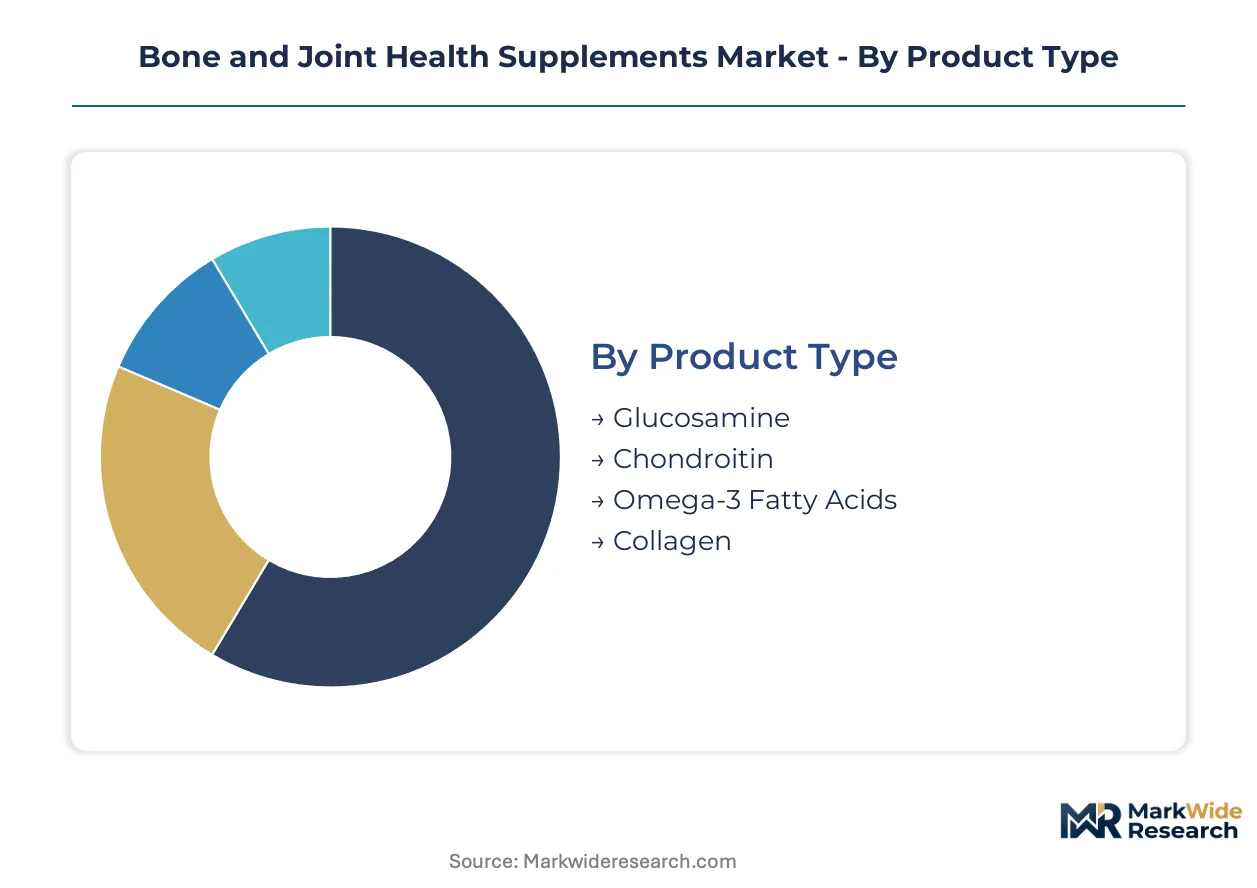
Segmentation in bone and joint health supplements reveals distinct service and loyalty dynamics across product categories. Formulation complexity and consumption frequency determine where manufacturers must invest in customer education and replenishment support.
Product Type:
After-sales intensity varies sharply across compound categories, with collagen peptides requiring the most sustained consumer guidance on dosing protocols and stacking combinations.
- Glucosamine:Sulfate and hydrochloride salts remain the reference standard for osteoarthritis symptom management in clinical and consumer settings. Demand concentrates among Germany's aging demographic seeking cartilage preservation protocols, though EFSA's tightening substantiation requirements now challenge legacy label claims.
- Collagen:Enzymatically hydrolyzed type I and type II peptides command premium positioning through sports nutrition crossover appeal. Athletes in United States metropolitan markets drive fastest adoption, motivated by recovery acceleration claims and influencer-backed education campaigns.
- Chondroitin:Sulfate formulations from bovine and marine sources provide synergistic cartilage matrix support when combined with glucosamine. Purity verification costs and religious dietary compliance complexity constrain margin expansion.
- Omega-3 Fatty Acids:EPA/DHA concentrates deliver anti-inflammatory modulation complementary to structural joint support. Sourcing from wild-caught fisheries and algae cultivation creates supply chain traceability differentiation.
Glucosamine holds the largest share; momentum sits with collagen.
Form:
Manufacturing capital allocation follows consumption occasion patterns, with convenience formats demanding flexible production lines and shorter batch cycles.
- Capsules:Hard gelatin and vegetable-derived shells deliver precise dosing with minimal excipient load. Pharmacy chains in Japan favor this format for FOSHU-compliant functional food positioning.
- Powders:Bulk collagen and glucosamine blends enable personalized dosing and beverage integration. Sports nutrition brands capture share fastest among digitally native athletes seeking stack customization.
- Gummies:Pectin and gelatin matrices mask marine collagen taste profiles for compliance-sensitive seniors. Sugar content and stability challenges elevate formulation expertise barriers.
- Tablets:Compressed granulation remains the cost-optimized default for mass-market glucosamine-chondroitin combinations. Direct-to-consumer subscription models are displacing this format in United States markets.
Tablets dominate current volume; powders are climbing the fastest.
End User:
Customer lifetime value calculations diverge across physiological life stages, with chronic condition management protocols generating recurring revenue against episodic athletic use.
- Seniors:Osteoarthritis prevalence and bone mineral density concerns drive sustained consumption of glucosamine and calcium-vitamin D combinations. Germany and Japan's demographic trajectories concentrate demand for geriatric-focused formulations.
- Athletes:Collagen peptides and anti-inflammatory compounds support connective tissue recovery from repetitive stress. Sports nutrition crossover positioning attracts younger consumers with higher digital engagement.
- Adults:Preventive supplementation among forty-to-sixty-year-olds bridges wellness and clinical positioning. Pharmacy recommendation influence remains strongest in this segment.
- Patients:Post-surgical and diagnosed osteoarthritis populations follow physician-guided protocols with higher compliance requirements. Clinical trial evidence demands elevate product selection criteria.
Seniors command the largest addressable base; athletes show the steepest expansion trajectory.
Distribution Channel:
Channel economics determine margin capture and data access, with direct relationships enabling personalized dosing algorithms and automated replenishment.
- Online Retail:Direct-to-consumer platforms bypass pharmacy gatekeepers to capture purchase behavior data and enable subscription-based adherence programs. Same-day delivery infrastructure in United States metropolitan markets supports chronic condition management protocols.
- Pharmacies:Community and chain dispensaries retain credibility advantage for senior consumers seeking pharmacist consultation. Bayer AG and GSK-Pfizer leverage pharmaceutical heritage to dominate shelf space across multiple continents.
- Health Stores:Specialty retailers curate premium collagen and sports nutrition assortments for enthusiast segments. Staff expertise requirements elevate operating costs relative to mass channels.
- Supermarkets:Mass-market glucosamine and basic multivitamin combinations reach convenience-oriented purchasers. Price competition and private label encroachment compress branded margins.
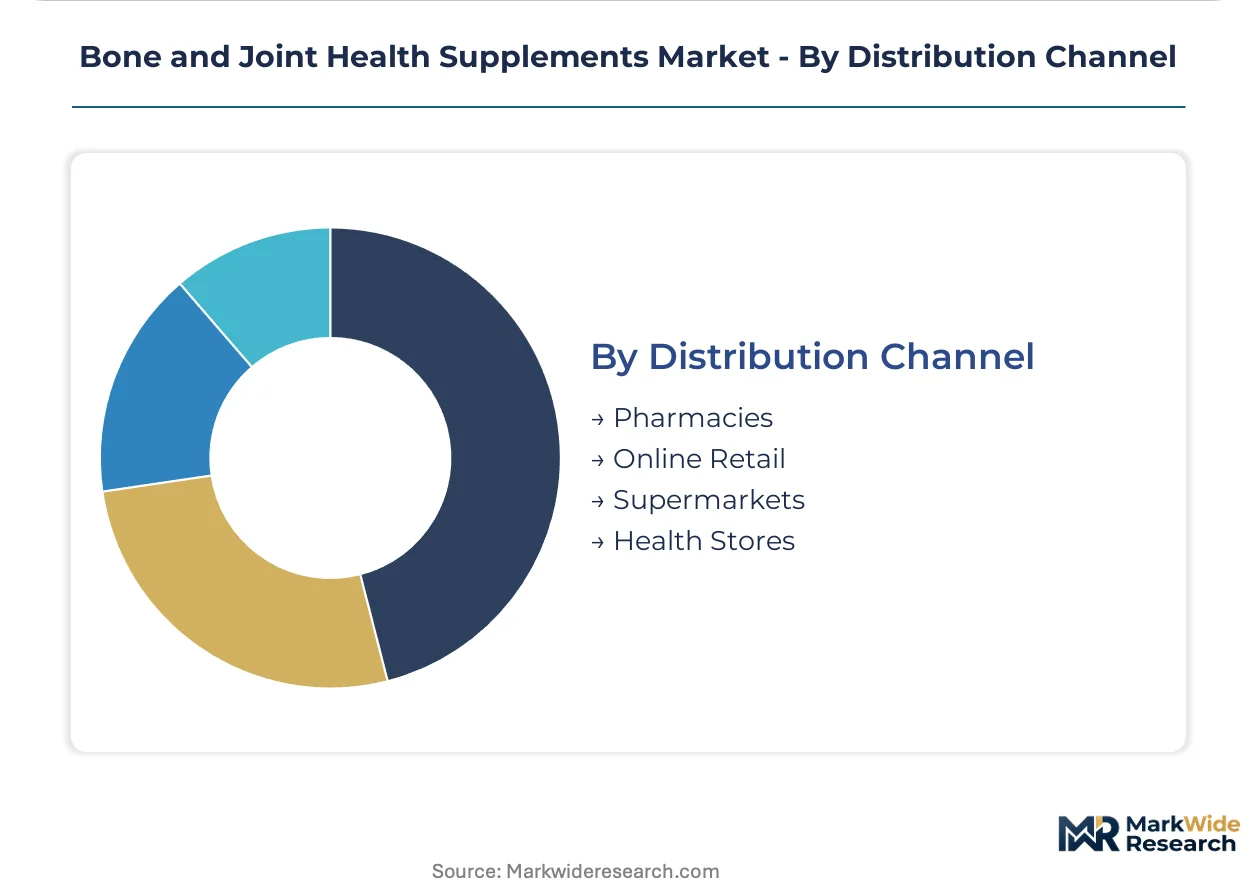
Pharmacies retain volume leadership; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price capture diverges sharply between United States direct-to-consumer channels and Germany's pharmacy-dominated retail, with American platforms extracting 15-20 point premiums through subscription personalization while German OTC shelf competition compresses branded margins.
United States
Metropolitan same-day delivery infrastructure and Medicare Advantage supplemental benefit expansion drive concentrated demand for glucosamine and collagen peptide subscriptions. FDA structure-function claim enforcement under DSHEA shapes permissible marketing language for cartilage support assertions. Silicon Valley wellness startups and Miami-based sports nutrition brands compete for digitally native athletes through influencer-backed education campaigns.
Germany
Accelerating senior demographic expansion and statutory health insurance reimbursement discussions for osteoarthritis management protocols concentrate demand for chondroitin sulfate formulations. EFSA Article 13.1 health claim assessments under EU Nutrition and Health Claims Regulation disqualify generic joint comfort assertions from product labels. Bavarian pharmaceutical manufacturers and North Rhine-Westphalian contract research organizations anchor clinical substantiation investments for export-ready dossiers.
Japan
FOSHU and FFC functional food labeling frameworks incentivize proprietary human intervention studies for collagen peptide positioning. Consumer Affairs Agency enforcement of post-market surveillance requirements elevates pharmacovigilance capability investments. Tokyo-based ingredient suppliers and Osaka pharmaceutical conglomerates dominate domestic pharmacy shelf space while targeting Southeast Asian export markets.
China
Alibaba and JD Health platform penetration into tier-two cities expands direct-to-consumer access for glucosamine and calcium-vitamin D combinations among aging urban populations. SAMR registration requirements for imported dietary supplements create compliance barriers for international suppliers. Zhejiang and Guangdong province contract manufacturers scale enzymatic hydrolysis capacity for marine collagen peptide production.
Vietnam
Government healthcare infrastructure investments modernize pharmacy retail channels beyond traditional informal markets, creating organized distribution pathways for premium supplement brands. Ministry of Health circulars on dietary supplement advertising tighten permissible health claim language. Ho Chi Minh City and Hanoi urban corridors concentrate emerging middle-class preventive supplementation demand.
Bone and Joint Health Supplements Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying bioactive compounds and dosage form technologies. The vendor base stratifies across three tiers: multinational consumer health conglomerates with pharmaceutical heritage, direct-to-consumer wellness platforms with subscription infrastructure, and contract manufacturers with enzymatic hydrolysis capabilities. Dominant competitive moves include M&A to capture vertical formulation expertise and strategic partnerships with sports nutrition influencers to access younger demographics.
Within the pharmaceutical heritage tier, GSK-Pfizer and Bayer AG exemplify credibility-driven positioning through clinical trial investments and pharmacy chain shelf space dominance. Herbalife International of America, Inc. occupies a distinct archetype combining personalized nutrition coaching with supplement distribution infrastructure. These three entities represent contrasting pathways to end-user access: clinical authority, platform-enabled coaching relationships, and mass retail presence.
| Leading Market Players |
|---|
| GSK-Pfizer |
| Herbalife International of America, Inc. |
| Nature's Bounty |
| Nature Made |
| By-Health Co., Ltd. |
| Bayer AG |
| GNC Holdings |
| Schiff Nutrition International |
| Amway |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese enzymatic hydrolysis facilities is compressing collagen peptide spot prices while simultaneously pressuring European contract manufacturers to absorb margin erosion or exit commodity-grade production. This utilization asymmetry between Asian peptide suppliers and Western finishers is reshaping procurement calendars and forcing brand-owners to consolidate supplier relationships around traceability-certified partners.
Pricing Analysis
The customization-premium spread between standard glucosamine-chondroitin tablets and configured collagen peptide stacks now exceeds threefold at wholesale level. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence: marine collagen with FOSHU substantiation commands top tier, bovine-sourced undifferentiated peptides occupy mid-tier, and unverified chondroitin sulfate from mixed animal origins sits at economy level. Price differentiation stems from EFSA dossier investment requirements and vertical integration into aquaculture sourcing. Cost compression in economy-tier chondroitin is intensifying because Middle Eastern import traceability mandates have elevated laboratory verification costs. Seniors purchasing through German pharmacy channels exhibit highest price sensitivity; sports nutrition enthusiasts in United States metropolitan markets show lowest elasticity due to influencer-mediated quality signaling.
Supply Chain Analysis
Contract-manufacturing concentration sits with Zhejiang and Guangdong province enzymatic hydrolysis specialists controlling marine collagen peptide capacity, while Bavarian and North Rhine-Westphalian finishers dominate European glucosamine tablet production. Geographic supply concentration centers on China for raw peptide inputs, Germany for pharmaceutical-grade finishing, and Vietnam for emerging encapsulation capacity. Raw material dependencies draw from wild-caught Alaskan pollock stocks, aquaculture-raised tilapia byproduct streams, and bovine trachea sourced from Brazilian and Argentine abattoirs. Single-source vulnerability runs through Japanese FOSHU-certified collagen suppliers given Consumer Affairs Agency post-market surveillance requirements that foreign manufacturers struggle to satisfy. Distribution runs through direct-to-consumer subscription platforms in United States markets and pharmacy chain procurement committees in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a defensive-moat story anchored in regulatory entrenchment: EFSA Article 13.1 dossier requirements and FDA New Dietary Ingredient notification standards create decade-long recertification barriers that freeze competitive dynamics.
For Market Incumbents: Build certification moats through proprietary human intervention studies that satisfy revised EFSA evidentiary thresholds for collagen peptide structure claims. Deepen backward integration into aquaculture sourcing to isolate from wild-caught fish stock volatility. Channel control through pharmacy chain exclusive distribution agreements in Germany and Japan defends against direct-to-consumer platform erosion. R&D investment in microencapsulation technology creates differentiation from commodity tablet competitors. For New Entrants and Emerging Players: Vietnam pharmacy modernization represents the most penetrable entry point for premium supplement brands seeking organized retail expansion beyond saturated United States and German markets. Preventive supplementation among forty-to-sixty-year-old adults in Chinese tier-two cities offers secondary white-space given Alibaba platform penetration gaps relative to tier-one saturation. Go-to-market angle should emphasize CSRD-aligned sustainability claims with certified traceable marine collagen supply chains to differentiate from incumbent commodity positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic hydrolysis capacity expansion due to pharmaceutical-grade cleanroom requirements and FOSHU-compliant quality systems. Long-term viability over the projection horizon favors contract manufacturers with captive peptide sourcing and established regulatory dossier libraries. Acquisition target archetype: mid-cap enzymatic hydrolysis specialists with existing EFSA or FOSHU certifications and underutilized capacity in Vietnam or Indonesia. Signal to watch: Consumer Affairs Agency enforcement actions against foreign suppliers failing post-market surveillance requirements, which would accelerate consolidation toward compliant incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Substantiation Investment | Proprietary human intervention studies satisfy EFSA Article 13.1 revised thresholds for collagen peptide claims. |
| Backward Integration into Aquaculture | Captive marine collagen sourcing isolates from wild-caught fish stock volatility and disease outbreak disruptions. |
| Direct-to-Consumer Platform Launch | Subscription algorithms capture lifetime value from osteoarthritis management protocols in United States metropolitan markets. |
| FOSHU Certification Pathway | Japan Consumer Affairs Agency approval unlocks premium positioning and Southeast Asian export market access. |
| Microencapsulation Technology Adoption | Lipid matrix delivery systems bypass gastric degradation to improve glucosamine bioavailability for quality-conscious buyers. |
Research Approach
Cross-validation between regulatory filing databases and trade flow records anchors the qualitative findings on formulation substantiation requirements. Primary interviews with regulatory affairs directors at consumer health conglomerates, pharmacovigilance specialists at contract research organizations, and pharmacy chain category buyers informed competitive positioning dynamics. Secondary validation draws from FDA New Dietary Ingredient notifications, EFSA Article 13.1 health claim assessments, Japan Consumer Affairs Agency FOSHU registrations, and SAMR dietary supplement filings. Bottom-up demand modeling across end-user segments triangulates against top-down market sizing from customs peptide import data.
Calibration against historical capacity utilization rates at enzymatic hydrolysis facilities and pharmacy inventory turnover metrics ensures forecast consistency across the analysis window. Segmentation dimensions modeled include product type compound categories, form factor convenience tiers, end-user physiological life stages, and distribution channel economics. CAGRs derive from trend extrapolation of aging demographic trajectories in Germany and Japan, sports nutrition crossover adoption curves in United States metropolitan markets, and regulatory timeline compression effects on formulation launch cadences. Industry-specific inputs incorporate FOSHU approval queue lengths and EFSA dossier rejection rates.
Macroeconomic conditions sit as an overlay; deviation in senior disposable income indices or marine collagen input cost volatility would shift the trajectory. Forecasts assume continued FDA structure-function enforcement stability and no relaxation of EFSA substantiation standards. Quarterly review of Consumer Affairs Agency enforcement actions and enzymatic hydrolysis capacity utilization reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Pet Herbal Supplements Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Medicated Confectionery Market
Dietary Supplements
Sleep Aid Supplements Market
Dietary Supplements
Global Nicotine Lozenges Market
Dietary Supplements
Menopause Supplement Market
Dietary Supplements
Global Oral Electrolyte Solutions Market
Dietary Supplements
Folic Acid Tablets Market
Dietary Supplements
Lifestyle-Related Disease Supplements Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Serotonin Supplement Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Canine Weight Loss Drugs Market
Dietary Supplements
Glucosamine Salt Market