
 Cardiovascular Health Supplements Market | 2026-2036
Cardiovascular Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Health Supplements Market Analytics
Asset-light contract manufacturing and third-party logistics financing is narrowing the capital threshold for mid-tier brands to achieve national distribution. Nordic Naturals leverages its Alaskan fishery partnerships to sustain omega-3 supply chain control across North America. Thorne competes through practitioner-exclusive channels that anchor clinical credibility and premium positioning. GNC Holdings extends its retail footprint through franchise models that occupy mall and strip-mall real estate without direct capital deployment.
Cardiovascular health supplements encompass orally administered bioactive compounds formulated to support circulatory function, lipid metabolism, and endothelial health, typically standardized to contain specified concentrations of EPA/DHA, ubiquinone, or allicin. These products serve both preventive wellness consumers and clinically managed populations seeking adjuvant nutritional support for hypertension, hyperlipidemia, and congestive heart failure. Omega-3 formulations dominate value generation due to prescription-adjacent positioning and pharmaceutical-grade certification requirements that concentrate margin pools. Home users represent the fastest-expanding end-user segment as telehealth platforms and wearable biometric devices enable self-directed cardiovascular monitoring. Powders and liquids are gaining shelf space in functional beverage and personalized nutrition formats.
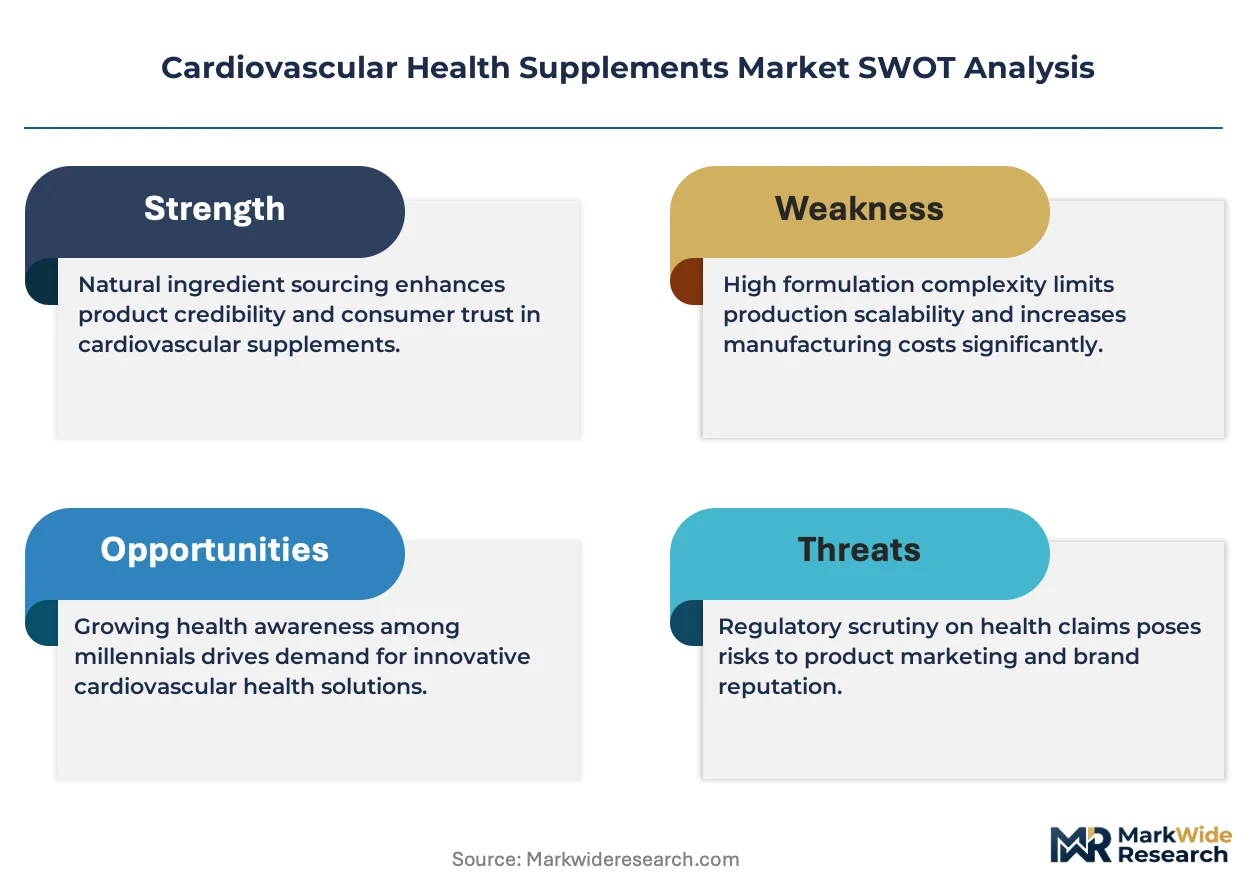
The FDA's Current Good Manufacturing Practice regulations and NDI notification requirements shape product development timelines and deter speculative entrants lacking analytical chemistry capabilities. EFSA health claim authorization processes in Europe constrain marketing language and necessitate dossier investment for omega-3 and CoQ10 positioning. Stakeholders must monitor evolving pharmacovigilance frameworks that could reclassify high-dose cardiovascular supplements as therapeutic products requiring prescription pathways.
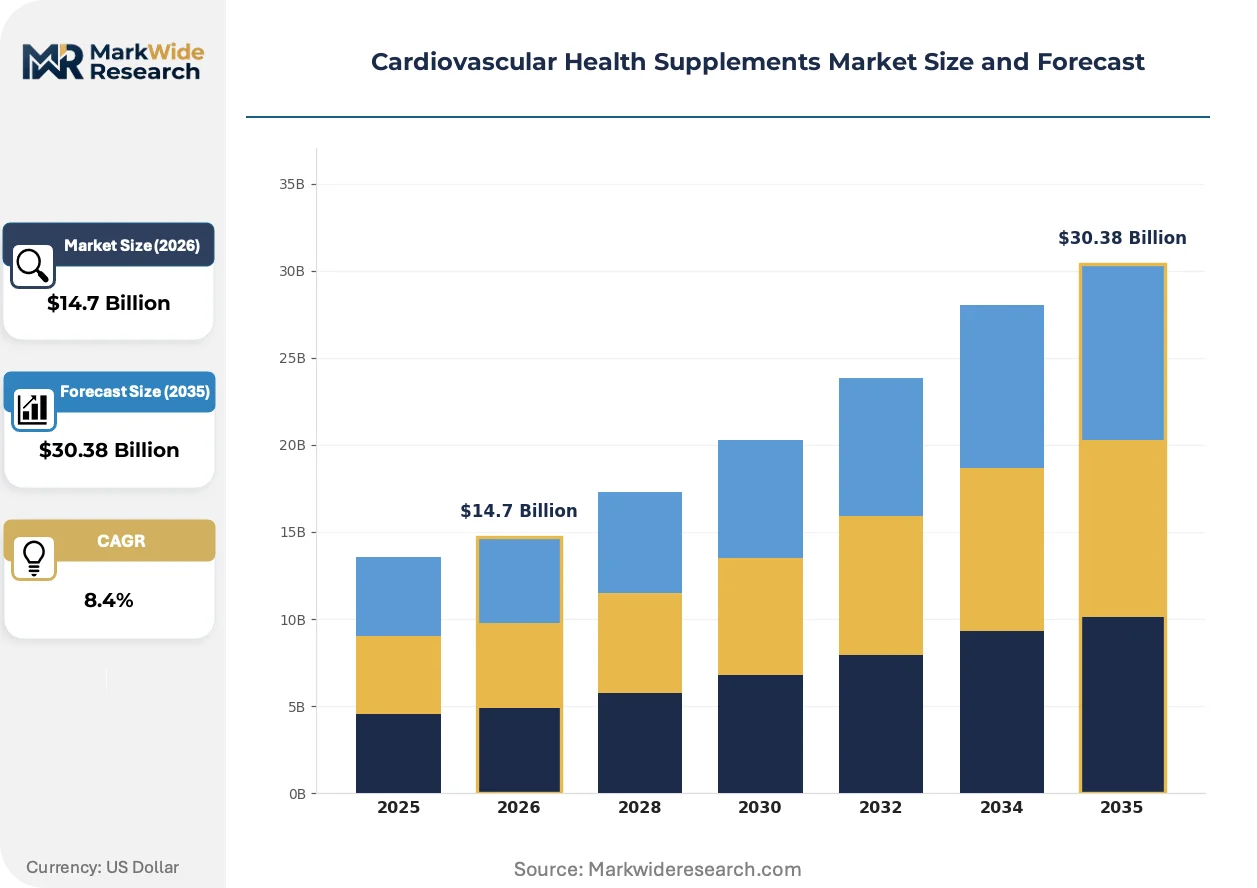
Market Dynamics
Telehealth platforms and wearable biometric devices are reconfiguring how consumers monitor cardiovascular markers, shifting purchasing decisions from pharmacy counters toward algorithm-driven subscription models that bundle supplements with real-time health data.
Growth Catalysts
- FDA's Current Good Manufacturing Practice regulations:Pharmaceutical-grade certification requirements for omega-3 concentrates are concentrating margin pools among analytical chemistry-capable manufacturers, elevating barrier-protected revenue streams.
- Germany's aging demographic profile:Preventive cardiology demand among consumers over 65 is expanding the addressable base for CoQ10 and allicin formulations through pharmacy and practitioner channels.
- Alaskan fishery traceability systems:Blockchain-enabled supply chain verification is enabling premium positioning for wild-caught EPA/DHA sources, differentiating against aquaculture-derived alternatives.
Market Restraints
- Anchovy and sardine biomass volatility:Peruvian and Chilean fishery quotas drive raw material cost swings that compress blender margins during El Niño cycles.
- EFSA health claim authorization timelines:The 18-24 month dossier review process for omega-3 cardiovascular claims constrains marketing velocity and ties up regulatory capital.
- Prescription-strength omega-3 displacement:FDA-approved icosapent ethyl formulations are capturing high-risk patient segments previously served by high-dose dietary supplements.
Strategic Opportunities
- Japan's functional foods regulatory pathway:Foods with Specified Health Uses certification enables cardiovascular positioning in conventional retail formats beyond supplement aisles.
- Personalized nutrition platforms:Integration of pharmacogenomic testing with lipid panel data is creating bespoke EPA/DHA dosing protocols that command subscription pricing.
- Clinical nutrition partnerships:Hospital discharge protocols for congestive heart failure patients are opening institutional procurement channels previously dominated by enteral feeding products.
Industry Challenges
- Analytical chemistry talent scarcity:NDI notification requirements demand mass spectrometry and chromatography expertise that mid-tier brands struggle to recruit at competitive compensation.
- Legacy ERP integration friction:Track-and-trace mandates for supply chain transparency require reconfiguration of inventory management systems originally architected for commodity botanicals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Health Supplements Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.38 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Omega-3, Coenzyme Q10, Garlic Extract, Fiber Supplements Delivery Mode: Capsules, Tablets, Powders, Liquid End User: Clinics, Wellness Centers, Home Users, Hospitals Ingredient Source: Natural, Synthetic, Herbal, Animal-Based |
| Companies Covered | NOW Foods, Nordic Naturals, Thorne, Nestlé Health Science, Amway, GNC Holdings, Pfizer Inc., Bayer AG, Herbalife Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Health Supplements Market Evolving Landscape
Digital biomarker integration and pharmaceutical-grade manufacturing standards are elevating cardiovascular supplements from commodity botanicals toward clinically validated adjunct therapies, compressing the historical separation between wellness and medical nutrition.
Artificial intelligence-driven formulation platforms are virtualizing the traditional R&D pipeline for cardiovascular bioactives. Startups and mid-tier brands now deploy machine learning models to predict EPA/DHA bioavailability across delivery formats, compressing development cycles from 24 months to under 12. The technology is virtualizing capital allocation decisions that previously required dedicated analytical chemistry laboratories.
The European Food Safety Authority's tightened substantiation requirements for cardiovascular health claims are forcing dossier investment toward human intervention trials. Manufacturers must now generate peer-reviewed endpoint data rather than relying on ingredient-level meta-analyses, raising compliance costs but creating defensible positioning against unsubstantiated competitors. Omega-3 and CoQ10 categories face the steepest evidentiary burden under this framework.
Subscription-based replenishment models are displacing retail replenishment cycles for cardiovascular supplements. Direct-to-consumer platforms leverage continuous glucose monitor and blood pressure wearable data to trigger automated reorder algorithms, locking in 90-day supply commitments. This behavioral shift is most visible among hypertensive consumers in the United States who integrate supplement adherence with telehealth medication management protocols.
Cardiovascular Health Supplements Market Segmentation
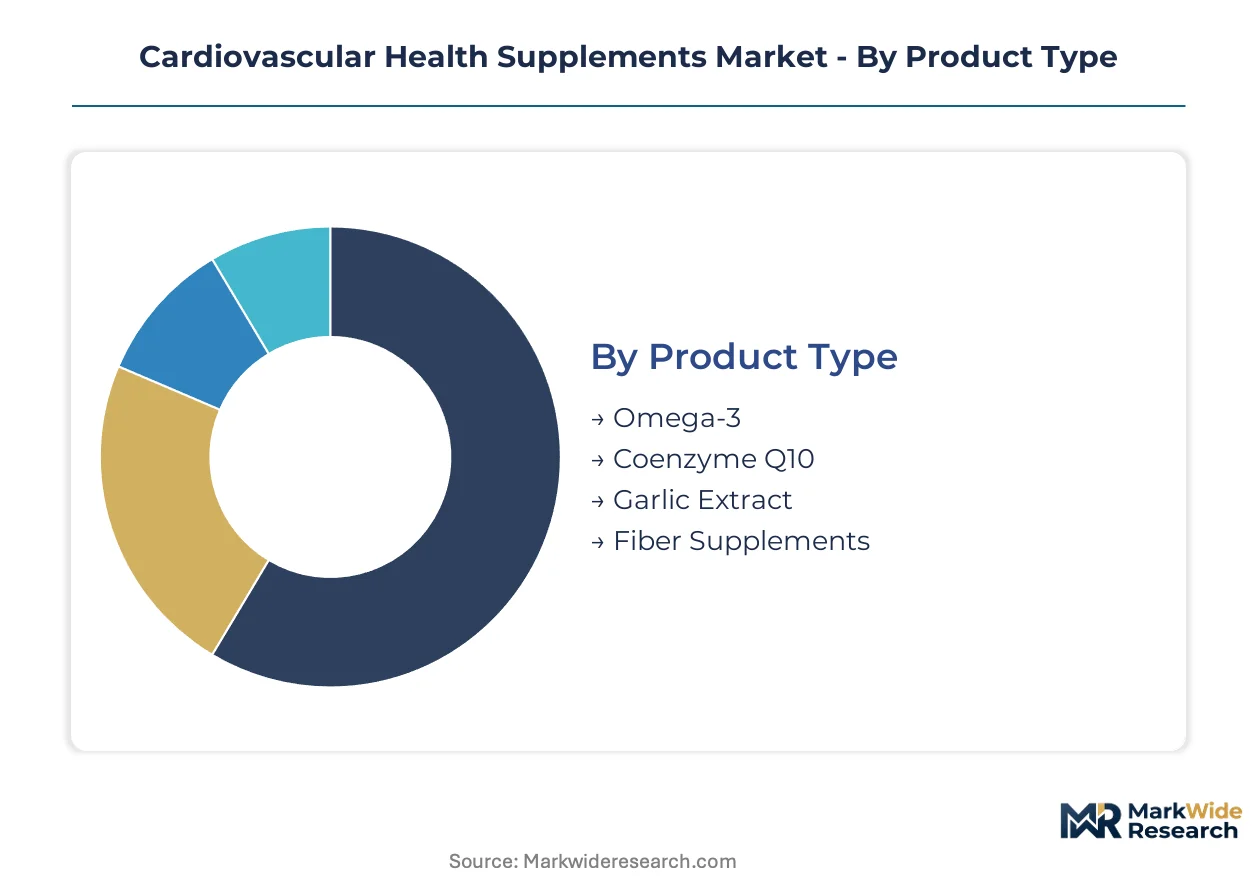
Cardiovascular supplement purchasing patterns fragment sharply across delivery preferences and clinical versus self-directed use cases. Cycle times vary from monthly replenishment for home users to quarterly institutional procurement for hospital systems.
Product Type:
Inventory velocity diverges dramatically between prescription-adjacent omega-3 concentrates and botanical extracts with longer trial periods.
- Omega-3:EPA/DHA concentrates standardized to pharmaceutical-grade specifications dominate value pools due to Lovaza-adjacent positioning. Demand concentrates among hypertensive consumers in the United States integrating supplementation with telehealth lipid management protocols.
- Coenzyme Q10:Ubiquinone and ubiquinol formulations target statin-associated myalgia patients seeking mitochondrial support. German pharmacy channels drive volume for this segment as aging demographics expand preventive cardiology adoption.
- Garlic Extract:Allicin-standardized preparations serve mild hyperlipidemia patients preferring botanical alternatives to synthetic actives.
- Fiber Supplements:Psyllium and beta-glucan formulations occupy the cholesterol management adjacency with lower per-unit pricing.
Omega-3 anchors the volume base while Coenzyme Q10 gains share at the steepest rate.
Delivery Mode:
Cost tiers separate premium liquid emulsions from commodity tablet formats, with powder intermediates capturing functional beverage integration.
- Capsules:Softgel and hard-shell formats dominate omega-3 delivery due to oxygen barrier properties preserving EPA/DHA integrity. Home users in the United States drive demand through subscription replenishment models bundling 90-day supplies.
- Powders:Bulk formats enable personalized dosing protocols and functional beverage integration. Wellness centers leverage powder flexibility for compounded cardiovascular stacks targeting lipid panel optimization.
- Tablets:Compressed formats serve price-sensitive segments and institutional procurement channels with extended shelf stability.
- Liquid:Emulsified preparations improve bioavailability for pediatric and geriatric populations with swallowing difficulties.
Capsules retain the largest installed base while powders expand most quickly through personalized nutrition platforms.
End User:
Customer type determines margin structure, with clinical channels commanding premium pricing and home users driving volume scale.
- Home Users:Self-directed consumers leveraging wearable biometric data and telehealth platforms represent the fastest-expanding addressable base. Algorithm-driven subscription models lock in recurring revenue through blood pressure monitor integration.
- Hospitals:Institutional procurement for congestive heart failure discharge protocols opens channels previously reserved for enteral nutrition products. Clinical nutrition partnerships require pharmaceutical-grade documentation and lot-level traceability.
- Clinics:Practitioner-exclusive channels anchor premium positioning through diagnostic integration and protocol-driven recommendations.
- Wellness Centers:Preventive cardiology programs bundle supplementation with biometric screening and lifestyle coaching services.
Home users generate the volume base while hospitals unlock the steepest expansion trajectory through discharge protocol integration.
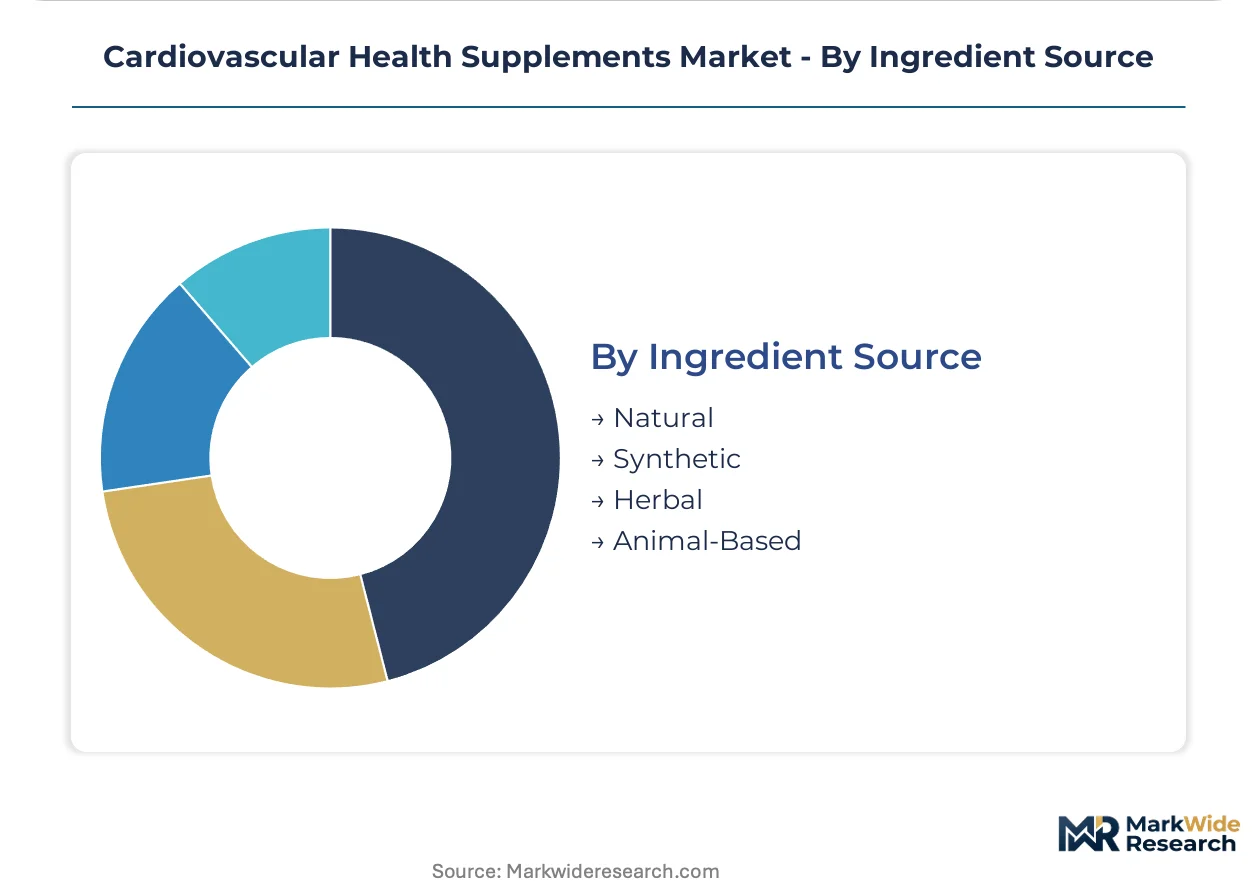
Ingredient Source:
Supply concentration and certification burden vary sharply across wild-caught marine, cultivated botanical, and synthetic fermentation origins.
- Natural:Wild-caught Alaskan fish oil and plant-derived phytosterols command premium positioning through blockchain-enabled traceability systems. EFSA health claim authorization requirements favor natural-source dossiers with established safety profiles.
- Synthetic:Fermentation-derived CoQ10 and molecularly distilled omega-3 concentrates enable pharmaceutical-grade purity specifications. FDA Current Good Manufacturing Practice regulations elevate analytical chemistry barriers that synthetic-capable manufacturers navigate more efficiently.
- Herbal:Garlic, hawthorn, and red yeast rice extracts serve traditional medicine-adjacent consumer segments in Asia-Pacific markets.
- Animal-Based:Marine and bovine-derived actives face sustainability scrutiny and religious dietary restriction limitations.
Natural sources anchor volume through premium positioning while synthetic alternatives gain share fastest via pharmaceutical-grade certification pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for omega-3 concentrates tilts the trade balance toward Peru and Chile for anchovy biomass, while finished supplement exports flow from US and German manufacturing hubs toward Asian markets seeking pharmaceutical-grade certification.
United States
Telehealth lipid management protocols and wearable blood pressure monitor integration are driving subscription replenishment demand. FDA Current Good Manufacturing Practice regulations elevate analytical chemistry barriers that concentrate manufacturing among certified facilities. The Boston-Cambridge corridor anchors clinical nutrition partnerships with hospital discharge protocols for congestive heart failure patients.
Germany
Preventive cardiology adoption among consumers over 65 is expanding pharmacy channel demand for CoQ10 and allicin formulations. EFSA health claim authorization timelines constrain marketing velocity for omega-3 cardiovascular positioning. The Frankfurt-Rhine-Main region concentrates practitioner-exclusive distribution networks serving statin-associated myalgia patients.
Japan
Functional foods regulatory pathways through Foods with Specified Health Uses certification enable cardiovascular positioning in conventional retail formats. METI standards for aging population health management support preventive supplement adoption. The Kanto region around Tokyo drives volume for clinically validated EPA/DHA formulations targeting metabolic syndrome management.
China
Domestic fermentation capacity for synthetic CoQ10 is displacing import dependence while NMPA pharmaceutical-grade standards reshape quality expectations. SAMR dual carbon goals pressure marine-derived omega-3 sourcing toward sustainable alternatives. The Yangtze River Delta clusters contract manufacturing capacity serving both domestic consumption and export markets.
Australia
TGA complementary medicine regulations create a pathway for cardiovascular supplements with evidence-based positioning between food and pharmaceutical categories. Pharmacogenomic testing integration with personalized nutrition platforms is emerging through Sydney-Melbourne health tech corridors. Wild-caught fish oil traceability systems from Tasmanian fisheries support premium export positioning toward Asian markets.
Cardiovascular Health Supplements Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with supply chain control or clinical credibility anchoring their positions. The market structures around three tiers: pharmaceutical-grade manufacturers with analytical chemistry capabilities, practitioner-channel brands with diagnostic integration, and retail-scale distributors with franchise footprint expansion. Strategic moves concentrate on clinical nutrition partnership formation and subscription platform acquisition to lock in recurring revenue streams.
Within the clinical-credibility tier, Thorne and Nordic Naturals exemplify divergent anchoring strategies—one through practitioner-exclusive channels, the other through Alaskan fishery supply chain control—while Nestlé Health Science occupies a position spanning pharmaceutical adjacency and institutional nutrition procurement. NOW Foods and GNC Holdings represent contrasting scale archetypes: direct manufacturing capability against retail franchise distribution without capital-intensive real estate deployment. Pfizer Inc. and Bayer AG sit within the pharmaceutical-grade certification vector where prescription-adjacent positioning concentrates margin pools.
| Leading Market Players |
|---|
| NOW Foods |
| Nordic Naturals |
| Thorne |
| Nestlé Health Science |
| Amway |
| GNC Holdings |
| Pfizer Inc. |
| Bayer AG |
| Herbalife Nutrition |
| Others |
Value Network & Pricing Analysis
Peruvian anchovy biomass volatility under pharmaceutical-grade omega-3 certification requirements determines both three-tier pricing stratification across premium, standard, and economy levels and the geographic shape of marine oil sourcing networks.
Pricing Analysis
Home users anchoring subscription replenishment models drive pharmaceutical-grade EPA/DHA concentrates toward premium positioning against commodity tablet formats. Price differentiation centers on FDA Current Good Manufacturing Practice certification tier and Alaskan fishery traceability systems. Cost compression in standard-grade softgels is intensifying because El Niño-driven raw material swings compress blender margins. Institutional procurement channels demonstrate lowest price sensitivity while direct-to-consumer home users exhibit highest elasticity.
Supply Chain Analysis
Anchovy and sardine biomass from Peru and Chile feeds into molecular distillation facilities across the United States and Germany. Supply chains rest on wild-caught marine oil, synthetic fermentation-derived CoQ10, and botanical garlic extracts from Asia-Pacific cultivation zones. Single-source vulnerability concentrates in Peruvian fishery quota allocations. Distribution runs through practitioner-exclusive channels, direct-to-consumer subscription platforms, and hospital discharge protocol procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemistry capabilities for mass spectrometry and chromatography expertise sit as the binding constraint separating pharmaceutical-grade manufacturers from commodity blenders.
For Market Incumbents: Pre-empt displacement from prescription-strength omega-3 formulations by deepening captive supply of Alaskan fishery partnerships and accelerating FDA New Dietary Ingredient notification dossier investment. Anchor clinical credibility through practitioner-channel control before telehealth platforms consolidate algorithm-driven subscription routing. For New Entrants and Emerging Players: Hospital discharge protocols for congestive heart failure patients represent the most penetrable entry point, bypassing entrenched retail shelf competition. Target clinical nutrition partnerships requiring pharmaceutical-grade documentation as the go-to-market angle, leveraging third-party logistics financing to narrow capital thresholds. For Investors and Strategic Acquirers: The market sits at a certification-concentration phase that favors analytical chemistry-capable mid-tier brands with existing NDI notification expertise. Long-term viability hinges on acquiring manufacturers with demonstrated FDA Current Good Manufacturing Practice compliance and blockchain-enabled supply chain verification infrastructure. Watch EFSA health claim authorization timelines as the inflection signal for European marketing velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Nutrition Partnership Formation | Hospital discharge protocols for congestive heart failure patients unlock institutional procurement channels previously reserved for enteral feeding products. |
| Blockchain-Enabled Traceability Investment | Alaskan fishery verification systems differentiate wild-caught EPA/DHA sources against aquaculture-derived alternatives in premium positioning. |
| Practitioner-Exclusive Channel Acquisition | Diagnostic integration and protocol-driven recommendations anchor premium pricing against retail-scale commodity competition. |
| Pharmaceutical-Grade Certification Pathway | FDA Current Good Manufacturing Practice compliance elevates barrier-protected revenue streams among analytical chemistry-capable manufacturers. |
| Subscription Platform Integration | Wearable biometric data triggers automated reorder algorithms locking in recurring revenue through blood pressure monitor integration. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with regulatory affairs leads at dietary supplement manufacturers, clinical nutrition directors at hospital systems, pharmacy procurement managers, and practitioner-channel sales executives; and secondary validation through FDA New Dietary Ingredient notifications, EFSA health claim authorization dossiers, fishery quota records from Peruvian and Chilean maritime authorities, and SEC filings from publicly traded supplement companies. Bottom-up volume modeling across product type, delivery mode, end user, and ingredient source segments triangulated against top-down market sizing.
Forecast inputs span the projection horizon through segmented demand modeling across omega-3 concentrates, Coenzyme Q10 formulations, garlic extracts, and fiber supplements by delivery format and clinical versus self-directed use case. CAGRs were derived from regression analysis of historical pharmaceutical-grade certification adoption rates, telehealth platform penetration curves, and aging demographic expansion patterns in Germany and Japan.
Macroeconomic conditions sit as an overlay; deviation in anchovy biomass yields, El Niño cycle intensity, or FDA enforcement posture on Current Good Manufacturing Practice compliance would shift the trajectory. Cross-checking against hospital discharge protocol adoption rates and wearable biometric device shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Herbal Tincture Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Glucosamine Supplements Market
Dietary Supplements
Nausea Relief Chews Market
Dietary Supplements
Postpartum Health Supplements Market
Dietary Supplements
Menopause Supplement Market
Dietary Supplements
Mediterranean Mood and Stress Support Complexes Market
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Detox Products Market
Dietary Supplements
Womens Health and Beauty Supplements Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Diabetic Food Market
Dietary Supplements
Medicated Confectionery Market
Dietary Supplements
Colostrum Chewable Tablets Market