
 Hair Loss Supplement Market | 2026-2036
Hair Loss Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Loss Supplement Market Insights
North American contract manufacturers is rebalancing capacity toward high-potency biotin and saw palmetto complexes as brand demand outstrips legacy output. Nutrafol leverages physician endorsement networks to sustain premium positioning in the direct-to-consumer channel. Viviscal anchors its European presence through pharmacy-exclusive distribution that controls professional recommendation flow. Unilever competes via mass-market scale that extends shelf access across supermarket and hypermarket formats in emerging economies.
Hair loss supplements comprise orally administered or topically applied formulations containing vitamins, minerals, amino acids, and botanical extracts designed to modulate follicular cycling and reduce telogen effluvium. These products function by addressing nutritional deficiencies, inhibiting dihydrotestosterone conversion, or improving scalp microcirculation to support anagen phase retention. Pills and gummies currently dominate volume due to convenience-driven compliance among working-age consumers, while topical solutions capture margin pools through higher per-unit pricing and dermatologist channel positioning. The ingredient dimension shows herbal extracts gaining formulation share as consumers seek alternatives to synthetic compounds, though vitamin-based SKUs maintain baseline demand through established clinical familiarity.
The FDA's dietary supplement CGMP regulations in the United States, EFSA health claim assessments in Europe, and China's SAMR blue-hat registration requirements collectively shape product development timelines and market access costs. Compliance with these frameworks demands substantiated safety documentation and, in some jurisdictions, pre-market notification that filters out undercapitalized entrants. Stakeholders must monitor evolving substantiation standards for structure-function claims as regulatory scrutiny intensifies across major consumption markets.
Market Dynamics
Preventive hair care normalization among men aged 25-45 is compressing the traditional reactive treatment window and forcing manufacturers to reposition formulations upstream in the consumer lifecycle. This demographic shift is accelerating SKU proliferation across gummy and softgel formats that prioritize convenience compliance over clinical dosing precision.
Growth Catalysts
- Physician endorsement networks:Dermatologist channel validation is elevating perceived efficacy above cosmetic positioning. Professional recommendation flows now determine premium tier access in direct-to-consumer channels.
- CGMP enforcement thresholds:FDA quality mandates in the United States are filtering undercapitalized entrants and consolidating shelf access among substantiated brands. Compliance documentation has become a competitive moat.
- Saw palmetto complex demand:Botanical DHT inhibition claims are capturing formulation share from synthetic alternatives. Contract manufacturers are rebalancing capacity toward high-potency herbal extraction.
Market Restraints
- Raw material concentration:Saw palmetto berry supply concentrates in Florida and Georgia harvest zones. Climate volatility in these regions introduces input cost instability.
- EFSA substantiation friction:European health claim assessments demand clinical trial investment that mid-tier brands cannot fund. Market access costs in Germany and France have doubled for unproven entrants.
- Topical solution substitution:Minoxidil formulations retain dermatologist preference for advanced androgenetic alopecia. Oral supplement positioning struggles to displace established pharmaceutical protocols.
Strategic Opportunities
- China SAMR blue-hat registration:Pre-market notification requirements create first-mover advantages for compliant entrants. Urban pharmacy chains in Shanghai and Beijing prioritize clinically positioned nutraceuticals.
- Subscription model penetration:Auto-replenishment platforms are capturing recurring revenue from working-age compliance seekers. Direct-to-consumer channels bypass traditional retail margin stacking.
- Scalp microbiome convergence:Probiotic and prebiotic ingredient combinations are emerging as differentiation vectors. Formulation science is migrating from systemic nutrition toward targeted follicular environment modulation.
Industry Challenges
- Clinical substantiation talent scarcity:Trichology research specialists command premium compensation. Brands struggle to staff in-house efficacy study design functions.
- Cross-border e-commerce compliance:Harmonizing label claims across FDA, EFSA, and SAMR jurisdictions requires dedicated regulatory affairs capacity. Misalignment triggers detention at customs checkpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Loss Supplement Market |
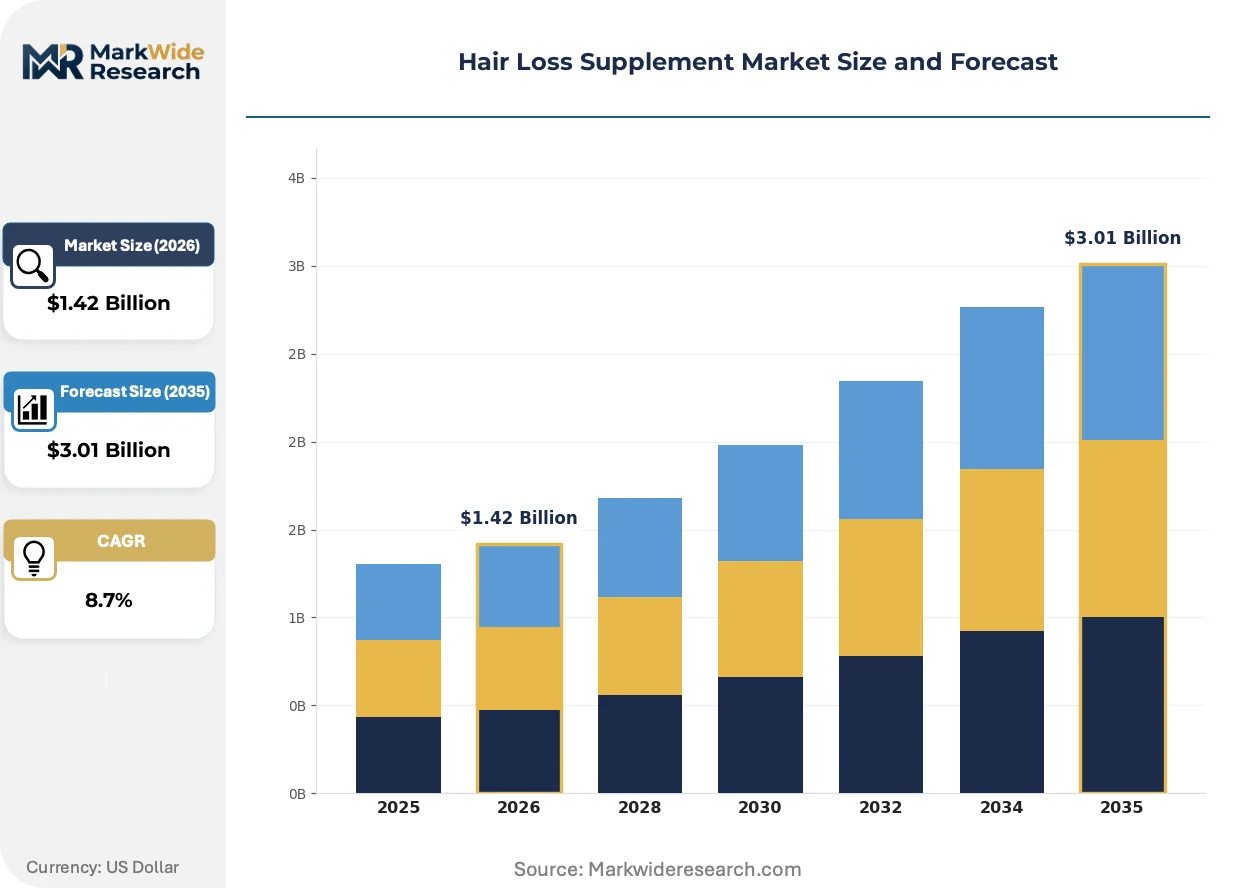
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pills, Powders, Topical Solutions, Gummies Ingredient Type: Vitamins, Herbal Extracts, Amino Acids, Minerals Target Consumer: Men, Women, Seniors, Teens Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Nutrafol, Viviscal, Nature’s Bounty, Unilever, Nestlé Health Science, Amway Corporation, HUM Nutrition, Nature’s Way Brands, Vitabiotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Loss Supplement Market Trends and Innovations
Formulation science is migrating from broad-spectrum vitamin complexes toward targeted bioactive delivery systems that modulate specific follicular signaling pathways. This precision shift is compressing the efficacy demonstration timeline and raising the bar for clinical substantiation.
Artificial intelligence is automating ingredient interaction modeling and predictive stability testing for complex botanical matrices. Mid-tier manufacturers are adopting machine learning platforms to compress formulation development cycles from eighteen months to under six. This capability compression is democratizing access to professional-grade product development without captive R&D infrastructure.
EFSA health claim assessments are tightening evidentiary standards for structure-function statements across European markets. Brands must now submit peer-reviewed clinical data rather than traditional literature reviews. German pharmacy-exclusive distributors are responding by demanding pre-submitted dossiers before listing decisions.
Men aged 25-35 are bypassing generalist retail in favor of telehealth-integrated supplement platforms that bundle diagnostic assessment with personalized regimens. This channel disintermediation is fragmenting traditional pharmacy recommendation flows. United States metropolitan markets show the strongest concentration of these vertically integrated service models.
Hair Loss Supplement Market Segmentation
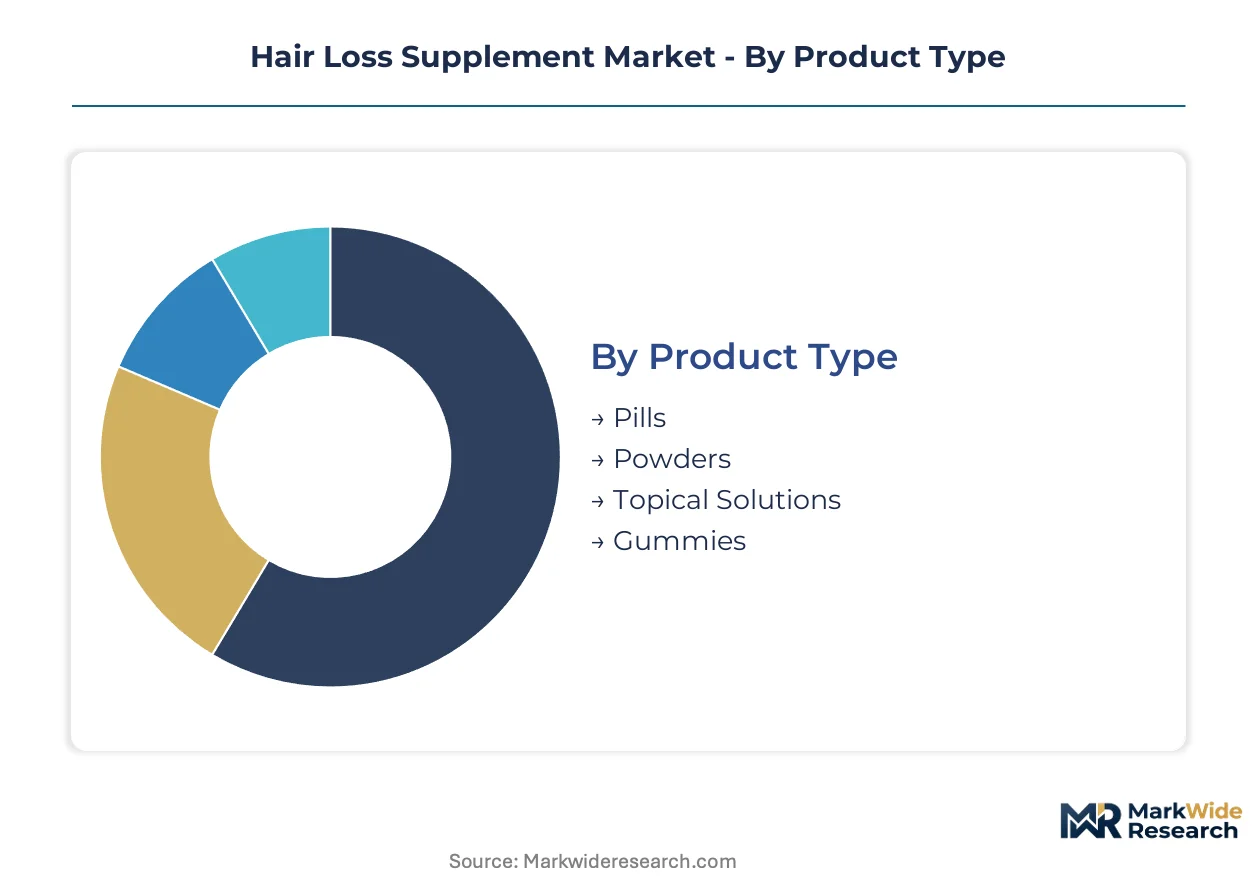
Hair loss supplement segmentation reveals how formulation science, demographic targeting, and channel economics fragment competitive strategy. Manufacturers must align capital deployment with segment-specific regulatory burdens and margin structures to capture sustainable positioning.
Product Type:
Capital intensity varies sharply across delivery formats, with topical solutions demanding the highest upfront investment in stability testing and dermatologist channel validation.
- Pills:Compressed tablet formulations containing standardized biotin, zinc, and iron complexes. Demand concentrates among working-age men in the United States seeking discrete daily compliance, though swallowing aversion limits penetration among older demographics.
- Gummies:Gelatin or pectin-based matrices masking active ingredients with flavor systems. Palatability-driven compliance is accelerating adoption among men aged 25-35 in China, where pharmacy chains now stock clinically positioned gummy SKUs alongside traditional pills.
- Powders:Bulk active blends requiring consumer measurement and mixing. Sports nutrition crossover applications in Germany drive modest volume through fitness channel distribution.
- Topical Solutions:Scalp-applied serums with liposomal or nanosomal delivery systems. Per-unit pricing power is strongest in this segment, though FDA cosmetic-drug distinction scrutiny elevates formulation legal review costs.
Most installed capacity flows through pills. Expansion is steepest in gummies.
Ingredient Type:
Raw material sourcing geography and extraction technology costs determine which ingredient classes absorb the greatest working capital.
- Herbal Extracts:Standardized saw palmetto, pumpkin seed, and ashwagandha concentrates requiring supercritical CO2 or ethanol extraction infrastructure. Saw palmetto berry harvest volatility in Florida and Georgia is forcing manufacturers toward long-term supply contracts with concentrated agricultural processors.
- Vitamins:Synthetic or fermentation-derived biotin, vitamin D, and B-complex compounds. Established clinical familiarity sustains baseline demand across all major markets, though commodity pricing pressure compresses margins for undifferentiated formulations.
- Amino Acids:L-cysteine, L-methionine, and L-lysine targeting keratin synthesis pathways. Niche positioning in European pharmacy channels depends on EFSA-compliant structure-function claim substantiation.
- Minerals:Zinc, iron, and selenium addressing deficiency-linked telogen effluvium. Bioavailability-enhanced chelated forms command premium positioning in Japanese functional food crossover applications.
Ingredient sourcing concentrates in herbal extracts. Steepest formulation innovation is occurring in amino acids.
Target Consumer:
Customer acquisition costs and lifetime value calculations diverge substantially across demographic cohorts, with men aged 25-45 offering the most favorable unit economics for subscription-based models.
- Men:Preventive positioning now normalized among 25-45 age band, compressing traditional reactive treatment windows. Telehealth-integrated platforms in United States metropolitan markets capture this cohort through bundled diagnostic and regimen services.
- Women:Postpartum and perimenopause-linked demand segments requiring distinct hormonal context messaging. Pharmacy-exclusive distribution in France and Germany controls professional recommendation flows for this sensitive positioning.
- Seniors:Chronic condition interaction concerns elevate pharmacist consultation dependency. Supermarket and hypermarket formats in emerging economies struggle to serve this cohort's information requirements.
- Teens:Nutritional deficiency correction and stress-linked telogen effluvium addressing. Parental purchase gatekeeping and pediatrician consultation requirements lengthen conversion funnels in all regulated markets.
Most marketing spend targets men. Expansion is fastest among women.
Distribution Channel:
Channel selection locks in margin structure and regulatory compliance burden simultaneously, with pharmacy-exclusive positioning demanding the most extensive documentation investment.
- Pharmacies:Professional recommendation-controlled environments in Germany, France, and China prioritizing clinically positioned nutraceuticals. SAMR blue-hat registration in China creates first-mover advantages for compliant entrants in Shanghai and Beijing urban pharmacy chains.
- Online Retail:Direct-to-consumer platforms capturing recurring revenue through auto-replenishment. Subscription model penetration is deepest in United States metropolitan markets where telehealth integration fragments traditional recommendation flows.
- Supermarkets:Mass-market scale extending shelf access across emerging economies. Unilever and similar conglomerates leverage existing retail relationships to push undifferentiated vitamin-based SKUs.
- Health Stores:Specialist positioning emphasizing botanical and clean-label formulations. EFSA health claim friction has doubled market access costs for mid-tier brands seeking European health store distribution.
Most volume flows through online retail. Expansion is steepest in pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates subscription-driven direct-to-consumer volume while China commands pharmacy-channel expansion through registration-gated access. Germany anchors European professional recommendation flows with pharmacy-exclusive positioning. These three markets diverge sharply in regulatory burden and channel economics.
United States
Telehealth-integrated platforms bundle diagnostic assessment with personalized regimens for men aged 25-35. FDA dietary supplement CGMP enforcement filters undercapitalized entrants and consolidates shelf access among substantiated brands. New York and Los Angeles metropolitan markets show the strongest concentration of vertically integrated service models.
China
Urban pharmacy chains in Shanghai and Beijing prioritize clinically positioned nutraceuticals over cosmetic alternatives. SAMR blue-hat registration requirements create first-mover advantages for compliant entrants through pre-market notification barriers. Pearl River Delta contract manufacturers rebalance capacity toward high-potency biotin and saw palmetto complexes.
Germany
Pharmacy-exclusive distribution controls professional recommendation flows for postpartum and perimenopause-linked segments. EFSA health claim assessments demand peer-reviewed clinical data rather than literature reviews. Bavaria-based distributors demand pre-submitted substantiation dossiers before listing decisions.
United Kingdom
Health store specialists emphasize botanical and clean-label formulations targeting deficiency-linked telogen effluvium. MHRA borderline product classifications elevate legal review costs for topical solution entrants. London-Southeast retail clusters fragment between pharmacy chains and direct-to-consumer platforms.
Japan
Functional food crossover applications absorb bioavailability-enhanced mineral complexes for keratin synthesis pathways. PMDA and FSSAI alignment demands harmonize label claims for cross-border e-commerce compliance. Tokyo-Osaka corridor pharmacies stock clinically familiar vitamin-based SKUs alongside emerging amino acid innovations.
Hair Loss Supplement Market Competitive Landscape
United States producers anchor the direct-to-consumer subscription tier; European specialists hold pharmacy-exclusive positioning through professional validation networks. The vendor base stratifies across three tiers: physician-endorsed premium brands, mass-market conglomerates with retail scale, and mid-tier botanical specialists seeking EFSA compliance. Consolidation pressure intensifies as CGMP documentation costs and clinical substantiation investments filter undercapitalized entrants. Dominant competitive moves include strategic partnerships with telehealth platforms and geographic expansion through SAMR registration in Chinese urban pharmacy chains.
Within the physician-endorsed premium tier, Nutrafol and Viviscal exemplify divergent channel strategies—one leveraging dermatologist networks for direct-to-consumer access, the other anchoring European presence through pharmacy-exclusive distribution. Unilever occupies a position among mass-market conglomerates that extend shelf access across supermarket formats in emerging economies. These three entities represent the archetype spectrum from clinical validation to scale-driven retail penetration.
| Leading Market Players |
|---|
| Nutrafol |
| Viviscal |
| Nature's Bounty |
| Unilever |
| Nestlé Health Science |
| Amway Corporation |
| HUM Nutrition |
| Nature's Way Brands |
| Vitabiotics |
| Others |
Pricing and Supply Chain Analysis
Subscription-driven direct-to-consumer buyers in United States metropolitan markets anchor pricing power toward recurring revenue models that compress customer acquisition costs. This buyer concentration elevates subscription-tier pricing above transactional pharmacy formats while forcing supply chain rebalancing toward high-potency botanical extraction capacity.
Pricing Analysis
Capacity additions in Pearl River Delta contract manufacturing zones are reshaping price floors for gummy and softgel formats. Three-tier pricing structure across premium, standard, and economy levels separates physician-endorsed brands from mass-market conglomerates and undifferentiated private-label entrants. Cost compression in standard-tier vitamin complexes is intensifying because commodity biotin pricing pressure and cross-border e-commerce margin stacking. Men aged 25-35 in United States metropolitan markets show least price sensitivity through telehealth-integrated bundling, while supermarket shoppers in emerging economies exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Florida and Georgia saw palmetto berry harvest zones that feed supercritical CO2 extraction infrastructure. Raw material sourcing concentrates in United States herbal agriculture, Chinese fermentation-derived vitamin production, and Indian amino acid synthesis. Supply chain risk rests on climate volatility in southeastern United States berry harvests that introduces input cost instability. Distribution runs through direct-to-consumer auto-replenishment platforms, pharmacy-exclusive professional channels, and mass-market retail formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States CGMP compliance costs and Chinese SAMR registration barriers that filter undercapitalized entrants from urban pharmacy expansion.
For Market Incumbents: Acquire clinical substantiation capabilities including trichology research specialists and in-house efficacy study design functions. Secure long-term supply contracts with Florida and Georgia saw palmetto processors to defend against climate-driven input volatility. Expand SAMR blue-hat registration coverage across Shanghai and Beijing pharmacy chains before mid-tier competitors accumulate compliance documentation. For New Entrants and Emerging Players: AI-enabled formulation development platforms offer technology-first wedge into mid-tier botanical specialist tier. Target scalp microbiome convergence segments where probiotic-prebiotic combinations remain underdeveloped relative to systemic vitamin complexes. Pursue telehealth-integrated distribution partnerships in United States metropolitan markets that fragment traditional pharmacy recommendation flows. For Investors and Strategic Acquirers: Consumer health conglomerates with existing retail scale represent the most active acquirer in this space. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than brand equity alone. Monitor EFSA health claim assessment tightening as inflection indicator that will consolidate European pharmacy-exclusive positioning among dossier-capable entities.| Strategic Initiative | Industry Significance |
|---|---|
| SAMR Blue-Hat Registration | Pre-market notification barriers in China create first-mover pharmacy access in Shanghai and Beijing. |
| Telehealth Platform Integration | Bundled diagnostic-regimen services capture United States men aged 25-35 through subscription lock-in. |
| Long-Term Saw Palmetto Supply Contracts | Concentrated Florida and Georgia harvest zones demand upstream control over climate-exposed inputs. |
| AI-Enabled Formulation Development | Machine learning compression of development cycles democratizes professional-grade R&D without captive infrastructure. |
| Scalp Microbiome Product Line Extension | Probiotic-prebiotic combinations differentiate from saturated systemic vitamin positioning in pharmacy channels. |
Research Methodology
Direct dialogue with contract manufacturing executives, regulatory affairs specialists at SAMR-registered entities, pharmacy chain category managers, and trichology research directors grounded qualitative insights. Secondary validation drew from FDA dietary supplement warning letters, SAMR blue-hat registration databases, EFSA health claim assessment opinions, and United States customs import records for saw palmetto extracts. Bottom-up capacity utilization data and top-down consumption estimates were triangulated to reconcile volume figures.
Segment-level outputs across the analysis window reflect product type, ingredient class, target demographic, and distribution channel dimensions. CAGRs were derived from regression analysis of historical volume trajectories and forward-looking regulatory event probabilities. Forecast inputs incorporated SAMR registration queue timing, EFSA substantiation friction indices, and saw palmetto harvest yield volatility patterns.
The model holds under stable regulatory enforcement intensity; deviation in FDA CGMP audit frequency or SAMR blue-hat approval timelines would shift capacity deployment assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Sleep Supplement Market
Dietary Supplements
Global Oral Electrolyte Solutions Market
Dietary Supplements
Folic Acid Tablets Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Vitamin D Deficiency Treatment Market
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Melatonin Sleep Supplements Market
Dietary Supplements
Herbal Tincture Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Pet Herbal Supplements Market
Dietary Supplements
Global Nicotine Lozenges Market
Dietary Supplements
Sleep Aid Supplements Market
Dietary Supplements
Medicated Confectionery Market