
 Robotics and Automation Actuators Market | 2026-2036
Robotics and Automation Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Robotics and Automation Actuators Market Outlook
ISO 13849-1 safety integrity ratings for robot joint actuators is rotating competitive access, forcing suppliers to recertify control architectures every three years. ABB leverages its servo motor-actuator integration to dominate high-payload automotive lines. Moog sustains aerospace-grade hydraulic actuator leadership through proprietary flight control heritage. Festo competes in cleanroom pneumatic systems for semiconductor handling, where particle emission standards exceed general industrial thresholds.
Robotics and automation actuators are electromechanical, fluid-power, or mechanical devices that convert energy into controlled linear or rotary motion, typically achieving positioning accuracy within ±0.01 mm in servo-electric variants and operating at dynamic response frequencies above 100 Hz for high-speed pick-and-place cycles. These components enable precise joint articulation, tool positioning, and load manipulation across industrial machinery, mobile robots, and process equipment. Electric actuators now lead technology adoption where energy efficiency and programmability matter, while hydraulic variants retain margin concentration in heavy-lift aerospace and defense applications. Pneumatic systems still occupy cost-sensitive conveyor and clamping roles despite slower growth, and robotic arms represent the fastest-expanding application dimension as collaborative robot deployments multiply across small-batch manufacturing.
FDA device manufacturing regulations in the US, EU Machinery Directive enforcement through notified bodies in Germany and Italy, and China's GB/T robot safety standards collectively dictate actuator design validation, traceability documentation, and fail-safe braking requirements for cross-border equipment sales. Japan's METI industrial robot roadmap and South Korea's KOSHA occupational safety framework add further certification layers for Asian market entry. Stakeholders must monitor evolving functional safety standards for autonomous mobile robots, where actuator redundancy architectures will determine which suppliers retain access to warehouse and logistics automation contracts.
Market Dynamics
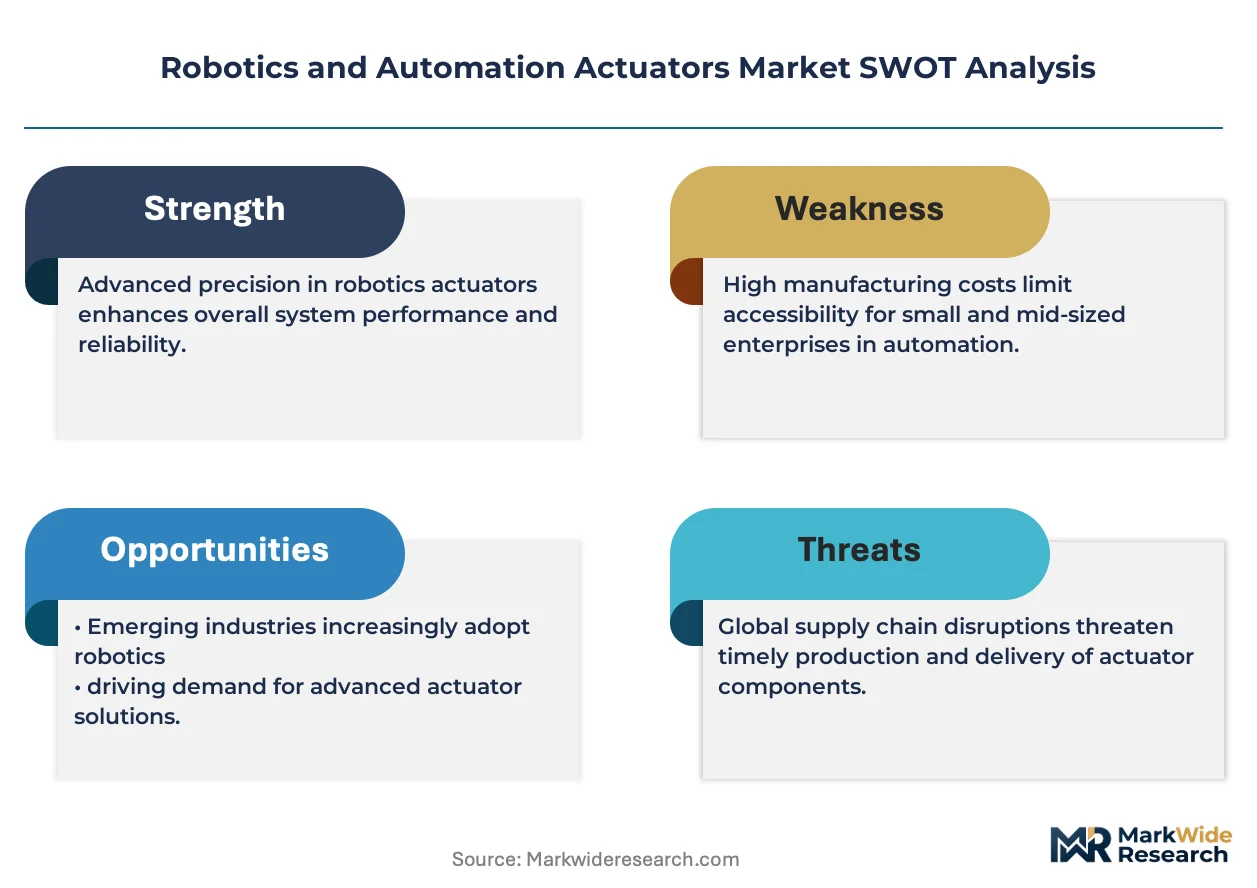
ISO 13849-1 recertification cycles every three years are forcing suppliers to redesign control architectures, while China's battery production corridor concentrates demand for high-force electric actuators in Shenzhen and Shanghai.
Growth Catalysts
- EU Machinery Directive enforcement:Notified bodies in Germany and Italy mandate fail-safe braking and traceability documentation, compelling equipment upgrades across cross-border automation sales.
- Automotive precision welding:Assembly lines in Germany and Japan expand actuator deployment for painting operations requiring ±0.01 mm positioning accuracy.
- Semiconductor cleanroom handling:Particle emission standards exceeding general industrial thresholds drive pneumatic system demand for wafer transport in fabrication facilities.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings squeeze margins for servo-electric actuator manufacturers dependent on permanent magnet motors.
- Hydraulic supply concentration:Aerospace-grade hydraulic actuator production clusters in US and European defense contractors, limiting civilian market access.
- Pneumatic efficiency ceiling:Compressed air systems face displacement by electric alternatives where energy recovery and programmability outweigh initial cost advantages.
Strategic Opportunities
- Collaborative robot safety standards:Emerging ISO frameworks for cobot joint actuators create first-mover advantage for suppliers certifying redundant torque-limiting architectures.
- Battery gigafactory automation:China's eastern manufacturing corridor specifies high-force electric actuators for cell stacking and module assembly lines.
- Mobile robot logistics:Warehouse automation contracts increasingly require actuator redundancy for autonomous mobile robots navigating dynamic environments.
Industry Challenges
- Functional safety engineering scarcity:SIL-rated control system design talent concentrates at established automotive and aerospace suppliers, constraining new market entrants.
- Legacy system integration friction:Brownfield manufacturing sites require custom mechanical adapters and communication protocol bridges for servo actuator retrofit.
- Multi-jurisdiction certification timelines:Simultaneous FDA device manufacturing, EU Machinery Directive, and China GB/T robot safety validation extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotics and Automation Actuators Market |
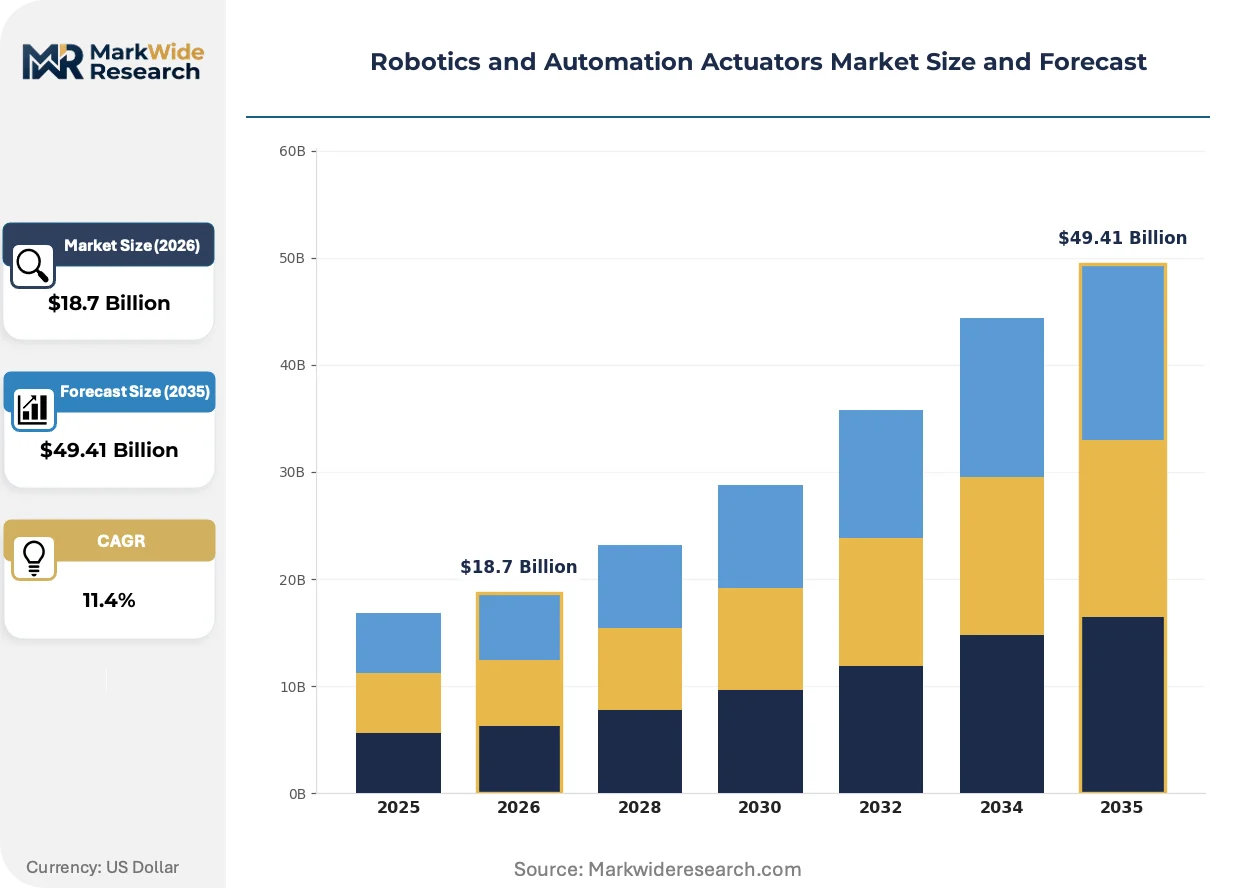
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Linear Actuators, Rotary Actuators, Pneumatic Actuators, Hydraulic Actuators Technology: Electric, Hydraulic, Pneumatic, Mechanical End User: Manufacturing, Automotive, Healthcare, Aerospace Application: Robotic Arms, Automated Guided Vehicles, CNC Machines, Conveyors |
| Companies Covered | ABB, Rockwell Automation, Moog, SMC, Emerson Electric, Festo, MISUMI Group, Curtiss-Wright, Altra Industrial Motion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotics and Automation Actuators Market Strategic Shifts
Servo-electric actuator architectures are splitting into distinct performance tiers as end-use requirements diverge, while regulatory pressure on functional safety intensifies design complexity.
Integrated motor-actuator systems with embedded drive electronics and absolute encoders are bifurcating competitive positioning. Automotive OEMs in Germany adopt these compact units for high-payload welding lines where cabinet space constraints dominate. The technology is bifurcating supplier tiers, separating vertically integrated motor manufacturers from standalone actuator assemblers lacking in-house servo motor production.
EU Machinery Directive amendments through notified bodies in Germany and Italy tighten compliance verification for collaborative robot installations. Industrial consequence includes mandatory third-party assessment of force-limiting actuator performance in human-robot shared workspaces. Automotive and electronics assembly sectors absorb the highest compliance burden, with integrators pre-certifying complete robot-actuator combinations to accelerate customer site acceptance.
Battery manufacturers now specify actuator performance through total cost of ownership metrics rather than capital expenditure alone. System integrators in China's eastern corridor compete on energy consumption guarantees and predictive maintenance integration for cell production lines. This specification shift is most visible in Shenzhen and Shanghai, where gigafactory procurement teams bundle actuator selection with multi-year service contracts covering spare inventory and firmware updates.
Robotics and Automation Actuators Market Segmentation
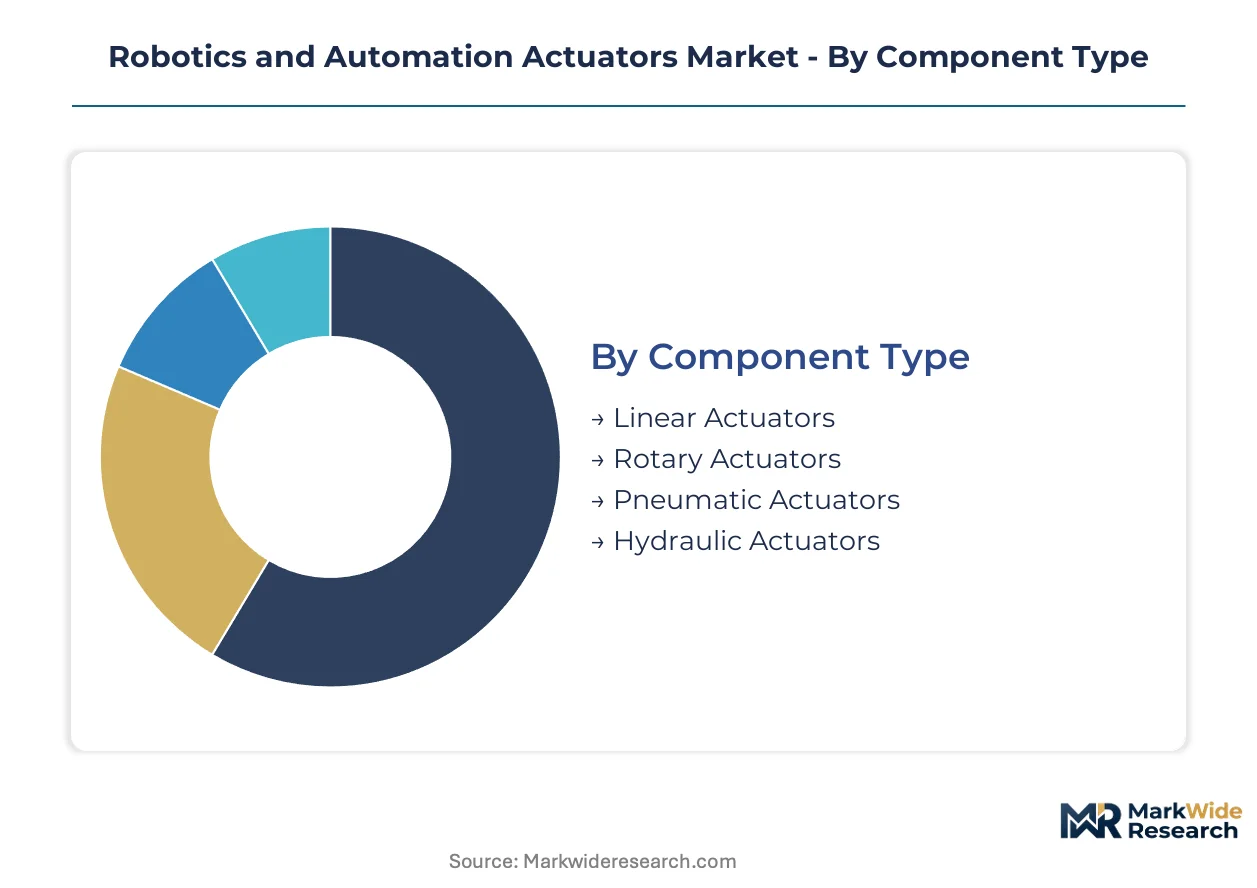
Actuator segmentation reveals where electric technologies displace fluid-power incumbents and which compliance burdens concentrate by end-use. Procurement teams in Germany and China now specify across multiple category dimensions simultaneously, forcing suppliers to map certification requirements to each intersection.
Component Type:
Pneumatic actuators face the steepest substitution pressure as energy efficiency mandates tighten across EU manufacturing corridors.
- Linear Actuators:Ball-screw and belt-drive mechanisms deliver thrust loads exceeding 50 kN with positioning repeatability to ±0.005 mm. Battery gigafactories in Shenzhen and Shanghai specify these for electrode stacking operations where force control determines cell yield. China's eastern manufacturing corridor concentrates procurement for high-force variants.
- Rotary Actuators:Direct-drive torque motors and harmonic gearheads enable precise joint articulation in collaborative robots. Automotive assembly lines in Germany adopt these for welding gun positioning where ISO 13849-1 safety ratings mandate redundant feedback systems. METI industrial robot roadmaps in Japan accelerate certification requirements.
- Pneumatic Actuators:Compressed air cylinders retain cost advantages in clamping and conveyor applications despite efficiency penalties. Semiconductor fabrication facilities specify cleanroom-rated variants with particle emissions below Class 100 thresholds.
- Hydraulic Actuators:High-pressure fluid systems dominate aerospace flight control and heavy-lift defense applications where power density exceeds electric alternatives. US and European defense contractors control supply access.
Linear actuators anchor the volume base while rotary actuators gain share at the steepest rate.
Technology:
Cost tiers separate premium servo-electric systems from commodity pneumatic alternatives, with hydraulic technologies occupying a narrow defense-aerospace niche.
- Electric:Servo motors with integrated drives achieve dynamic response above 100 Hz and energy recovery during deceleration cycles. Automotive OEMs in Germany specify compact motor-actuator combinations for cabinet-constrained welding lines. Rare earth magnet cost volatility constrains margin stability for permanent magnet motor suppliers.
- Hydraulic:Proportional valves and servo cylinders deliver force densities unmatched by electromechanical alternatives. Aerospace applications in the US and Europe require flight heritage certification that limits new supplier entry.
- Pneumatic:Directional control valves and positioners offer lowest capital cost for simple motion sequences. Energy consumption penalties drive displacement by electric alternatives in continuous-duty applications.
- Mechanical:Cam, linkage, and screw mechanisms persist in legacy equipment where programmability requirements remain minimal. Brownfield manufacturing sites in Italy retain these for cost-constrained retrofits.
Electric technologies capture the premium tier while pneumatic systems defend the economy segment through lowest first cost.
End User:
Application maturity varies sharply, with healthcare and aerospace demanding the longest certification timelines while manufacturing absorbs volume.
- Manufacturing:General automation across electronics, food processing, and packaging lines specifies mid-range electric actuators with standard IP65 environmental sealing. EU Machinery Directive enforcement through German and Italian notified bodies mandates fail-safe braking documentation.
- Automotive:Paint shop and body-in-white operations require explosion-proof pneumatic actuators and precision servo-electric systems for robotic welding. Assembly lines concentrate in Germany and Japan.
- Healthcare:Surgical robots and diagnostic equipment demand ISO 13485 quality systems and FDA device manufacturing validation. Actuator redundancy architectures determine supplier qualification for robotic surgery platforms.
- Aerospace:Flight control surfaces and landing gear systems require DO-178C software certification and MIL-STD environmental qualification. US and European defense contractors dominate supply.
Manufacturing absorbs the highest unit volumes while healthcare commands the steepest pricing premiums.
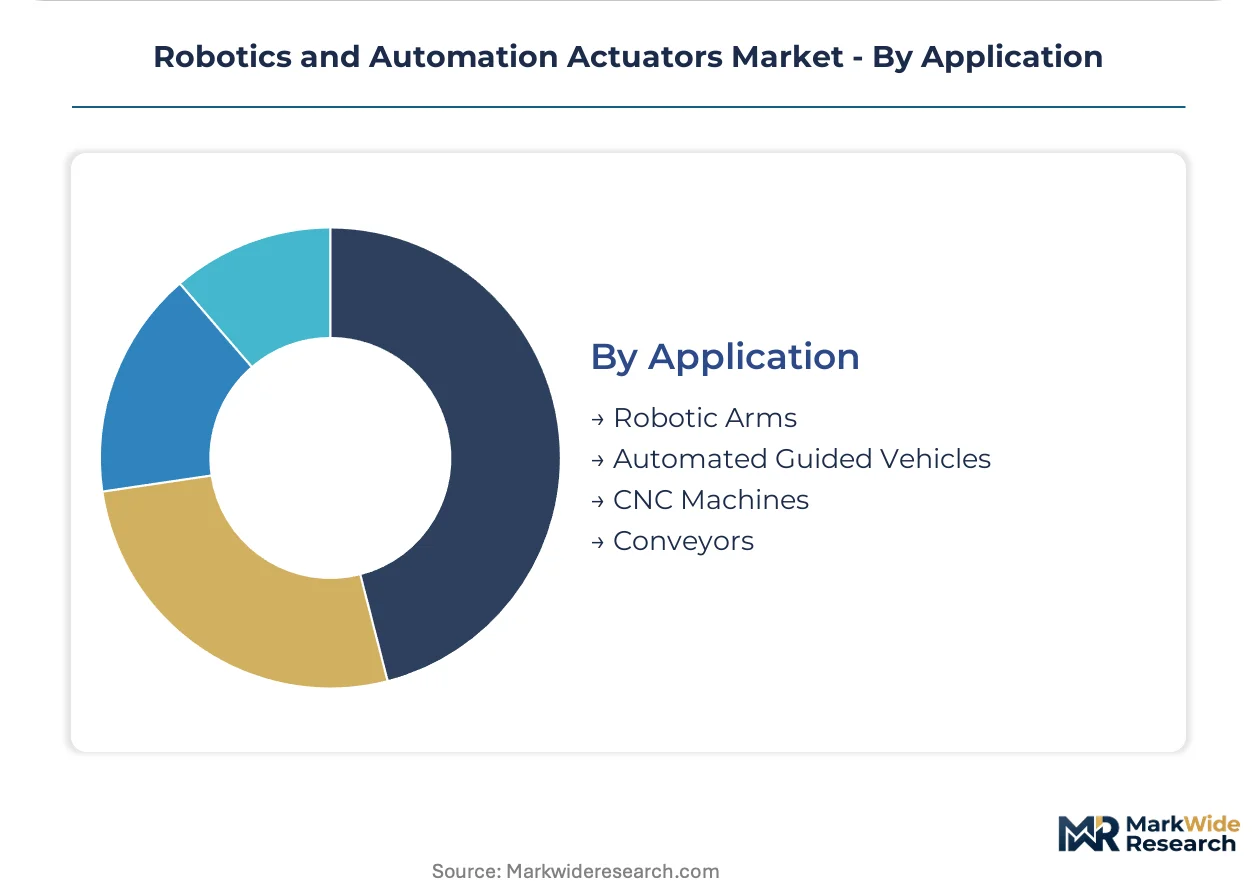
Application:
Customer procurement patterns diverge between integrators specifying complete robot-actuator combinations and end-users buying standalone components for retrofit.
- Robotic Arms:Six-axis and collaborative robot joints require compact rotary actuators with torque limiting for human-robot shared workspaces. Emerging ISO safety standards for cobots force recertification cycles every three years.
- Automated Guided Vehicles:Mobile robot drive systems and lift mechanisms need actuator redundancy for navigation safety in dynamic warehouse environments. Logistics automation contracts increasingly specify SIL-rated control architectures.
- CNC Machines:Linear axes and rotary tables demand high-stiffness ball-screw actuators with thermal compensation for precision machining. Machine tool builders in Germany and Japan specify integrated motor-spindle combinations.
- Conveyors:Belt drives and sorting diverters utilize low-cost pneumatic and electric actuators where positioning accuracy requirements remain relaxed. Cost-sensitive procurement favors pneumatic alternatives in high-volume distribution centers.
Conveyors anchor the installed base while robotic arms expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Machinery Directive amendments and China's dual carbon goals are redirecting procurement patterns toward high-efficiency electric systems. Battery gigafactory buildouts and automotive precision welding requirements concentrate demand in specific industrial corridors. Regulatory compliance timelines now determine supplier qualification across major manufacturing economies.
Germany
Automotive OEMs expand servo-electric actuator deployment for body-in-white welding lines requiring ISO 13849-1 safety certification. Notified bodies under the EU Machinery Directive enforce mandatory third-party assessment of fail-safe braking systems. Stuttgart and Munich industrial clusters anchor procurement for integrated motor-actuator combinations.
China
GB/T robot safety standards and MIIT industrial automation roadmaps accelerate domestic certification requirements for collaborative robot joints. Shenzhen and Shanghai-based integrators specify high-force electric actuators for battery cell stacking operations. The eastern manufacturing corridor concentrates demand for predictive maintenance-enabled systems.
Japan
METI's industrial robot roadmap tightens functional safety requirements for torque-limiting actuator architectures. Automotive paint shops and electronics assembly lines drive precision positioning demand. Nagoya and Osaka manufacturing belts specify compact rotary actuators for human-robot collaborative workspaces.
United States
FDA device manufacturing regulations and OSHA workplace safety frameworks dictate actuator redundancy requirements for surgical robotics platforms. Aerospace flight control applications sustain demand for MIL-STD qualified hydraulic systems. Detroit automotive corridors and Boston medical device clusters anchor regional procurement.
South Korea
KOSHA occupational safety frameworks and MFDS medical device standards create multi-layer certification requirements for automation suppliers. Electronics assembly and semiconductor fabrication drive cleanroom-rated pneumatic actuator demand. Seoul Capital Area and Busan-Ulsan industrial zones concentrate integrator activity.
Robotics and Automation Actuators Market Competitive Environment
Listed leaders compete with private specialists across servo motor integration and fluid-power heritage dimensions. The supplier base separates into consolidated motion control conglomerates and focused component specialists. Three archetypes dominate: vertically integrated motor-actuator manufacturers, aerospace-grade hydraulic heritage suppliers, and cleanroom pneumatic system providers. Competitive moves center on functional safety certification acceleration and geographic expansion into China's battery production corridor.
Within the integrated motion control tier, ABB and Rockwell Automation exemplify the convergence of servo motor production with actuator assembly capabilities. Moog occupies a position representing aerospace-grade hydraulic heritage, while Festo anchors the cleanroom pneumatic specialization segment. These three companies illustrate how supplier positioning diverges across electric, hydraulic, and pneumatic technology vectors.
| Leading Market Players |
|---|
| ABB |
| Rockwell Automation |
| Moog |
| SMC |
| Emerson Electric |
| Festo |
| MISUMI Group |
| Curtiss-Wright |
| Altra Industrial Motion |
| Others |
Value Chain & Pricing Dynamics
Ninety-day safety certification lead times for ISO 13849-1 compliance concentrate pricing power with German and Japanese incumbents who maintain pre-certified architectures, while battery manufacturers in Shenzhen negotiate total cost of ownership contracts that bundle actuator hardware with multi-year service agreements and firmware update commitments.
Pricing Analysis
Certification level creates the primary spread across servo-electric actuator tiers, with FDA-grade surgical robot components commanding substantial premiums over standard industrial variants. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13849-1 safety integrity ratings, volume scale, and after-sales service bundling. Cost compression in mid-range electric actuators is intensifying because rare earth magnet price volatility squeezes permanent magnet motor margins. Automotive OEMs in Germany exhibit lowest price sensitivity due to cabinet-space constraints and safety mandates, while conveyor integrators in distribution centers remain most cost-sensitive and favor pneumatic alternatives.
Supply Chain Analysis
China and Japan anchor rare earth magnet processing and servo motor manufacturing for electric actuators, while Germany and the United States control aerospace-grade hydraulic system production. Supply chains draw from neodymium-dysprosium magnet supply, precision ball-screw mechanisms, and embedded drive electronics. Single-source vulnerability concentrates in Chinese rare earth refining capacity, exposing electric actuator manufacturers to export restriction risk. Distribution runs through system integrators in Shenzhen, Stuttgart, and Detroit who bundle actuator selection with complete automation line contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotics and automation actuators face high-growth disruption as collaborative robot safety standards force three-year recertification cycles that rotate competitive access and concentrate procurement with pre-certified suppliers.
For Market Incumbents: Secure ISO 13849-1 certification acceleration through notified body partnerships in Germany and Italy to defend against emerging electric actuator specialists from China. Deepen backward integration into rare earth magnet supply chains to offset neodymium price volatility. Extend predictive maintenance service contracts to lock in battery gigafactory relationships across Shenzhen and Shanghai. For New Entrants and Emerging Players: ISO 13849-1 fast-track programs through German TÜV or Italian notified bodies open qualification pathways for collaborative robot joint architectures. White-space concentrates in mobile robot actuator redundancy for warehouse logistics contracts requiring SIL-rated control systems. Target South Korean electronics assembly integrators who face KOSHA occupational safety deadlines and seek alternative suppliers to Japanese incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming actuator divisions lacking functional safety certification depth. Long-term viability favors suppliers with captive servo motor production and established aerospace flight heritage. Watch for battery manufacturer procurement shifts toward energy consumption guarantees as the inflection signal indicating specification power migration from capital expenditure to total cost of ownership metrics.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Acceleration | ISO 13849-1 pre-certification through German notified bodies secures automotive welding line contracts before three-year recertification windows close. |
| Rare Earth Magnet Supply Integration | Backward integration into neodymium processing insulates margins from Chinese export volatility and magnet price swings. |
| Battery Gigafactory Service Contracting | Multi-year predictive maintenance agreements with Shenzhen and Shanghai integrators transform actuator sales into recurring revenue streams. |
| Collaborative Robot Joint Architecture Development | Redundant torque-limiting designs for ISO cobot standards capture fastest-expanding application dimension in small-batch manufacturing. |
| Cleanroom Pneumatic System Specialization | Particle emission control below Class 100 thresholds defends semiconductor fabrication market share against electric substitution pressure. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automation system integrators in Shenzhen and Stuttgart, plant engineers at automotive OEMs, procurement leads at battery manufacturers, and aftermarket service heads at motion control distributors. Secondary validation drew from EU Machinery Directive enforcement records through German and Italian notified bodies, FDA device manufacturing registration databases, METI industrial robot roadmap publications, and SEC filings of listed motion control conglomerates. Bottom-up actuator shipment estimates triangulated against top-down manufacturing automation capex forecasts.
Across the analysis window, volume and value outputs segmented by component type, technology, end user, and application with regional production cluster overlays. CAGRs derived from historical shipment trajectories and forward-looking procurement pipeline analysis. Forecast inputs incorporated ISO 13849-1 recertification cycle impacts, rare earth magnet price elasticity assumptions, and battery gigafactory buildout schedules across China's eastern manufacturing corridor.
Decision-makers should treat outputs as directional under sustained EU Machinery Directive enforcement and continued Chinese rare earth supply dominance; material deviation in regulatory timelines or export restriction severity would warrant model refresh. Recalibration cycles align with material shifts in collaborative robot safety standard finalization and battery manufacturer procurement specification evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Intelligent Parcel Delivery Lockers Market
Robotics and Automation
Harvesting Robot Market
Robotics and Automation
Internet of Robotic Things Market
Robotics and Automation
Smart Exoskeleton Market
Robotics and Automation
Consumer and Office Robot Market
Robotics and Automation
Articulated Robots for Injection Molding Machine Market
Robotics and Automation
Underwater Jetpack Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Robot Charging Station Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Europe Educational Robot Market
Robotics and Automation
Medical Service Robots Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market