
 Robot Operating System Market | 2026-2036
Robot Operating System Market Size, Share, and Industry Trends Forecast 2026-2036
Robot Operating System Market Analysis
Embedded processor fabrication in Taiwan is realigning how ROS-compatible hardware reaches system integrators. Nvidia leverages its Jetson platform to dominate edge-AI robotics workloads, while ABB Robotics anchors its RobotStudio environment on ROS2 middleware for factory-floor synchronization. Open Robotics competes through governance of the core distribution, ensuring interoperability across vendor stacks.
Robot Operating System denotes an open-source middleware framework built on a publish-subscribe architecture with DDS (Data Distribution Service) backbone, enabling hardware abstraction and inter-process communication across heterogeneous robotic components. Its primary purpose lies in accelerating development cycles for autonomous navigation, manipulation, and perception systems across industrial and service domains. Middleware deployments currently occupy the largest value pool within the product-type split, though edge-computing configurations are capturing the fastest expansion as latency-sensitive applications multiply. Industrial automation leads application penetration, while healthcare end-users represent the highest-margin segment due to validation and certification overhead.
FDA software-as-medical-device guidance, EU AI Act risk-classification tiers, and ISO 10218 safety standards collectively constrain how ROS-based systems enter regulated environments, particularly in healthcare and collaborative manufacturing. The EU Cyber Resilience Act further mandates vulnerability disclosure timelines for robot software supply chains. Stakeholders must monitor whether ROS2 security enhancements achieve certification parity with proprietary real-time operating systems before committing long-term platform roadmaps.
Market Dynamics
The convergence of DDS-based middleware with deterministic real-time requirements is forcing ROS2 vendors to recertify stacks for safety-critical deployments, compressing development timelines and elevating engineering costs across industrial automation.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification tiers for autonomous systems are compelling manufacturers to adopt standardized middleware with audit trails, directly benefiting ROS-Industrial adoption in collaborative manufacturing.
- Edge-AI hardware maturation:Nvidia Jetson and Qualcomm RB3 platforms now ship with pre-integrated ROS2 drivers, collapsing integration overhead for warehouse robotics developers.
- German automotive clustering:BMW, Mercedes-Benz, and Fraunhofer IPA anchor ROS-Industrial consortia, creating reference architectures that diffuse through Tier-1 supplier networks.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundry capacity constraints for ARM-based SoCs create 26-40 week lead times for ROS-compatible compute modules.
- Real-time determinism gap:ROS2's best-effort scheduling fails IEC 61508 SIL-2 requirements, excluding the framework from high-speed pick-and-place pharmaceutical lines.
- Cybersecurity certification friction:The EU Cyber Resilience Act mandates 24-hour vulnerability disclosure timelines that open-source governance structures struggle to operationalize.
Strategic Opportunities
- Healthcare service robotics:ISO 13482 certification pathways for patient-handling robots remain underdeveloped, creating first-mover advantage for middleware vendors achieving FDA software-as-medical-device alignment.
- India manufacturing automation:PLI scheme incentives for electronics assembly are driving Foxconn and Dixon Technologies to evaluate ROS2 against proprietary ABB and Fanuc stacks.
- Digital twin convergence:Unity and Unreal Engine integrations with ROS2 Gazebo are enabling simulation-first deployment models that slash physical commissioning costs.
Industry Challenges
- Real-time systems engineering talent scarcity:DDS configuration and micro-ROS firmware optimization require specialized skill sets concentrated in Stuttgart, Munich, and Silicon Valley consulting pools.
- Multi-standard certification stacking:Systems entering collaborative manufacturing must simultaneously satisfy ISO 10218-1, ISO/TS 15066, and sector-specific machinery directives, extending validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot Operating System Market |
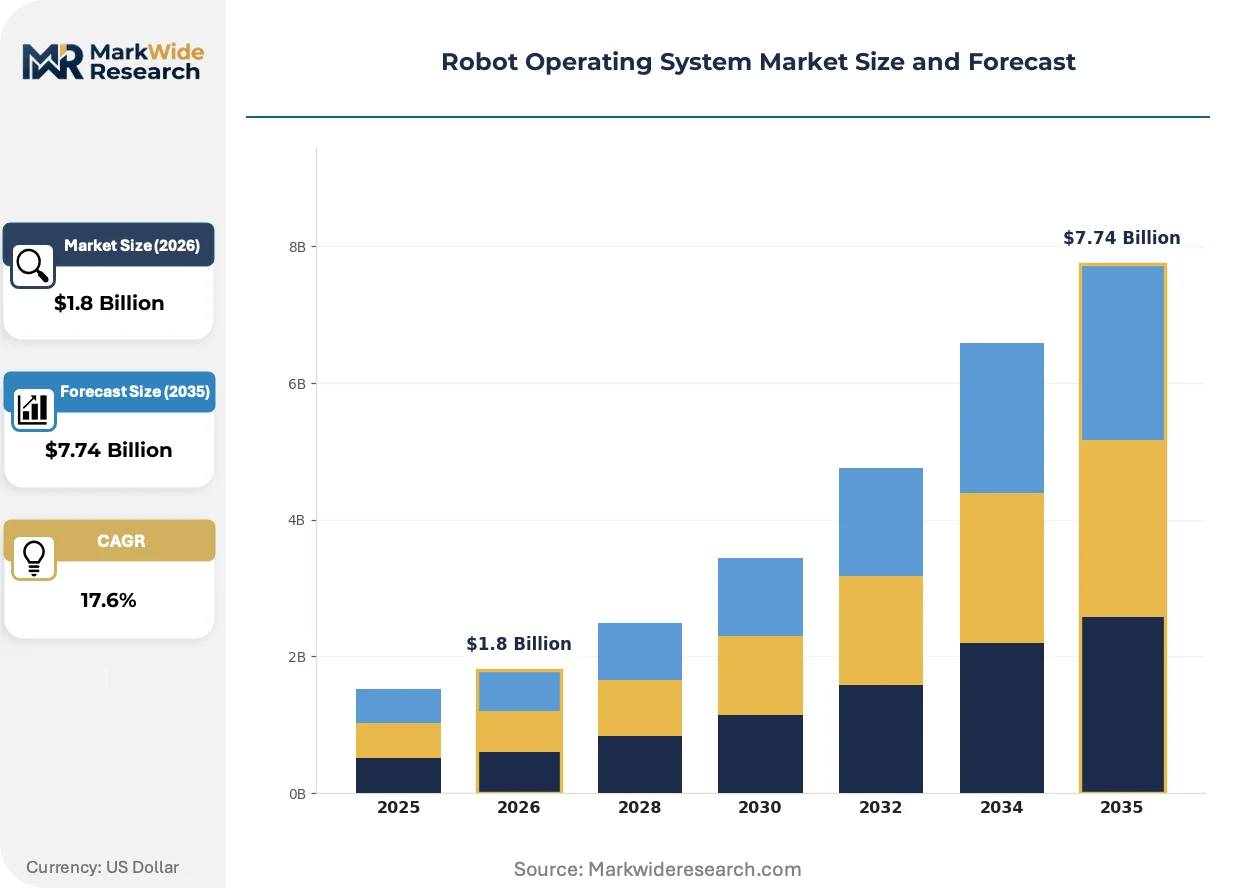
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.74 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Middleware, Framework, Tools, Libraries Application: Industrial Automation, Service Robotics, Research, Entertainment Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Aerospace, Manufacturing, Healthcare, Education |
| Companies Covered | Nvidia, ABB Robotics, Open Robotics, KUKA, FANUC, Amazon Robotics, Universal Robots, Intrinsic, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot Operating System Market Emerging Trajectories
ROS2's technical evolution is decoupling from its academic origins, with commercial vendors hardening distributions for deterministic workloads and embedding security-by-design architectures that satisfy emerging regulatory mandates.
Micro-ROS is rewriting how resource-constrained nodes participate in distributed robotic systems. The framework ports ROS2 client libraries to FreeRTOS and Zephyr RTOS, enabling 32-bit microcontrollers to publish sensor data directly to DDS networks. Automotive Tier-1 suppliers are adopting micro-ROS for battery management systems and brake-by-wire modules, collapsing the historical separation between vehicle dynamics controllers and higher-level autonomy stacks.
The EU AI Act's risk-based conformity assessment is restructuring middleware procurement in collaborative robotics. High-risk applications now require technical documentation, human oversight protocols, and post-market monitoring systems that open-source distributions must retrofit. German system integrators are responding by bundling ROS2 with liability insurance and long-term support contracts, transforming middleware from a cost center into a managed service relationship.
Buyer preference is rotating toward simulation-validated deployment guarantees. Automotive OEMs now require suppliers to demonstrate 10 million virtual miles before physical prototype commissioning, compressing traditional hardware-in-the-loop cycles. This behavioral shift elevates vendors offering integrated Gazebo-Isaac Sim-Unreal Engine pipelines, particularly in Michigan and Bavaria where regulatory pre-homologation requirements are most stringent.
Robot Operating System Market Segmentation
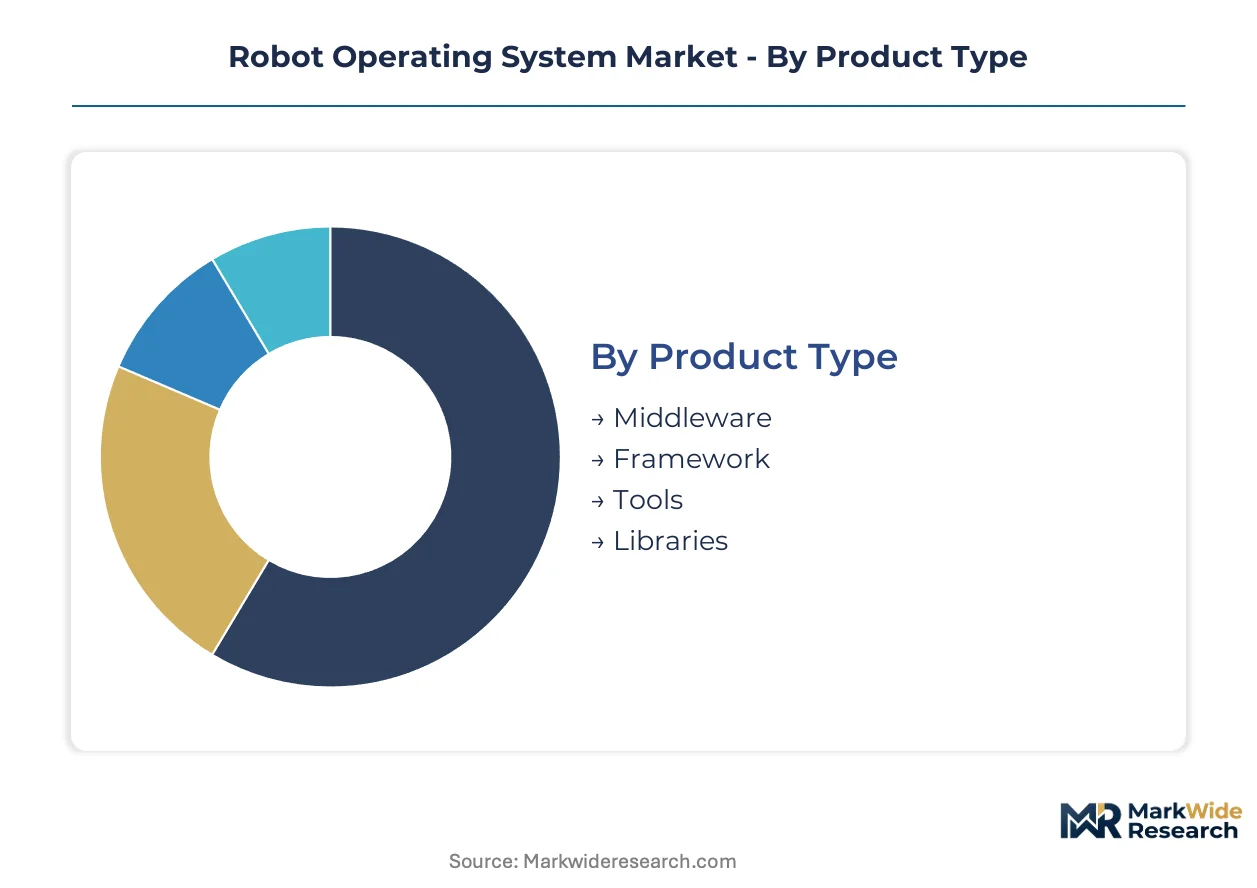
Middleware architecture choices determine certification pathways and integration costs across robotics deployments. Deployment model selection directly constrains latency performance and regulatory compliance scope for autonomous systems.
Product Type:
Middleware stacks concentrate engineering talent and certification investment, while tools and libraries fragment across academic and commercial contributors with uneven maintenance commitments.
- Middleware:DDS-based communication backbone enables deterministic inter-process coordination across heterogeneous hardware. Demand concentrates in German automotive consortia and Amazon warehouse fleets where ISO 10218 and EU AI Act compliance documentation is mandatory.
- Framework:Core distribution governance by Open Robotics ensures interoperability across vendor stacks. Fraunhofer IPA and BMW anchor ROS-Industrial reference architectures that diffuse through Tier-1 supplier networks in Stuttgart and Munich.
- Tools:Gazebo simulation environments and RViz visualization utilities accelerate prototyping cycles for university labs and startup developers.
- Libraries:Perception and navigation packages from the ROS ecosystem reduce sensor integration overhead for mid-sized system integrators.
Today's leader: Middleware. Tomorrow's challenger: Framework.
Application:
Industrial automation commands the deepest integration budgets, while service robotics carries the steepest certification premiums due to human-robot proximity requirements.
- Industrial Automation:Factory-floor synchronization demands real-time determinism that ROS2 vendors are hardening for safety-critical workloads. DHL hubs and ABB RobotStudio deployments in Bavaria and Michigan drive middleware procurement at scale.
- Service Robotics:Patient-handling and elder-care applications require ISO 13482 certification pathways that remain underdeveloped, creating first-mover advantage for vendors achieving FDA software-as-medical-device alignment.
- Research:Academic institutions in Boston and Zurich advance algorithmic frontiers without production-grade liability exposure.
- Entertainment:Theme park animatronics and drone shows leverage ROS2 for choreographed multi-agent coordination with lower safety barriers.
Industrial automation holds current volume dominance. Service robotics offers the steepest margin expansion trajectory.
Deployment Model:
Edge computing configurations are climbing the fastest as latency-sensitive applications multiply, though on-premises retains preference in classified defense and regulated healthcare environments.
- On-Premises:Air-gapped installations satisfy defense and pharmaceutical manufacturing requirements where cloud connectivity introduces unacceptable attack surface. NHTSA and FDA pre-market submissions favor locally contained data flows.
- Cloud-Based:Centralized fleet management enables over-the-air updates for warehouse robotics at Amazon and JD.com facilities, though EU GDPR data residency rules constrain cross-border processing.
- Hybrid:Split architectures process time-critical control loops locally while offloading mapping and analytics to remote infrastructure.
- Edge Computing:Nvidia Jetson and Qualcomm RB3 platforms with pre-integrated ROS2 drivers collapse integration overhead for warehouse developers in Shenzhen and Rotterdam.
Edge computing is gaining share fastest. On-premises defends in regulated verticals.
End User:
Manufacturing absorbs the highest absolute middleware spend, while healthcare end-users represent the highest-margin segment due to validation and certification overhead.
- Aerospace:Satellite servicing and UAV swarming demand radiation-hardened compute with deterministic scheduling that ROS2 is adapting for orbital deployment timelines.
- Manufacturing:Collaborative robot installations at BMW Leipzig and Mercedes-Benz Sindelfingen require simultaneous ISO 10218-1, ISO/TS 15066, and machinery directive compliance.
- Healthcare:Surgical navigation and rehabilitation robotics face FDA software-as-medical-device guidance and EU MDR risk-classification tiers that extend validation cycles.
- Education:University curricula in Zurich, Tokyo, and Pittsburgh standardize on ROS2 for robotics engineering training with minimal procurement friction.
Manufacturing dominates current procurement volume. Healthcare represents the premium pricing tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates ROS-Industrial deployment through Fraunhofer IPA consortia, while the United States dominates edge-AI hardware integration through Nvidia's Jetson platform and Amazon warehouse fleets.
United States
Amazon Robotics operates over 750,000 mobile robots across fulfillment centers, driving middleware procurement at scale. FDA software-as-medical-device guidance constrains how ROS-based surgical systems enter regulated healthcare. Pittsburgh and Boston anchor academic robotics clusters where Carnegie Mellon and MIT advance algorithmic frontiers without production-grade liability exposure.
Germany
BMW Leipzig and Mercedes-Benz Sindelfingen require simultaneous ISO 10218-1, ISO/TS 15066, and EU machinery directive compliance for collaborative installations. The EU AI Act's risk-classification tiers compel manufacturers to adopt standardized middleware with audit trails. Stuttgart and Munich system integrators bundle ROS2 with liability insurance and long-term support contracts.
China
JD.com and Alibaba deploy warehouse robotics fleets exceeding 100,000 units, creating concentrated demand for ROS-compatible compute modules. GB standards and MIIT robotics development guidelines shape middleware certification requirements. Shenzhen and Guangzhou hardware manufacturers face 26-40 week lead times for ARM-based SoCs from Taiwan-based foundries.
Japan
FANUC and Yaskawa Electric anchor industrial robot production, evaluating ROS2 against proprietary stacks for next-generation collaborative platforms. METI's Society 5.0 initiative and JIS safety standards influence middleware procurement in manufacturing automation. Nagoya and Osaka automotive clusters drive deterministic real-time requirements for pick-and-place pharmaceutical lines.
South Korea
Hyundai Motor Group and Samsung Electronics pilot ROS2-based autonomous navigation for smart factory deployments. MFDS medical device regulations and KOSHA industrial safety standards constrain healthcare robotics entry. Seoul Capital Area and Busan-Ulsan manufacturing hubs concentrate system integrator talent for DDS configuration and micro-ROS firmware optimization.
Robot Operating System Market Vendor Landscape
United States producers anchor one tier through semiconductor and cloud infrastructure dominance; German and Japanese specialists hold another through precision manufacturing and industrial automation heritage. The vendor base organizes around three strategic archetypes: semiconductor platform vendors hardening edge-AI compute, traditional robotics OEMs retrofitting proprietary stacks with open middleware, and governance foundations ensuring interoperability across heterogeneous deployments. Competitive moves concentrate on strategic partnerships between chip fabricators and system integrators, plus certification investments for safety-critical workloads.
Within the semiconductor platform tier, Nvidia exemplifies edge-AI hardware maturation through Jetson platforms with pre-integrated ROS2 drivers. ABB Robotics represents industrial automation incumbents anchoring RobotStudio environments on ROS2 middleware for factory-floor synchronization. Open Robotics occupies a foundational governance position, ensuring core distribution interoperability across vendor stacks through DDS backbone standardization.
| Leading Market Players |
|---|
| Nvidia |
| ABB Robotics |
| Open Robotics |
| KUKA |
| FANUC |
| Amazon Robotics |
| Universal Robots |
| Intrinsic |
| Intel |
| Others |
Supply Flow & Price Mechanics
ARM-based SoC spot prices from Taiwan-based foundries cascade through three distinct pricing tiers for ROS-compatible compute modules, compressing margins for system integrators while premium-certified middleware stacks command sustained markups.
Pricing Analysis
Distributor margins for ROS2 middleware typically range between 15-25% for standard deployments, collapsing to single digits for high-volume warehouse robotics contracts at Amazon-scale buyers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical stacks from industrial-grade distributions and unsupported academic packages. Pricing pressure stems from Nvidia's Jetson platform bundling ROS2 drivers at zero incremental cost, eroding standalone middleware licensing value. Automotive OEMs in Stuttgart and Munich exhibit lowest price sensitivity due to bundled liability insurance requirements, while Indian electronics contract manufacturers face acute cost compression.
Supply Chain Analysis
Dual-sourcing requirements for safety-critical deployments compel German automotive OEMs to qualify both Taiwan Semiconductor Manufacturing and Samsung Foundry for ARM-based compute modules, though 26-40 week lead times persist. The supply chain draws from Taiwan for SoC fabrication, Germany for precision mechanical components, and China for sensor module assembly. Single-source vulnerability concentrates in advanced node semiconductor manufacturing. Distribution runs through direct OEM relationships for Tier-1 automotive suppliers, with cloud-based marketplace procurement gaining share among startup robotics developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the Robot Operating System Market rests on certification cost amortization across expanding deployment volumes, particularly as EU AI Act compliance documentation becomes table stakes for collaborative manufacturing procurement.
For Market Incumbents: Anticipate regulatory fragmentation between EU AI Act tiers and FDA software-as-medical-device pathways by pre-certifying multiple stack variants. Defend position through backward integration into edge-AI hardware reference designs, anchoring system integrators on proprietary compute module form factors. Prioritize micro-ROS firmware optimization talent acquisition in Seoul and Munich consulting pools.
For New Entrants and Emerging Players: Cloud-native deployment channels offer the lowest customer acquisition friction for mid-sized warehouse operators seeking over-the-air fleet management. Target healthcare service robotics for first-mover advantage in ISO 13482 certification pathways, where incumbent documentation gaps persist. Pursue simulation-first go-to-market positioning through Unity or Unreal Engine integration partnerships.
For Investors and Strategic Acquirers: Asymmetric upside sits with middleware vendors achieving deterministic real-time certification parity with proprietary RTOS stacks. Long-term viability hinges on sustained ROS2 governance influence and recurring support contract attach rates. Watch for inflection in FDA 510(k) clearance velocity for ROS-based surgical navigation systems.
| Strategic Initiative | Industry Significance |
|---|---|
| ROS2 Safety Certification Investment | Achieves IEC 61508 SIL-2 alignment, unlocking pharmaceutical pick-and-place lines at Merck and Roche facilities. |
| Micro-ROS Firmware Optimization | Enables brake-by-wire integration at Hyundai Mobis, collapsing separation between vehicle dynamics and autonomy stacks. |
| Digital Twin Platform Integration | Reduces physical commissioning costs for BMW Leipzig through 10 million virtual mile validation guarantees. |
| Healthcare Liability Insurance Bundling | Transforms middleware procurement into managed service relationships for German patient-handling robot deployments. |
| Edge-AI Hardware Reference Design | Locks in system integrator dependency through Nvidia Jetson-compatible module form factor standardization. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with robotics platform engineers, automotive OEM procurement leads, system integrator technical directors, and healthcare regulatory affairs specialists with secondary validation against SEC filings from semiconductor vendors, Open Robotics governance documentation, EU AI Act implementation guidance, and FDA software-as-medical-device guidance documents. Bottom-up deployment forecasts triangulated against top-down middleware spend estimates from industrial automation consortia.
Segment-weighting approaches distributed value across middleware architecture, deployment model, application vertical, and end-user industry, with particular attention to certification tier differentiation. CAGRs derived from logistic adoption curves fitted to warehouse robotics fleet deployment data and automotive collaborative robot installation trajectories. Modeling incorporated Taiwan foundry capacity constraints, EU Cyber Resilience Act vulnerability disclosure timelines, and German automotive clustering effects across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for deterministic real-time middleware certification would alter the outlook substantially. Deviation in Taiwan semiconductor manufacturing capacity allocation or EU AI Act enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
Clean Room Robot Market
Robotics and Automation
Europe AUV and ROV Market
Robotics and Automation
Cognitive Robotic Process Automation Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
UV-C Disinfection Robots Market
Robotics and Automation
Robotics and Automation Actuators Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
India Cloud Robotics Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Inspection Robots Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
Smart Lawn Robot Market
Robotics and Automation
Automotive Robotics Market
Robotics and Automation
Asia-Pacific Logistics Robotics Market
Robotics and Automation
Global Security Robots Market