
 Japan Agricultural Robot Market | 2026-2036
Japan Agricultural Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Agricultural Robot Market Intelligence
A widening capital-intensity gap between industrial conglomerates and emerging specialists is rotating competitive dynamics across the sector. Kubota Corporation leverages its entrenched dealer network and tractor manufacturing scale to dominate hardware-software integration for broadacre applications. Inaho Corporation competes through compact AI-vision systems purpose-built for greenhouse vegetable harvesting. FANUC Corporation anchors its position via precision servo-motor supply chains that underpin robotic arm reliability in uneven field terrain.
Japan agricultural robots comprise electromechanical systems integrating machine vision, GPS guidance, and articulated manipulators to execute crop-specific tasks with minimal human intervention. These platforms typically operate at sub-2-centimeter positioning accuracy and incorporate LiDAR or multispectral sensors for real-time plant health assessment, primarily serving commercial farms facing acute seasonal labor shortages. Harvesting robots currently occupy the largest product category as strawberry and tomato picking automation commands premium deployment budgets from large agribusinesses. AI-powered technology segments are expanding fastest where deep-learning models trained on domestic cultivar morphology enable selective fruit removal without bruising. Monitoring robots sustain narrower margin pools due to commoditized drone hardware, though subscription-based analytics layers partially offset equipment commoditization.
METI's Smart Agriculture promotion framework, JIS standards for agricultural machinery safety, and PMDA guidelines for data-driven crop protection systems collectively shape product certification timelines and R&D budget allocations. Compliance with JIS B 9205 collision-avoidance protocols adds six to twelve months to development cycles but creates defensible barriers against lower-specification imports. Stakeholders must weigh METI subsidy eligibility requirements against the capital demands of proprietary AI training datasets as domestic cultivar diversity limits transferability of foreign machine-learning models.
Market Dynamics
Structural transformation in Japanese agriculture centers on METI's subsidy-driven mechanization mandate intersecting with acute demographic contraction in rural prefectures, forcing capital deployment toward autonomous systems that substitute for vanishing seasonal labor pools.
Growth Catalysts
- Smart Agriculture Promotion Framework:METI's subsidy programs covering up to half of robot acquisition costs for certified farms accelerate capital deployment across Hokkaido and Tohoku vegetable operations.
- Domestic cultivar AI training:Deep-learning models trained on Japanese strawberry and tomato morphology enable selective harvesting without bruising, unlocking premium pricing for high-value greenhouse producers.
- Hokkaido labor shortages:Severe seasonal worker deficits in Japan's primary vegetable belt drive urgent mechanization timelines for planting and weeding operations.
Market Restraints
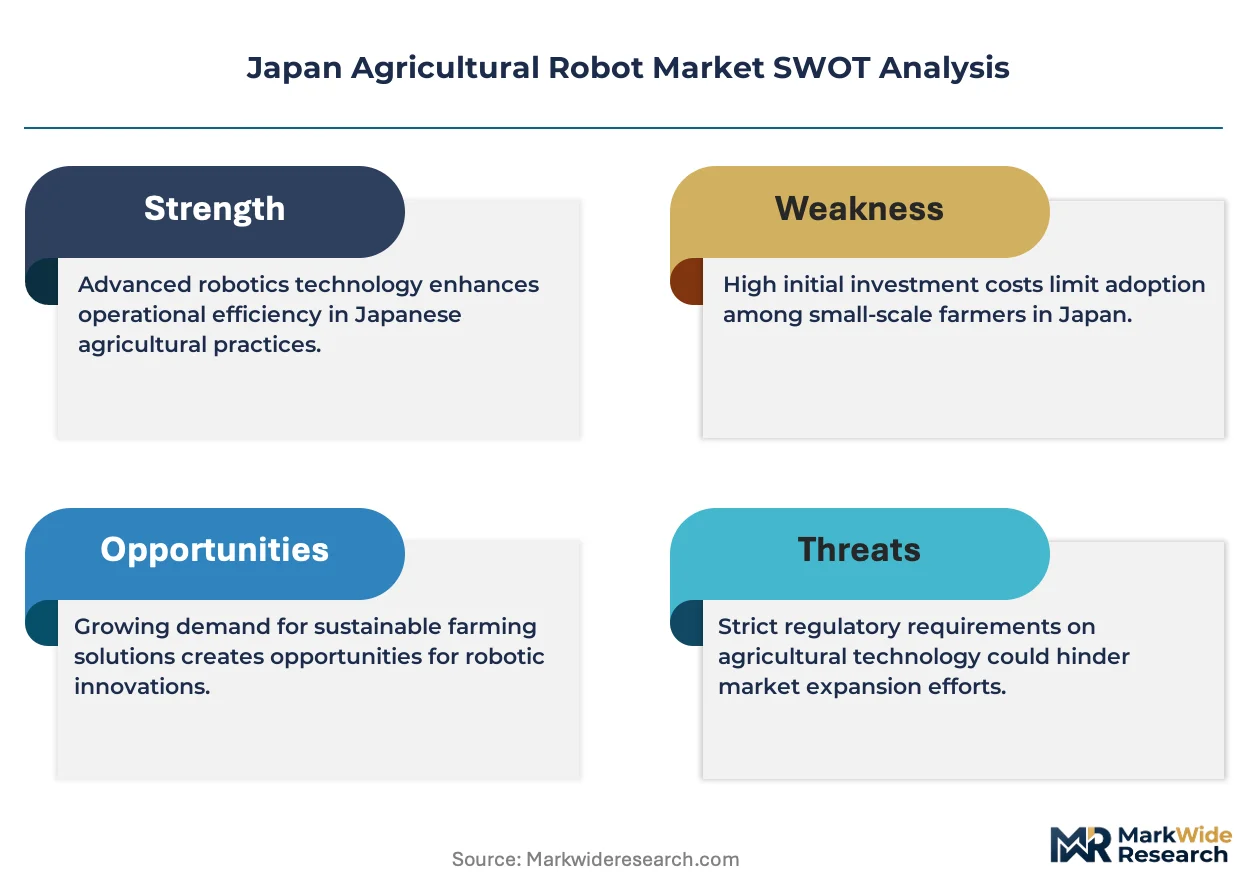
- Proprietary sensor costs:LiDAR and multispectral imaging components remain import-dependent, exposing margins to yen volatility and concentrated East Asian supply chains.
- JIS B 9205 certification timelines:Collision-avoidance protocol compliance adds six to twelve months to product development, compressing first-mover windows against faster-certifying imports.
- Limited cultivar transferability:Machine-learning models trained on foreign crop varieties fail on Japan's domestic strawberry and tomato breeds, forcing costly dataset rebuilding.
Strategic Opportunities
- Kyushu rice paddy automation:Underpenetrated precision weeding demand in southwestern Japan's dominant rice belt offers expansion terrain beyond Hokkaido's saturated vegetable focus.
- Subscription analytics layering:Monitoring robot hardware commoditization creates opening for recurring revenue models through plant-health data services sold to agricultural cooperatives.
- Greenhouse-humanoid convergence:Integration of collaborative robotic arms with existing protected-culture infrastructure addresses Japan's protected horticulture sector without field-terrain complexity.
Industry Challenges
- Mechatronics talent scarcity:Shortage of engineers combining agricultural domain knowledge with robotics integration expertise constrains deployment velocity for complex harvesting platforms.
- Legacy farm management system integration:Proprietary data protocols from incumbent tractor manufacturers block seamless connectivity for third-party robot fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Agricultural Robot Market |
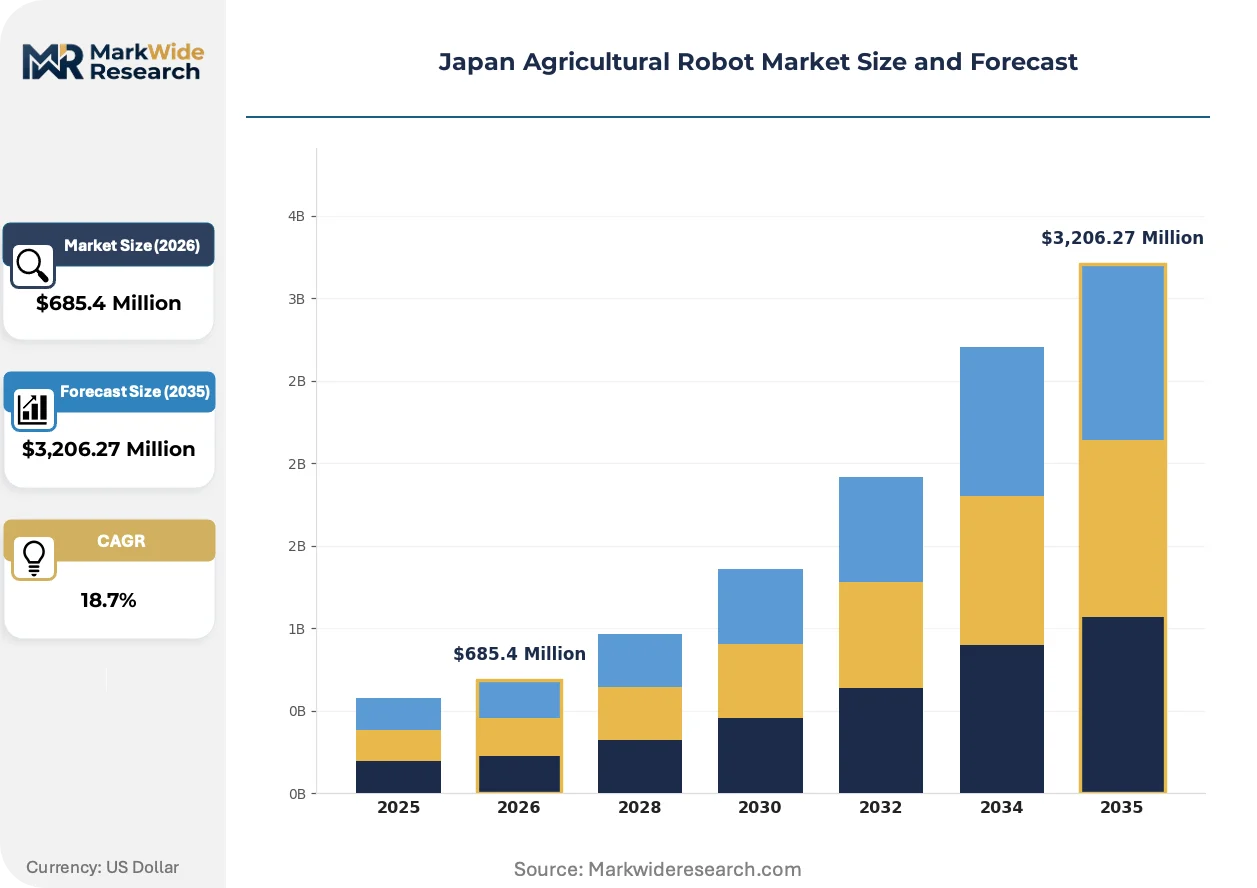
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harvesting Robots, Weeding Robots, Planting Robots, Monitoring Robots Technology: AI-Powered, GPS-Based, Sensor-Driven, Autonomous End User: Farm Operators, Agribusinesses, Research Institutions, Government Agencies Installation: On-Farm, Centralized, Decentralized, Remote |
| Companies Covered | Kubota Corporation, Spread Corporation, DENSO Corporation, Yanmar Holdings Co., Ltd., Iseki & Co., Ltd., FANUC Corporation, Omron Corporation, Inaho Corporation, Yaskawa Electric Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Agricultural Robot Market Strategic Shifts & Innovations
Active reshaping of Japan's agricultural robot sector stems from three intersecting vectors: hardware-software integration complexity, regulatory acceleration of safety certification, and evolving procurement relationships between equipment vendors and agricultural cooperatives.
Machine vision architectures for fruit recognition are bifurcating between high-cost stereo-camera arrays for premium strawberry operations and monocular depth-estimation systems for commodity tomato harvesting. Large agribusinesses in Ibaraki Prefecture deploy the former for export-grade cultivars, while regional cooperatives adopt the latter for domestic-market volumes. This technical split is compressing mid-tier vendor margins as buyers polarize toward performance extremes.
METI's 2023 revision to Smart Agriculture implementation guidelines tightens data-localization requirements for crop-protection algorithms processed through cloud-connected robots. The policy forces foreign platform vendors to establish domestic server infrastructure or partner with local IT providers, raising operational barriers for non-Japanese competitors. Domestic manufacturers with existing domestic cloud partnerships capture accelerated certification timelines under the revised framework.
Agricultural cooperatives are consolidating equipment procurement through prefecture-level purchasing consortiums, displacing individual farm direct sales that historically dominated robot distribution. This buyer concentration shifts negotiation leverage toward volume-discount structures and bundled service contracts. The transformation is most visible in Gunma and Nagano prefectures, where vegetable-growing cooperatives now negotiate fleet-wide maintenance agreements rather than per-unit hardware purchases.
Japan Agricultural Robot Market Segmentation
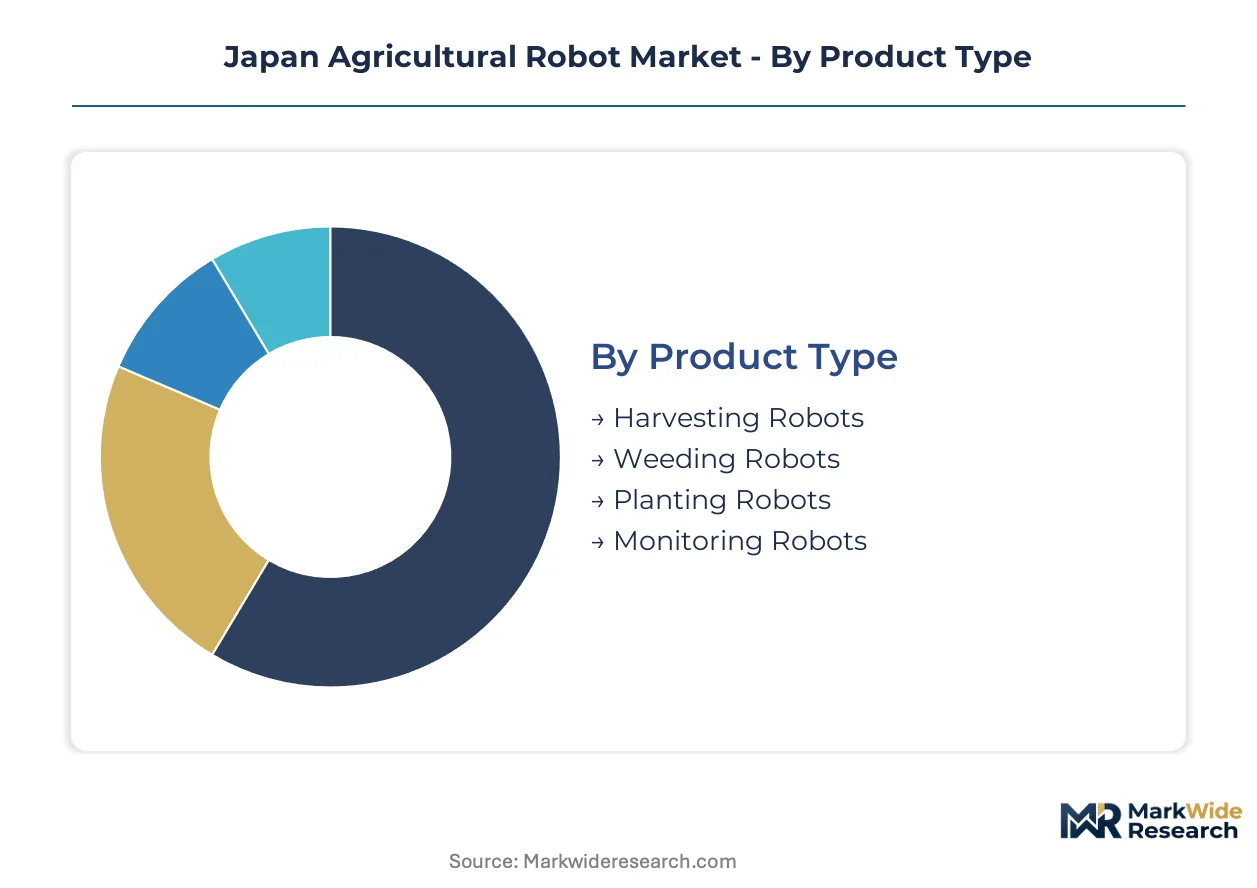
Segmentation in Japan's agricultural robot market reveals how METI certification requirements and prefectural subsidy structures concentrate procurement around specific technology configurations. Product and technology categories intersect with installation approaches to determine capital deployment timelines and operational complexity for Hokkaido vegetable operations versus Kyushu rice belt deployments.
Product Type:
METI's Smart Agriculture subsidy tiers differentiate reimbursement rates across functional categories, with harvesting platforms commanding premium certification pathways under JIS B 9205 collision-avoidance protocols.
- Harvesting Robots:Articulated manipulator systems integrate stereo-camera arrays and soft-grip end-effectors for selective fruit removal. Large agribusinesses in Ibaraki Prefecture deploy these for export-grade strawberry cultivars where bruise-free handling justifies capital intensity against acute seasonal labor shortages.
- Weeding Robots:Precision mechanical and thermal systems operate at sub-2-centimeter GPS accuracy for intra-row cultivation. Kyushu's underpenetrated rice paddy belt drives urgent demand as demographic contraction eliminates manual weeding labor pools across Fukuoka and Kumamoto prefectures.
- Planting Robots:Automated seeding and transplanting platforms reduce labor dependency for vegetable operations.
- Monitoring Robots:Drone and ground-based sensor platforms deliver plant-health analytics through subscription models to agricultural cooperatives.
Established volume favors harvesting robots; emerging adoption favors weeding robots.
Technology:
Technology selection determines development cost structures and data-localization compliance under METI's revised Smart Agriculture guidelines.
- AI-Powered:Deep-learning models trained on domestic strawberry and tomato morphology enable selective harvesting without bruising. Domestic manufacturers with existing cloud partnerships capture accelerated certification timelines under data-localization requirements that force foreign vendors into costly infrastructure investments.
- Autonomous:Self-navigating platforms integrate LiDAR, multispectral imaging, and real-time path planning for unstructured field terrain. These systems face six-to-twelve-month JIS B 9205 certification extensions that compress first-mover windows against faster-certifying import alternatives.
- GPS-Based:RTK-Guidance systems provide centimeter-level positioning for broadacre mechanization.
- Sensor-Driven:Multispectral and thermal detection platforms support crop protection decisions.
AI-powered systems are climbing the fastest; GPS-based installations retain the largest installed base.
End User:
Procurement concentration through prefecture-level purchasing consortiums restructures buyer power across end-user categories.
- Agribusinesses:Large-scale vegetable producers in Hokkaido and Ibaraki deploy premium strawberry harvesting systems with integrated hardware-software stacks. Volume-discount negotiations and fleet-wide maintenance agreements displace per-unit purchasing as Gunma and Nagano cooperatives consolidate equipment procurement.
- Farm Operators:Individual growers access subsidized platforms through JA agricultural cooperative financing structures. METI's half-cost reimbursement programs lower capital barriers for certified farms in Tohoku vegetable operations facing severe seasonal worker deficits.
- Research Institutions:Universities and national agriculture centers validate cultivar-specific training datasets.
- Government Agencies:Prefectural governments deploy demonstration units for technology diffusion programs.
Direct procurement favors agribusinesses; subsidy-mediated access favors farm operators.
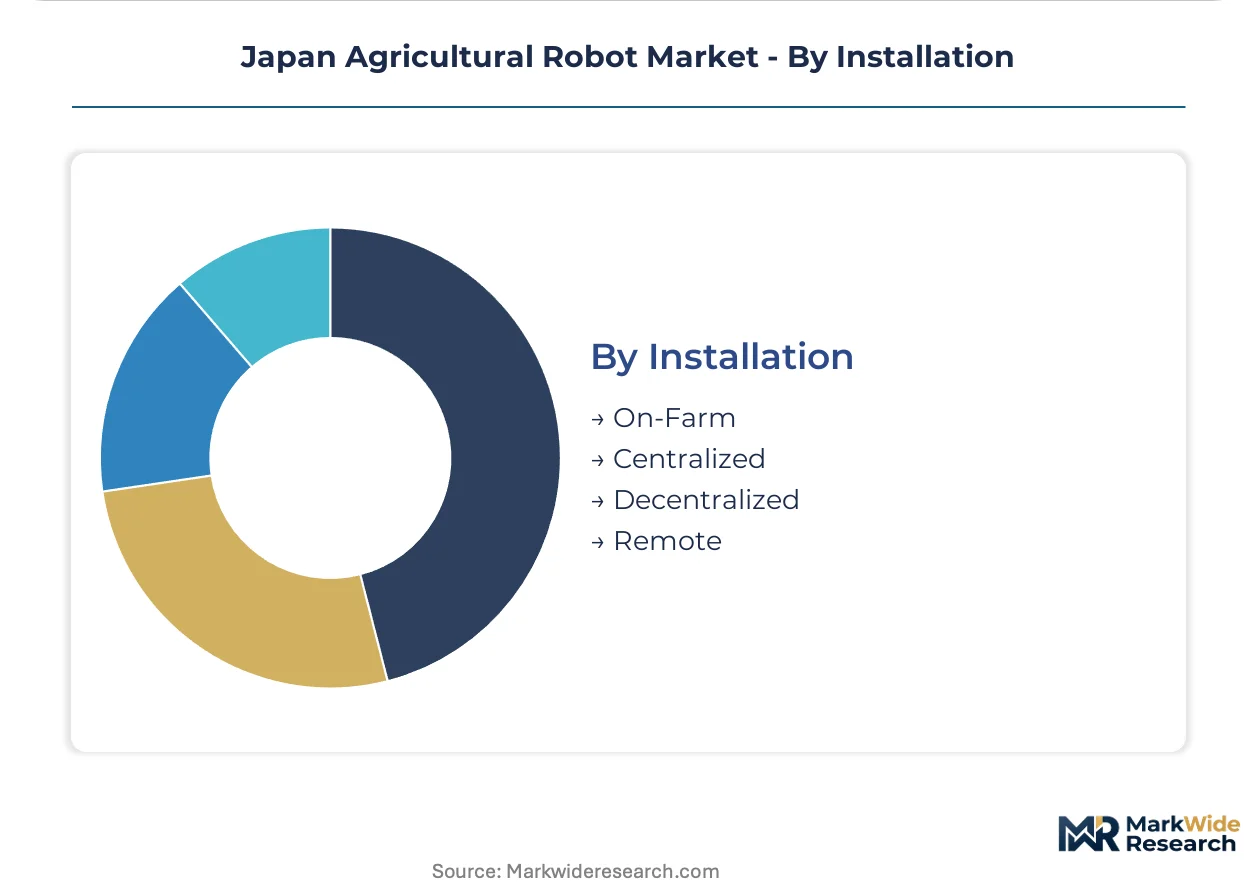
Installation:
Installation architecture determines connectivity requirements and data governance compliance under tightened cloud-processing regulations.
- On-Farm:Edge-computing configurations process crop-protection algorithms locally without cloud transmission. These architectures satisfy METI's data-localization mandates while avoiding latency dependencies for real-time collision avoidance in greenhouse environments.
- Centralized:Hub-and-spoke models aggregate sensor data at cooperative processing centers. Regional vegetable-growing cooperatives in Gunma and Nagano prefectures favor this approach for subscription-based plant-health analytics that offset hardware commoditization.
- Decentralized:Peer-to-peer networked devices share operational data across farm clusters.
- Remote:Cloud-dependent architectures face operational barriers from revised Smart Agriculture guidelines.
Regulatory compliance favors on-farm installation; recurring revenue potential favors centralized deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hokkaido's vegetable belt deploys harvesting robots for labor substitution, while Kyushu's rice paddies prioritize precision weeding systems. Tohoku operations balance subsidy access against terrain complexity. Sub-regional specialization patterns reflect divergent crop economics and METI certification timelines.
Hokkaido
Large-scale vegetable producers deploy strawberry and tomato harvesting robots to offset acute seasonal worker deficits. METI's Smart Agriculture subsidies cover half of acquisition costs for certified farms. The Kamikawa and Tokachi sub-regions concentrate premium greenhouse operations where bruise-free handling justifies capital intensity.
Kyushu
Rice paddy automation demand clusters around precision weeding robots operating at sub-2-centimeter GPS accuracy. JIS B 9205 collision-avoidance protocols extend certification timelines for autonomous platforms. Fukuoka and Kumamoto prefectures face urgent mechanization pressure as manual weeding labor pools contract.
Tohoku
Vegetable operations combine subsidy-mediated robot access with challenging terrain constraints. Prefectural governments deploy demonstration units for technology diffusion programs. Iwate and Aomori prefectures balance METI reimbursement eligibility against the capital demands of proprietary AI training datasets.
Kanto
Ibaraki Prefecture's large agribusinesses deploy stereo-camera array systems for export-grade strawberry cultivars. Volume-discount negotiations through prefecture-level purchasing consortiums displace per-unit hardware sales. Gunma and Saitama cooperatives consolidate fleet-wide maintenance agreements.
Kansai
Osaka-based industrial conglomerates supply precision servo-motor components for robotic arm reliability. Manufacturing scale advantages support hardware-software integration for broadacre applications. Kyoto and Hyogo prefectures host research institutions validating cultivar-specific training datasets.
Japan Agricultural Robot Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with mid-scale manufacturers occupying intermediate positions. The upper tier commands dealer networks and tractor manufacturing scale. Specialist competitors deploy compact AI-vision systems for protected-culture environments. Dominant competitive moves include backward integration into precision component supply chains and strategic partnerships with agricultural cooperatives for fleet procurement consolidation.
Among Japan-based fabricators, Kubota Corporation exemplifies the integrated leader archetype through entrenched distribution infrastructure. Inaho Corporation occupies a specialist position purpose-built for greenhouse vegetable harvesting. FANUC Corporation anchors the precision component tier via servo-motor supply chain control. These three represent distinct strategic postures within METI's subsidy-driven mechanization framework.
| Leading Market Players |
|---|
| Kubota Corporation |
| Spread Corporation |
| DENSO Corporation |
| Yanmar Holdings Co., Ltd. |
| Iseki & Co., Ltd. |
| FANUC Corporation |
| Omron Corporation |
| Inaho Corporation |
| Yaskawa Electric Corporation |
| Others |
Cost & Logistics Intelligence
JIS B 9205 collision-avoidance certification gates both supplier qualification and price stratification simultaneously, compressing first-mover premiums for domestic manufacturers while extending development timelines that protect incumbent hardware margins against faster-certifying imports.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between agricultural cooperatives and established manufacturers, displacing spot-market transactions as Gunma and Nagano prefectures consolidate fleet-wide maintenance agreements. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified harvesting platforms from uncertified monitoring drones and refurbished legacy equipment. Cost compression in mid-tier autonomous systems is intensifying because agricultural cooperatives now negotiate volume-discount structures rather than per-unit purchases. Smallholder farm operators accessing METI's half-cost reimbursement programs exhibit highest price sensitivity, while Ibaraki Prefecture's large agribusinesses prioritize bruise-free handling performance over capital outlay.
Supply Chain Analysis
Strategic stockpiling of LiDAR and multispectral imaging components dominates inventory strategy as yen volatility exposes margins to concentrated East Asian supply chains. Precision servo-motors and AI-vision chipsets draw from Japan, Taiwan, and South Korean fabrication facilities, with soft-grip end-effector polymers and RTK-GPS modules resting on German and Swiss specialty suppliers. Single-source vulnerability concentrates in high-resolution stereo-camera arrays where domestic cultivar training datasets require proprietary sensor calibration. Distribution runs through prefecture-level purchasing consortiums that displace individual farm direct sales, channeling hardware-software bundles through JA agricultural cooperative financing structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around service-layer gaps where incumbent tractor manufacturers under-serve greenhouse-humanoid convergence applications, as protected horticulture operators demand collaborative robotic arms without field-terrain complexity.
For Market Incumbents: Fortify dealer network control through backward integration into precision servo-motor supply chains, countering FANUC Corporation's component-tier dominance while accelerating JIS B 9205 certification timelines to compress emerging specialist windows. Channel consolidation by agricultural cooperatives threatens per-unit margin structures; preemptive fleet-maintenance bundling locks in multi-year offtake relationships before procurement concentration hardens. For New Entrants and Emerging Players: Subscription analytics layering for plant-health data services represents the most penetrable white-space target, as monitoring robot hardware commoditization creates recurring revenue openings that offset equipment margin compression. Kyushu's underpenetrated rice paddy belt offers geographic expansion terrain beyond Hokkaido's saturated vegetable focus, with precision weeding demand accelerating as manual labor pools contract across Fukuoka and Kumamoto prefectures. Partner with domestic IT providers to satisfy METI's data-localization mandates without costly infrastructure buildout. For Investors and Strategic Acquirers: METI's 2023 Smart Agriculture guideline revision reshapes the acquisition landscape by forcing foreign platform vendors into domestic server partnerships, elevating valuations for domestic manufacturers with existing cloud infrastructure. Long-term viability centers on AI training dataset exclusivity for domestic strawberry and tomato cultivars where foreign machine-learning models fail. Acquisition target archetype: compact AI-vision specialists with greenhouse deployment track records and established agricultural cooperative relationships. Signal to monitor: prefecture-level purchasing consortium formation velocity in Tohoku vegetable operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Captures servo-motor margins that FANUC Corporation currently extracts from robotic arm manufacturers. |
| Domestic Cloud Infrastructure Partnership | Satisfies METI data-localization mandates that foreign competitors struggle to meet under revised guidelines. |
| Cultivar-Specific AI Dataset Development | Builds non-transferable training moats around Japanese strawberry and tomato morphology that foreign models cannot replicate. |
| Fleet-Wide Maintenance Contracting | Locks in recurring revenue streams as Gunma and Nagano cooperatives displace per-unit hardware purchasing. |
| Greenhouse-Humanoid Convergence Platform | Addresses protected horticulture demand without JIS B 9205 field-terrain certification delays. |
Research Approach
Initial hypotheses were tested against primary input from agricultural cooperative procurement directors, robotics integration engineers at greenhouse operations, METI subsidy program administrators, and precision component sourcing managers, then refined through secondary validation against METI Smart Agriculture implementation reports, JIS B 9205 certification filings, JA Zenchu cooperative equipment procurement databases, and customs records for LiDAR and multispectral imaging imports. Bottom-up triangulation across prefecture-level deployment data converged with top-down analysis of manufacturer revenue disclosures.
Variance-decomposition framing separated volume drivers across the projection horizon by product type, technology architecture, end-user procurement channel, and installation configuration, with CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Rice paddy automation penetration rates in Kyushu and greenhouse harvesting adoption curves in Ibaraki Prefecture supplied industry-specific forecast inputs.
Underlying assumptions cover METI subsidy continuation at current reimbursement tiers, JIS certification timeline stability, and yen exchange rate bands, with deviation risk concentrated in agricultural cooperative consolidation velocity and LiDAR supply chain disruption. Revision becomes warranted when prefecture-level purchasing consortium formation accelerates beyond modeled thresholds or data-localization enforcement tightens unexpectedly.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
Global Medical Telepresence Robot Market
Robotics and Automation
Personal Robots Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Indonesia Robotics Market
Robotics and Automation
Bionic Glove's Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Global Smart Robots Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Global Security Robots Market
Robotics and Automation
Hospitality Robots Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Long-Range Drone Package Delivery Market