
 Global Machine Vision and Vision Guided Robotics Market | 2026-2036
Global Machine Vision and Vision Guided Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Machine Vision and Vision Guided Robotics Market Outlook
Multi-source procurement of machine vision components is shifting toward vertically integrated supply chains as OEMs seek tighter quality control over sensor-to-software stacks. Cognex Corporation leverages captive semiconductor sourcing to protect margin pools in high-speed inspection. Keyence Corporation sustains direct sales channels across Asia-Pacific manufacturing hubs. Basler AG anchors European demand through specialized camera architectures for medical and automotive qualification.
Machine vision and vision guided robotics denotes integrated electro-optical systems that capture, process, and interpret visual data to guide robotic actuation, typically operating at frame rates exceeding 100 fps with sub-pixel measurement accuracy for closed-loop industrial automation. The technology serves primary commercial purposes in defect detection, dimensional verification, and real-time robotic path correction across high-throughput production environments. Camera and processing unit hardware commands the largest installed base, while deep learning software layers capture expanding margin pools as customers prioritize adaptive inspection algorithms over rule-based configurations. Automotive end-use applications retain the highest average selling prices due to safety-critical validation requirements, whereas electronics manufacturing drives volume deployment of compact 2D vision systems.
FDA qualification pathways for machine vision in medical device manufacturing, EU AI Act conformity requirements for autonomous decision systems, and ISO 10218 safety standards for collaborative robots collectively elevate compliance costs while creating barriers for non-validated suppliers. China's GB standard harmonization with IEC vision system protocols further fragments certification requirements for multinational deployments. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional product variants or unified global platforms deliver superior capital efficiency.
Market Dynamics
Deep learning inference is decentralizing from centralized server farms to edge-embedded vision processors, collapsing latency requirements for real-time robotic guidance while fragmenting the traditional camera-processor hardware stack.
Growth Catalysts
- EU AI Act Conformity Requirements:Mandatory algorithmic transparency for autonomous inspection systems is accelerating replacement cycles of legacy rule-based vision platforms across German and French automotive assembly plants.
- 3D Vision System Deployment:Shenzhen and Shanghai electronics factories are driving volume adoption of structured-light and time-of-flight sensors for sub-millimeter precision in smartphone and semiconductor packaging.
- FDA Device Classification Pathways:Stringent validation protocols for medical device manufacturing are expanding the addressable market for vision-guided robotic systems in pharmaceutical packaging and surgical instrument inspection.
Market Restraints
- Specialized CMOS Sensor Concentration:Japanese and Taiwanese foundries control critical supply nodes for high-speed global shutter sensors, exposing OEMs to single-source risk during capacity constraints.
- ISO 10218 Safety Certification Costs:Collaborative robot integration mandates exhaustive third-party validation, extending deployment timelines and freezing budget allocation for mid-tier manufacturers.
- Laser Diode Price Volatility:Structured-light 3D systems depend on gallium arsenide components whose input costs fluctuate with compound semiconductor wafer availability.
Strategic Opportunities
- India PLI Scheme for Electronics Manufacturing:Production-linked incentives for mobile phone and component assembly are creating greenfield demand for compact 2D vision systems in Noida and Chennai industrial corridors.
- Hyperspectral Imaging Convergence:Fusion of spectral analysis with traditional machine vision is opening quality-control applications in food processing and pharmaceutical raw material verification.
- Direct-to-Factory Software Licensing:Cloud-native vision platforms are bypassing traditional systems integrators, enabling OEMs to capture recurring revenue through subscription-based algorithm updates.
Industry Challenges
- Multi-Jurisdiction Certification Burden:China's GB standard harmonization with IEC protocols forces manufacturers to maintain parallel product variants, complicating inventory management for multinational deployments.
- Optomechanical Integration Talent Scarcity:Shortage of engineers capable of calibrating sub-pixel alignment between lens assemblies and sensor planes is extending commissioning timelines for high-precision installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Machine Vision and Vision Guided Robotics Market |
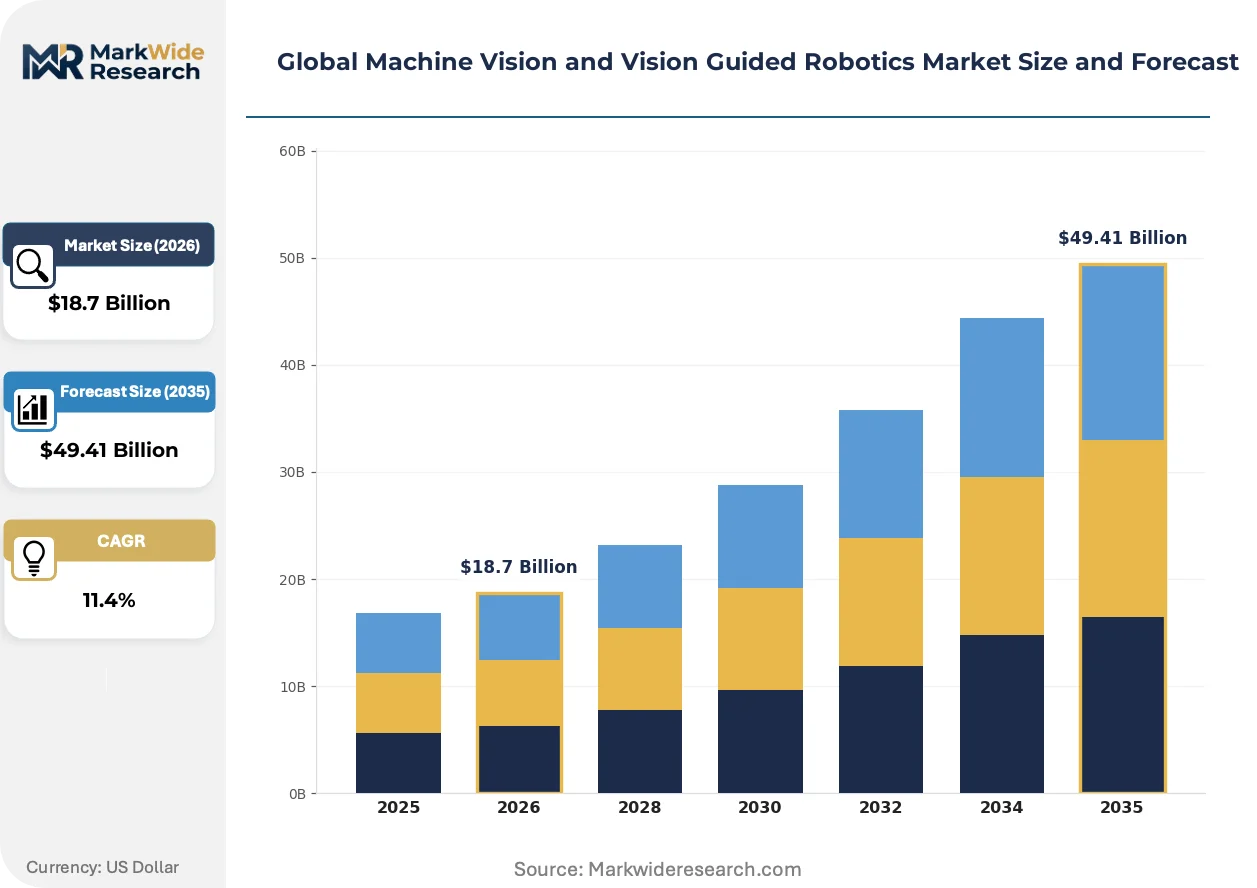
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Lighting Systems, Software, Processing Units Application: Quality Control, Pick and Place, Autonomous Navigation, Inspection End User: Manufacturing, Food & Beverage, Electronics, Automotive Technology: 2D Vision, 3D Vision, Hyperspectral Imaging, Deep Learning |
| Companies Covered | Cognex Corporation, Keyence Corporation, Basler AG, Teledyne Technologies, Omron Corporation, FANUC Corporation, SICK AG, ABB Ltd., Yaskawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Machine Vision and Vision Guided Robotics Market Strategic Shifts
Edge-native processing architectures are collapsing the traditional separation between image capture and algorithmic decision-making, compressing hardware footprints while elevating software monetization potential across industrial automation.
Embedded GPU and NPU silicon is decentralizing inference workloads from factory-floor servers to camera housings and robotic end-effectors. Automotive tier-one suppliers in Germany and Japan are deploying these systems for millisecond-latency weld inspection and adhesive bead verification. The shift is compressing infrastructure requirements while fragmenting the competitive landscape between semiconductor vendors and traditional camera OEMs.
REACH and RoHS substance restrictions are forcing redesigns of LED illumination modules and solder connections in vision system hardware. European medical device manufacturers face cascading compliance costs as MDR documentation requirements extend to subcomponent suppliers. The regulatory pressure is favoring vertically integrated producers with captive materials science capabilities over assembly-focused competitors.
Buyer concentration among battery cell manufacturers and EV assemblers is compressing negotiation cycles and unbundling traditional turnkey service contracts. Korean and Chinese gigafactories are demanding modular hardware with separately priced software licenses, disintermediating regional systems integrators who previously captured margin through opaque bundling. The procurement model shift is most visible in cylindrical cell inspection lines where standardized vision platforms now compete directly with custom-engineered solutions.
Global Machine Vision and Vision Guided Robotics Market Segmentation
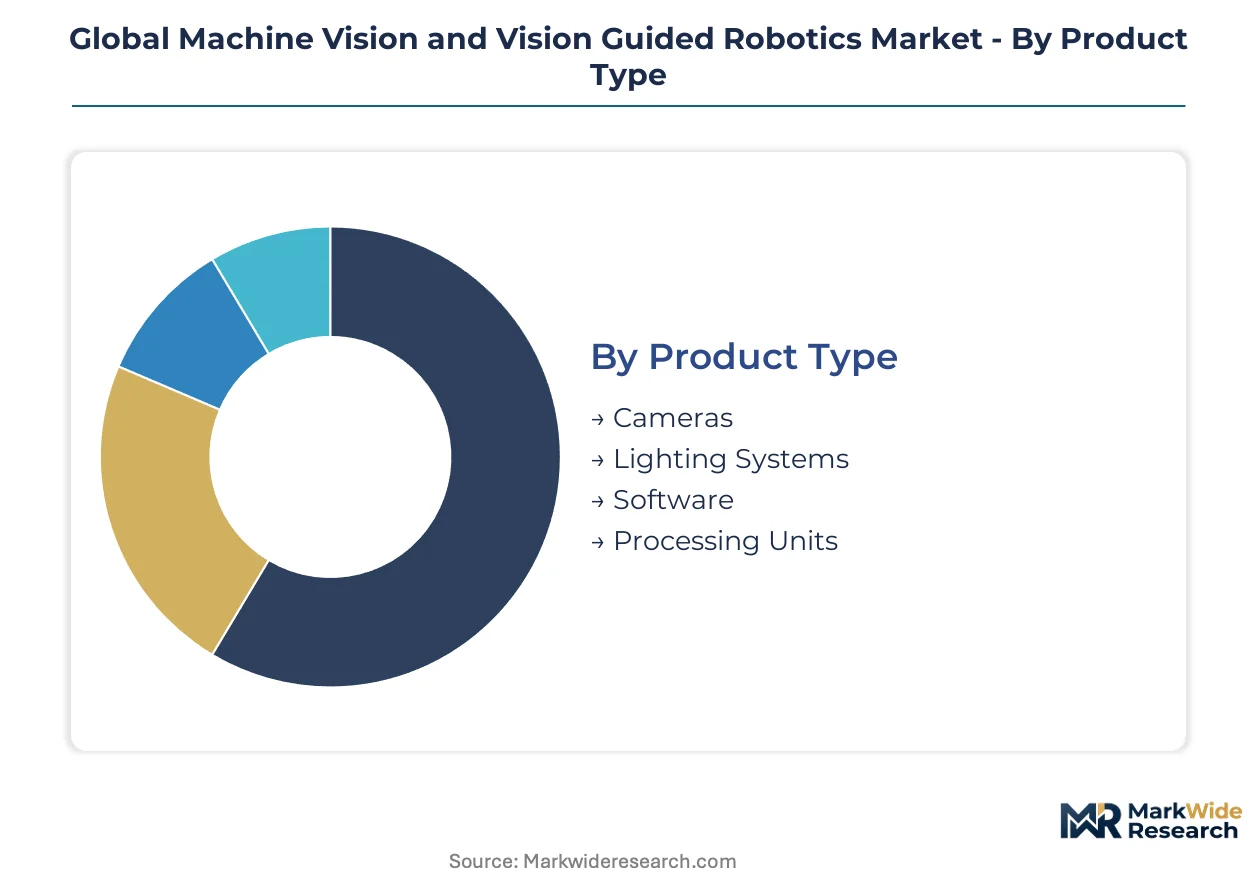
Machine vision segmentation reveals divergent compliance burdens across hardware and software layers, with FDA-validated medical applications and EU AI Act-governed autonomous systems commanding premium certification investments that reshape supplier economics.
Product Type:
Cameras and processing units face the heaviest regulatory layering, with FDA 21 CFR Part 11 validation for pharmaceutical inspection and EU AI Act conformity for autonomous decision systems driving qualification costs that software modules largely avoid.
- Cameras:CMOS and CCD sensor assemblies with global shutter architectures operating above 100 fps for motion capture. German automotive plants and Shenzhen electronics factories concentrate demand for IP67-rated industrial housings that withstand weld spatter and cleanroom chemical exposure. ISO 10218 safety certification for collaborative robot integration extends procurement cycles.
- Processing Units:Edge-embedded GPU and NPU silicon collapsing inference latency from server farms to factory-floor devices. Japanese automotive tier-one suppliers deploy these for millisecond-latency adhesive bead verification, with METI standards governing functional safety in robotic workcells.
- Software:Deep learning frameworks for adaptive defect detection with cloud-native update architectures.
- Lighting Systems:LED and structured-light modules subject to REACH and RoHS substance restrictions requiring materials science redesigns.
Leading the category by volume: Cameras. Growing fastest: Processing Units.
Application:
Cost stratification separates inspection-intensive applications requiring multi-sensor fusion from simpler pick-and-place operations where single-camera configurations dominate.
- Quality Control:Multi-point dimensional verification and surface defect detection using sub-pixel measurement algorithms. Electronics manufacturing in Shanghai and semiconductor packaging facilities in South Korea drive volume deployment of 3D structured-light configurations for sub-millimeter precision. FDA validation pathways extend deployment timelines for medical device producers.
- Inspection:Real-time flaw detection in safety-critical components with full traceability documentation. Automotive assembly lines across Germany, Japan, and the United States mandate these systems for weld integrity and brake component verification under NHTSA and KBA oversight.
- Pick and Place:Robotic bin-picking with 2D or 3D guidance for unstructured object handling.
- Autonomous Navigation:Vision-guided mobile robots for warehouse and factory-floor logistics routing.
Commanding highest average selling prices: Inspection. Expanding most quickly: Quality Control.
End User:
Customer maturity varies sharply, with automotive and electronics sectors driving specification standards that food and beverage and general manufacturing later adopt.
- Automotive:Safety-critical validation requirements for weld inspection, adhesive dispensing verification, and component traceability. German OEMs and Japanese tier-one suppliers specify ISO 10218-compliant collaborative systems with exhaustive third-party certification, sustaining the highest price tiers in the market.
- Electronics:High-throughput precision assembly for smartphone and semiconductor packaging. Shenzhen and Shanghai factories deploy compact 2D and 3D vision systems for PCB inspection and component placement under MIIT-guided GB standard harmonization with IEC protocols.
- Manufacturing:General industrial automation spanning metal fabrication and assembly operations.
- Food & Beverage:Hyperspectral integration for contamination detection and packaging integrity verification under FSSAI and FDA HACCP frameworks.
Generating largest absolute revenue: Automotive. Gaining share fastest: Electronics.
Technology:
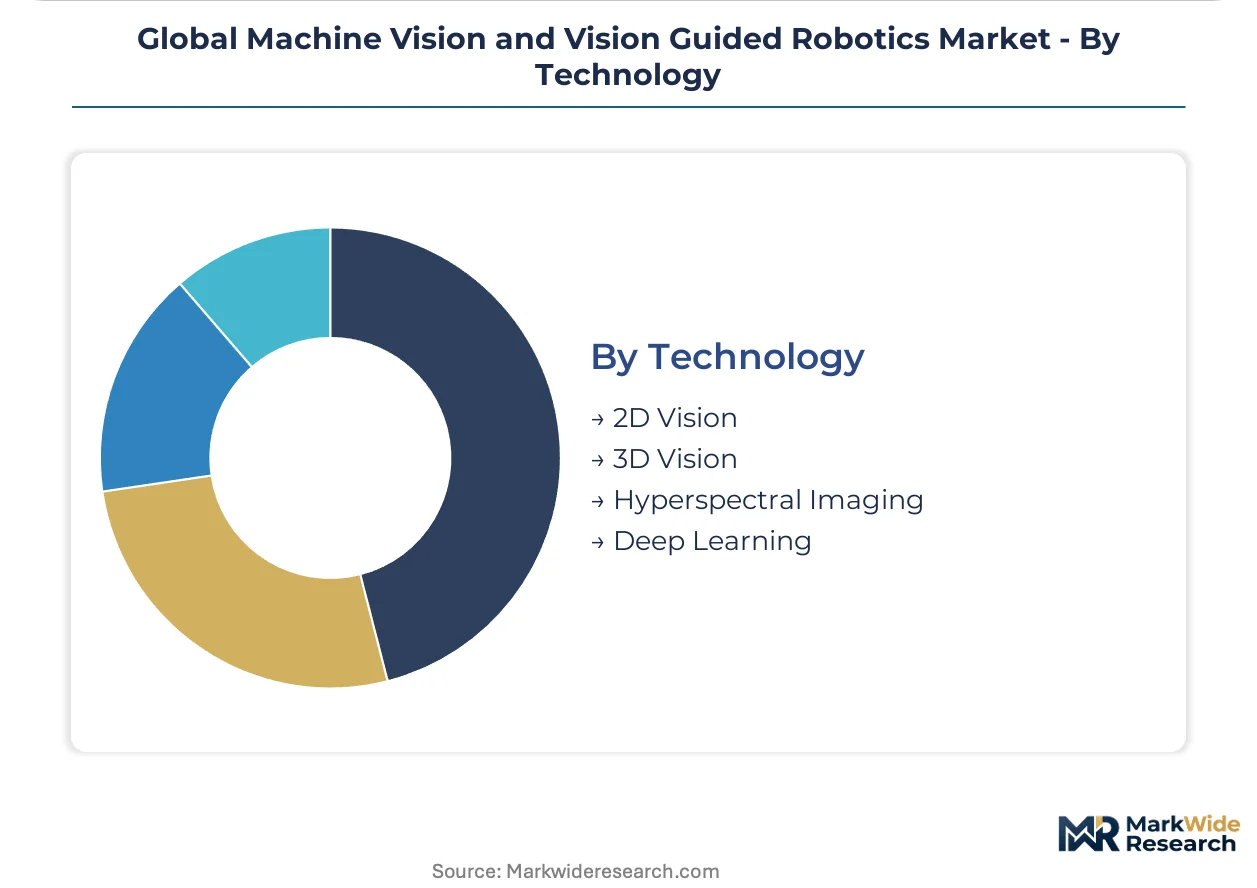
Technology adoption curves reflect hardware-software bundling shifts, with deep learning software layers capturing expanding margin pools as customers prioritize adaptive algorithms over fixed rule-based configurations.
- Deep Learning:Neural network-based defect classification with continuous algorithmic improvement from production data feedback. EU AI Act mandatory transparency requirements are accelerating replacement cycles of legacy rule-based platforms across French and German automotive plants, creating upgrade revenue concentration.
- 3D Vision:Structured-light and time-of-flight sensors for spatial measurement and robotic guidance. Korean battery gigafactories and Chinese EV assemblers drive modular procurement with separately priced software licenses, disintermediating traditional systems integrators.
- 2D Vision:Established monochrome and color imaging for presence-absence detection and barcode reading.
- Hyperspectral Imaging:Spectral analysis fusion opening quality-control applications in pharmaceutical raw material verification and food safety inspection.
Installed base leader: 2D Vision. Steepest expansion trajectory: Deep Learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for machine vision systems concentrates in manufacturing corridors where automotive electrification and precision electronics assembly intersect with tightening regulatory validation frameworks.
United States
Automotive OEMs in Michigan and Ohio are retrofitting weld inspection lines with EU AI Act-compliant vision platforms ahead of export certification requirements. NHTSA safety documentation mandates extend procurement cycles for collaborative robotic systems. Detroit-area tier-one suppliers deploy structured-light 3D sensors for battery pack assembly verification under ISO 10218 safety protocols.
Germany
Bavarian automotive plants accelerate replacement of rule-based inspection systems to satisfy EU AI Act algorithmic transparency requirements. KBA oversight of safety-critical component traceability elevates validation costs for vision-guided robotic welding cells. Stuttgart industrial corridor manufacturers specify METI-harmonized functional safety standards for adhesive dispensing verification systems.
China
Shenzhen and Shanghai electronics factories drive volume deployment of compact 3D vision systems for smartphone and semiconductor packaging precision. MIIT-guided GB standard harmonization with IEC protocols fragments certification requirements for multinational equipment suppliers. Yangtze River Delta battery gigafactories demand modular hardware procurement with separately priced software licenses.
Japan
Nagoya automotive tier-one suppliers deploy edge-embedded GPU processors for millisecond-latency adhesive bead verification. METI standards govern functional safety in robotic workcells producing hybrid vehicle components. Osaka industrial clusters sustain direct sales channel relationships with camera OEMs for high-speed global shutter sensor procurement.
South Korea
Gyeonggi-do battery cell manufacturers compress negotiation cycles for cylindrical cell inspection lines, unbundling traditional turnkey service contracts. MFDS pharmaceutical packaging regulations expand addressable demand for vision-guided robotic systems in Seoul-area medical device production. Busan-Ulsan industrial corridor EV assemblers standardize on modular vision platforms competing with custom-engineered solutions.
Global Machine Vision and Vision Guided Robotics Market Competitive Environment
Backward integration into captive semiconductor sourcing dominates the current landscape as margin protection intensifies. The vendor base separates into three tiers: vertically integrated specialists controlling sensor-to-software stacks, direct-sales channel operators with regional manufacturing proximity, and modular platform providers capturing recurring software revenue. Capacity expansion in edge-embedded processor foundries and strategic partnerships for regulatory pre-certification represent the dominant competitive vectors reshaping supplier economics.
Within the integrated hardware-software tier, Cognex Corporation and Keyence Corporation exemplify divergent channel strategies—one leveraging captive component sourcing, the other sustaining direct factory-floor relationships across Asia-Pacific manufacturing hubs. Basler AG anchors European demand through specialized camera architectures calibrated for medical and automotive qualification requirements. These three entities occupy positions reflecting distinct responses to regulatory fragmentation: unified global platforms versus regional product variants.
| Leading Market Players |
|---|
| Cognex Corporation |
| Keyence Corporation |
| Basler AG |
| Teledyne Technologies |
| Omron Corporation |
| FANUC Corporation |
| SICK AG |
| ABB Ltd. |
| Yaskawa Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
Edge-native processing architectures collapsing inference latency from server farms to factory-floor devices simultaneously compress hardware footprints and concentrate margin capture among semiconductor vendors with captive NPU silicon production. This technological shift fragments the traditional camera-processor hardware stack while elevating software monetization potential, reshaping how OEMs negotiate component costs and service bundling across German automotive plants and Shenzhen electronics corridors.
Pricing Analysis
Warranty and multi-year service contract bundling now separates premium-tier vision system suppliers from competitors offering unbundled hardware-only procurement. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by FDA validation tier and ISO 10218 safety certification completeness. Price erosion runs through mid-tier camera assemblies as Korean battery gigafactories demand modular hardware with separately priced software licenses, unbundling traditional turnkey contracts. Electronics manufacturers in China's eastern manufacturing corridor exhibit highest price sensitivity, while automotive OEMs in Germany and Japan absorb premium pricing for exhaustive third-party validation.
Supply Chain Analysis
Engineering talent scarcity for optomechanical calibration in Germany, Japan, and Taiwan extends commissioning timelines and elevates labor cost components in high-precision installations. Japanese and Taiwanese foundries control critical supply nodes for high-speed global shutter CMOS sensors, exposing OEMs to single-source vulnerability during capacity constraints. The supply chain draws from gallium arsenide wafer production for structured-light laser diodes, with compound semiconductor availability subject to price volatility. Distribution runs through direct sales channels anchored by regional manufacturing proximity, particularly across Asia-Pacific hubs where Keyence Corporation maintains factory-floor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep learning inference decentralization from centralized servers to edge-embedded processors marks a definitive technology-transition phase, displacing legacy rule-based vision platforms across EU AI Act-governed automotive assembly lines.
For Market Incumbents: Acquire captive semiconductor sourcing capabilities to protect margin pools in high-speed inspection segments threatened by modular procurement demands from Korean and Chinese battery manufacturers. Invest in FDA pre-certification pathways for pharmaceutical inspection systems to defend against emerging software-native competitors. Prioritize backward integration into NPU silicon design to maintain differentiation as inference workloads fragment toward camera housings.
For New Entrants and Emerging Players: Begin with cloud-native vision platforms offering subscription-based algorithm updates, targeting India's PLI scheme electronics manufacturing corridors in Noida and Chennai where greenfield demand lacks entrenched supplier relationships. Exploit hyperspectral imaging convergence for food processing and pharmaceutical raw material verification, segments where incumbent hardware-software bundling remains weak. Pursue direct-to-factory software licensing models that bypass traditional systems integrators.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to industrial automation conglomerates seeking edge-AI capabilities, with strategic value accruing to targets with regulatory pre-certification assets across multiple jurisdictions. Five-to-ten year viability favors vertically integrated specialists controlling sensor-to-software stacks over assembly-focused competitors vulnerable to REACH and RoHS compliance cost cascades. Monitor EU AI Act enforcement intensity across German automotive plants as the critical inflection signal for replacement cycle acceleration.
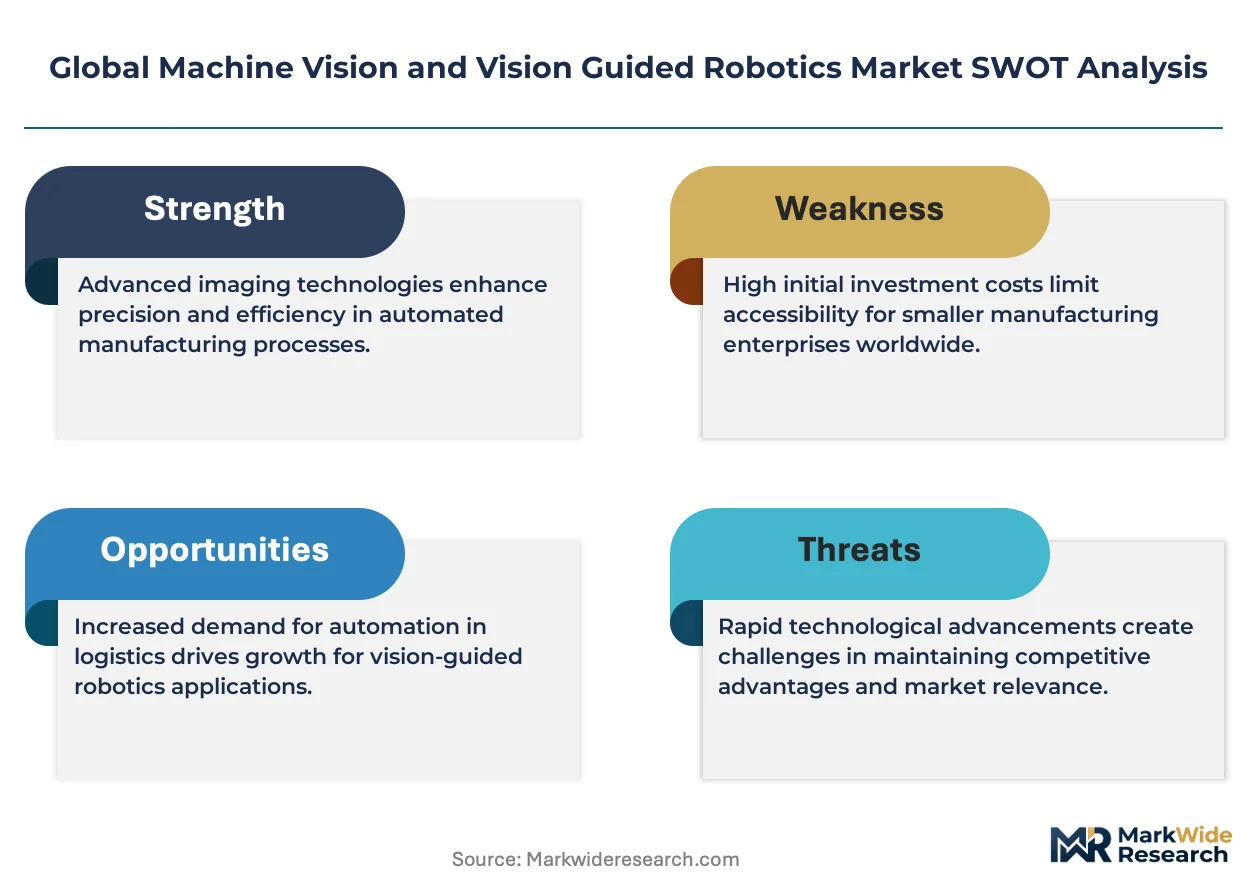
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | FDA 21 CFR Part 11 and EU AI Act conformity create barriers for non-validated suppliers in medical and automotive segments. |
| Captive Semiconductor Sourcing | Backward integration into high-speed global shutter sensor production protects margins during Taiwanese foundry capacity constraints. |
| Cloud-Native Platform Development | Subscription-based algorithm updates enable recurring revenue capture from battery gigafactories demanding modular procurement. |
| Hyperspectral Imaging Integration | Spectral analysis fusion opens quality-control applications in pharmaceutical raw material verification under MFDS oversight. |
| Direct Sales Channel Expansion | Factory-floor relationships across Asia-Pacific manufacturing hubs sustain pricing power against systems integrator disintermediation. |
Study Parameters
Multi-period observation of frame-rate specifications, pixel-density trajectories, and regulatory certification timelines anchored the trend analysis, supplemented by interviews with vision system R&D directors, automotive tier-one supplier procurement leads, pharmaceutical manufacturing engineers, and semiconductor foundry account managers. Secondary validation drew from FDA 510(k) filings, EU AI Act implementation guidance, METI functional safety standards, SEC 10-K disclosures from listed automation suppliers, and MIIT GB standard harmonization documents. Bottom-up unit economics triangulated against top-down manufacturing capacity assessments.
Input-output matrices modeled demand flows across product type, application intensity, end-user maturity, and technology adoption curve dimensions throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macro manufacturing investment cycles. Industry-specific forecast inputs included automotive electrification capex trajectories in Germany and China, plus electronics assembly automation penetration in Vietnam and India.
Regulatory enforcement divergence, compound semiconductor wafer supply disruptions, and collaborative robot safety certification backlogs are the dominant revision risks to modeled projections. Material deviation in any of these triggers warrants pause and re-evaluation of deployment timeline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Gimbal Stabilizers Market
Robotics and Automation
Underwater Exploration Robots Market
Robotics and Automation
Humanoids Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
India Cloud Robotics Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Global Adaptive Robot Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Asia-Pacific Robotics and Automation Actuators Market
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Europe Articulated Robot Market