
 Virtual Companion Care Market | 2026-2036
Virtual Companion Care Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Companion Care Market Analytics
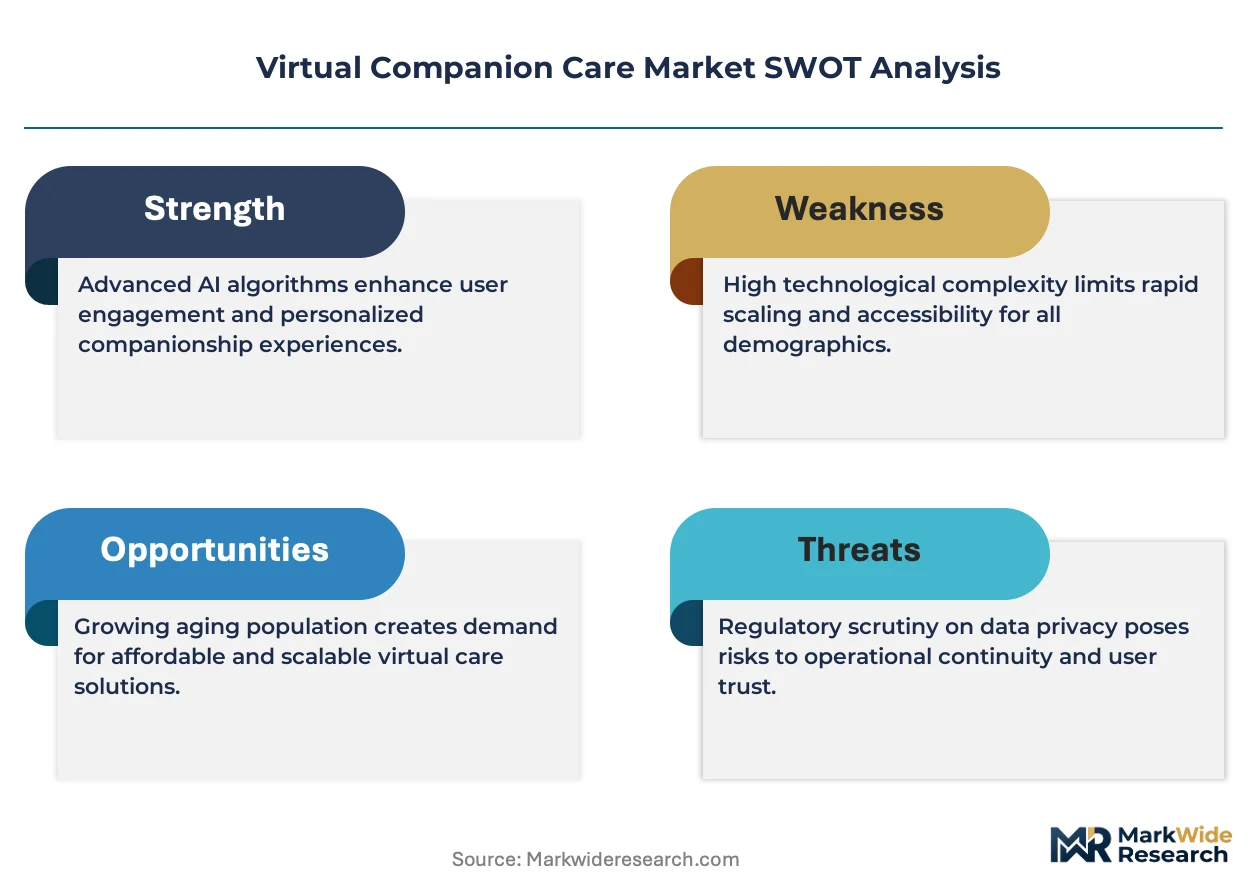
North American telehealth infrastructure is hardening as a supply-side anchor for virtual companion care delivery. Teladoc Health leverages its established payer relationships to sustain platform scalability across chronic care populations. Amwell anchors its position through health system partnerships that embed companion services into existing clinical workflows. HelloRache differentiates by specializing in human-augmented virtual assistance rather than fully automated interactions.
Virtual companion care encompasses AI-driven and human-supported digital interfaces designed to deliver continuous social engagement, health monitoring, and emotional assistance to isolated or vulnerable users, typically operating through natural language processing engines with response latencies under 500 milliseconds. The primary commercial purpose centers on reducing acute care utilization by detecting behavioral deterioration and prompting early intervention. Mobile applications currently lead service delivery due to minimal hardware barriers and rapid deployment cycles, while robotics represents the fastest-expanding segment as tactile interaction capabilities mature. Wearable devices concentrate margin pools through recurring data subscription models tied to biometric streams.
FDA software-as-a-medical-device oversight and HIPAA security rule enforcement shape product architecture decisions, particularly for platforms processing protected health information from home-based sensors. The Federal Communications Commission's rural broadband initiatives indirectly expand addressable markets by reducing connectivity dead zones that previously excluded remote users. Cloud Computing and Machine Learning segments within the technology dimension face escalating compliance costs as OCR audits intensify. Stakeholders must weigh the capital requirements of FDA 510(k) pathways against the pricing power that regulatory clearance confers in Medicare Advantage channel negotiations.
Market Dynamics
Medicare Advantage reimbursement expansion for remote care coordination is compressing sales cycles and forcing platform vendors to rearchitect around HIPAA interoperability mandates.
Growth Catalysts
- FDA Software-as-a-Medical-Device Pathway:Clearance requirements for AI-driven diagnostic features are creating de facto quality barriers that reward compliant incumbents with preferred payer status.
- Senior Living Facility Consolidation:Large operators are mandating unified virtual companion platforms across portfolios, concentrating procurement power with vendors offering enterprise-grade integration.
- Natural Language Processing Latency Compression:Sub-500 millisecond response thresholds now enable real-time emotional calibration, expanding addressable use cases beyond simple reminder functions into crisis intervention.
Market Restraints
- Cloud Infrastructure Concentration:AWS, Microsoft Azure, and Google Cloud control over 80 percent of health-grade compute capacity, exposing vendors to egress cost volatility and regional outage risk.
- Biometric Sensor Supply Bottlenecks:Photoplethysmography chip fabrication concentrates in Taiwan and South Korea, creating input cost instability for wearable-integrated companion systems.
- State-Level Telehealth Licensing Fragmentation:Inconsistent scope-of-practice rules across US jurisdictions force redundant compliance architecture and limit single-deployment scalability.
Strategic Opportunities
- Japan's Super-Aged Society:METI funding for loneliness-mitigation technology creates a $2 billion annual procurement channel with preference for culturally localized interaction protocols.
- Voice-First Interface Convergence:Integration of large language models with ambient sensing hardware enables passive monitoring without explicit user activation, opening institutional adoption in memory care units.
- Rural Broadband Subsidies:FCC Universal Service Fund expansions into connectivity deserts unlock previously excluded Medicare populations in Appalachia and the Mountain West.
Industry Challenges
- Clinical Validation Talent Scarcity:Platform developers struggle to recruit geriatric psychiatrists and behavioral health data scientists capable of training ethically bounded intervention algorithms.
- 510(k) Submission Timeline Compression:FDA review backlogs for software-based therapeutic claims extend product launch windows by 14-22 months, burning runway for venture-backed entrants.
- Electronic Health Record Integration Complexity:Proprietary APIs from Epic, Cerner, and Meditech force costly custom middleware development for each health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Companion Care Market |
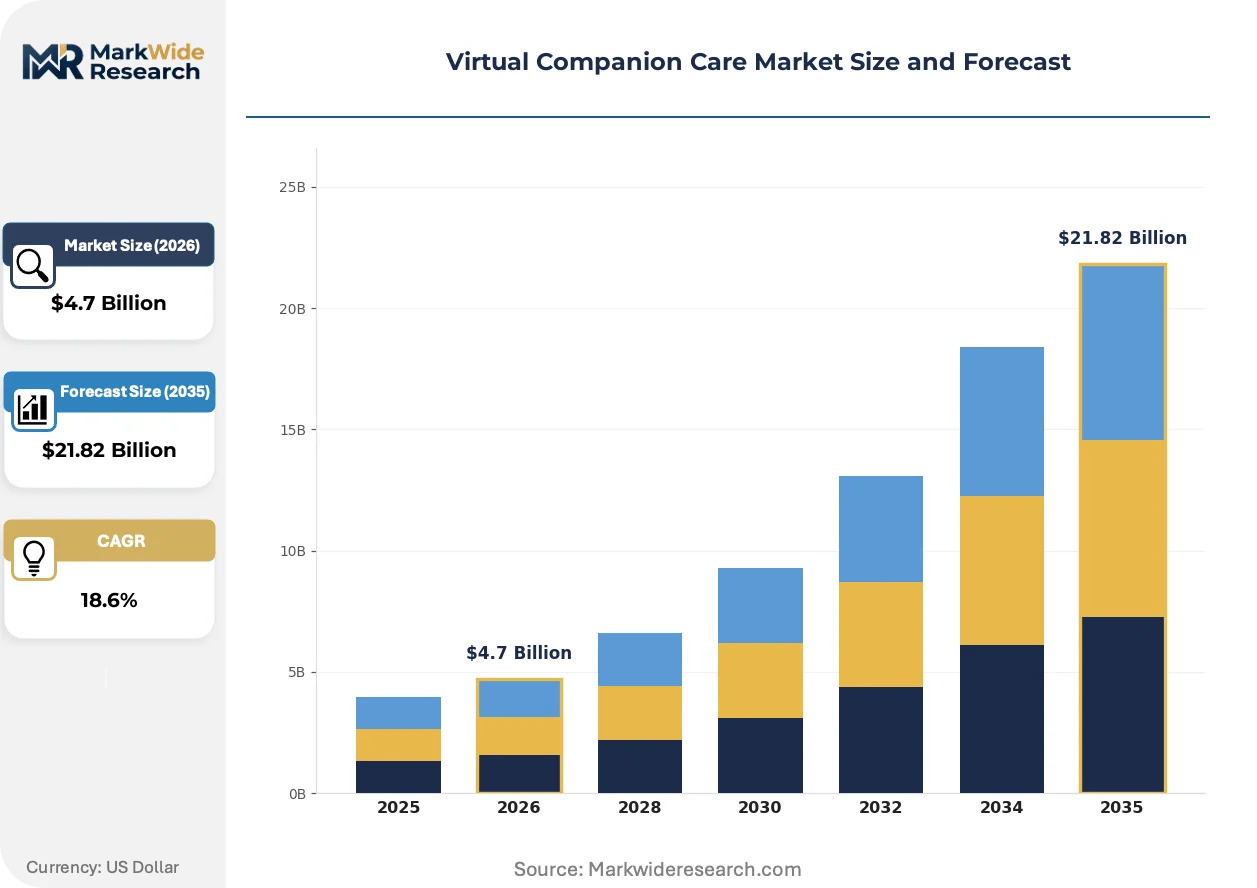
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Applications, Wearable Devices, Telehealth Systems, Robotics End User: Senior Citizens, Healthcare Providers, Family Caregivers, Individuals with Disabilities Technology: AI, Cloud Computing, Machine Learning, Virtual Reality Service Type: Monitoring Services, Social Interaction, Health Management, Emotional Support |
| Companies Covered | Sesame Care, Portiva, Teladoc Health, HelloRache, MedVirtual, Amwell, HealthTap, MyOutDesk, MDLive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Companion Care Market Evolving Landscape
Multimodal sensing architectures are displacing single-channel interaction models, while regulatory clarity on AI-enabled diagnostic claims is separating funded platforms from pilot-stage competitors.
Edge-deployed large language models are overtaking cloud-dependent inference for real-time companion dialogue. Senior living operators in Florida and Arizona are piloting on-device processing to eliminate latency during fall-risk conversations. This shift is compressing infrastructure costs for facilities in bandwidth-constrained locations.
The EU AI Act's high-risk system classification for health-monitoring AI is mandating conformity assessment procedures before market access. Developers must now document training data provenance and algorithmic bias testing for platforms deployed in Germany, France, and the Netherlands. Medium-sized vendors are consolidating compliance functions to spread fixed audit costs across product lines.
Subscription unbundling is fragmenting traditional all-inclusive pricing. Payers in the US Medicare Advantage channel are separating social engagement modules from clinical monitoring tiers, allowing selective procurement based on star-rating priorities. This pattern is most visible in California and New York, where managed care organizations operate dense provider networks with granular benefit design authority.
Virtual Companion Care Market Segmentation
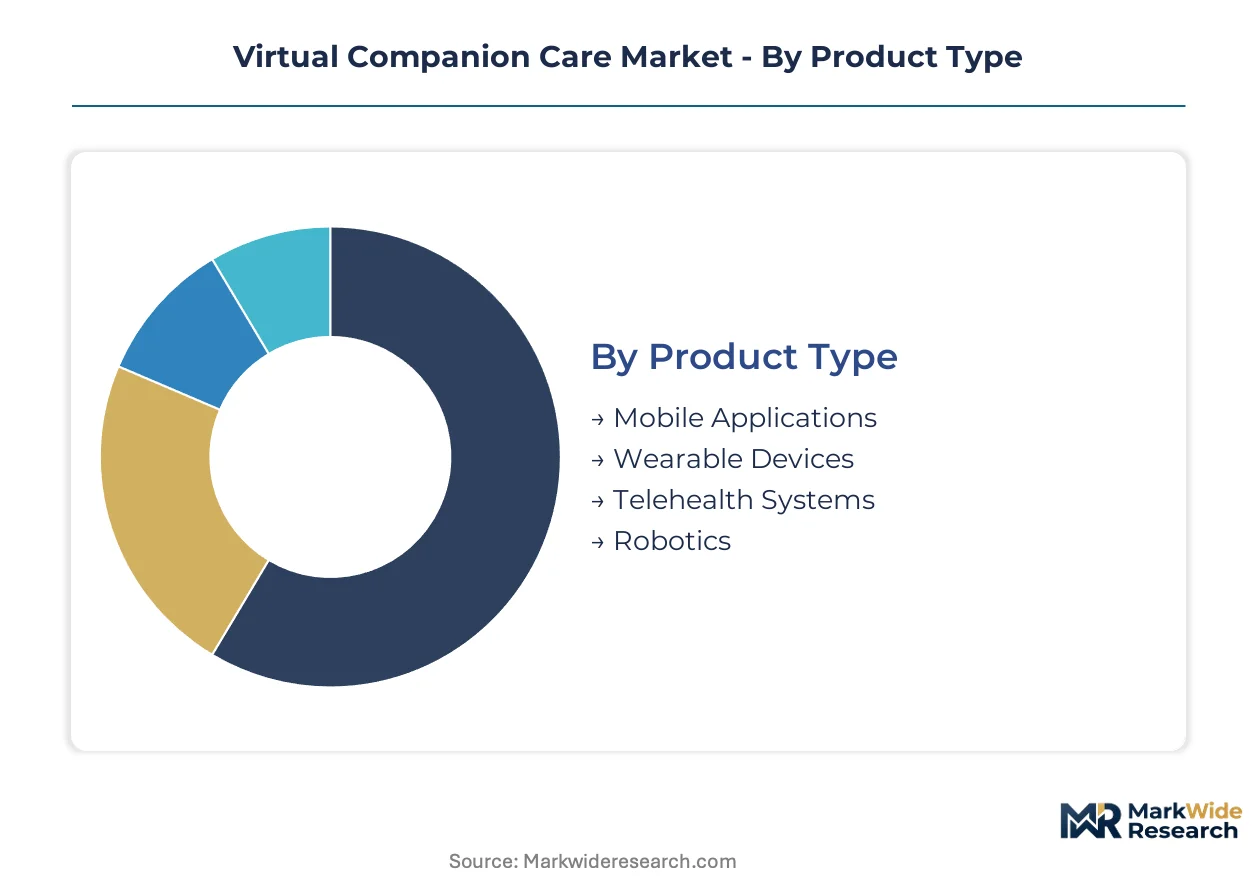
Segmentation in virtual companion care reveals how procurement decisions fragment across technical sophistication, care setting, and reimbursement eligibility. Product architecture, user capability, and regulatory classification all shape vendor positioning within each slice.
Product Type:
Customization intensity varies sharply across hardware-software boundaries in this category.
- Mobile Applications:Software-only delivery minimizes deployment friction through existing smartphone infrastructure. Demand clusters among Medicare Advantage plans in California and New York seeking rapid member onboarding without device subsidies. HIPAA-compliant SDKs now embed directly into payer-native apps, compressing procurement cycles.
- Robotics:Tactile interaction hardware requires FDA 510(k) clearance for fall-detection claims, creating capital barriers that favor venture-backed entrants with clinical validation budgets. Japanese senior living operators under METI funding programs prioritize culturally localized gesture protocols, driving specialized industrial design requirements.
- Wearable Devices:Photoplethysmography-integrated wristbands and pendants stream biometric data through recurring subscription models.
- Telehealth Systems:Hub-and-spoke hardware configurations anchor institutional deployments in skilled nursing facilities.
Leading the category by volume: Mobile Applications. Growing fastest: Robotics.
End User:
Reimbursement pathway availability determines addressable margin across user types.
- Senior Citizens:Isolated adults over 65 with chronic conditions drive platform utilization through Medicare Advantage remote care coordination benefits. Arizona and Florida senior living operators mandate enterprise-wide companion platform deployment across memory care and independent living wings.
- Healthcare Providers:Skilled nursing facilities and home health agencies integrate companion tools into 24/7 monitoring workflows. Epic and Cerner EHR integration requirements force costly custom middleware development per health system.
- Family Caregivers:Adult children purchasing direct-to-consumer subscriptions for remote parent oversight represent a cash-pay channel with higher churn.
- Individuals with Disabilities:Medicaid waiver programs in select states cover assistive technology with companion features for cognitive and mobility impairments.
Dominant by reimbursement volume: Senior Citizens. Expanding most quickly: Healthcare Providers.
Technology:
Infrastructure cost and latency sensitivity separate deployment architectures.
- AI:Natural language processing engines with sub-500 millisecond response thresholds enable real-time emotional calibration for crisis intervention. Edge-deployed large language models in Florida facilities eliminate cloud latency during fall-risk conversations.
- Cloud Computing:AWS, Microsoft Azure, and Google Cloud control health-grade compute capacity, exposing vendors to egress cost volatility and regional outage risk.
- Machine Learning:Behavioral deterioration detection algorithms require geriatric psychiatrist oversight for ethical training boundaries, creating talent scarcity.
- Virtual Reality:Immersive environments for reminiscence therapy and social simulation remain pilot-stage with limited payer coverage.
Highest deployment penetration: AI. Gaining share fastest: Edge-deployed Machine Learning.
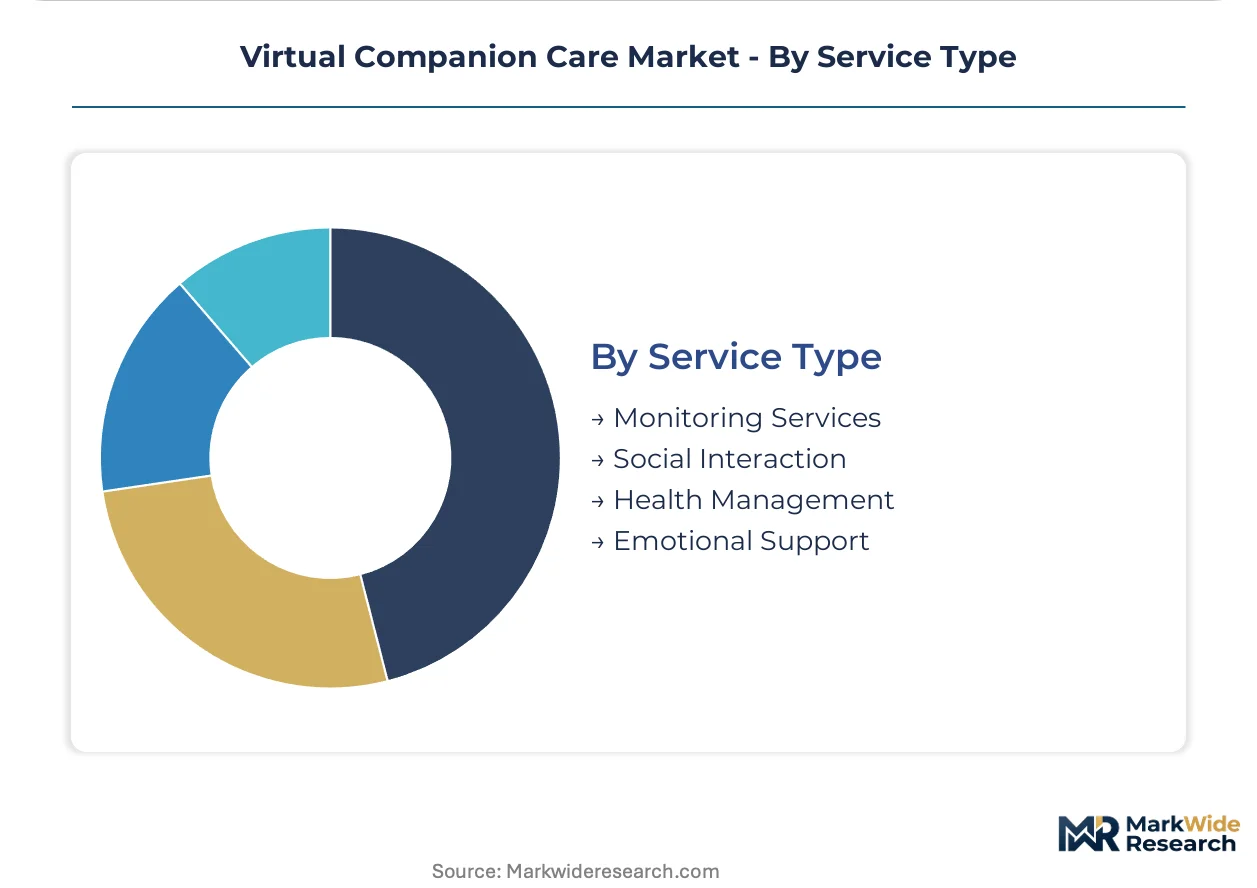
Service Type:
Clinical claim status determines FDA oversight intensity and pricing power.
- Monitoring Services:Passive biometric surveillance and anomaly alerting qualify as software-as-a-medical-device when tied to diagnostic claims. FDA 510(k) clearance extends launch timelines by 14-22 months but confers preferred status in Medicare Advantage negotiations.
- Health Management:Medication adherence prompting and care plan coordination integrate with remote patient monitoring reimbursement codes.
- Social Interaction:Unstructured conversation and companionship fall outside FDA jurisdiction, enabling faster deployment but limiting payer coverage to supplemental benefits.
- Emotional Support:Crisis intervention and mood monitoring occupy a regulatory gray zone requiring careful claim structuring to avoid medical device classification.
Leading by reimbursement attach rate: Monitoring Services. Steepest expansion trajectory: Emotional Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud computing infrastructure anchors North American platform delivery, while Taiwan's photoplethysmography chip fabrication supplies biometric sensor inputs for wearable-integrated systems worldwide.
United States
Medicare Advantage remote care coordination benefits and senior living facility consolidation drive procurement concentration. FDA software-as-a-medical-device oversight and HIPAA interoperability mandates reshape product architecture for domestic vendors. Arizona and Florida operators mandate enterprise-wide companion deployment across memory care portfolios.
Japan
METI loneliness-mitigation funding creates a $2 billion annual procurement channel with preference for culturally localized interaction protocols. PMDA consultation procedures guide developers on health-monitoring AI classification thresholds. Tokyo-based senior living operators pilot gesture-protocol robotics under national technology adoption programs.
Germany
The EU AI Act's high-risk system classification mandates conformity assessment for health-monitoring platforms before market access. EMA guidance on software-based medical devices shapes diagnostic claim structuring. Berlin and Munich clusters concentrate compliance-consolidating vendors spreading fixed audit costs across product lines.
United Kingdom
NHS remote monitoring frameworks and social care integration pilots expand addressable institutional channels. MHRA software-as-a-medical-device guidance aligns with EU MDR transitional provisions for post-Brexit market access. London health tech clusters anchor voice-first interface development for memory care applications.
South Korea
MFDS digital therapeutics pathways and national dementia care plans accelerate regulatory clarity for companion platforms. Photoplethysmography chip fabrication concentrates near Seoul, creating supply proximity for wearable-integrated system developers. Busan medical device clusters specialize in biometric sensor integration for export markets.
Virtual Companion Care Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue voice-first ambient sensing and edge-deployed language models. The vendor base stratifies across three tiers: telehealth incumbents with payer relationships, human-augmented virtual assistance specialists, and robotics hardware developers with FDA clearance capacity. Strategic archetypes include platform aggregators, clinical workflow embedders, and tactile interaction hardware fabricators. Competitive moves concentrate on health system EHR integration partnerships and Medicare Advantage channel exclusivity arrangements.
Among telehealth-anchored platforms, Teladoc Health exemplifies payer-relationship scalability, while Amwell occupies a position as health system workflow embedder. HelloRache represents the human-augmented specialization archetype, differentiating through staffed virtual assistance rather than fully automated interaction models. These three companies illustrate how vendor positioning fragments across automation philosophy and reimbursement pathway access.
| Leading Market Players |
|---|
| Sesame Care |
| Portiva |
| Teladoc Health |
| HelloRache |
| MedVirtual |
| Amwell |
| HealthTap |
| MyOutDesk |
| MDLive |
| Others |
Value Network & Pricing Analysis
Medicare Advantage unbundling of social engagement from clinical monitoring tiers is forcing vendors to reconstruct service packaging and exposing cost structures that previously hid in all-inclusive subscriptions. This procurement fragmentation compels platform developers to isolate hardware, software, and human-augmented components for selective payer procurement, compressing margins on standalone social interaction modules while preserving pricing power in FDA-cleared diagnostic tiers.
Pricing Analysis
Warranty and service bundling separates cleared medical device tiers from unregulated wellness offerings, with FDA 510(k) pathways commanding premium positioning against commodity social engagement subscriptions. Three-tier pricing structure across enterprise, health system, and direct-to-consumer levels reflects integration complexity and reimbursement eligibility rather than feature depth alone. Pricing pressure stems from Medicare Advantage star-rating priorities that favor basic monitoring over emotional support modules. Healthcare providers exhibit lowest price sensitivity due to bundled reimbursement codes, while family caregivers in cash-pay channels face steepest churn from subscription fatigue.
Supply Chain Analysis
Freight cost volatility for photoplethysmography chip imports from Taiwan and South Korea is compressing wearable device margins and accelerating onshore assembly near Arizona and Florida senior living clusters. Cloud computing infrastructure draws from AWS, Microsoft Azure, and Google Cloud concentration in US data centers, creating egress cost exposure for biometric streaming architectures. Single-source vulnerability in Taiwan semiconductor fabrication threatens sensor input stability for wristband-integrated companion systems. Distribution runs through health system procurement committees and Medicare Advantage plan administrators rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform vendor consolidation is accelerating as FDA 510(k) timeline compression and EHR integration costs exhaust venture-backed entrants before revenue scaling. This attrition dynamic favors incumbents with established payer relationships and clinical validation budgets.
For Market Incumbents: To counter edge-deployed language model entrants in Florida and Arizona memory care pilots, Teladoc Health and Amwell should deepen health system EHR integration partnerships with Epic and Cerner to embed companion workflows into existing clinical protocols. Backward integration into photoplethysmography sensor supply through South Korean foundry relationships would mitigate Taiwan concentration risk and secure input cost stability for wearable-integrated offerings. For New Entrants and Emerging Players: The premium-to-economy gap in human-augmented virtual assistance creates white-space opportunity for mid-tier vendors offering staffed emotional support without full clinical monitoring overhead. Japan's METI-funded loneliness-mitigation procurement channel remains underpenetrated by Western platforms due to cultural localization gaps. Voice-first ambient sensing for crisis intervention in rural broadband expansion zones offers the most penetrable Medicare Advantage entry point with minimal device subsidy requirements. For Investors and Strategic Acquirers: The window for entry favors clinical workflow embedders with FDA clearance momentum and health system contract velocity over pure-play social engagement platforms. Acquisition targets should demonstrate Epic or Cerner live integrations and Medicare Advantage channel exclusivity arrangements in Arizona or Florida. Watch for FDA 510(k) backlog resolution timelines as inflection signal for venture-backed entrant distress and consolidation availability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Clearance confers preferred payer status in Medicare Advantage star-rating negotiations. |
| Epic EHR Integration Partnership | Embeds companion workflows into existing clinical documentation and ordering systems. |
| Edge-Deployed Language Model Launch | Eliminates cloud latency for fall-risk conversations in bandwidth-constrained senior facilities. |
| Japan METI Localization Program | Unlocks $2 billion annual procurement channel with culturally adapted gesture protocols. |
| Rural Broadband Expansion Targeting | FCC Universal Service Fund subsidies unlock previously excluded Medicare populations in Appalachia. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with senior living facility operators, Medicare Advantage plan administrators, biomedical engineers at wearable device manufacturers, and geriatric psychiatrists training intervention algorithms. FDA 510(k) submission databases, HIPAA security rule enforcement actions, and CMS Medicare Advantage bid data provided secondary validation. Bottom-up modeling of platform deployments triangulated against top-down reimbursement flow analysis across the analysis window.
Granularity-level modeling captured product type splits across mobile applications, robotics, wearables, and telehealth systems; end-user segmentation across senior citizens, healthcare providers, family caregivers, and individuals with disabilities; technology deployment across AI, cloud computing, machine learning, and virtual reality; and service type differentiation across monitoring, health management, social interaction, and emotional support. CAGRs derived from logistic adoption curve fitting for AI-enabled diagnostic claims and reimbursement eligibility expansion trajectories. Photoplethysmography chip supply constraints and FDA review backlog assumptions shaped wearable and software-as-a-medical-device forecast sensitivity.
Underlying measurement precision varies by segment; mobile application and wearable device volumes carry tighter precision than robotics and virtual reality pilot-stage deployments. Forecasts reflect assumptions on Medicare Advantage remote care coordination benefit expansion, FDA software-as-a-medical-device enforcement intensity, and Taiwan semiconductor supply continuity. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Europe Home Care Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Global Elderly Care Market
Home Healthcare
Global Home Infusion Therapy Market
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
Home Care Market
Home Healthcare
US Home Healthcare Market
Home Healthcare
House Call Market
Home Healthcare
Adult Day Care Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
US Home Infusion Therapy Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Chemotherapy at Home Services Market