
 Senior in-Home Care Services Market | 2026-2036
Senior in-Home Care Services Market Size, Share, and Industry Trends Forecast 2026-2036
Senior in-Home Care Services Market Analytics
Digital health monitoring platforms is consolidating around wearable-enabled remote patient monitoring as the central nervous system of modern care delivery. Amedisys, Inc. leverages telehealth infrastructure to extend skilled nursing reach into rural service deserts. Home Instead, Inc. anchors its competitive position through franchise-based geographic density and standardized caregiver training protocols. Visiting Angels differentiates via flexible scheduling models that accommodate episodic rather than continuous care needs.
Senior in-Home Care Services encompass medical and non-medical assistance delivered within a client's residence, spanning medication management, mobility support, wound care, and activities of daily living supervision through licensed or certified personnel. These services functionally substitute institutional long-term care by maintaining clinical outcomes at lower per-diem cost structures while preserving patient autonomy and household stability. Skilled Nursing commands the deepest margin pools due to licensing barriers and reimbursement rate differentials under Medicare Part A, while Companion Care expands fastest as families seek affordable cognitive engagement and socialization support for early-stage dementia clients. Payment Source dynamics reveal Out-of-Pocket as the most predictable revenue stream, though Medicaid waiver programs in states like Texas and Florida are capturing growing share of lower-acuity service volumes.
CMS Conditions of Participation for home health agencies and state-level nurse practice acts govern workforce ratios, clinical documentation, and permissible service scopes across the United States. OSHA bloodborne pathogen standards and HIPAA privacy requirements impose compliance costs that favor scaled operators with dedicated compliance infrastructure over fragmented independent providers. Stakeholders must monitor state Medicaid expansion trajectories and Medicare Advantage plan in-home benefit carve-ins as decisive variables for regional market access and reimbursement adequacy.
Market Dynamics
CMS reimbursement rule changes for home health services are redirecting care delivery away from institutional settings, while Medicare Advantage plan expansion accelerates in-home benefit carve-ins that reshape provider economics.
Growth Catalysts
- Medicare Advantage Penetration:Private plan enrollment growth under CMS Medicare Part C contracts expands supplemental in-home care benefits beyond traditional fee-for-service coverage.
- Medicaid 1915(c) Waivers:State-level home and community-based services waivers in Texas and Florida authorize personal care attendant hours for lower-acuity seniors outside nursing facilities.
- Wearable RPM Integration:Continuous glucose monitors and pulse oximetry devices enable remote patient monitoring platforms to substitute periodic skilled nursing visits with automated data transmission.
Market Restraints
- Workforce Licensing Barriers:State nurse practice acts impose supervised practice requirements that restrict task delegation to lower-cost home health aides.
- Reimbursement Rate Compression:Medicare prospective payment system annual recalibration reduces per-episode margins for skilled nursing providers.
- Family Caregiver Substitution:Unpaid household caregiving absorbs service demand that would otherwise convert to paid professional hours.
Strategic Opportunities
- Rural Service Deserts:Telehealth infrastructure extension into non-metropolitan counties captures Medicare beneficiaries beyond traditional 60-minute drive-time radii.
- Dementia Care Specialization:Early-stage Alzheimer's companion programs address cognitive engagement gaps left by medical-model home health.
- State Medicaid Expansion:Non-expansion state conversions to expansion status under Affordable Care Act provisions unlock new eligibility cohorts for personal care services.
Industry Challenges
- Certified Nursing Assistant Shortage:State registry training program bottlenecks limit pipeline throughput for entry-level direct care workers.
- Electronic Visit Verification Compliance:CMS-mandated EVV system implementation imposes technology capital requirements on smaller independent providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Senior in-Home Care Services Market |
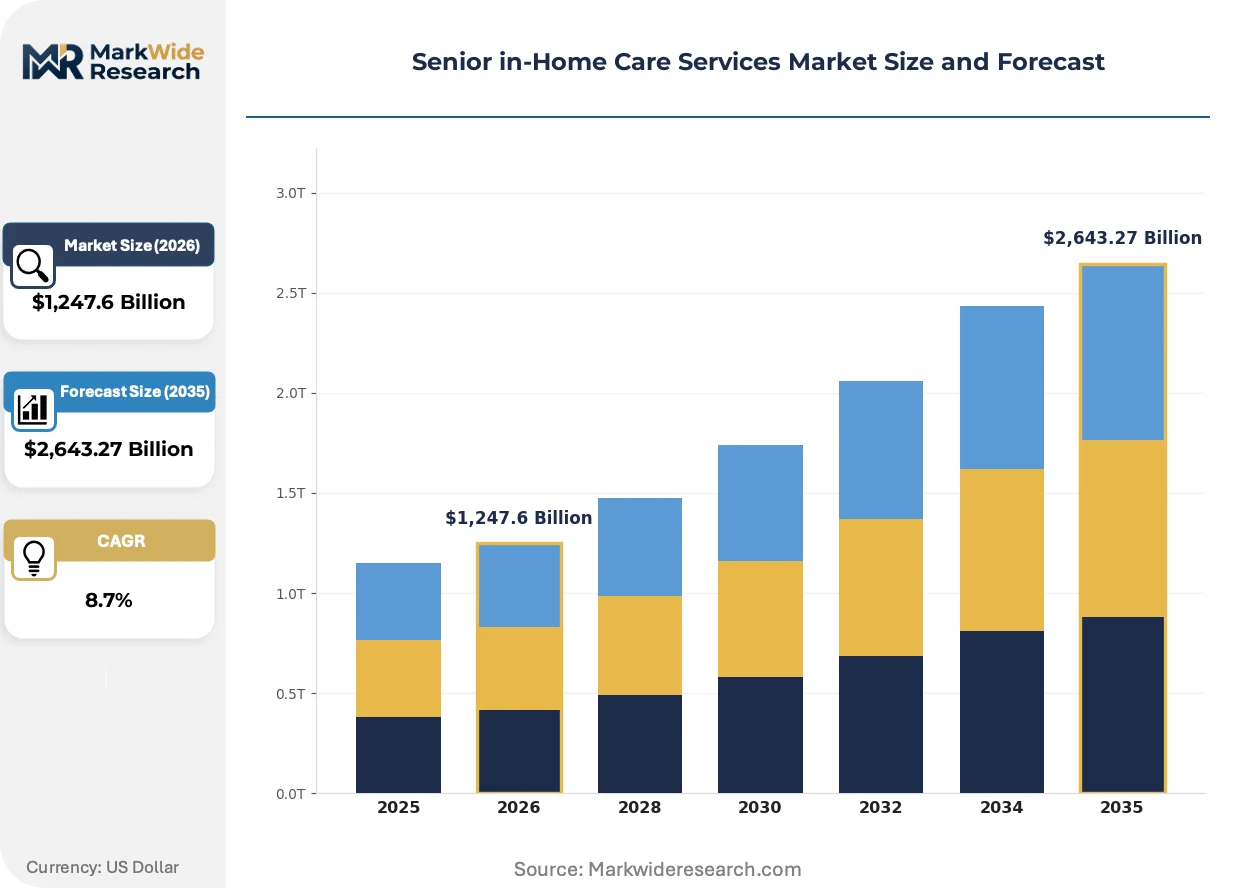
| Market Size in 2026 | $1,247.6 Billion |
| Market Size in 2035 | $2,643.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Care, Companion Care, Skilled Nursing, Specialized Medical Care Payment Source: Out-of-Pocket, Medicare, Medicaid, Long-Term Care Insurance Caregiver Type: Professional Caregivers, Family Caregivers, Volunteers, Healthcare Professionals Client Type: Individuals, Families, Elderly Communities, Rehabilitation Centers |
| Companies Covered | Home Instead, Inc., Amedisys, Inc., Brookdale Senior Living Inc., Right at Home, LLC, Visiting Angels, Senior Helpers, Comfort Keepers, Interim HealthCare Inc., BrightStar Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Senior in-Home Care Services Market Evolving Landscape
Digital health infrastructure is consolidating around interoperable data exchange platforms that connect wearable sensors, electronic health records, and payer authorization systems into unified care coordination workflows.
Remote patient monitoring technology is converging with artificial intelligence triage algorithms to enable predictive intervention before acute episodes require emergency department utilization. Medicare Advantage plans with in-home benefit carve-ins are deploying these integrated systems fastest among payer segments. The structural result compresses hospital readmission rates while extending skilled nursing reach into geographic territories previously served only by intermittent home health visits.
CMS Conditions of Participation updates for home health agencies impose stricter clinical documentation and quality reporting requirements effective across all Medicare-certified providers. The industrial consequence elevates compliance infrastructure costs that favor scaled multi-site operators over independent single-location agencies. Skilled nursing segments with existing quality assurance departments are absorbing these requirements with minimal margin disruption, while smaller companion care providers face consolidation pressure.
Family purchasing patterns for senior care are fragmenting across episodic, subscription, and concierge payment models rather than defaulting to continuous hourly arrangements. Direct-to-consumer platforms are disintermediating traditional agency referral relationships by enabling families to schedule vetted caregivers through mobile applications. This behavioral shift is most visible in metropolitan United States markets where dual-income adult children lack bandwidth for traditional agency coordination processes.
Senior in-Home Care Services Market Segmentation
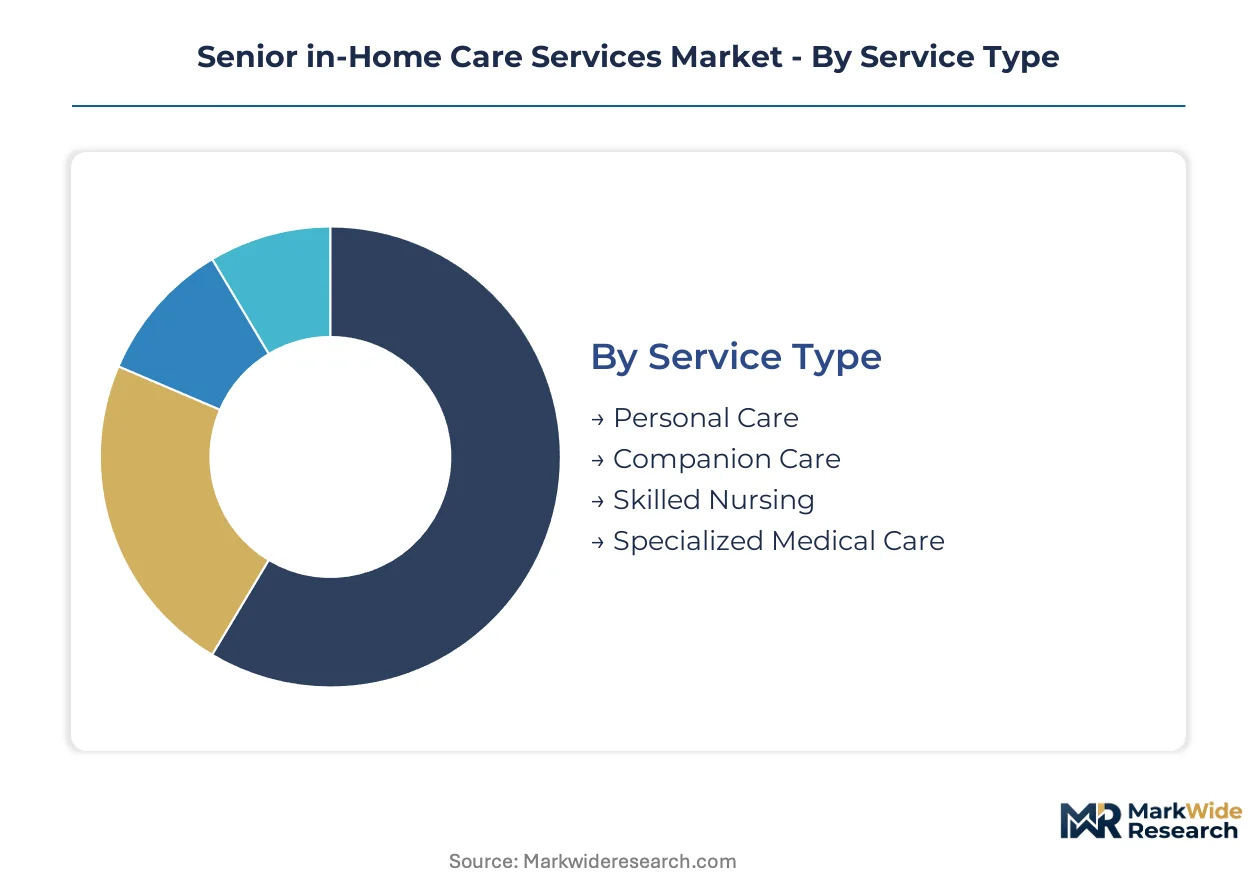
Segmentation in senior in-home care services reveals how payment flows and workforce configurations determine provider economics. Understanding these divisions exposes where margin pressure concentrates and which service lines attract capital deployment.
Service Type:
Volume concentrates in lower-acuity personal support, while premium pools cluster around licensed clinical interventions requiring specialized credentials.
- Personal Care:Assistance with bathing, dressing, grooming, and toileting delivered by certified home health aides under state registry protocols. Demand clusters heaviest in Florida and Texas where Medicaid 1915(c) waivers authorize personal care attendant hours for functional impairment without medical necessity. Workforce licensing barriers restrict task delegation, compressing margins despite high volume.
- Skilled Nursing:Wound care, medication administration, and post-acute monitoring performed by registered nurses under Medicare Part A reimbursement. Medicare Advantage penetration in California and New York accelerates in-home benefit carve-ins that reshape provider economics for this segment. Licensing requirements create the deepest margin pools due to reimbursement rate differentials.
- Companion Care:Cognitive engagement, meal preparation, and socialization support for early-stage dementia clients. Families in metropolitan United States markets seek affordable alternatives to medical-model home health.
- Specialized Medical Care:Ventilator management, infusion therapy, and palliative interventions requiring physician oversight. Hospice-integrated programs in Pennsylvania and Ohio capture complex cases.
Today's leader: Skilled Nursing. Tomorrow's challenger: Companion Care.
Payment Source:
Predictability separates stable revenue streams from administrative burden, with out-of-pocket and Medicaid occupying opposite poles of this spectrum.
- Out-of-Pocket:Direct family payments for private-duty nursing and concierge care coordination. Affluent households in Massachusetts and Connecticut sustain premium pricing for 24-hour live-in arrangements without insurance intermediation.
- Medicare:Fee-for-service and Medicare Advantage reimbursement for skilled nursing episodes under prospective payment systems. CMS annual recalibration reduces per-episode margins, forcing operational efficiency investments.
- Medicaid:State waiver programs and personal care services for low-income seniors. Texas and Florida expansion of 1915(c) waivers captures growing share of lower-acuity service volumes.
- Long-Term Care Insurance:Private policy benefits triggering after elimination periods for cognitive or functional impairment claims. Underwriting crises in the 2000s reduced new policy issuance, constraining this pool's growth trajectory.
Out-of-Pocket delivers margin stability. Medicaid waiver expansion is climbing the fastest as states rebalance long-term care spending.
Caregiver Type:
Credential requirements create a hierarchy where professional licensure commands premium rates and volunteer labor subsidizes nonprofit service delivery.
- Professional Caregivers:Agency-employed home health aides and certified nursing assistants completing state-mandated training hours. Registry bottlenecks in Illinois and Georgia limit pipeline throughput for entry-level direct care workers.
- Family Caregivers:Unpaid household members providing informal support that absorbs demand otherwise converting to paid professional hours. Adult children in dual-income households face bandwidth constraints that accelerate professional substitution.
- Volunteers:Faith-based and community organization members delivering companionship and transportation. Nonprofit hospice programs in Minnesota and Wisconsin leverage this layer to extend reach without reimbursement dependency.
- Healthcare Professionals:Registered nurses, physical therapists, and occupational therapists with scope-of-practice authority under state nurse practice acts. Supervision requirements restrict task delegation to lower-cost aides.
Professional Caregivers anchor current capacity. Healthcare Professionals face the steepest shortage trajectory as clinical complexity rises.
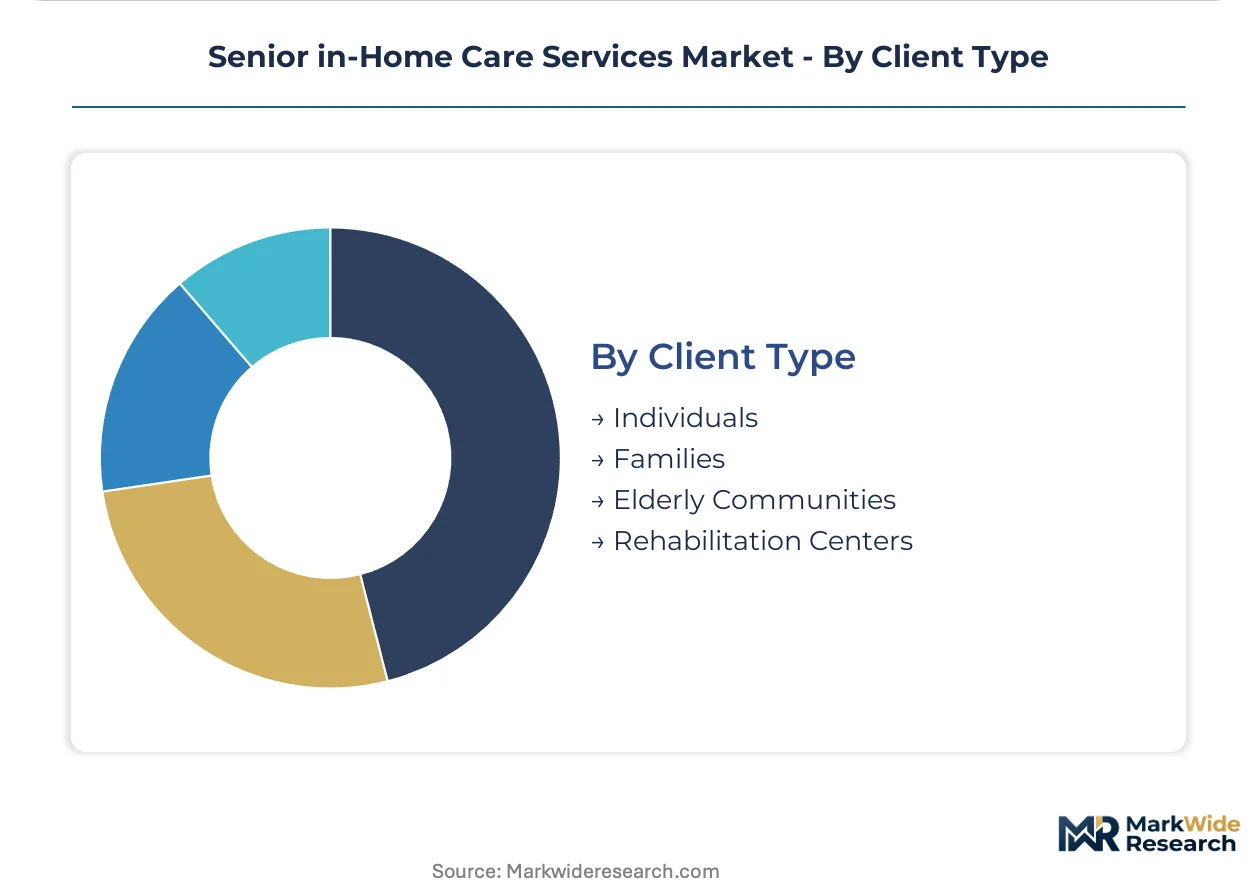
Client Type:
Decision-making authority fragments across individual preferences, family financial capacity, and institutional procurement processes.
- Individuals:Seniors self-directing care arrangements through direct-to-consumer platforms. Mobile application scheduling disintermediates traditional agency relationships in urban United States markets.
- Families:Adult children coordinating services for parents with cognitive or functional decline. Episodic and subscription payment models replace continuous hourly arrangements in metropolitan areas.
- Elderly Communities:Independent living and assisted living facilities contracting for supplemental in-home support. Arizona and Nevada retirement concentrations drive geographic demand clustering.
- Rehabilitation Centers:Post-acute facilities arranging home health for discharge continuity. Hospital readmission reduction mandates accelerate partnerships with skilled nursing providers.
Families dominate current purchasing volume. Rehabilitation Centers are gaining share fastest as value-based care contracts expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates the deepest demand pools for senior in-home care services, where Medicare Advantage penetration and state-level Medicaid waivers accelerate service adoption. Regional variation reflects reimbursement policy fragmentation and workforce licensing heterogeneity across state boundaries.
United States
Medicare Advantage enrollment expansion under CMS Part C contracts drives supplemental in-home benefit carve-ins beyond traditional fee-for-service coverage. The 1915(c) waiver programs in Texas and Florida authorize personal care attendant hours for functional impairment without medical necessity. Phoenix and Tampa metropolitan clusters absorb the highest per-capita service volumes as retirement migration concentrates aging populations in Sun Belt corridors.
Germany
Long-term care insurance mandates under the Pflegeversicherung system stabilize demand for professional home nursing services. The Federal Ministry of Health regulates workforce ratios and clinical documentation standards through the German Social Code. Bavaria and North Rhine-Westphalia host the densest provider networks, where multi-site operators absorb compliance infrastructure costs more efficiently than fragmented independent agencies.
Japan
Super-aging demographics compress family caregiver availability and accelerate professional substitution for household eldercare. The Ministry of Health, Labour and Welfare administers the Long-Term Care Insurance system that caps out-of-pocket exposure for certified care recipients. Tokyo and Osaka metropolitan prefectures concentrate demand for dementia-specialized companion programs as cognitive engagement gaps exceed medical-model home health capacity.
United Kingdom
Local authority commissioning patterns fragment payment flows across means-tested and self-funded client segments. The Care Quality Commission imposes registration and inspection requirements that elevate compliance costs for smaller independent providers. London and Southeast England sustain premium pricing for 24-hour live-in arrangements among affluent households without insurance intermediation.
Canada
Provincial health authority procurement processes determine regional market access for home care contractors. Health Canada guidelines intersect with provincial nurse practice acts to govern task delegation and supervision requirements. Ontario and Quebec concentrate the largest service volumes, where hospital readmission reduction mandates accelerate partnerships between acute discharge planners and skilled nursing providers.
Senior in-Home Care Services Market Competitive Landscape
Global majors compete with regional champions across franchise density and telehealth infrastructure deployment. The vendor base stratifies into scaled multi-site operators, franchise-network consolidators, and technology-enabled platform intermediaries. Three archetypes dominate: Medicare Advantage-integrated skilled nursing specialists, franchise-based personal care aggregators, and direct-to-consumer scheduling platforms. M&A activity concentrates among mid-cap regional agencies seeking geographic footprint expansion, while strategic partnerships between home health operators and wearable RPM vendors reshape care delivery economics.
Within the franchise-network tier, Home Instead, Inc. and Visiting Angels occupy positions as geographic density leaders through standardized caregiver training protocols and flexible scheduling models. Amedisys, Inc. anchors the telehealth-integrated vector, exemplifying how remote patient monitoring infrastructure extends skilled nursing reach into rural service deserts. These three entities represent distinct competitive positioning strategies: franchise scalability, scheduling flexibility, and technology-enabled geographic expansion.
| Leading Market Players |
|---|
| Home Instead, Inc. |
| Amedisys, Inc. |
| Brookdale Senior Living Inc. |
| Right at Home, LLC |
| Visiting Angels |
| Senior Helpers |
| Comfort Keepers |
| Interim HealthCare Inc. |
| BrightStar Care |
| Others |
Value Network & Pricing Analysis
Medicare Advantage plan sponsors concentrate purchasing power for skilled nursing services and negotiate episode-based rates that compress per-visit margins while expanding volume commitments. This buyer concentration forces providers to absorb cost volatility through operational efficiency rather than price pass-through.
Pricing Analysis
Labor cost pass-through dominates pricing dynamics as certified nursing assistant wages constitute the largest cost component across all service tiers. Pricing stratifies across premium live-in arrangements, standard hourly skilled nursing, and economy companion care levels, with certification grade and geographic delivery cost as primary differentiation drivers. Pricing pressure stems from Medicare prospective payment system annual recalibration that reduces per-episode reimbursement. Medicaid waiver programs exhibit highest price sensitivity due to state budget constraints, while affluent out-of-pocket households show lowest sensitivity for concierge coordination services.
Supply Chain Analysis
Single-source vulnerability sits with Philippines-based caregiver training programs that feed state registry pipelines in California and Texas. Workforce supply concentrates in Mexico, Philippines, and domestic community college systems as primary source countries for entry-level direct care labor. Raw material dependencies include state-mandated training curricula, background check infrastructure, and electronic visit verification software licenses. Tariff exposure on healthcare technology imports from China elevates remote patient monitoring platform costs. Distribution runs through franchise networks, direct-to-consumer platforms, and hospital discharge planning partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value as CMS Conditions of Participation updates impose stricter clinical documentation requirements that favor scaled operators with dedicated compliance infrastructure.
For Market Incumbents: Hedge against workforce compression by automating documentation workflows and securing preferred hiring pipelines with community college nursing programs. Consolidate smaller independent agencies facing Electronic Visit Verification compliance costs to capture geographic density in Sun Belt retirement corridors. Threat substitution from direct-to-consumer scheduling platforms demands channel control investment. For New Entrants and Emerging Players: Rural Medicare beneficiaries beyond 60-minute drive-time radii represent the most underserved buyer archetype for telehealth-integrated skilled nursing. Capture this white space through remote patient monitoring partnerships with Medicare Advantage plans. Target dementia-specialized companion programs as the most penetrable segment given medical-model home health capacity gaps. Pursue hospital system partnership as the primary go-to-market angle for post-acute discharge continuity. For Investors and Strategic Acquirers: Medicare Advantage insurers are the most active acquirer in this space, seeking vertical integration into in-home benefit delivery. Long-term viability centers on platforms with durable payer relationships and technology-enabled care coordination capabilities. Target mid-cap regional agencies with existing quality assurance departments that absorb compliance requirements with minimal margin disruption. Monitor state Medicaid expansion trajectories as the decisive inflection signal for personal care service volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Patient Monitoring Platform Integration | CMS reimbursement shifts reward Amedisys-style telehealth infrastructure for rural Medicare reach. |
| Franchise Network Geographic Expansion | Home Instead's standardized training protocols enable rapid Sun Belt corridor penetration. |
| Dementia Care Specialization Program Launch | Early-stage Alzheimer's companion services address cognitive engagement gaps in Tokyo and Osaka. |
| Electronic Visit Verification Compliance Investment | CMS-mandated EVV systems impose technology capital requirements that consolidate smaller providers. |
| Medicare Advantage Plan Partnership | In-home benefit carve-ins reshape provider economics through supplemental coverage beyond fee-for-service. |
Research Methodology
Direct dialogue with home health agency executives, Medicare Advantage contracting officers, state Medicaid waiver administrators, and family caregiver coordinators grounded qualitative insights in operational reality. Secondary validation drew from CMS Medicare data, state nurse practice act filings, hospital procurement databases, and franchise disclosure documents. Bottom-up triangulation across service type volumes and top-down reconciliation against payer expenditure flows ensured cross-verified estimates.
Bottom-up modeling aggregated county-level Medicare beneficiary demographics, Medicaid waiver enrollment trends, and caregiver supply pipeline capacity across the projection horizon. Segmentation dimensions included service type, payment source, caregiver credential tier, and client decision-making authority. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns and reimbursement policy trajectories. Forecast inputs incorporated Medicare Advantage penetration scenarios and state Medicaid expansion probability assessments.
Underlying measurement precision varies by segment; skilled nursing carries tighter precision due to standardized CMS claims data, while companion care estimates reflect greater uncertainty from fragmented direct-to-consumer activity. Forecasts embed assumptions about regulatory stability and workforce supply elasticity that could revise materially if state training program funding shifts or immigration policy changes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Home Care Products Market
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Virtual Companion Care Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Smart Mattress Market
Home Healthcare
Smart Pillow Market
Home Healthcare
Portable Toilet for Elderly Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Home Care Service Market
Home Healthcare
US Home Healthcare Services Market
Home Healthcare
Adult Day Care Market
Home Healthcare
US Home Infusion Therapy Market
Home Healthcare
House Call Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
Europe Home Care Market