
 Global Home Infusion Therapy Market | 2026-2036
Global Home Infusion Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Infusion Therapy Market Foresight
Biocompatible polymers are replacing traditional PVC in infusion pump construction, which is recalibrating supply chain economics across the sector. Baxter International Inc. leverages vertical integration in elastomer manufacturing to secure raw material access. Fresenius Kabi AG anchors its position through captive production of parenteral nutrition formulations. Option Care Health Inc. competes on geographic density, operating over 100 infusion suites across metropolitan clusters.
Home infusion therapy encompasses the administration of medications, nutrients, or fluids directly into a patient's circulatory system within a non-acute care residence, typically requiring programmable electromechanical pumps with flow-rate precision of 0.1 milliliters per hour and sterile closed-system delivery to prevent bloodstream infection. The primary commercial purpose is to shift clinically appropriate treatments from institutional settings to lower-cost environments while maintaining therapeutic equivalence. Infusion pumps dominate product-type revenue due to capital replacement cycles and software upgrade requirements, while oncology leads therapy-area growth driven by biologic agent expansion. Intravenous delivery mode maintains volume leadership, though subcutaneous administration is gaining fastest in immunoglobulin protocols due to patient preference and reduced nursing time.
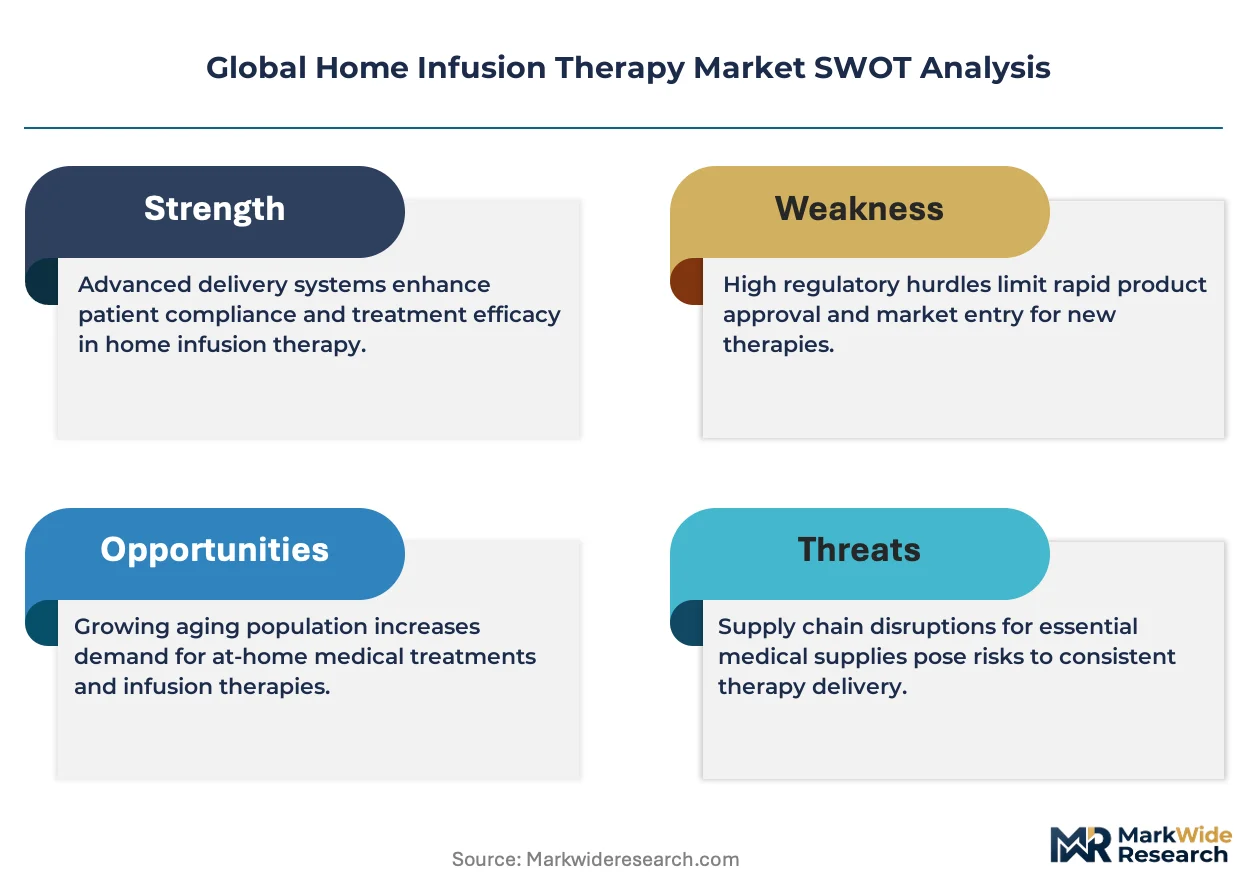
FDA 503B outsourcing facility regulations, EPA medical waste disposal standards, and ISO 80601-2-24 electromechanical pump safety requirements collectively shape product development timelines and market access barriers for new entrants. The FDA's emphasis on beyond-use dating and sterility assurance testing is forcing manufacturers to invest in closed-system transfer device integration. Stakeholders must monitor Medicare site-neutral payment rulemaking and state-level nursing scope-of-practice expansions to anticipate reimbursement and labor model shifts.
Market Dynamics
Hospital-at-home reimbursement expansion is compressing site-of-care economics, forcing infusion providers to reconfigure nursing deployment models and pump fleet management systems to capture Medicare site-neutral payments.
Growth Catalysts
- Oncology biologic pipeline:Antibody-drug conjugates and immune checkpoint inhibitors require extended intravenous administration protocols that institutional settings cannot accommodate at scale.
- Medicare site-neutral payment rules:Reimbursement parity between hospital outpatient departments and home settings removes financial disincentives for discharge planning teams.
- Elastomer supply security:Captive production of medical-grade silicone and thermoplastic elastomers insulates pump manufacturers from petrochemical volatility.
Market Restraints
- Specialized pharmacy concentration:Three national 503B outsourcing facilities control the majority of sterile compounding capacity for high-risk parenteral formulations.
- Biocompatible polymer cost premium:DEHP-free PVC alternatives and TPE formulations carry 40-60% raw material cost escalations versus conventional polymers.
- Nursing labor density thresholds:Rural and exurban geographies fall below the patient density required to sustain 24/7 on-call infusion nurse coverage.
Strategic Opportunities
- Subcutaneous immunoglobulin protocols:Rapid-push subcutaneous administration reduces nursing time by 70% and opens home therapy to patients previously requiring institutional infusion.
- Closed-system transfer device integration:FDA beyond-use dating requirements for hazardous drug compounding mandate CSTD adoption, creating upgrade cycles for legacy pump installations.
- Metropolitan infusion suite networks:Hybrid models combining home nursing with supervised ambulatory suites address patient preference for proximity while maintaining cost advantages.
Industry Challenges
- Electromechanical pump software validation:ISO 80601-2-24 safety requirements demand extensive firmware verification timelines that compress product launch windows.
- Interoperability with electronic health records:Pump data integration with Epic, Cerner, and Meditech systems requires custom API development that fragments vendor development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Infusion Therapy Market |
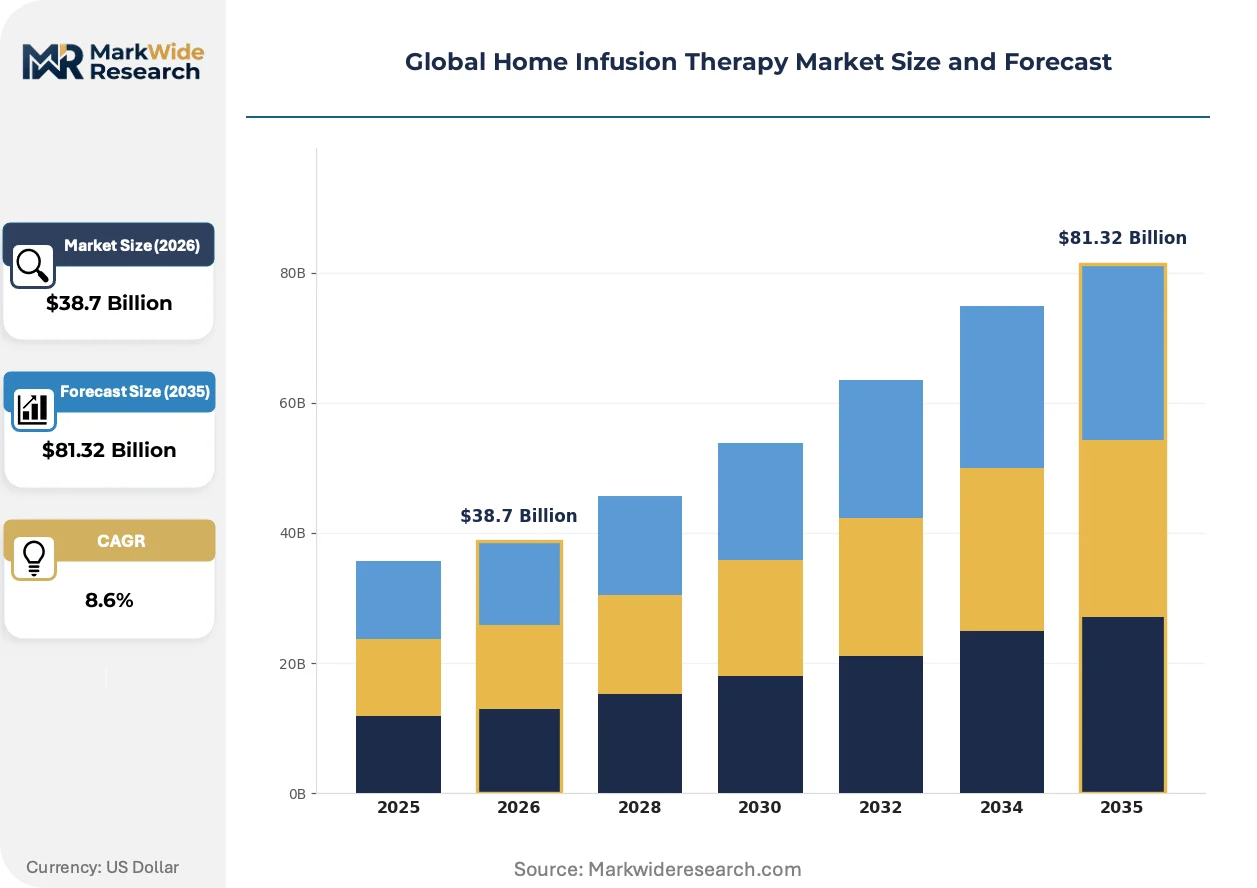
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Pumps, IV Catheters, Infusion Sets, Safety Devices, Others Therapy Area: Oncology, Infectious Diseases, Pain Management, Immunology, Gastroenterology, Hematology End User: Home Healthcare Agencies, Specialty Clinics, Nursing Services, Rehabilitation Centers Delivery Mode: Intravenous, Subcutaneous, Epidural, Intramuscular, Continuous Infusion |
| Companies Covered | Baxter International Inc., B. Braun Melsungen AG, Fresenius Kabi AG, Option Care Health Inc., ICU Medical Inc., Optum Inc., CVS Health, McKesson Corporation, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Infusion Therapy Market Shifts & Advancements
Connected pump ecosystems and predictive analytics platforms are displacing standalone electromechanical devices, embedding therapy management into broader remote patient monitoring architectures.
Smart infusion pumps with bidirectional wireless connectivity and dose error reduction software are expanding into oncology and anti-infective protocols. Hospital systems in the United States and Germany are deploying fleet-wide pump data lakes to predict maintenance failures and optimize drug library updates. This connectivity layer is compressing service revenue models toward subscription-based remote monitoring.
The FDA's updated 503B compounding guidance imposes sterility assurance testing and beyond-use dating protocols that extend quality validation timelines for outsourced facilities. Compounders serving the home infusion channel must now demonstrate environmental monitoring and personnel competency programs that match hospital pharmacy standards. High-risk sterile preparations face the steepest compliance cost escalation.
Patients and payers are consolidating purchasing authority through specialty pharmacy benefit managers that bundle drug, pump, and nursing services into single-case rates. This unbundling of legacy fee-for-service contracts favors providers with geographic density and captive nursing networks. The United States exhibits the most advanced case-rate contracting penetration.
Global Home Infusion Therapy Market Segmentation
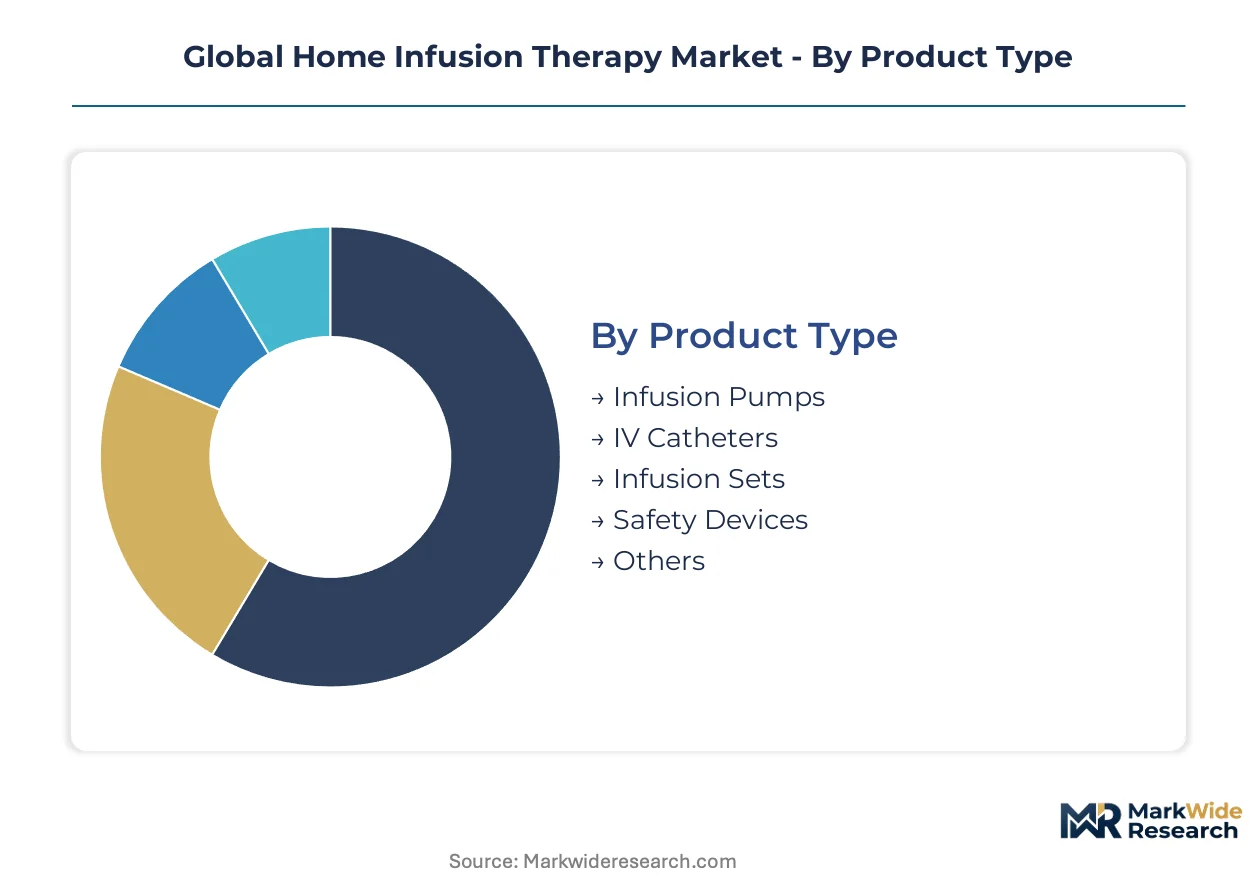
Home infusion therapy segments reflect divergent capital intensity and regulatory exposure. Product type determines hardware replacement cycles, while therapy area shapes reimbursement risk and nursing specialization requirements.
Product Type:
Standalone programmable devices dominate capital expenditure budgets, whereas disposable sets and safety accessories embed into recurring procurement streams.
- Infusion Pumps:Electromechanical devices with flow-rate precision to 0.1 milliliters per hour require software validation under ISO 80601-2-24 and drive fleet-wide data lake investments for predictive maintenance. Demand concentrates in United States hospital-at-home programs where Medicare site-neutral payments justify capital deployment.
- IV Catheters:Peripheral and central venous access devices manufactured from biocompatible polymers command premium pricing over DEHP-containing alternatives. German and Japanese acute care systems are accelerating conversions to polyurethane and silicone formulations ahead of regulatory deadlines.
- Infusion Sets:Disposable tubing assemblies with needle-free connectors.
- Safety Devices:Closed-system transfer devices and needle guards for hazardous drug handling.
- Others:Pole-mounted carriers, battery packs, and carrying cases.
Volume placements concentrate in Infusion Pumps; the faster expansion belongs to Safety Devices.
Therapy Area:
Oncology biologics command the highest per-patient revenue, while infectious disease protocols deliver volume through standardized antibiotic regimens.
- Oncology:Antibody-drug conjugates and immune checkpoint inhibitors require extended infusion protocols exceeding four hours that institutional settings cannot accommodate at scale. United States discharge planning teams are routing these cases to home infusion under site-neutral reimbursement.
- Infectious Diseases:Parenteral antibiotic therapy for osteomyelitis and endocarditis follows established clinical pathways with lower nursing complexity. Demand is climbing fastest in United States metropolitan infusion suites where geographic density supports 24/7 on-call coverage.
- Pain Management:Patient-controlled analgesia and epidural infusions for palliative care.
- Immunology:Immunoglobulin replacement and monoclonal antibody administration.
- Gastroenterology:Parenteral nutrition for short bowel syndrome and malabsorption disorders.
- Hematology:Chelation therapy and factor replacement for bleeding disorders.
Revenue gravity centers on Oncology; Immunology is expanding most quickly as subcutaneous protocols reduce nursing dependency.
End User:
Direct-to-patient models compete with hybrid ambulatory approaches for site-of-care economics and patient preference.
- Home Healthcare Agencies:Full-service organizations bundling nursing, pharmacy, and equipment into single-case rates. United States specialty pharmacy benefit managers are consolidating purchasing authority through these entities.
- Specialty Clinics:Physician-supervised infusion centers with on-site pharmacy compounding.
- Nursing Services:Staffing agencies providing per-visit or per-hour clinical labor.
- Rehabilitation Centers:Post-acute facilities transitioning patients to independent home management.
Contracting authority concentrates in Home Healthcare Agencies; the steepest expansion trajectory belongs to Specialty Clinics as metropolitan networks proliferate.
Delivery Mode:
Route selection determines pump complexity, nursing time, and patient training burden.
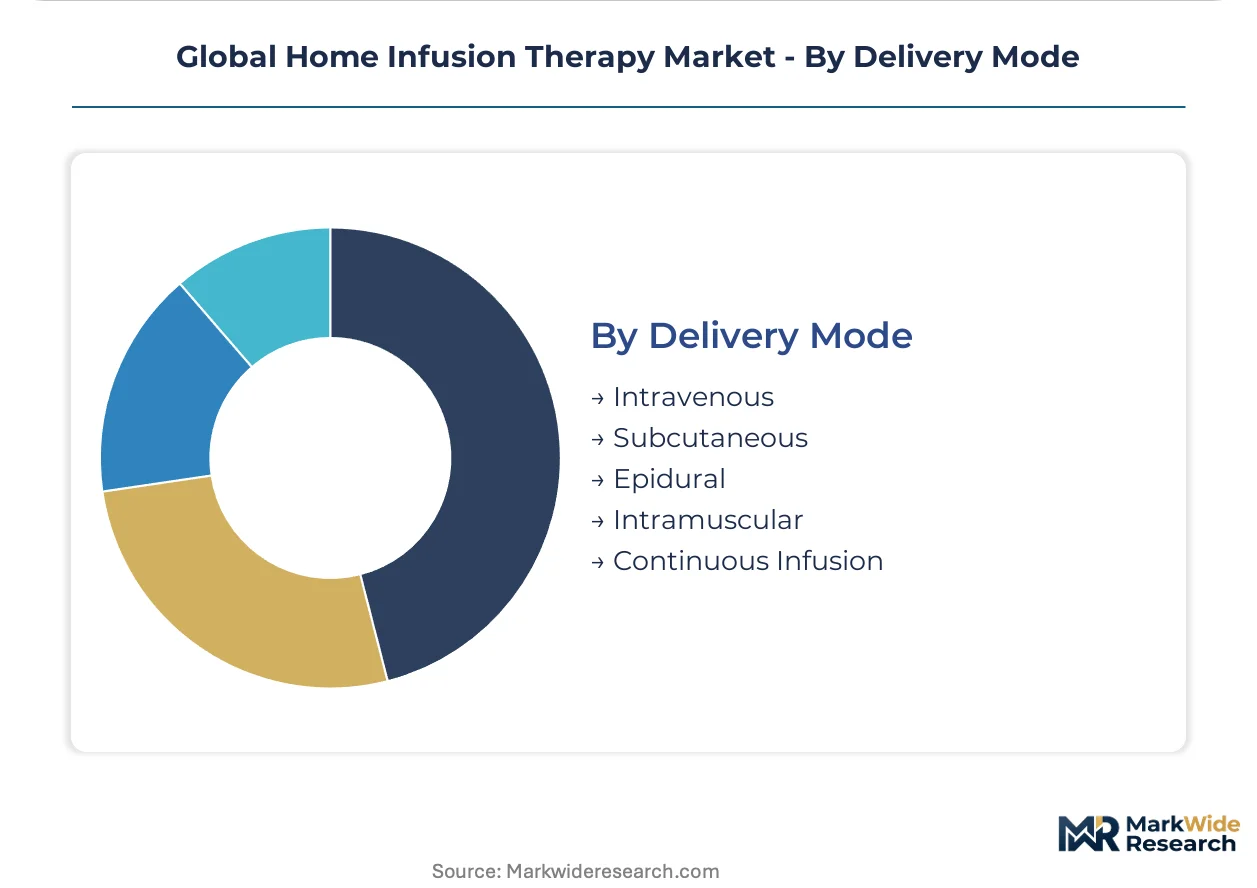
- Intravenous:Central and peripheral venous access with programmable flow control remains the default for high-volume infusions and vesicant medications. United States oncology protocols continue to specify IV delivery for antibody-drug conjugates.
- Subcutaneous:Rapid-push immunoglobulin administration reduces nursing time by approximately 70 percent and opens home therapy to patients previously requiring institutional placement. German and Australian reimbursement frameworks are expanding coverage for subcutaneous routes.
- Epidural:Catheter-based regional anesthesia for chronic pain and obstetric applications.
- Intramuscular:Depot formulations and intermittent antibiotic boluses.
- Continuous Infusion:24-hour basal delivery for chemotherapy, inotropes, and parenteral nutrition.
Procedure volume concentrates in Intravenous delivery; Subcutaneous protocols are gaining share fastest as patient preference and labor efficiency align.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States discharge planning teams and German hospital systems currently concentrate demand for home infusion therapy, with site-neutral reimbursement frameworks and biologic pipeline expansion compressing site-of-care economics across both markets.
United States
Medicare site-neutral payment rules and oncology biologic protocols drive demand concentration. FDA 503B compounding guidance imposes sterility assurance testing requirements on outsourcing facilities. Metropolitan infusion suites in Chicago, Houston, and Phoenix anchor hybrid care models combining home nursing with supervised ambulatory access.
Germany
Hospital-at-home reimbursement expansion and subcutaneous immunoglobulin protocol adoption reshape care delivery. EMA oversight of sterile compounding facilities aligns quality standards with hospital pharmacy benchmarks. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host precision elastomer manufacturing for pump component supply.
Japan
Aging demographics and chronic disease prevalence expand parenteral nutrition and palliative infusion demand. PMDA electromechanical safety requirements under JIS standards extend product validation timelines. Tokyo-Osaka metropolitan corridors concentrate specialty pharmacy networks and home healthcare agency deployment.
Australia
Subcutaneous immunoglobulin reimbursement expansion and rural nursing labor scarcity accelerate delivery mode shifts. TGA medical device regulations mandate ISO 80601-2-24 compliance for programmable pump imports. Sydney and Melbourne metropolitan clusters support 24/7 on-call infusion nurse coverage density thresholds.
United Kingdom
NHS hospital-at-home pilots and oncology discharge pathway redesigns redirect institutional volume. MHRA alignment with EU MDR post-Brexit maintains stringent pump safety validation requirements. London and Greater Manchester health systems lead procurement consolidation through specialty pharmacy benefit managers.
Global Home Infusion Therapy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with electromechanical pump fabrication consolidating around captive elastomer supply chains while pharmacy services fragment across geographic density thresholds. Three strategic archetypes dominate: vertically integrated device manufacturers with raw material backward integration, full-service home health agencies bundling nursing and pharmacy, and specialty pharmacy benefit managers consolidating purchasing authority. M&A activity targets metropolitan infusion suite networks and 503B outsourcing facility capacity, while portfolio diversification moves capture subcutaneous protocol and closed-system transfer device segments.
Within the integrated device tier, Baxter International Inc. and B. Braun Melsungen AG occupy positions anchored by in-house elastomer production capabilities. Fresenius Kabi AG exemplifies the formulation-anchored archetype through captive parenteral nutrition manufacturing. Option Care Health Inc. represents geographic density specialization with metropolitan infusion suite network scale.
| Leading Market Players |
|---|
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Fresenius Kabi AG |
| Option Care Health Inc. |
| ICU Medical Inc. |
| Optum Inc. |
| CVS Health |
| McKesson Corporation |
| BD |
| Others |
Supply & Pricing Matrix
ISO 80601-2-24 certification tiers bifurcate the electromechanical pump market into premium-validated and economy-unvalidated strata, with FDA 503B compliance requirements propagating this division through sterile compounding services and elastomer sourcing decisions across United States and German supply networks.
Pricing Analysis
High-volume disposable infusion sets trade on thin margins against low-unit-capital pumps that capture software upgrade subscriptions. Price differentiation hinges on FDA 503B certification tier and captive elastomer production, with German and Japanese manufacturers commanding premiums for medical-grade silicone. Cost compression in standard IV catheters intensifies as Chinese polymer converters expand DEHP-free PVC capacity. Hospital procurement committees exhibit highest price sensitivity; oncology biologic protocols show lowest sensitivity due to site-neutral reimbursement parity.
Supply Chain Analysis
Medical-grade silicone supply rests on German industrial clusters in Baden-Württemberg and North Rhine-Westphalia, with Japanese precision elastomer producers and United States petrochemical derivatives filling specialty grades. Raw material dependencies span pharmaceutical-grade thermoplastic elastomers, lithium-ion pump battery cells, and biocompatible polyurethane formulations. Single-source vulnerability concentrates in high-purity silicone for peristaltic pump mechanisms. Distribution runs through specialty pharmacy benefit managers bundling device, drug, and nursing into single-case rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 503B sterility assurance mandates erect a cost-of-compliance barrier that favors incumbents with validated environmental monitoring programs, entrenching quality infrastructure as a sustainable moat against undercapitalized entrants.
For Market Incumbents: Acquire metropolitan infusion suite networks to defend against site-neutral reimbursement compression threatening standalone home nursing models. Consolidate 503B outsourcing facility capacity before state-level pharmacy board enforcement intensifies. Backward integration into medical-grade elastomer production insulates margin structures from petrochemical volatility. For New Entrants and Emerging Players: Rural exurban nursing labor scarcity presents the most penetrable white-space target, where patient density falls below 24/7 on-call coverage thresholds for established agencies. Subcutaneous immunoglobulin protocol specialization reduces capital intensity versus full-service infusion pump deployment. Reimbursement strategy anchored to German and Australian subcutaneous route expansion frameworks accelerates payer acceptance. For Investors and Strategic Acquirers: Re-rating potential sits with 503B-certified compounders possessing hospital-at-home pharmacy partnerships given Medicare site-neutral rulemaking acceleration. Long-term viability frames around captive sterile capacity and geographic nursing density. The signal to watch is state-level scope-of-practice expansion enabling paramedic-administered infusion protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Transfer Device Integration | FDA beyond-use dating requirements for hazardous drug compounding mandate CSTD adoption across legacy pump installations. |
| Metropolitan Infusion Suite Network Expansion | Hybrid ambulatory-home models capture site-neutral reimbursement while addressing patient proximity preferences in Chicago and Houston clusters. |
| Subcutaneous Protocol Development | Immunoglobulin rapid-push administration reduces nursing time seventy percent and expands addressable patient populations. |
| Medical-Grade Elastomer Backward Integration | In-house silicone production secures raw material access against petrochemical supply volatility affecting pump component costs. |
| Electronic Health Record Interoperability Investment | Epic and Cerner API integration requirements fragment vendor development resources and create switching costs for hospital systems. |
Research Methodology
Multi-period observation of Medicare site-neutral payment rulemaking, FDA 503B enforcement patterns, and elastomer pricing indices anchored the trend analysis, supplemented by interviews with home infusion pharmacy directors, biomedical equipment procurement managers, GPO contracts specialists, and 503B facility quality officers. Secondary validation drew from FDA warning letter databases, CMS Medicare claims data, ISO 80601-2-24 certification registries, and hospital system capital expenditure disclosures. Bottom-up pump shipment modeling and top-down therapy-area spending estimates were triangulated against reimbursement rate schedules.
Input-output matrices mapped electromechanical pump replacement cycles, sterile compounding volume throughput, and nursing labor deployment density across product type, therapy area, end user, and delivery mode segmentation dimensions. CAGRs were derived from regression analysis of historical reimbursement shifts and biologic pipeline expansion trajectories. Forecast inputs incorporated Medicare site-neutral payment parity implementation timing and subcutaneous protocol adoption curves across German and Australian reimbursement frameworks.
Revisions become necessary when FDA 503B guidance enforcement intensity shifts, Medicare site-neutral rulemaking accelerates or stalls, or elastomer supply disruptions from petrochemical feedstock volatility materialize. Forecasts reflect documented assumptions regarding therapy-area migration rates and nursing scope-of-practice expansion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
Global Nursing Care Market
Home Healthcare
US House Calls Market
Home Healthcare
Chemotherapy at Home Services Market
Home Healthcare
Global Elderly Care Market
Home Healthcare
Europe Home Care Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
US Home Healthcare Market
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Adult Day Care Market
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
Global Home Health Care Services Market
Home Healthcare
Global Ambient Assisted Living (AAL) Market
Home Healthcare
Portable Toilet for Elderly Market