
 Elder Care Subscription Market | 2026-2036
Elder Care Subscription Market Size, Share, and Industry Trends Forecast 2026-2036
Elder Care Subscription Market Foresight
CMS reimbursement parity for remote patient monitoring is expanding the addressable market for home-based elder care subscriptions. Home Instead Senior Care leverages its franchise network density to sustain last-mile service coverage across suburban markets. BrightStar Care anchors its competitive position through clinical staffing credentials that exceed state minimums. Always Best Care Senior Services differentiates by integrating technology-enabled care coordination with traditional companion services.
An elder care subscription constitutes a recurring-payment service model delivering coordinated non-medical and health-adjacent support to aging individuals, typically encompassing remote vital sign monitoring, meal logistics, social engagement, and medication adherence protocols administered through digital platforms and in-person caregiver dispatch. The primary commercial purpose centers on reducing acute care utilization while extending independent living duration for seniors with chronic conditions or functional limitations. Health Monitoring commands the largest revenue share within service type segments due to its direct linkage with payer cost-avoidance incentives, while Telehealth Platforms represent the fastest-expanding technology segment as health systems seek scalable alternatives to clinic-based geriatric follow-up. Tiered Services within subscription models capture disproportionate margin pools by aligning feature bundles with Medicare Advantage supplemental benefit tiers.
FDA oversight of software-as-medical-device applications intersects with state-level home care licensing regimes to create a bifurcated compliance landscape for platform operators. HIPAA requirements for data portability and breach notification impose infrastructure costs that favor scaled providers with dedicated security operations. Stakeholders must monitor evolving CMS guidance on in-home digital health reimbursement to calibrate capital allocation between technology development and caregiver workforce expansion.
Market Dynamics
CMS reimbursement parity for remote patient monitoring is compressing the economics of traditional clinic-based geriatric care while expanding the viable service radius for home-based subscription operators.
Growth Catalysts
- CMS Digital Health Reimbursement Expansion:Medicare Advantage plans now bundle supplemental home care benefits, creating direct revenue pathways for remote monitoring services. This policy shift aligns payer incentives with independent living extension.
- IoT Sensor Miniaturization:Wearable vital sign monitors with multi-day battery life enable continuous data streams without disrupting senior routines. Device manufacturers report deployment scaling across suburban markets previously deemed uneconomical.
- Japan's Super-Aged Society Density:Metropolitan Tokyo and Osaka prefectures concentrate over-75 populations exceeding 15% of residents, generating sufficient demand density for profitable subscription operations at lower per-capita marketing spend.
Market Restraints
- HIPAA Infrastructure Costs:Data portability and breach notification requirements impose dedicated security operations expenditures that favor scaled providers over emerging entrants.
- Caregiver Supply Concentration:Licensed home health aides cluster in coastal US metropolitan areas, leaving interior and rural markets with 40% staffing gaps relative to subscriber demand.
- FDA Software-as-Medical-Device Oversight:Algorithm-based fall detection and medication adherence tools face bifurcated federal-state compliance pathways that extend commercialization timelines.
Strategic Opportunities
- Germany's Pflegeversicherung Digitalization Mandate:Long-term care insurance digitization creates reimbursement channels for technology-enabled care coordination platforms.
- AI-Enabled Predictive Triage:Machine learning models analyzing passive sensor data promise emergency department visit reduction. Convergence of edge computing and natural language processing enables real-time caregiver dispatch optimization.
- Direct-to-Employer Channel:Self-insured corporations seek elder care subscriptions as dependent care benefits to reduce workforce productivity loss from employee caregiving responsibilities.
Industry Challenges
- Geriatric-Certified Nurse Practitioner Scarcity:Clinical oversight roles require specialized credentials with limited training program capacity, constraining service quality scaling.
- Legacy EHR Integration Friction:Subscription platforms must interface with Epic, Cerner, and Meditech systems through non-standard APIs, requiring custom development per health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elder Care Subscription Market |
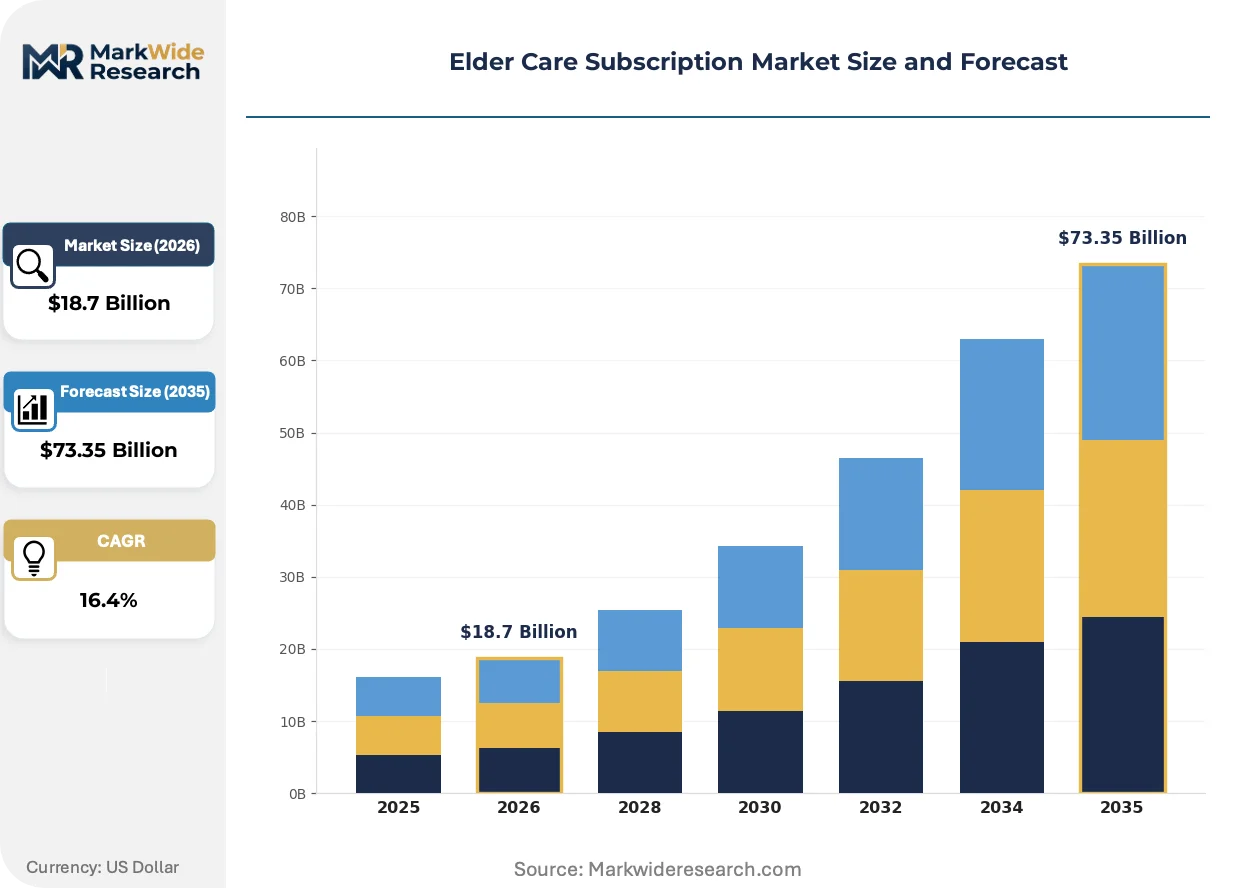
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Health Monitoring, Meals Delivery, Companionship Services, Medication Management End User: Seniors, Family Caregivers, Healthcare Providers, Assisted Living Facilities Subscription Model: Monthly Packages, Annual Plans, Pay-As-You-Go, Tiered Services Technology: Mobile Apps, Telehealth Platforms, Wearable Devices, Smart Home Solutions |
| Companies Covered | Interim HealthCare, Senior Helpers, Home Instead Senior Care, Homewatch CareGivers, ComForCare Home Care, Right at Home, BrightStar Care, Always Best Care Senior Services, Synergy HomeCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elder Care Subscription Market Shifts & Advancements
Passive environmental sensing and voice-first interfaces are displacing active patient engagement requirements, lowering adoption barriers for cognitively declining seniors.
Multi-sensor ambient monitoring is consolidating discrete point solutions into unified platforms. Ceiling-mounted radar units, bed pressure mats, and smart pill dispensers now feed single dashboards. Medicare Advantage plans in Florida and Arizona deploy these integrated systems to reduce nursing facility diversion costs. The technology stack is consolidating vendor relationships from five-plus specialized suppliers to two-to-three full-stack platform partners.
The EU AI Act's risk classification framework imposes conformity assessment requirements on algorithmic care recommendations. High-risk applications including fall risk scoring and medication interaction alerts face notified body oversight. German and French operators are responding by segregating EU-specific algorithm versions with enhanced explainability features from US deployments.
Adult children increasingly initiate subscription contracts rather than seniors themselves. This proxy purchasing pattern shifts marketing channels from direct-response television to employer benefits portals and financial advisor referrals. The behavioral shift concentrates subscriber acquisition in coastal metropolitan corridors where adult children maintain professional employment with dependent care benefits.
Elder Care Subscription Market Segmentation
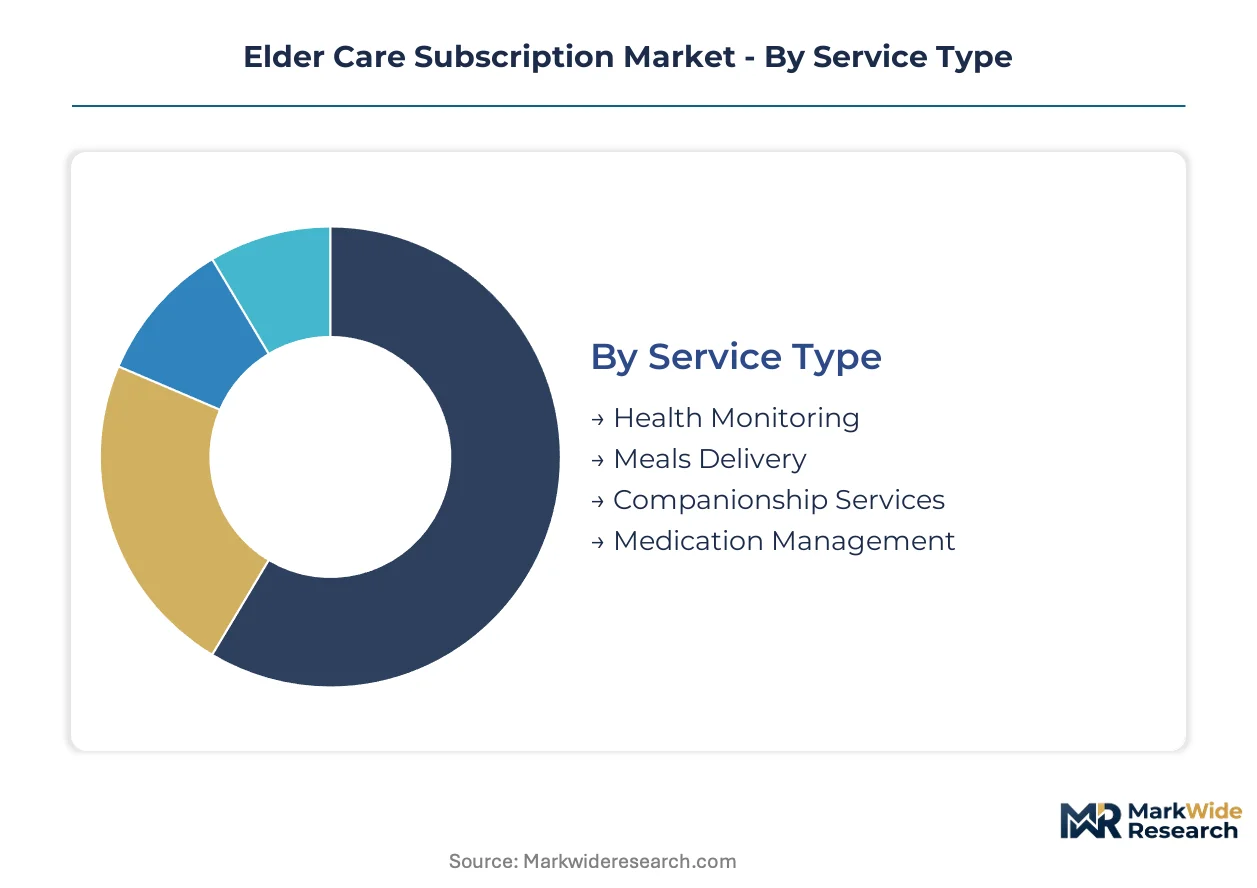
Subscription economics in elder care depend on matching service intensity to payer willingness and clinical acuity. Segmentation reveals where Medicare Advantage plans concentrate reimbursement versus where families pay out-of-pocket.
Service Type:
Buyers in this category sort by clinical risk tolerance and regulatory comfort—health systems demand FDA-cleared monitoring while families prioritize social engagement.
- Health Monitoring:Remote vital sign tracking through FDA-cleared pulse oximeters, blood pressure cuffs, and weight scales transmits continuous data to clinical dashboards. Demand concentrates among Medicare Advantage plans in Florida and Arizona seeking nursing facility diversion. CMS reimbursement parity for remote patient monitoring directly expands viable deployment economics.
- Meals Delivery:Nutritionally calibrated meal kits addressing diabetes, renal disease, and cardiac conditions with dietitian oversight. Growth clusters in suburban markets where grocery access barriers intersect with chronic condition prevalence. Payer cost-avoidance incentives align subscriber acquisition with hospital system discharge planning.
- Companionship Services:Scheduled in-person social visits and transportation assistance addressing isolation metrics. Family caregivers in coastal metropolitan corridors drive contract initiation.
- Medication Management:Smart pill dispensers with adherence tracking and pharmacist intervention protocols. Pharmacy benefit managers increasingly bundle these services for high-risk polypharmacy populations.
Volume sits with Health Monitoring; growth tilts toward Meals Delivery.
End User:
Contract authority and payment source diverge sharply—seniors rarely initiate subscriptions while healthcare providers control reimbursement pathways.
- Seniors:Direct subscribers typically exhibit high health literacy and technology comfort, representing a narrow sliver of the addressable over-75 population. Cognitive decline barriers limit self-directed adoption.
- Family Caregivers:Adult children initiate the majority of contracts through employer benefits portals and financial advisor referrals. Proxy purchasing concentrates subscriber acquisition in professional employment corridors.
- Healthcare Providers:Accountable care organizations and Medicare Advantage plans deploy subscriptions as population health infrastructure. Risk-based contracts create direct revenue pathways for remote monitoring services.
- Assisted Living Facilities:Operators subscribe to technology platforms for resident monitoring and staff optimization. Labor cost pressures accelerate platform adoption across multi-site operators.
Contract volume flows through Family Caregivers; Healthcare Providers command the steepest expansion trajectory.
Subscription Model:
Pricing architecture reflects payer sophistication—annual commitments signal institutional procurement while pay-as-you-go serves trial behavior.
- Monthly Packages:Standardized service bundles with fixed caregiver hours and technology access. Churn rates exceed annual plans but lower entry barriers for family-initiated contracts.
- Annual Plans:Prepaid subscriptions with discounted rates and priority caregiver matching. Medicare Advantage supplemental benefit tiers anchor demand.
- Pay-As-You-Go:Per-visit or per-interaction pricing for episodic needs. Limited scale due to caregiver dispatch inefficiencies.
- Tiered Services:Feature bundles aligned with Medicare Advantage benefit structures—basic companion care, intermediate health monitoring, advanced clinical oversight. Captures disproportionate margin pools through upsell pathways.
Annual Plans lock in predictable revenue; Tiered Services capture expanding margin contribution.
Technology:
Platform selection hinges on integration burden versus user accessibility—health systems demand EHR connectivity while seniors need frictionless interfaces.
- Mobile Apps:Caregiver coordination portals and family communication tools with scheduling and billing transparency. Adult children initiate usage; senior adoption lags.
- Telehealth Platforms:Video consultation infrastructure for geriatric follow-up and specialist access. Health systems in the United States deploy these as scalable alternatives to clinic-based care. Regulatory clarity on CMS reimbursement accelerates health system procurement.
- Wearable Devices:Continuous vital sign monitoring through wrist-worn or pendant form factors. Battery life and comfort trade-offs limit continuous use.
- Smart Home Solutions:Passive environmental sensing through motion detectors, bed sensors, and smart pill dispensers. Voice-first interfaces lower adoption barriers for cognitively declining seniors.
Smart Home Solutions accumulate installed base fastest; Telehealth Platforms gain share in institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for elder care subscriptions concentrates in markets with aging demographics, favorable reimbursement frameworks, and sufficient caregiver supply density. The United States dominates commercial volume through Medicare Advantage bundling, while Japan and Germany present parallel growth vectors through public insurance digitization mandates. Emerging adoption clusters in Australia and the United Kingdom reflect employer benefit expansion and social care privatization trends.
United States
Medicare Advantage plans in Florida and Arizona drive subscriber acquisition through supplemental home care benefit tiers that bundle remote monitoring with traditional services. CMS reimbursement parity for remote patient monitoring under the Physician Fee Schedule creates direct revenue pathways for platform operators. The suburban corridor between Phoenix and Tucson hosts concentrated deployment of ambient sensor networks by multi-site operators seeking nursing facility diversion savings.
Japan
Metropolitan Tokyo and Osaka prefectures concentrate over-75 populations exceeding 15% of residents, generating sufficient demand density for profitable subscription operations at reduced per-capita marketing spend. The Ministry of Economy, Trade and Industry (METI) promotes digital health adoption through regional integrated care system subsidies. Kansai-based operators deploy voice-first interfaces targeting cognitively declining seniors in Osaka's dense apartment complexes.
Germany
Pflegeversicherung digitization mandates create reimbursement channels for technology-enabled care coordination platforms serving the 5.4 million long-term care beneficiaries. The Federal Ministry of Health (BMG) pilots algorithmic care recommendation systems under strict EU AI Act conformity assessment protocols. North Rhine-Westphalia's Ruhr region hosts clustered deployment of integrated sensor-to-dispatch platforms by multi-site care networks.
Australia
Self-insured corporations in Sydney and Melbourne adopt elder care subscriptions as dependent care benefits to reduce workforce productivity loss from employee caregiving responsibilities. The Therapeutic Goods Administration (TGA) regulates software-as-medical-device applications with risk-based classification pathways. New South Wales hosts concentrated pilot programs linking home monitoring data to hospital-at-home discharge protocols.
United Kingdom
Local authority social care commissioning shifts toward outcomes-based contracts that reward independent living extension through technology-enabled support. The Care Quality Commission (CQC) oversees registration of digital care coordination platforms alongside traditional domiciliary services. Greater Manchester's integrated care system deploys tiered subscription models across its 2.8 million population footprint.
Elder Care Subscription Market Competitive Landscape
United States operators anchor the scale tier through franchise network density and Medicare Advantage contracting relationships; European specialists hold position through public insurance integration and regulatory compliance depth. Market structure tilts toward consolidation as multi-site operators acquire regional platforms to achieve caregiver supply pooling and technology stack standardization. Two strategic archetypes dominate: clinical credentialing specialists competing on staffing quality thresholds, and technology-forward coordinators optimizing sensor-to-dispatch logistics. Competitive moves concentrate on strategic partnerships with health systems for risk-based contracting and geographic expansion through franchise development in suburban corridors.
Within the clinical credentialing tier, BrightStar Care and Home Instead Senior Care occupy positions exemplifying workforce quality differentiation and last-mile service coverage respectively. Always Best Care Senior Services represents the technology-forward archetype through its integration of care coordination platforms with traditional companion services. These three operators illustrate the strategic bifurcation between clinical staffing depth and digital infrastructure investment that defines competitive positioning in this market.
| Leading Market Players |
|---|
| Interim HealthCare |
| Senior Helpers |
| Home Instead Senior Care |
| Homewatch CareGivers |
| ComForCare Home Care |
| Right at Home |
| BrightStar Care |
| Always Best Care Senior Services |
| Synergy HomeCare |
| Others |
Supply & Pricing Matrix
Medicare Advantage supplemental benefit bundling pressures platform operators to absorb upfront sensor deployment costs while recovering margin through multi-year subscriber retention. This procurement preference forces supply chain reconfiguration toward volume-scaled device manufacturing partnerships and away from premium per-unit sourcing.
Pricing Analysis
Volume concentrates in standardized monthly packages with thin margins, while tiered services aligned with Medicare Advantage benefit structures capture disproportionate margin contribution. Price differentiation rests on clinical oversight intensity and FDA device clearance tier, with health system contracts commanding premium rates over family-initiated subscriptions. Cost compression in basic companion care tiers is intensifying because caregiver wage inflation outpaces reimbursement rate adjustments. Family caregivers in coastal metropolitan corridors exhibit highest price sensitivity, whereas risk-bearing Medicare Advantage plans prioritize outcome guarantees over per-dollar efficiency.
Supply Chain Analysis
FDA software-as-medical-device clearance and state home care licensing create dual qualification gates that filter component suppliers and platform integrators. Hardware concentrates in Taiwan for sensor fabrication, China for battery and connectivity modules, and the United States for clinical-grade device final assembly. Raw material dependencies span lithium-ion cells, millimeter-wave radar components, and medical-grade polymers. Single-source vulnerability runs through specialized fall-detection algorithm providers. Distribution runs through health system procurement committees and Medicare Advantage plan administrator networks rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as HIPAA infrastructure costs and CMS reimbursement complexity force sub-scale operators toward acquisition or exit. Platform operators lacking dedicated security operations or direct payer contracts face existential margin pressure.
For Market Incumbents: Hedge against caregiver supply concentration by establishing captive training pipelines in interior US markets where staffing gaps reach 40% relative to demand. Secure backward integration into ambient sensor manufacturing through exclusive partnerships with Taiwanese fabrication facilities to lock in component allocation ahead of competing platforms.
For New Entrants and Emerging Players: Enter via Germany's Pflegeversicherung digitization mandate, where reimbursement channels for technology-enabled care coordination remain underdeveloped relative to beneficiary volume. Target the Ruhr region's multi-site care networks with EU AI Act-compliant algorithm versions featuring enhanced explainability features distinct from US deployments.
For Investors and Strategic Acquirers: The window for entry favors clinical credentialing specialists with excess state licensing capacity that can absorb technology-forward regional platforms. Acquisition targets should demonstrate direct Medicare Advantage risk-contracting relationships rather than fee-for-service revenue concentration. Watch CMS guidance evolution on in-home digital health reimbursement as the primary inflection signal for capital reallocation between technology development and workforce expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Health System Risk Contracting | Direct Medicare Advantage relationships lock in predictable subscriber volume and reduce acquisition cost. |
| Caregiver Workforce Pipeline Development | Proprietary training programs in underserved interior markets address 40% staffing gaps and build competitive moats. |
| EU AI Act Compliance Segregation | Dual algorithm versions for European and US deployments satisfy notified body oversight without compromising domestic performance. |
| Sensor-to-Dispatch Platform Integration | Unified dashboards consolidating radar, pressure mat, and dispenser data reduce vendor management burden for multi-site operators. |
| Direct-to-Employer Channel Expansion | Dependent care benefit positioning captures adult children initiating contracts through employer portals in professional employment corridors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with Medicare Advantage plan administrators, home care franchise operators, geriatric-certified nurse practitioners, and biomedical device procurement managers at health systems. Primary fieldwork triangulated against CMS reimbursement guidance documents, FDA software-as-medical-device clearance databases, state-level home care licensing registries, and hospital procurement database extracts. Bottom-up subscriber volume estimates from platform operator disclosures converged with top-down payer spending projections across the analysis window.
Granularity-level modeling distinguished service intensity tiers, technology stack configurations, and regional reimbursement frameworks at the metropolitan statistical area level. CAGRs derived from fitted growth curves applied to subscriber penetration rates, device deployment volumes, and per-subscriber revenue trajectories. Forecast inputs incorporated Medicare Advantage plan expansion timelines, caregiver workforce training pipeline capacity, and sensor battery life improvement curves affecting replacement cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt CMS reimbursement rate adjustments or state-level licensing regime fragmentation. Model assumptions reflect documented payer contracting patterns, device manufacturer production disclosures, and workforce survey data. A model refresh is warranted upon material change in CMS remote patient monitoring fee schedule guidance or EU AI Act enforcement precedent affecting algorithmic care recommendations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
Portable Toilet for Elderly Market
Home Healthcare
Global Elderly Care Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
US House Calls Market
Home Healthcare
Europe Home Care Market
Home Healthcare
Home Care Market
Home Healthcare
Home Healthcare Market
Home Healthcare
Home Care Service Market
Home Healthcare
US Home Healthcare Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Home Care Products Market
Home Healthcare
Global Home Health Hub Market
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Global Ambient Assisted Living (AAL) Market