
 Olive Leaf Extract Market | 2026-2036
Olive Leaf Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Olive Leaf Extract Market Outlook
Synthetic antioxidants in food preservation are realigning toward plant-derived alternatives as olive polyphenols gain cost parity at scale. Comvita Ltd. leverages its New Zealand apiary-to-extraction infrastructure to secure premium oleuropein supply chains. Gaia Herbs Inc. differentiates through certified organic cultivation partnerships in North American growing regions. Evergreen Life Products Srl anchors its competitive position via Sicilian estate-controlled harvesting and cold-press extraction protocols.
Olive leaf extract comprises bioactive compounds—principally oleuropein, hydroxytyrosol, and verbascoside—derived from Olea europaea leaves through aqueous or solvent extraction, standardized typically to 6-20% oleuropein content for commercial applications. The extract serves primarily as a natural antimicrobial, antioxidant, and vasodilatory agent across dietary supplement and functional food formulations. Liquid extractions command premium positioning in pharmaceutical-grade applications where precise titration and rapid bioavailability drive procurement decisions. Powder formats dominate bulk nutraceutical manufacturing due to stability in tableting and encapsulation processes, while skin care applications within cosmetics represent the fastest-growing demand vector as formulators substitute synthetic preservatives with olive-derived antimicrobials.
EFSA novel food catalog listings and EU Health Claims Regulation assessments shape permissible marketing language and substantiation requirements for olive polyphenol products across European member states. FDA GRAS self-affirmation pathways and DSHEA compliance frameworks govern U.S. market entry for dietary supplement applications, with USDA organic certification increasingly gating retail placement in premium channels. Stakeholders must monitor evolving pharmacovigilance data on oleuropein-drug interactions as regulatory bodies weigh therapeutic classification thresholds against current food-supplement designations.
Market Dynamics
Olive leaf extract supply chains are consolidating around Mediterranean estate-controlled harvesting as EFSA novel food approvals compress compliance timelines for European nutraceutical entrants. This regulatory acceleration is concentrating procurement relationships with vertically integrated cultivators who control extraction quality from leaf to finished ingredient.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined safety assessments for oleuropein-rich extracts are reducing time-to-market for immune-support formulations across EU member states.
- Pharmaceutical-Grade Liquid Demand:Precision titration requirements in clinical nutrition applications are pulling premium extraction capacity toward aqueous protocols with rapid bioavailability profiles.
- Cosmetic Preservative Substitution:Formulators in skin care are displacing synthetic antimicrobials with olive-derived polyphenols as clean-label mandates intensify.
Market Restraints
- Raw Material Concentration:Leaf supply clusters in Andalusia and Sicily create weather-dependent input volatility for non-estate processors.
- Extraction Cost Structure:Cold-press and supercritical CO2 protocols require capital-intensive equipment that elevates unit economics for small-batch producers.
- Therapeutic Classification Risk:Pharmacovigilance monitoring of oleuropein-drug interactions by EMA and FDA threatens reclassification from food supplement to pharmaceutical status.
Strategic Opportunities
- North American Organic Cultivation:USDA-certified growing partnerships in California and Arizona offer tariff-advantaged supply for premium supplement channels.
- Functional Food Integration:Beverage manufacturers are embedding standardized oleuropein into ready-to-drink immune support lines with shelf-stable powder formats.
- EU Green Deal Incentives:Circular economy subsidies for agricultural waste valorization are funding leaf-to-extract processing infrastructure upgrades.
Industry Challenges
- Analytical Chemist Scarcity:Standardization of hydroxytyrosol and verbascoside markers requires specialized phytochemistry expertise that outpaces graduate program output.
- Cross-Border Certification Timelines:Dual FDA GRAS self-affirmation and EFSA novel food dossier preparation extends product launch cycles by 18-24 months.
- Legacy Equipment Retrofit Costs:Solvent extraction facilities face capital outlays to convert aqueous systems for organic certification compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Olive Leaf Extract Market |
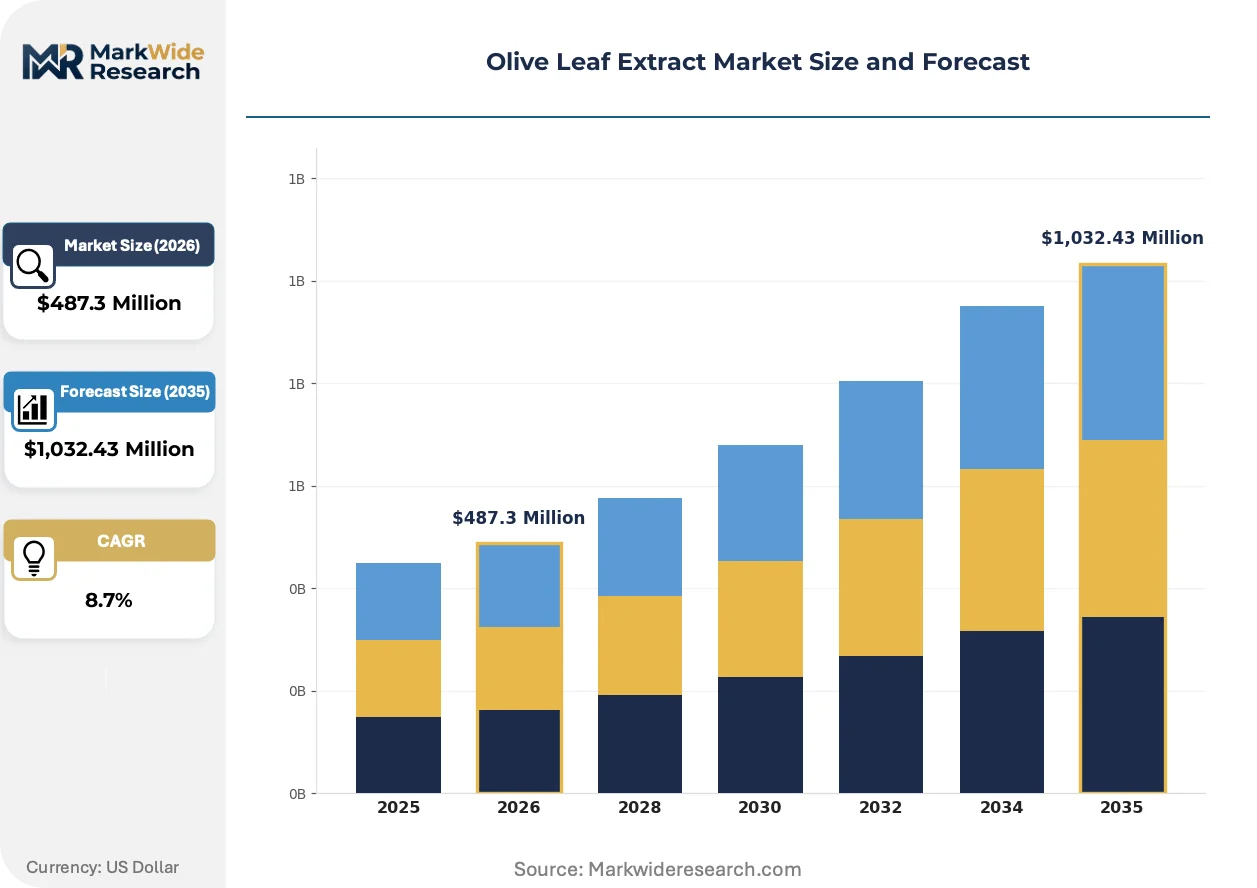
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powder, Liquid Extractions, Tea End User: Pharmaceuticals, Nutraceuticals, Food & Beverages, Cosmetics Distribution Channel: Online Retail, Health Stores, Supermarkets, Pharmacies Application: Dietary Supplements, Herbal Remedies, Functional Foods, Skin Care |
| Companies Covered | Comvita Ltd., Dohler GmbH, Dr. Willmar Schwabe GmbH and Co. KG, Barleans Organic Oils LLC, Gaia Herbs Inc., Olivus Inc., Evergreen Life Products Srl, International Flavors and Fragrances Inc., Medikonda Nutrients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Olive Leaf Extract Market Strategic Shifts
Supercritical fluid extraction is displacing conventional solvent methods as the dominant processing technology, while regulatory harmonization efforts and buyer procurement consolidation are compressing supplier margins. These forces are reshaping competitive positioning toward captive supply chains and certified organic cultivation.
Supercritical CO2 extraction technology is converging with ultrasonic-assisted protocols to enhance oleuropein yield rates while eliminating residual solvent concerns. Pharmaceutical-grade manufacturers in Germany and Switzerland are adopting these hybrid systems to meet USP monograph specifications. The technology convergence is enabling single-step purification that reduces downstream processing costs by consolidating extraction and concentration phases.
EFSA's updated guidance on novel food equivalence assessments is compressing dossier preparation timelines for olive leaf extract derivatives with established safety profiles. Food supplement manufacturers are accelerating EFSA Health Claims Regulation substantiation investments to secure Article 13.1 functional claims. Mediterranean suppliers with prior novel food approvals are capturing disproportionate share of new entrant co-manufacturing contracts.
Certification-driven procurement is concentrating buyer preference on USDA Organic and EU Organic certified extracts with full chain-of-custody documentation. North American contract manufacturers are disqualifying uncertified suppliers from RFP processes regardless of price positioning. The shift is most visible in premium supplement channels where retail placement requires third-party organic verification and pesticide residue testing below 0.01 ppm thresholds.
Olive Leaf Extract Market Segmentation
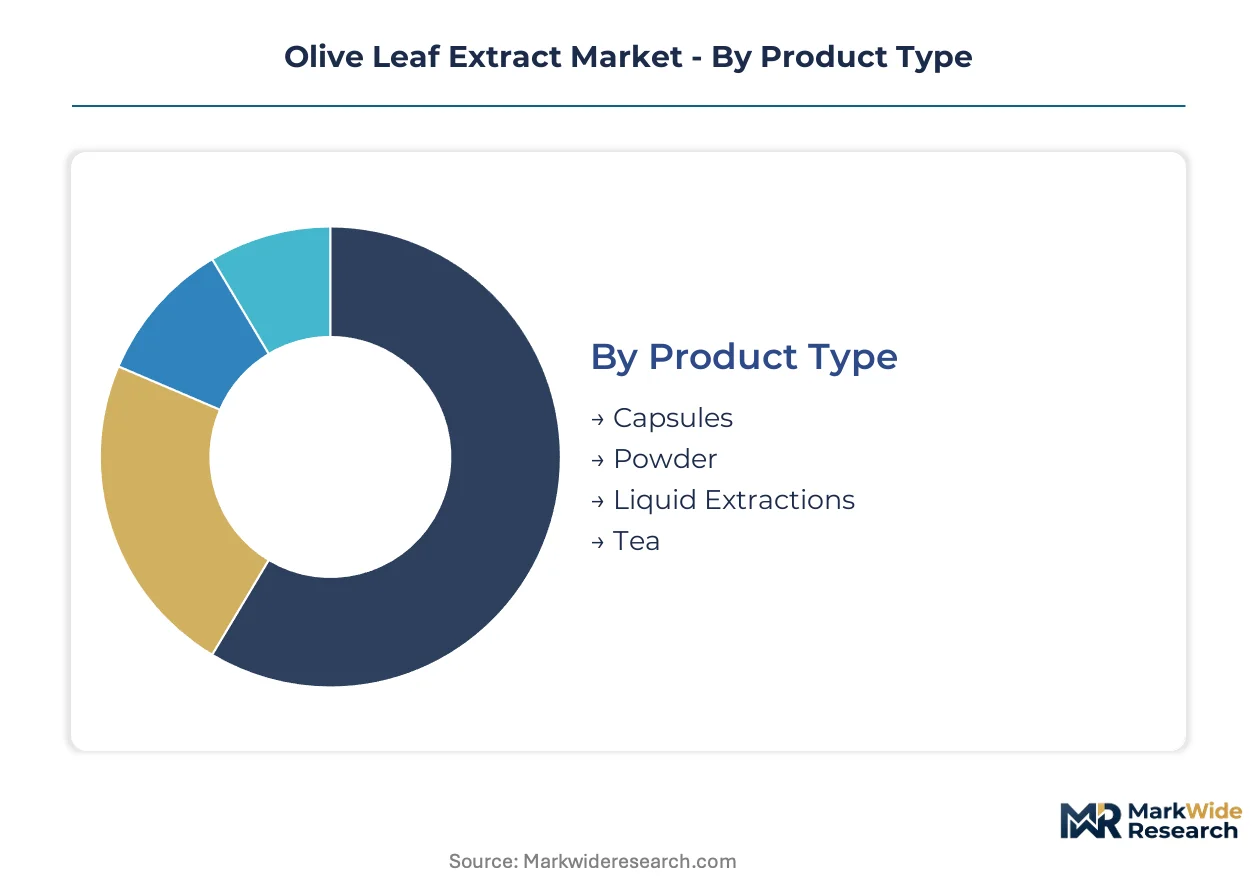
Olive leaf extract segmentation reflects divergent processing standards across pharmaceutical, nutraceutical, and cosmetic channels. Product format selection dictates extraction protocol investment, while end-use application determines regulatory compliance burden and margin capture potential.
Product Type:
Volume formats dominate bulk manufacturing, yet liquid extractions command premium positioning through bioavailability differentiation.
- Liquid Extractions:Aqueous and solvent-based concentrates standardized to 6-20% oleuropein content serve pharmaceutical-grade applications requiring precise titration. German and Swiss manufacturers prioritize these formats for clinical nutrition protocols where rapid absorption profiles justify procurement premiums.
- Powder:Spray-dried and freeze-dried variants offer stability in tableting and encapsulation processes, anchoring bulk nutraceutical manufacturing. California-based contract manufacturers source powder formats for high-volume supplement lines targeting mass-market immune support positioning.
- Capsules:Pre-measured dosage units streamline consumer compliance in preventive health regimens.
- Tea:Whole-leaf and cut-leaf formats occupy traditional wellness channels with minimal processing value-add.
Today's leader: Powder. Tomorrow's challenger: Liquid Extractions.
End User:
Application-driven purity requirements split the market between GMP-certified pharmaceutical demand and flexible cosmetic formulation standards.
- Cosmetics:Skin care formulators embed olive polyphenols as natural antimicrobial alternatives to synthetic preservatives. Clean-label mandates from Paris and Milan-based beauty houses are accelerating oleuropein inclusion in premium skincare lines targeting preservative-free positioning.
- Pharmaceuticals:Clinical nutrition and therapeutic applications require USP-grade specifications with full Certificate of Analysis documentation. Swissmedic and EMA pharmacovigilance monitoring of oleuropein-drug interactions shapes permissible therapeutic claims and dosing protocols.
- Nutraceuticals:Dietary supplement manufacturers balance standardization costs with immune-support marketing claims.
- Food & Beverages:Functional food integration demands shelf-stable formats compatible with thermal processing.
Cosmetics climbs fastest on preservative substitution demand; Pharmaceuticals holds margin concentration through specification barriers.
Distribution Channel:
Channel selection determines certification documentation requirements and price realization transparency.
- Online Retail:Direct-to-consumer platforms enable subscription-based immune support regimens with full traceability storytelling. Amazon and specialized wellness marketplaces are capturing share from brick-and-mortar as third-party testing documentation becomes standard listing requirement.
- Pharmacies:Pharmacist-recommended positioning in German and Italian apothecary networks supports premium pricing for standardized extracts. EU Health Claims Regulation compliance enables permissible efficacy language at point of sale.
- Health Stores:Staff-curated selection favors certified organic and full-spectrum formulations with educational collateral.
- Supermarkets:Mass-market placement requires economy pricing and simplified benefit messaging for unassisted purchase decisions.
Pharmacies retain trust premium; Online Retail expands most quickly on convenience and subscription mechanics.
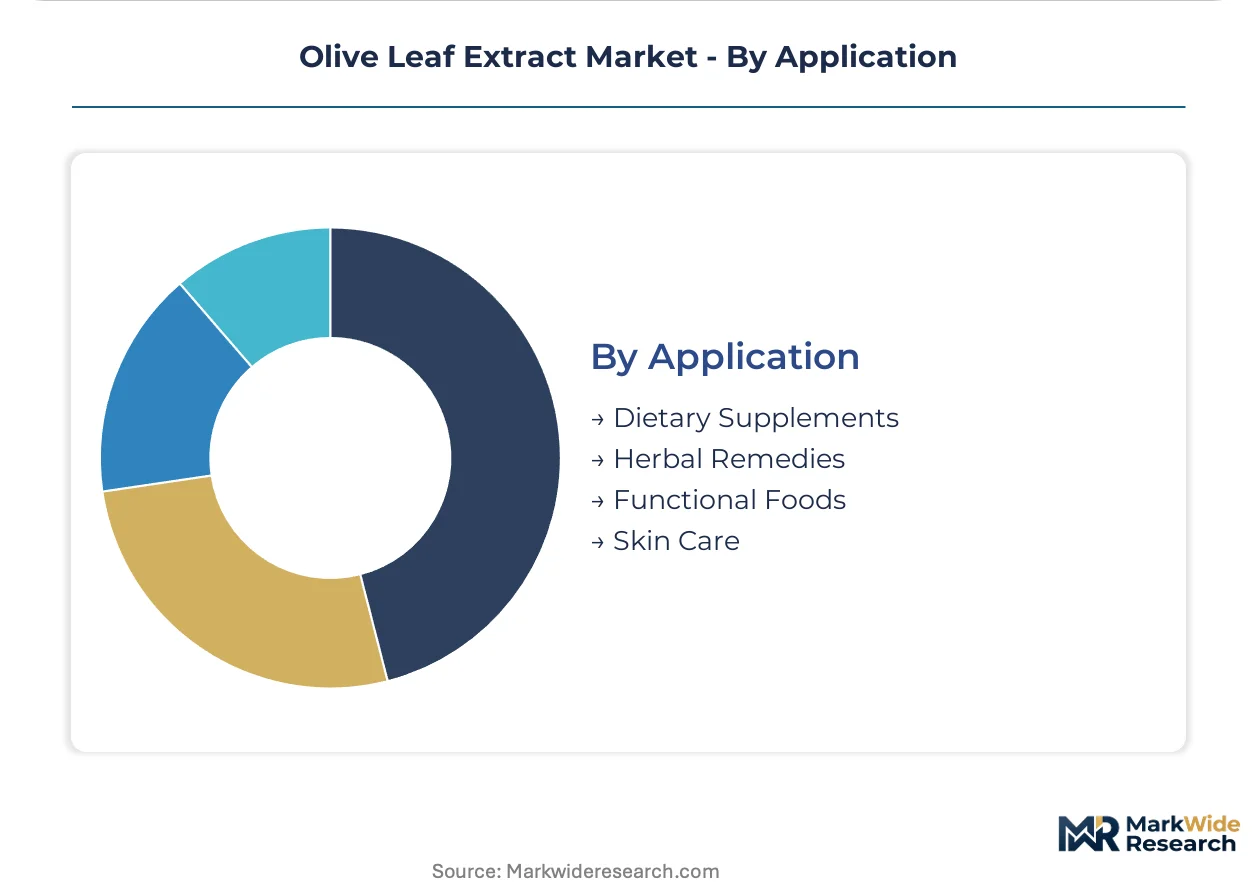
Application:
Functional positioning depth varies from disease-prevention claims requiring clinical substantiation to general wellness permissive under food regulations.
- Skin Care:Topical formulations leverage hydroxytyrosol antioxidant capacity for anti-aging and protective applications. Formulation labs in Barcelona and Provence are developing microencapsulated delivery systems to enhance dermal bioavailability and stability in emulsion bases.
- Dietary Supplements:Capsule and tablet formats dominate preventive health consumption with EFSA Article 13.1 functional claims driving permissible marketing language. Novel food approval status determines EU market access for concentrated oleuropein products.
- Herbal Remedies:Traditional medicine positioning operates under distinct regulatory frameworks with reduced evidentiary requirements.
- Functional Foods:Beverage and fortified food integration requires taste-masking and thermal stability solutions.
Skin Care gains share fastest on clean-label cosmetic momentum; Dietary Supplements maintains volume concentration through established consumption habits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mediterranean estate clusters in Spain and Italy concentrate raw material supply for olive leaf extract processing, with regulatory harmonization across the EU, North American organic cultivation expansion, and Asia-Pacific functional food integration reshaping procurement geography.
Spain
Andalusian olive cooperatives supply bulk leaf biomass to extraction facilities serving pharmaceutical-grade liquid demand. EFSA novel food catalog listings streamline market entry for standardized oleuropein products. Seville-based processors are upgrading cold-press infrastructure to meet EU Green Deal circular economy subsidies for agricultural waste valorization.
Italy
Sicilian estate-controlled harvesting anchors premium supply chains for cosmetic and nutraceutical applications. EU Health Claims Regulation assessments determine permissible marketing language for immune-support formulations. Florence and Milan formulation labs are developing microencapsulated delivery systems for skin care applications targeting preservative-free positioning.
United States
California and Arizona USDA-certified growing partnerships reduce tariff exposure for premium supplement channels. FDA GRAS self-affirmation pathways govern dietary supplement market entry with DSHEA compliance frameworks. Los Angeles and Phoenix contract manufacturers source powder formats for high-volume immune support lines.
Germany
Swissmedic-influenced pharmacovigilance monitoring shapes therapeutic classification thresholds for oleuropein-drug interaction data. EMA regulatory guidance affects permissible clinical nutrition claims across German-speaking markets. Munich and Hamburg extraction facilities adopt hybrid supercritical CO2 and ultrasonic-assisted protocols for USP-grade specifications.
Australia
TGA compliance requirements for complementary medicines influence extract standardization protocols for Asia-Pacific export markets. Clean-label cosmetic demand from Sydney and Melbourne beauty houses accelerates natural antimicrobial substitution. Victorian organic cultivation trials are evaluating Mediterranean cultivar adaptation for domestic leaf supply security.
Olive Leaf Extract Market Competitive Environment
Global majors compete with regional champions across extraction technology and certification tiers, producing a market structure where Mediterranean estate-integrated suppliers, North American organic specialists, and pharmaceutical-grade processors each occupy distinct competitive positions. Three archetypes dominate: vertically integrated cultivator-extractors controlling leaf-to-ingredient quality chains, contract manufacturers serving bulk nutraceutical demand, and cosmetic ingredient specialists targeting clean-label preservative replacement. Capacity expansion in supercritical CO2 processing and strategic partnerships for organic certification coverage represent the dominant competitive moves reshaping supplier relationships.
Among estate-integrated Mediterranean suppliers, Evergreen Life Products Srl exemplifies the cultivator-controlled archetype through Sicilian harvesting operations. Comvita Ltd. and Gaia Herbs Inc. represent geographically diversified positions spanning New Zealand apiary-to-extraction infrastructure and North American certified organic partnerships respectively. These three companies anchor the competitive landscape across premium supply chain configurations.
| Leading Market Players |
|---|
| Comvita Ltd. |
| Dohler GmbH |
| Dr. Willmar Schwabe GmbH and Co. KG |
| Barleans Organic Oils LLC |
| Gaia Herbs Inc. |
| Olivus Inc. |
| Evergreen Life Products Srl |
| International Flavors and Fragrances Inc. |
| Medikonda Nutrients |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal circular economy subsidies gate qualified supply and premium-tier pricing access, rewarding Andalusian and Sicilian processors who valorize agricultural waste through cold-press infrastructure upgrades. This sustainability mandate concentrates procurement relationships with estate-controlled cultivators who capture oleuropein standardization premiums while non-compliant suppliers face margin compression from certification disqualification.
Pricing Analysis
Input-cost pass-through from leaf biomass volatility in Mediterranean growing regions shapes three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification premiums for USDA Organic and EU Organic chain-of-custody documentation, while economy processors absorb weather-driven raw material swings without pricing power. Cost compression in standard-grade powder formats is intensifying because California contract manufacturers are consolidating volume purchases around qualified suppliers. Mass-market nutraceutical buyers exhibit highest price sensitivity, whereas pharmaceutical-grade liquid purchasers prioritize bioavailability specifications over unit cost.
Supply Chain Analysis
Reverse-logistics flows for spent leaf biomass feed EU Green Deal subsidized composting and bioenergy recovery programs in Andalusia and Sicily, reducing waste disposal costs for estate-integrated processors. Geographic supply concentrates in Spain, Italy, and Greece, with emerging cultivation trials in California and Arizona. Raw material dependencies rest on Mediterranean cultivar leaf quality, aqueous extraction capacity, and supercritical CO2 equipment availability. Single-source vulnerability from Andalusian weather patterns threatens input security for non-estate processors. Distribution runs through vertically integrated cultivator-extractors, contract manufacturers, and cosmetic ingredient specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EFSA novel food approval acceleration drives formulation demand and gates competitive access across EU member states.
For Market Incumbents: Anchor competitive position through captive supply chain control over Sicilian and Andalusian estate harvesting, insulating against weather-driven input volatility that threatens non-integrated processors. Invest in supercritical CO2 and ultrasonic-assisted hybrid extraction capacity to meet USP-grade pharmaceutical specifications before regulatory reclassification of oleuropein-drug interactions tightens. Certification investment in dual USDA Organic and EU Organic coverage secures retail placement in premium channels where third-party verification is mandatory. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms targeting immune support regimens with full traceability storytelling, bypassing pharmacy channel consolidation. White-space targets include North American USDA-certified organic cultivation partnerships in California and Arizona for tariff-advantaged supply, and microencapsulated skin care delivery systems for Paris and Milan-based clean-label cosmetic houses. Functional food integration into ready-to-drink beverage lines offers the most penetrable application segment. For Investors and Strategic Acquirers: Roll-up economics work for estate-integrated Mediterranean cultivator-extractors because EFSA novel food approval scarcity creates durable competitive moats and co-manufacturing contract concentration. Long-term viability over the next decade hinges on therapeutic classification thresholds for oleuropein remaining within food-supplement frameworks rather than pharmaceutical reclassification. Acquisition target archetype: vertically integrated Sicilian or Andalusian processors with cold-press infrastructure and prior novel food dossier approvals. Monitor EMA and FDA pharmacovigilance guidance releases as inflection indicators for regulatory risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Investment | Prior approvals accelerate co-manufacturing contract capture from new EU entrants. |
| Supercritical CO2 Capacity Expansion | Hybrid ultrasonic systems meet USP monographs for German and Swiss pharmaceutical demand. |
| USDA Organic Cultivation Partnership | California and Arizona growing secures tariff-advantaged supply for premium supplement channels. |
| Microencapsulation R&D Program | Barcelona and Provence labs target dermal bioavailability for preservative-free cosmetic positioning. |
| Reverse Logistics Infrastructure | EU Green Deal subsidies fund agricultural waste valorization for circular economy compliance. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extraction facility operators, nutraceutical formulation scientists, cosmetic R&D directors, and EU regulatory affairs specialists with secondary validation. Primary sources included EFSA novel food catalog listings, FDA GRAS self-affirmation filings, USDA organic certification databases, and EU Health Claims Regulation assessments. Secondary data drew from trade flow records, customs documentation, and pharmaceutical-grade monograph specifications. Bottom-up volume modeling and top-down value triangulation cross-validated segment-level estimates.
Historical reference periods anchored the projection framework across the analysis window, with growth trajectories derived from segment-specific demand elasticity and supply capacity expansion schedules. Segmentation dimensions modeled include product format, end-use application, distribution channel, and regional regulatory cluster. Forecast inputs incorporated EFSA approval timeline acceleration, supercritical CO2 technology adoption curves, and organic certification penetration rates by geography.
Forecast precision tightens around the base case; tail outcomes carry wider variance under therapeutic reclassification scenarios or extreme Mediterranean weather events. Practitioners should monitor EMA pharmacovigilance bulletins and Andalusian agricultural yield reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Zea Mays Starch Market
Ingredients
Asia Pacific Feed Yeast Market
Ingredients
Ximenia Oil Market
Ingredients
Smoke Ingredients for Food Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
Birch Sap Market
Ingredients
United States Soy Protein Market
Ingredients
Terminalia Extract Market
Ingredients
South America Fruit and Vegetable Ingredients Market
Ingredients
Vegan Ingredients Market
Ingredients
Soybean Meal Market
Ingredients
Europe Fats and Oil Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Fermentation Ingredient Market
Ingredients
Fucoidan Extract Market
Ingredients
Africa Sodium Reduction Ingredients Market