
 Organic Pastry Flour Market | 2026-2036
Organic Pastry Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Pastry Flour Market Analytics
Buyer concentration among artisan bakeries is expanding as regional chains consolidate purchasing through dedicated organic distributors. King Arthur Baking Company leverages its direct-to-bakery channel to sustain premium positioning in specialty flour. Bob's Red Mill Natural Foods anchors the natural foods retail segment with heritage grain sourcing. Ardent Mills competes through integrated organic wheat procurement networks spanning multiple growing regions.
Organic pastry flour consists of soft wheat milled to a fine, low-protein specification typically below nine percent gluten content, engineered to produce tender, flaky baked goods through minimal gluten development. Whole wheat variants lead volume as health-conscious consumers accept denser crumb structures, while gluten-free formulations represent the fastest-growing sub-segment driven by celiac and clean-label demand. Margin pools concentrate in bulk packaging for commercial bakeries, where contract stability offsets lower per-unit premiums.
USDA organic certification and FDA food safety regulations govern domestic market access, while EU REACH and EFSA pesticide standards shape import eligibility for European supply chains. The EU Green Deal's carbon border adjustments will force non-European millers to document cultivation emissions or face tariff disadvantages. Stakeholders must monitor evolving mycotoxin thresholds and traceability mandates that threaten small-scale suppliers lacking laboratory testing infrastructure.
Market Dynamics
The EU Green Deal's carbon border adjustments are forcing millers to restructure sourcing documentation and emissions verification protocols, compressing supplier qualification timelines while elevating compliance costs across European-bound supply chains.
Growth Catalysts
- EU Farm to Fork pesticide thresholds:Tightening residue limits under the EU Green Deal are disqualifying conventional grain imports and redirecting bakery procurement toward certified organic channels.
- Artisan bakery consolidation:Regional chains are centralizing purchasing through dedicated organic distributors, amplifying volume commitments and stabilizing contract terms for qualified millers.
- Heritage grain revival:Soft wheat landraces with documented provenance are commanding premium positioning in laminated dough applications across French pâtisserie supply chains.
Market Restraints
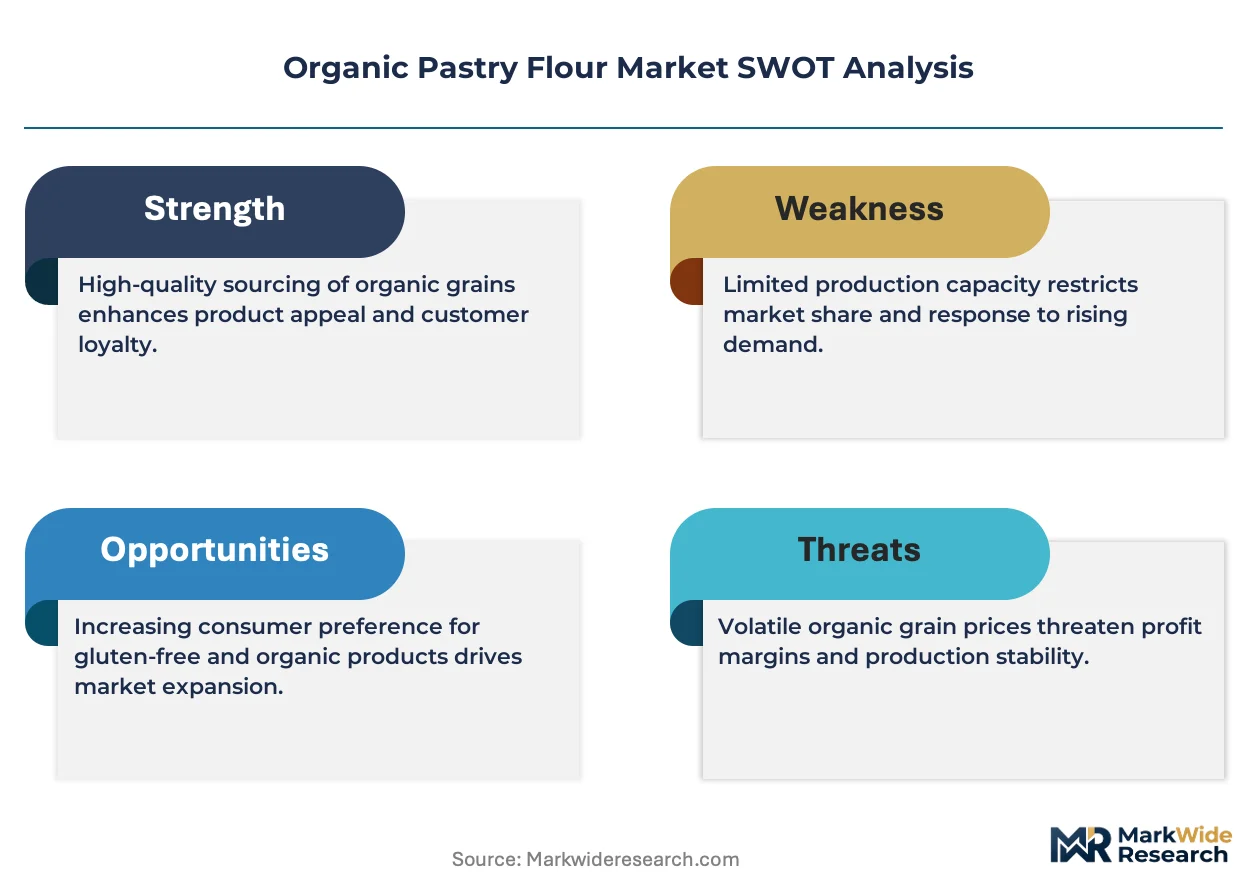
- Input cost volatility:Organic wheat premiums fluctuate with weather-driven yield variability across the US Northern Plains and Canadian Prairies.
- Supply concentration risk:Certified organic grain origination clusters in limited growing regions, exposing millers to localized drought or disease pressure.
- Technical limitation:Soft wheat protein levels below nine percent restrict flour functionality in high-hydration dough systems, constraining product line extensions.
Strategic Opportunities
- Underpenetrated geography:German artisan bakeries lag French counterparts in organic flour adoption, presenting first-mover positioning for certified suppliers.
- Regulatory tailwind:EU Green Deal carbon border documentation requirements favor millers with existing farm-level emissions tracking infrastructure.
- Technology convergence:Near-infrared spectroscopy and blockchain traceability are integrating to deliver real-time protein verification and lot provenance for commercial bakery customers.
Industry Challenges
- Certification timeline compression:USDA organic and EU organic equivalency audits now demand 18-24 month transition documentation, straining small-scale farm relationships.
- Talent scarcity in mycotoxin analysis:Laboratory testing infrastructure for aflatoxin and DON screening requires specialized technicians that rural milling regions struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Pastry Flour Market |
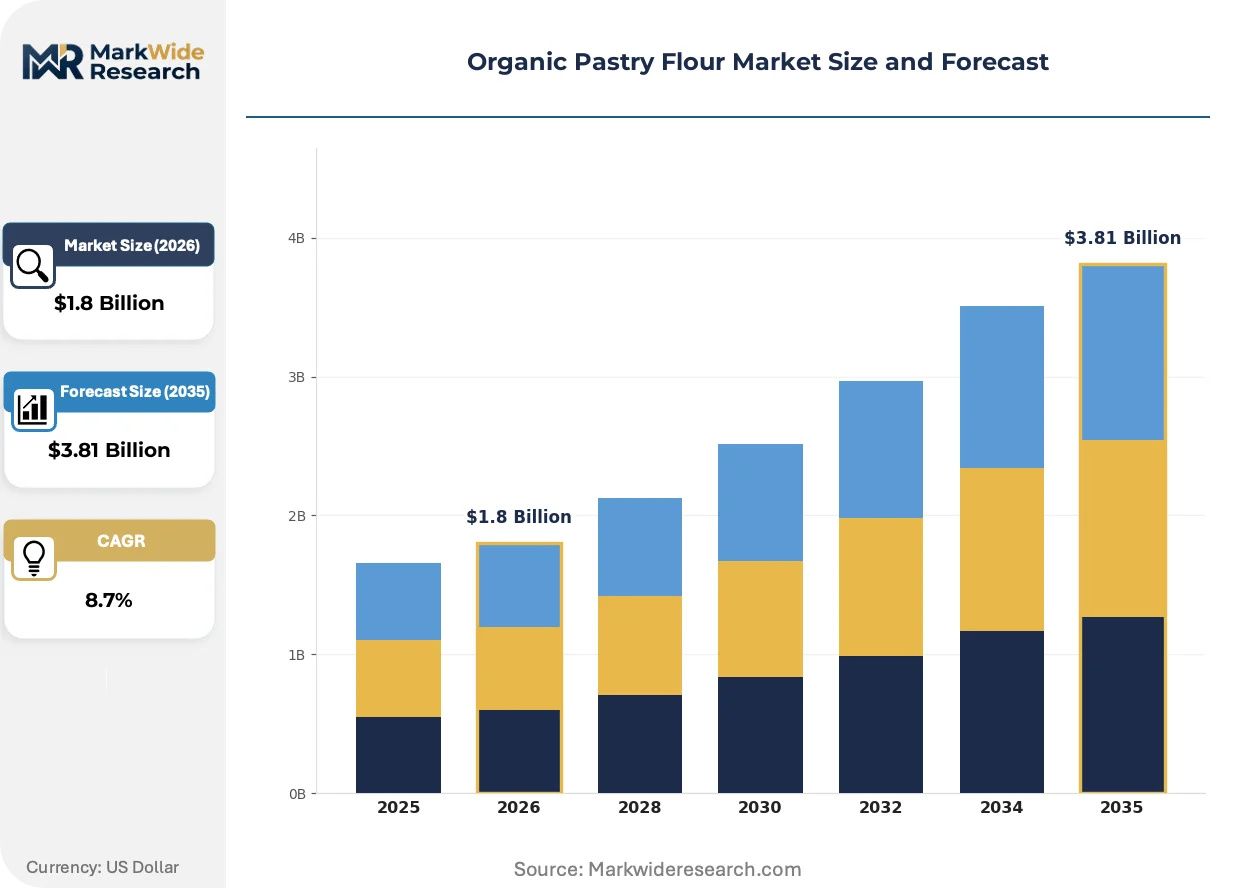
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Wheat, All-Purpose, Gluten-Free, Multi-Grain Packaging Type: Bags, Boxes, Bulk, Sachets End Use: Bakeries, Restaurants, Home Baking, Cafes Distribution Channel: Online, Supermarkets, Specialty Stores, Farmers' Markets |
| Companies Covered | Ardent Mills, Bob’s Red Mill Natural Foods, King Arthur Baking Company, General Mills, Heartland Mill Inc., Sunrise Flour Mill, Lindley Mills, Bay State Milling Company, Great River Organic Milling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Pastry Flour Market Evolving Landscape
Digital traceability infrastructure and precision milling technologies are converging to redefine quality assurance protocols, while regulatory documentation requirements reshape competitive differentiation beyond finished-product specifications.
Optical sorting technology is integrating computer vision and machine learning to remove damaged kernels and foreign material prior to milling, preserving endosperm integrity in soft wheat processing. Artisan and industrial bakeries alike are specifying flour milled through these systems to ensure consistent protein distribution and color uniformity. The technology is integrating quality control directly into the production line, compressing the gap between farm-gate variability and finished-product consistency.
EU REACH and EFSA pesticide residue standards are tightening maximum residue limits for imported grain, forcing non-European suppliers to adopt integrated pest management documentation or exit the market. Millers serving EU-bound channels must now maintain dual supply chains: one compliant with EU Green Deal Farm to Fork protocols, another serving less stringent markets. French and German bakery manufacturers are accelerating supplier audits to preempt enforcement actions scheduled under the 2024-2027 regulatory rollout.
Direct-to-bakery distribution models are displacing traditional wholesale intermediaries as regional chains seek margin capture and supply chain transparency. Specialty flour distributors with organic certification expertise are consolidating relationships with mid-sized artisan operations that lack in-house procurement specialization. This channel shift concentrates most visibly in France, where pâtisserie chains are negotiating multi-year contracts with millers offering farm-level traceability and carbon footprint documentation.
Organic Pastry Flour Market Segmentation
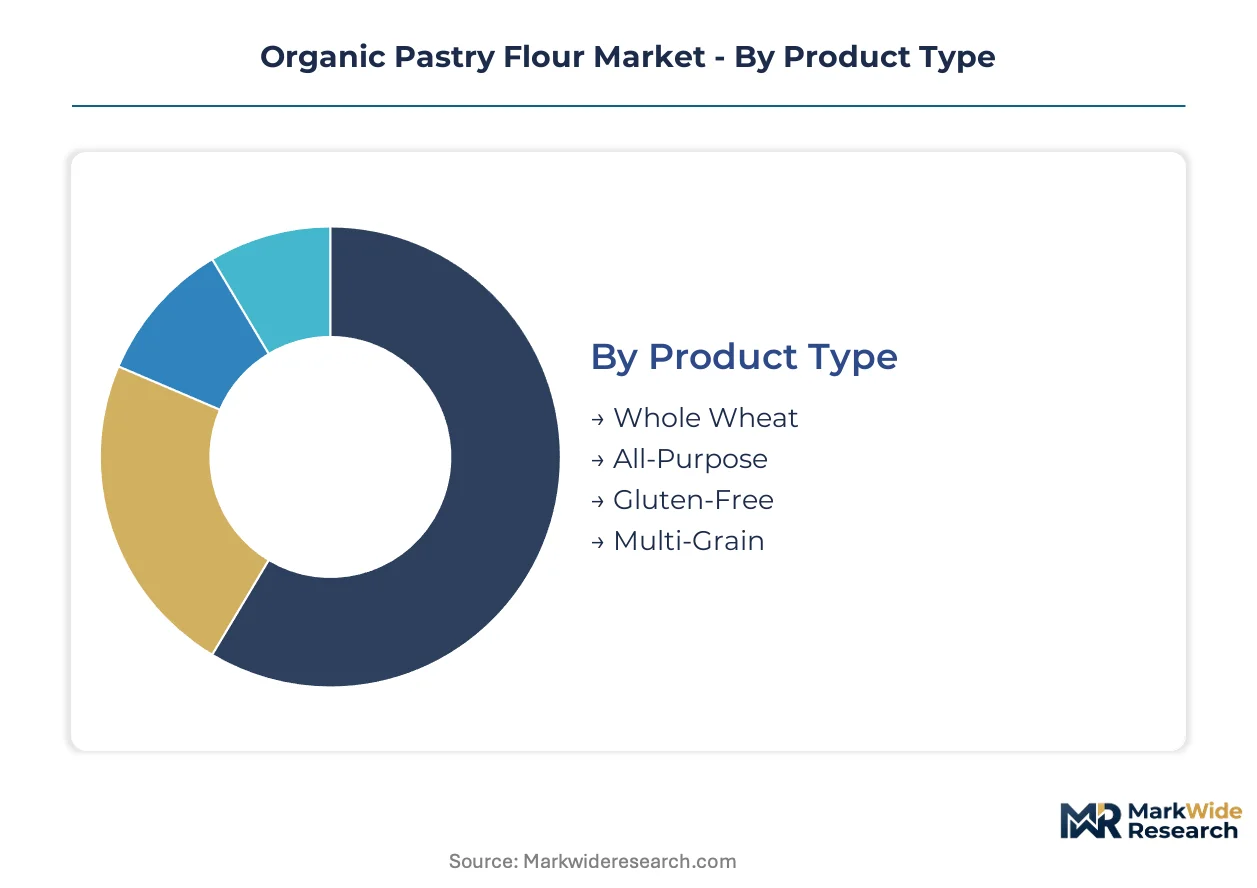
Organic pastry flour segmentation reflects divergent technical requirements across commercial and retail channels. Protein specifications, packaging formats, and distribution infrastructure vary sharply between artisan bakery procurement and home baking consumption.
Product Type:
Whole wheat variants function as standalone nutritional positioning plays, while gluten-free formulations demand embedded processing infrastructure and dedicated milling lines to prevent cross-contamination.
- Whole Wheat:Milled from complete soft wheat berries retaining bran and germ layers, delivering denser crumb structures with elevated fiber content. French pâtisserie chains specify this grade for health-positioned viennoiserie lines, though the protein matrix limits lamination performance in croissant production.
- Gluten-Free:Formulated from rice, tapioca, and sorghum starches with xanthan gum binding systems engineered to mimic soft wheat extensibility. Celiac-safe certification and clean-label positioning are expanding most quickly in German retail channels where diagnostic rates exceed neighboring markets.
- All-Purpose:Blended soft and hard wheat specifications offering versatility across cake, cookie, and quick bread applications.
- Multi-Grain:Composite flours integrating spelt, einkorn, or rye for heritage grain positioning in premium bakery segments.
Whole wheat leads volumes today; gluten-free is gaining share fastest.
Packaging Type:
Packaging economics stratify sharply between high-frequency commercial consumption and intermittent retail purchase patterns.
- Bulk:25-50 kg sacks and silo deliveries dominate artisan bakery procurement, with contract pricing tied to harvest-year wheat futures. Margin stability in this channel offsets per-kilogram premium compression, though transportation logistics concentrate supplier relationships within 300-kilometer milling radii.
- Bags:1-5 kg paper or woven polypropylene formats anchor natural foods retail placement. King Arthur Baking Company and Bob's Red Mill compete through shelf-stable packaging with resealable closures and printed provenance narratives targeting home bakers.
- Boxes:Rigid cardboard containment for gift-oriented or subscription flour deliveries.
- Sachets:Single-use 250-500 gram portions for trial sizing and recipe-specific purchasing.
Bulk commands the largest revenue pool; sachets are climbing the fastest.
End Use:
Application requirements span precision-controlled commercial environments and variable home kitchen conditions.
- Bakeries:Artisan and industrial operations specify certified organic flour with documented protein percentages, ash content, and falling number indices. French laminated dough specialists demand sub-9% protein soft wheat with consistent granulation for mechanical sheeting compatibility.
- Home Baking:Enthusiast consumers purchase through direct-to-consumer channels and specialty retail, prioritizing recipe reliability over technical specifications. King Arthur's recipe-linked flour SKUs dominate this segment with tested hydration ratios and baking temperature guidance.
- Restaurants:Dessert-forward establishments with in-house pastry programs.
- Cafes:Coffee-forward operations with limited baking infrastructure outsourcing to commissary suppliers.
Bakeries generate the dominant volume; home baking shows the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture and customer relationship depth for millers and branded flour suppliers.
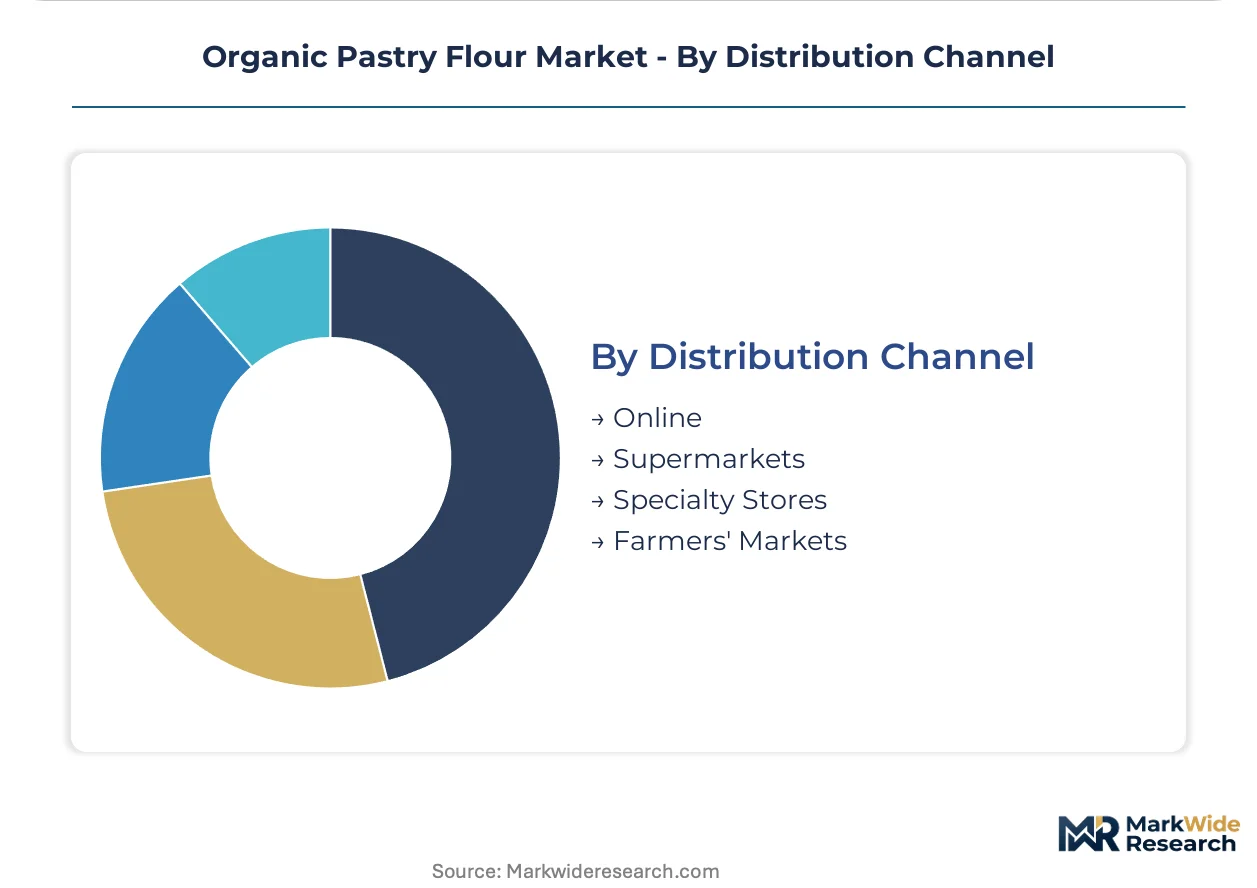
- Specialty Stores:Natural foods retailers and dedicated baking supply shops provide education-intensive environments where staff training converts organic certification awareness into purchase intent. Bob's Red Mill anchors this channel with heritage grain storytelling and bulk bin accessibility.
- Online:Direct-to-consumer and marketplace platforms enable subscription models and geographic reach beyond milling facility distribution radii. Carbon footprint documentation and farm-level traceability features command premium positioning in EU-bound e-commerce.
- Supermarkets:Conventional grocery placement requires slotting fee investment and mass-market packaging formats.
- Farmers' Markets:Local miller direct sales with minimal intermediation and maximum provenance transparency.
Specialty stores maintain the largest footprint; online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master millers and certified organic grain agronomists cluster in traditional wheat-growing regions where heritage cultivation expertise intersects with modern certification infrastructure. Their geographic concentration shapes supply availability and quality differentiation across consuming markets.
France
Traditional pâtisserie culture drives artisan bakery demand for certified organic soft wheat flour, particularly for laminated dough applications. The EU Green Deal's Farm to Fork strategy tightens pesticide residue thresholds for imported grain, redirecting procurement toward domestic organic channels. Paris and Lyon anchor concentrated purchasing networks where regional pâtisserie chains negotiate multi-year contracts with traceability documentation.
Germany
Diagnostic rates for celiac disease exceed neighboring markets, accelerating gluten-free organic pastry flour expansion through retail and foodservice channels. EFSA pesticide standards and REACH compliance requirements shape import eligibility for non-European suppliers. Bavarian artisan bakeries lag French counterparts in organic adoption, creating first-mover positioning opportunities for certified millers.
United States
USDA organic certification governs domestic market access while FDA food safety regulations enforce mycotoxin screening protocols. Organic wheat premiums fluctuate with weather-driven yield variability across the Northern Plains and Canadian Prairies. Minneapolis and Kansas City concentrate integrated organic wheat procurement networks spanning multiple growing regions.
Canada
Prairie provinces supply certified organic soft wheat to North American and European millers under equivalency agreements with EU organic standards. The Canadian Food Inspection Agency enforces pesticide residue limits aligned with Codex Alimentarius thresholds. Winnipeg and Saskatoon anchor grain origination infrastructure exposed to localized drought pressure.
Italy
Heritage grain revival programs promote soft wheat landraces with documented provenance for premium bakery positioning. EU organic regulations and national quality designations create layered compliance requirements for imported and domestic flour. Emilia-Romagna and Piedmont concentrate artisan milling operations supplying traditional pasticceria applications.
Organic Pastry Flour Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between integrated grain handlers with captive organic wheat supply and independent millers leveraging heritage sourcing narratives. Three archetypes dominate: diversified food conglomerates with flour divisions, independent specialty millers with direct-to-bakery channels, and heritage-focused operators emphasizing landrace grain provenance. Capacity expansion and certification infrastructure investments constitute the dominant competitive moves as suppliers position for EU Green Deal compliance timelines.
Within the heritage-focused tier, Bob's Red Mill Natural Foods and Great River Organic Milling exemplify independent operators emphasizing provenance transparency and organic certification depth. King Arthur Baking Company occupies a position bridging specialty retail and direct-to-bakery distribution with recipe-linked product development. Ardent Mills represents the integrated grain handler archetype with multi-region organic wheat procurement networks. These three companies anchor distinct competitive vectors: heritage storytelling, recipe-enabled consumer engagement, and supply chain scale.
| Leading Market Players |
|---|
| Ardent Mills |
| Bob's Red Mill Natural Foods |
| King Arthur Baking Company |
| General Mills |
| Heartland Mill Inc. |
| Sunrise Flour Mill |
| Lindley Mills |
| Bay State Milling Company |
| Great River Organic Milling |
| Others |
Value Network & Pricing Analysis
Backward integration into certified organic wheat origination anchors both supply security and premium pricing power for millers serving EU-bound channels, as the EU Green Deal's carbon border documentation requirements force non-integrated suppliers toward costly third-party verification or market exit.
Pricing Analysis
Bundled farm-level traceability and carbon footprint documentation command substantial premiums over unbundled commodity flour, with pricing stratifying across certified organic, transitional organic, and conventional tiers. Price differentiation hinges on EU organic equivalency certification and volume-scale contract terms, with artisan bakeries showing lowest price sensitivity due to end-consumer premium absorption while industrial processors face intense cost compression. Pricing pressure stems from organic wheat premium volatility across the US Northern Plains and Canadian Prairies.
Supply Chain Analysis
Regional distribution centers within 300-kilometer milling radii anchor hub-and-spoke delivery patterns to artisan bakeries, with Paris and Lyon serving as critical consolidation nodes for French pâtisserie procurement. Certified organic soft wheat concentrates in the US Northern Plains, Canadian Prairies, and select French growing regions, with supply chains drawing from heritage landrace programs and commercial organic breeding operations. Single-source vulnerability clusters around drought-exposed Prairie provinces, with distribution running through dedicated organic distributors displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic pastry flour market functions as a geographic-arbitrage play between North American origination costs and European regulatory premiums, as EU Green Deal compliance timelines compress supplier qualification windows and elevate documentation burdens for non-European millers.
For Market Incumbents: Hedge against EU carbon border adjustment exposure by accelerating farm-level emissions tracking infrastructure investments and securing multi-year contracts with French pâtisserie chains before 2024-2027 enforcement actions tighten import eligibility. Prioritize certification depth over capacity expansion, as USDA-EU organic equivalency audits now demand 18-24 month transition documentation that strains small-scale farm relationships and creates defensive moats for prepared suppliers. For New Entrants and Emerging Players: Blockchain-enabled traceability platforms offer a technology-first wedge into German artisan bakery channels, where organic flour adoption lags French counterparts and first-mover positioning remains achievable. Target Bavarian regional chains with direct-to-bakery distribution models emphasizing real-time protein verification and lot provenance, bypassing established wholesale intermediaries through carbon footprint documentation that satisfies impending EU Green Deal mandates. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale heritage millers because fragmented ownership structures and certification infrastructure gaps prevent standalone players from achieving EU market access at viable cost. Acquire operators with existing organic equivalency credentials and farm-level emissions tracking capabilities, watching for inflection when EU enforcement actions trigger supplier disqualification waves across non-compliant import channels.| Strategic Initiative | Industry Significance |
|---|---|
| Farm-Level Emissions Tracking Deployment | EU Green Deal carbon border documentation requirements favor early infrastructure investors with tariff-advantaged positioning. |
| Heritage Grain Landrace Revival Programs | Soft wheat varieties with documented provenance command premium positioning in French laminated dough applications. |
| Direct-to-Bakery Channel Expansion | Regional pâtisserie chains seek margin capture and supply transparency through dedicated organic distributor relationships. |
| Near-Infrared Spectroscopy Integration | Real-time protein verification compresses quality assurance gaps between farm-gate variability and finished-product consistency. |
| Gluten-Free Dedicated Line Investment | Celiac-safe certification and clean-label positioning accelerate fastest in German retail channels with elevated diagnostic rates. |
Research Methodology
Multiple input streams — primary interviews with master millers, certified organic grain agronomists, and artisan bakery procurement directors, alongside secondary validation through USDA organic certification databases, EU Farm to Fork strategy documentation, and customs trade data — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Historical shipment patterns were cross-referenced against panel input from organic wheat growers and specialty flour distributors to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, packaging format, end-use application, and distribution channel complexity, with CAGRs derived from harvest-year wheat futures correlation and certified acreage expansion trajectories.
The model holds under stable EU-US organic equivalency agreements and consistent Farm to Fork enforcement timelines; deviation in mycotoxin threshold revisions or carbon border adjustment scope would shift supplier qualification economics and regional competitiveness. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Protein Market
Ingredients
Lipids Market
Ingredients
Australia Soy Protein Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Macleaya Cordata Extract Market
Ingredients
Soy and Milk Protein Ingredients Market
Ingredients
Cheese Ingredients Market
Ingredients
China Soy Protein Market
Ingredients
Oak Extract Market
Ingredients
Chickpea Protein Market
Ingredients
Oat Grass Powder Market
Ingredients
APAC Savoury Ingredients Market
Ingredients
United States Protein Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Date Syrup Market