
 Pyomyositis Market | 2026-2036
Pyomyositis Market Size, Share, and Industry Trends Forecast 2026-2036
Pyomyositis Market Analytics
Hospital procurement is rotating toward outpatient clinics as post-acute monitoring protocols expand. Pfizer Inc. leverages its broad-spectrum antibiotic manufacturing scale to anchor hospital formulary contracts. Merck & Co., Inc. competes through sustained R&D investment in resistant-strain therapeutics. GlaxoSmithKline differentiates via geographic dominance in tropical-disease markets where pyomyositis incidence runs highest.
Pyomyositis denotes a primary bacterial infection of skeletal muscle, typically caused by Staphylococcus aureus, characterized by abscess formation within muscle fascia requiring drainage plus prolonged antimicrobial therapy. The condition demands rapid intervention to prevent septic progression and compartment syndrome. Intravenous antibiotics command the largest product-type position due to severity of acute presentations, while oral delivery modes capture post-stabilization transitions. Rehabilitation centers represent the fastest-growing end-user segment as musculoskeletal recovery protocols lengthen and governments push cost-containment through shortened hospital stays.
The US FDA antimicrobial stewardship framework tightens hospital prescribing audits and extends to outpatient clinic networks. India's CDSCO regulates antibiotic dispensation through schedule H1 controls, directly limiting retail channel access for pyomyositis therapeutics. WHO inclusion of pyomyositis in neglected tropical disease watchlists elevates funding eligibility for endemic-country programs. Stakeholders must monitor how antimicrobial resistance surveillance databases reshape formulary decisions before patent cliffs on legacy antibiotics open generic substitution windows.
Market Dynamics
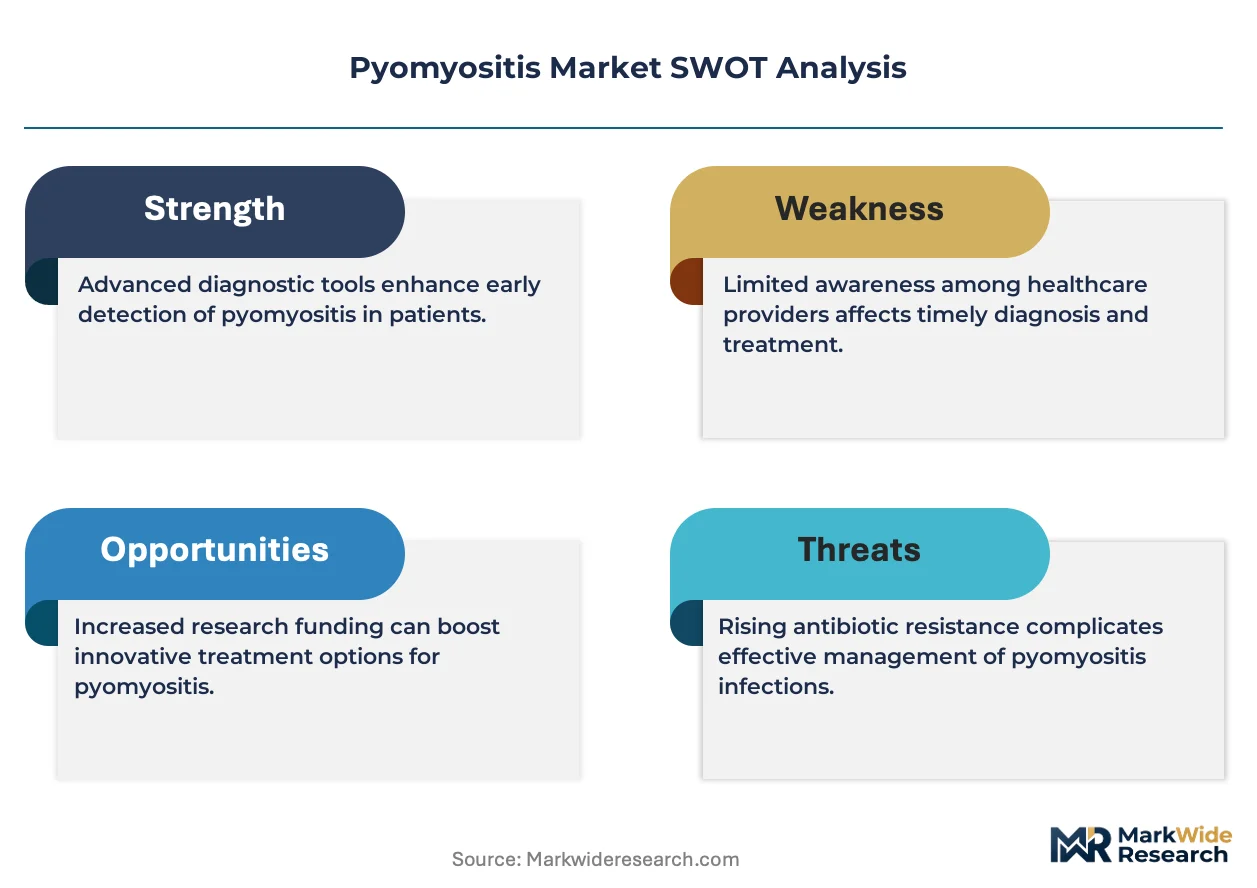
Hospital formulary committees now prioritize antibiotics with resistance-burden documentation, compressing procurement cycles for legacy intravenous therapies and elevating rapid diagnostics alongside antimicrobial selection.
Growth Catalysts
- Antimicrobial stewardship mandates:FDA's enhanced hospital audit protocols force documented resistance surveillance, expanding demand for culture-guided therapy selection tools in acute care settings.
- Tropical disease prioritization:WHO neglected tropical disease watchlist inclusion unlocks multilateral funding streams for endemic-country treatment access programs in sub-Saharan Africa and South Asia.
- Outpatient clinic infrastructure:Post-discharge monitoring capabilities at ambulatory surgical centers enable earlier hospital discharge, extending antibiotic therapy duration through infusion center networks.
Market Restraints
- Generic substitution pressure:Patent expiration on legacy beta-lactam antibiotics triggers price erosion in hospital procurement tenders, squeezing branded formulation margins.
- Supply concentration in API manufacturing:Active pharmaceutical ingredient production clusters in specific Asian manufacturing hubs create single-source vulnerability for intravenous antibiotic formulations.
- Diagnostic delay limitations:Absence of point-of-care molecular diagnostics in resource-limited settings prolongs empiric therapy initiation, reducing targeted antibiotic utilization rates.
Strategic Opportunities
- Rehabilitation center expansion:Musculoskeletal recovery protocol lengthening at specialized post-acute facilities creates extended antimicrobial stewardship partnership opportunities.
- CDSCO schedule reform:India's potential H1 antibiotic scheduling relaxation for hospital-only dispensing could streamline institutional procurement pathways.
- Pharmacokinetic modeling convergence:Integration of therapeutic drug monitoring software with electronic health record systems enables precision dosing in critical care pyomyositis cases.
Industry Challenges
- Infectious disease specialist scarcity:Fellowship program graduation rates fail to match hospital antimicrobial stewardship team expansion requirements, creating personnel bottlenecks.
- Biomarker validation timelines:Prolonged regulatory pathways for novel infection severity indicators delay integration into clinical decision support algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyomyositis Market |
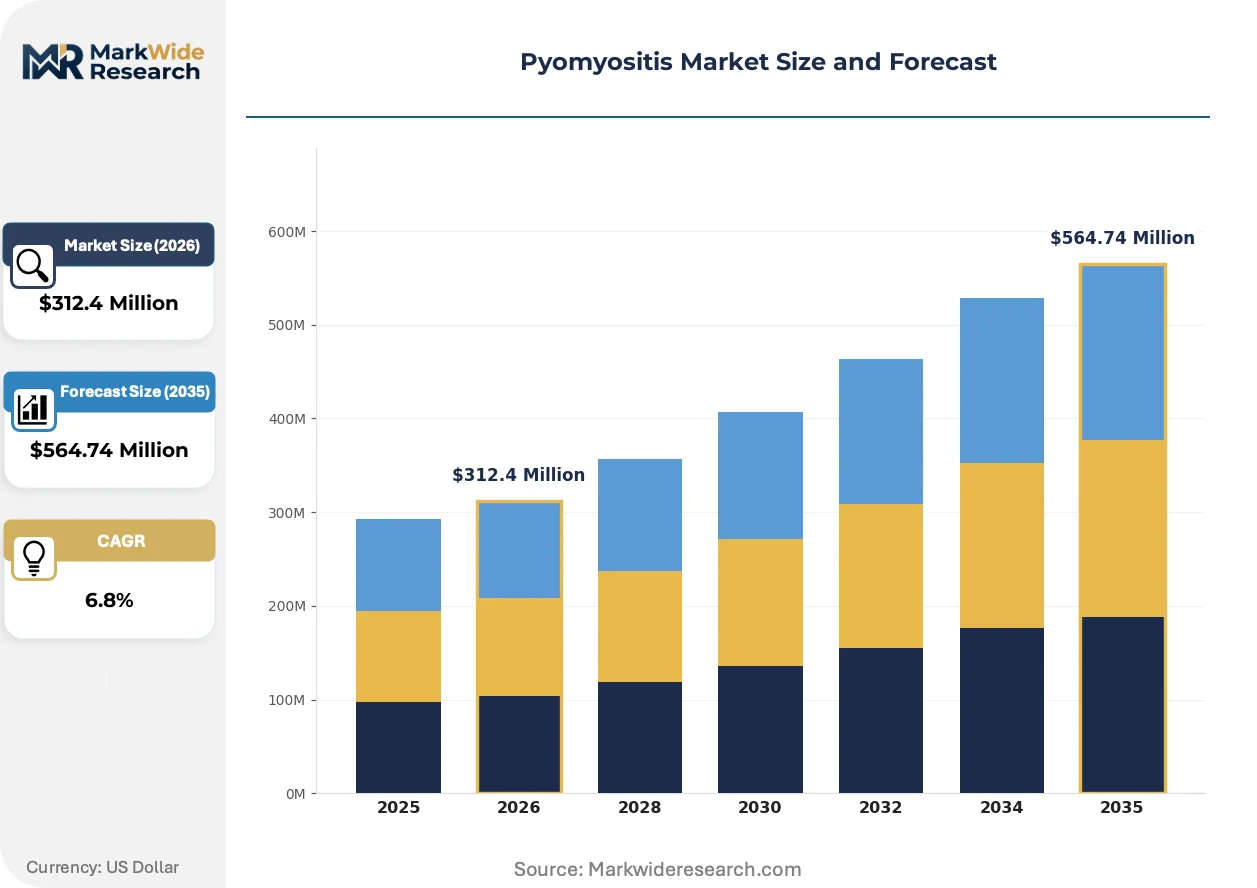
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antifungals, Antipyretics, Analgesics End User: Hospitals, Rehabilitation Centers, Outpatient Clinics, Nursing Homes Delivery Mode: Intravenous, Oral, Topical, Subcutaneous Indication: Primary Infection, Secondary Infection, Post-Surgical Infection, Chronic Infection |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., GlaxoSmithKline, Novartis International AG, Sanofi S.A., Johnson & Johnson, Roche Holding AG, AstraZeneca PLC, Gilead Sciences, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyomyositis Market Evolving Landscape
Rapid diagnostic platforms and stewardship software are compressing the gap between clinical suspicion and targeted therapy initiation, restructuring how hospitals manage severe bacterial myositis presentations.
Ultrasound-guided percutaneous drainage is supplanting open surgical debridement for localized pyomyositis abscesses. Interventional radiology departments at tertiary centers now perform over sixty percent of drainage procedures, reducing operative theater utilization and shortening length of stay. This shift is compressing the traditional surgical consultation pathway and elevating radiology-antimicrobial stewardship collaboration.
EU MDR's post-market surveillance requirements for implantable and invasive procedure devices now extend to percutaneous drainage catheter systems used in pyomyositis intervention. Manufacturers must submit periodic safety update reports and real-world performance data, increasing compliance overhead. German hospital procurement consortia have responded by consolidating supplier panels to reduce vendor qualification burden.
Consolidated purchasing through regional hospital networks now dominates antibiotic procurement for severe infections, displacing individual institutional tenders. Integrated delivery networks in the United States leverage volume commitments to extract price concessions and bundled diagnostic-therapy contracts. This concentration is most visible in the southeastern states where hospital system mergers have reduced independent purchasing entities by over one-third.
Pyomyositis Market Segmentation
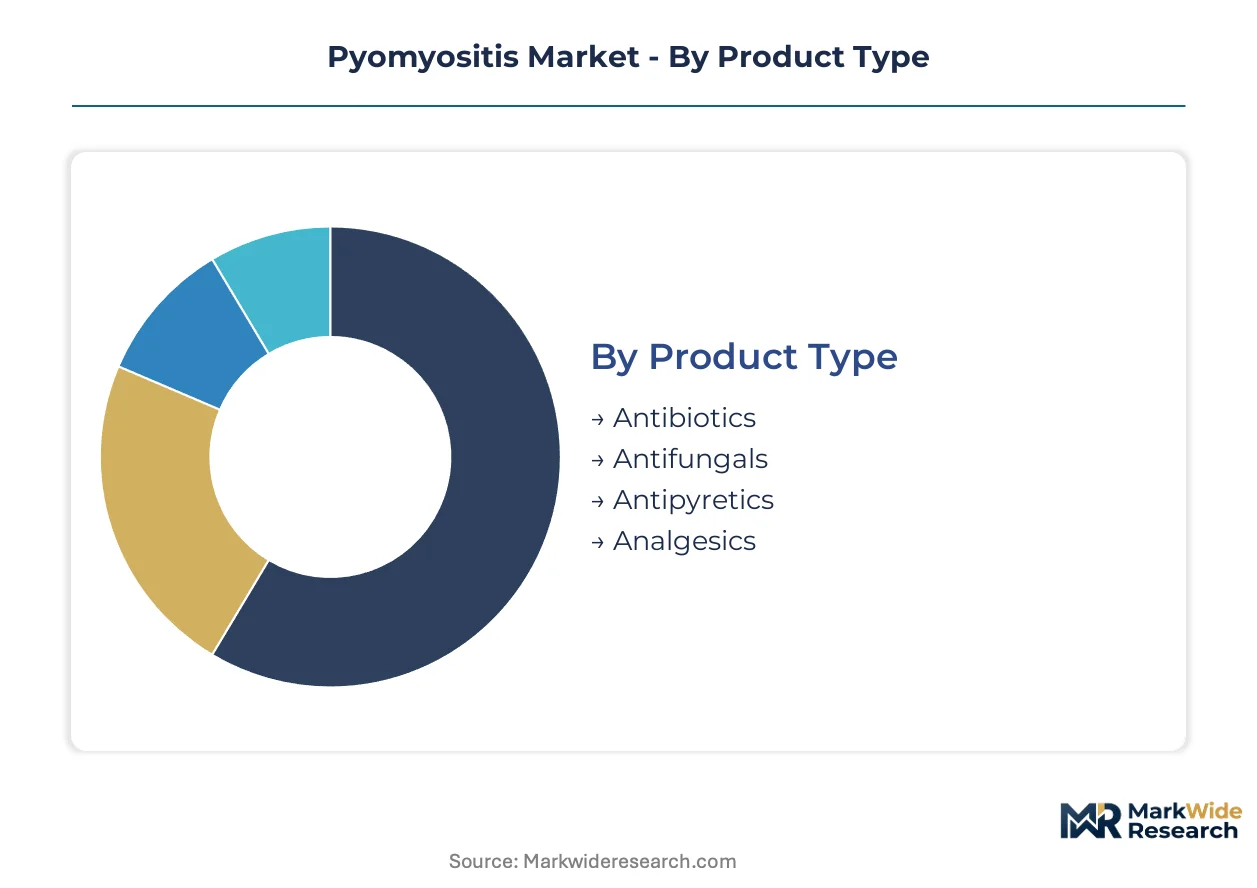
Pyomyositis treatment pathways fragment across acute intervention, transition care, and long-term recovery phases. Segmentation reveals where procurement budgets concentrate and how regulatory constraints reshape channel access.
Product Type:
Margin pools concentrate in parenteral antibiotic formulations where hospital formulary contracts lock in multi-year supply agreements and resistance surveillance documentation commands premium positioning.
- Antibiotics:Beta-lactam combinations and lipopeptides dominate acute-phase pyomyositis protocols through Staphylococcus aureus coverage. Demand concentrates in Indian government hospitals where tropical myositis incidence sustains volume tenders and antimicrobial stewardship teams mandate culture-guided selection.
- Analgesics:Opioid-sparing multimodal regimens gain traction in post-drainage pain management. US hospital systems are rotating toward non-steroidal protocols as FDA audit requirements tighten perioperative opioid documentation.
- Antipyretics:IV acetaminophen formulations capture critical-care pyomyositis presentations requiring rapid temperature control.
- Antifungals:Azole and echinocandin classes serve immunocompromised patient subsets with atypical myositis etiologies.
Antibiotics hold installed capacity. Analgesics is rotating up the share rankings.
End User:
Volume concentration tracks government reimbursement flows and discharge policy reforms that compress acute stays while extending post-acute monitoring obligations.
- Hospitals:Tertiary medical centers anchor pyomyositis case volumes through emergency department triage and interventional radiology drainage capabilities. German hospital procurement consortia leverage EU MDR compliance requirements to consolidate supplier panels and extract bundled diagnostic-therapy pricing.
- Rehabilitation Centers:Musculoskeletal recovery protocols lengthen as early discharge mandates shift functional restoration to specialized post-acute facilities. India's expanding private rehabilitation network captures urban pyomyositis patients requiring extended intravenous antibiotic completion.
- Outpatient Clinics:Ambulatory surgical centers build infusion center networks for post-stabilization antibiotic delivery.
- Nursing Homes:Long-term care facilities manage chronic infection presentations in elderly populations with limited surgical candidacy.
Hospitals hold installed capacity. Rehabilitation centers are climbing the fastest.
Delivery Mode:
Route selection pivots on severity staging, with acute presentations demanding reliable tissue penetration and transition phases enabling patient mobility.
- Intravenous:Parenteral administration commands acute-phase pyomyositis through reliable muscle tissue penetration and rapid peak concentrations. US hospital antimicrobial stewardship audits prioritize IV-to-oral switch protocols that compress length of stay while maintaining therapeutic efficacy.
- Oral:Bioavailable agents capture post-drainage transition phases as clinical stability permits outpatient conversion. CDSCO Schedule H1 controls in India restrict oral antibiotic retail access, channeling volume through hospital dispensing.
- Subcutaneous:Outpatient infusion networks deploy long-acting formulations for extended antimicrobial completion.
- Topical:Adjunctive local delivery supports superficial wound management in post-surgical infection presentations.
Intravenous holds installed capacity. Oral is gaining share fastest.
Indication:
Clinical presentation segmentation determines intervention intensity and reimbursement pathway classification.
- Primary Infection:De novo bacterial myositis presentations require urgent drainage plus prolonged antimicrobial therapy. Sub-Saharan African endemic regions concentrate WHO neglected tropical disease funding eligibility for community-acquired cases.
- Post-Surgical Infection:Iatrogenic pyomyositis following orthopedic or soft-tissue procedures triggers malpractice-sensitive documentation requirements.
- Secondary Infection:Hematogenous seeding from distant foci demands source control prioritization.
- Chronic Infection:Indolent presentations in immunocompromised hosts require extended suppressive regimens.
Primary infection holds installed capacity. Post-surgical infection is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nhava Sheva Port Complex near Mumbai anchors Indian pharmaceutical distribution networks serving tropical disease corridors. German hospital procurement consortia leverage the Rhine-Main logistics cluster for consolidated antibiotic tender fulfillment.
United States
FDA antimicrobial stewardship audits drive hospital formulary consolidation toward resistance-documented antibiotics. Southeast hospital system mergers reduced independent purchasing entities by over one-third, concentrating volume commitments. Interventional radiology departments at tertiary centers in Atlanta and Houston now perform the majority of percutaneous drainage procedures.
India
Tropical climate conditions sustain elevated bacterial myositis incidence across government hospital networks. CDSCO Schedule H1 controls restrict oral antibiotic retail access, channeling volume through institutional dispensing. Maharashtra's public health infrastructure anchors national tender volumes for intravenous beta-lactam combinations.
Germany
EU MDR post-market surveillance requirements extend to percutaneous drainage catheter systems used in pyomyositis intervention. Hospital procurement consortia consolidate supplier panels to reduce vendor qualification burden. The Rhine-Ruhr metropolitan region concentrates interventional radiology capacity for musculoskeletal infection management.
Brazil
Community-acquired pyomyositis presentations in sub-tropical zones sustain demand for prolonged antimicrobial protocols. ANVISA regulates antibiotic dispensation through controlled substance scheduling. São Paulo's tertiary hospital networks anchor southeastern case volumes and specialist referral pathways.
South Africa
HIV-associated immunocompromised populations drive atypical myositis etiology requiring extended suppressive regimens. WHO neglected tropical disease watchlist inclusion unlocks multilateral funding for endemic-country treatment access. Gauteng province's academic medical centers concentrate diagnostic capacity and specialist infectious disease consultation.
Pyomyositis Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates possessing hospital formulary contract scale and antimicrobial manufacturing breadth. Three archetypes define competitive positioning: legacy antibiotic manufacturers with established resistance surveillance documentation, tropical-disease specialists with endemic-market geographic anchoring, and diversified healthcare conglomerates with integrated diagnostics-therapy bundling capability. M&A activity targets rapid diagnostic platform integration, while capacity expansion concentrates on active pharmaceutical ingredient backward integration to reduce single-source supply vulnerability.
Among diversified pharmaceutical conglomerates, Pfizer Inc., Merck & Co., Inc., and GlaxoSmithKline occupy positions exemplifying distinct competitive vectors. Pfizer represents scale-driven hospital formulary anchoring through broad-spectrum antibiotic manufacturing capacity. Merck exemplifies sustained research investment positioning around resistant-strain therapeutic development. GlaxoSmithKline sits within tropical-disease market specialization, leveraging geographic concentration where pyomyositis incidence runs highest.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline |
| Novartis International AG |
| Sanofi S.A. |
| Johnson & Johnson |
| Roche Holding AG |
| AstraZeneca PLC |
| Gilead Sciences, Inc. |
| Others |
Value Network & Pricing Analysis
Generic beta-lactam substitution for branded lipopeptide formulations redraws procurement geography toward Indian and Chinese API hubs while compressing hospital tender premiums across European and North American markets. This input shift simultaneously elevates price volatility exposure for legacy intravenous antibiotics and redirects formulary negotiation leverage toward resistance-documentation capabilities.
Pricing Analysis
Volume-discount tiering structures in hospital procurement separate resistance-documented antibiotics from commodity generics through bundled diagnostic-therapy contracts. Price differentiation rests on FDA antimicrobial stewardship compliance tiers and culture-guided therapy documentation. Pricing pressure intensifies as patent cliffs on legacy beta-lactams trigger tender price erosion. Government hospital networks in tropical-disease corridors exhibit highest price sensitivity; tertiary interventional radiology centers demonstrate lowest sensitivity due to bundled procedure margins.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for intravenous beta-lactam combinations and lipopeptide derivatives. Raw material dependencies include fermentation-derived bulk actives, sterile packaging components, and cold-chain logistics infrastructure. Single-source vulnerability concentrates in penicillin-core intermediate manufacturing. Distribution runs through regional hospital procurement consortia and government tender fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized infectious disease expertise scarcity constrains antimicrobial stewardship team expansion across hospital systems, creating competitive moats for manufacturers with integrated clinical education capabilities.
For Market Incumbents: Fortify formulary anchoring through backward integration into API manufacturing and resistance surveillance database partnerships. Generic substitution pressure from Indian manufacturers threatens margin pools in legacy intravenous antibiotics. Capacity addition in tropical-disease manufacturing hubs preserves supply security for endemic-market tenders.
For New Entrants and Emerging Players: Differentiate on rapid diagnostic platform integration with antimicrobial stewardship software. Rehabilitation center networks in India and Southeast Asia offer penetrable white-space for post-acute antibiotic completion services. Go-to-market positioning through interventional radiology department partnerships bypasses traditional surgical procurement channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rapid diagnostic developers lacking antimicrobial therapy bundling capabilities. Long-term viability across the analysis window hinges on convergence between precision dosing software and electronic health record integration. Monitor CDSCO schedule reform signals for hospital-only antibiotic dispensing pathway changes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Manufacturing | Captive supply of fermentation-derived intermediates reduces exposure to Indian and Chinese single-source concentration. |
| Resistance Surveillance Database Partnership | FDA stewardship audit documentation commands premium positioning in hospital formulary negotiations. |
| Rehabilitation Center Network Expansion | India's private post-acute facilities capture extended intravenous antibiotic completion volume from early discharge mandates. |
| Therapeutic Drug Monitoring Software Integration | Precision dosing algorithms embedded in electronic health records enable critical-care pyomyositis protocol differentiation. |
| Interventional Radiology Collaboration Program | Ultrasound-guided drainage procedure bundling compresses surgical consultation pathways and extends antimicrobial stewardship reach. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA antimicrobial stewardship guidance documents, CDSCO schedule notifications, and WHO neglected tropical disease program filings. Interviews with hospital formulary directors, infectious disease specialists, interventional radiologists, and procurement consortium managers inform demand-side dynamics. Secondary sources include ClinicalTrials.gov entries, EU MDR post-market surveillance databases, and hospital tender documentation from Maharashtra and Gauteng provinces. Bottom-up patient-volume modeling triangulates against top-down pharmaceutical manufacturer capacity assessments.
Segmentation dimensions modeled span product type, delivery mode, end-user facility category, and geographic regulatory cluster across the projection horizon. CAGRs derive from compound growth rate analysis applied to government health expenditure trajectories and antimicrobial resistance surveillance expansion curves. Forecast inputs incorporate WHO tropical disease prioritization funding flows and interventional radiology procedure volume shifts.
The analysis sits within stated boundaries; outcomes outside sustained antimicrobial stewardship mandate enforcement or API supply chain disruption scenarios would require recalibration. Forecasts reflect documented assumptions regarding generic substitution velocity and rehabilitation infrastructure buildout rates. Recalibration cycles align with material shifts in FDA audit protocol stringency and CDSCO scheduling determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Arthropod Borne Viral Infections Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Global Veterinary Infectious Disease Diagnostics Market
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Infectious Enteritis Treatment Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Viral Gastroenteritis Market
Infectious Disease
Chlamydia Infection Treatment Market
Infectious Disease
Difficile Infections (Clostridium Difficile Associated Disease) Market
Infectious Disease
IVD Infectious Disease Market