
 Asia Pacific Power Tools Market | 2026-2036
Asia Pacific Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Power Tools Market Insights
Brushless motor tier is rotating through the Asia Pacific power tools landscape as manufacturers chase efficiency benchmarks and thermal durability. Robert Bosch GmbH leverages its German-engineered platform architecture across Indian and Chinese assembly plants. Makita Corporation anchors its position through deep channel control in Japanese home improvement retail. Techtronic Industries Co. Ltd. competes aggressively on cordless lithium-ion density in Southeast Asian construction markets.
Asia Pacific power tools encompass electrically, pneumatically, or manually actuated handheld and stationary devices engineered to torque, cut, drill, grind, or fasten materials with rotational speeds typically spanning 500 to 30,000 RPM. These instruments serve industrial fabrication, residential construction, and vehicle assembly by converting electrical or compressed air energy into mechanical force at controlled precision thresholds. Cordless tools command the fastest expansion trajectory as lithium-ion cell energy density improves and job site mobility becomes non-negotiable across Japanese and Australian commercial building sites. Construction end users represent the dominant value pool, though home improvement channels in South Korea and Taiwan are deepening penetration through online retail platforms that bypass traditional wholesale markups.
China's SAMR enforces GB standards for battery cell thermal runaway containment, while India's BIS mandates compulsory registration for imported power tool motors under its quality control order framework. Japan's METI directs industrial equipment efficiency benchmarks that push manufacturers toward brushless motor architectures. Stakeholders must monitor how divergent certification timelines across these three regulatory jurisdictions reshape inventory planning and localized sourcing decisions.
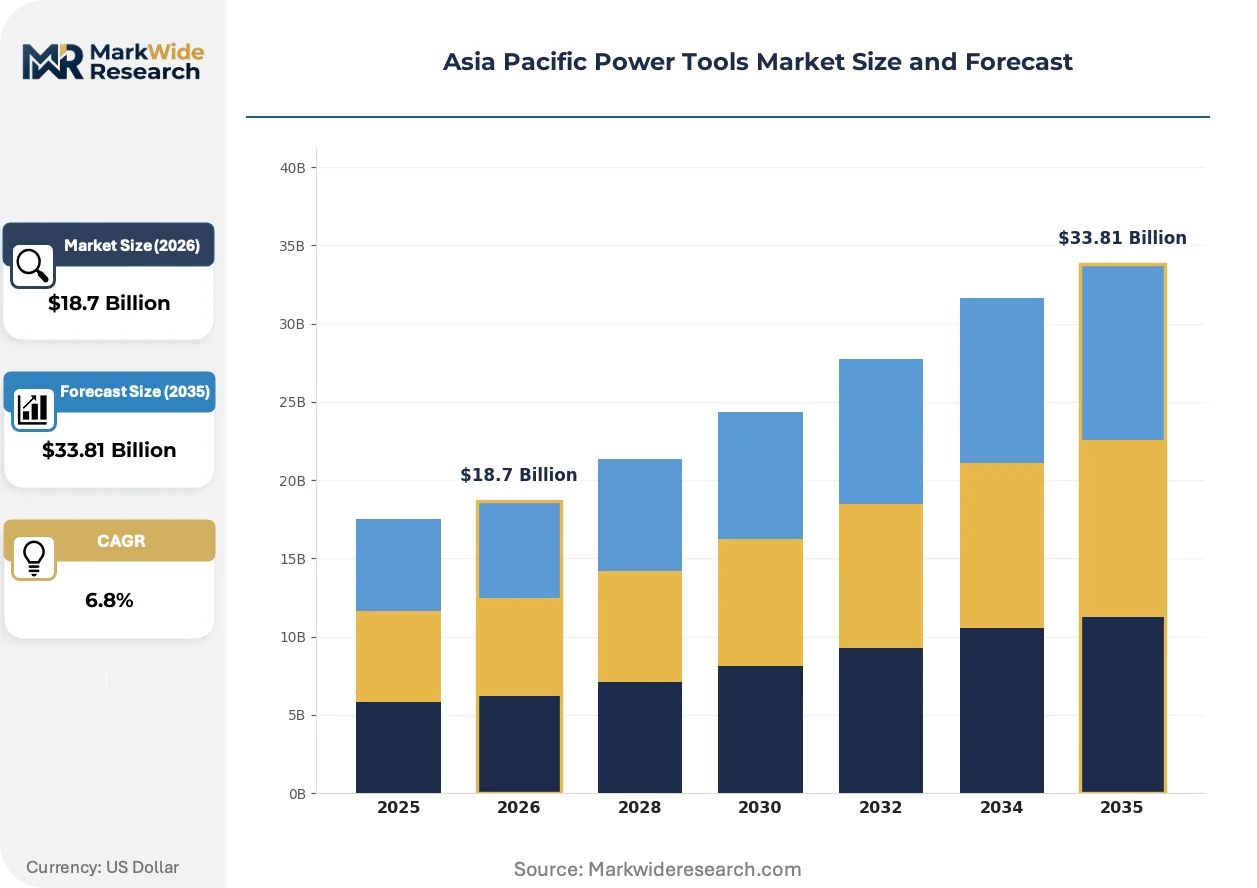
Market Dynamics
Brushless motor migration across Asia Pacific power tools is compressing incumbent supply chains while China's GB 31241-2022 battery safety mandates force parallel certification tracks that fragment inventory planning.
Growth Catalysts
- India's BIS Quality Control Order:Compulsory motor registration for imported power tools is accelerating domestic assembly investments across Maharashtra and Gujarat industrial corridors.
- Cordless lithium-ion density improvements:Construction contractors in Vietnam and Australia are retiring pneumatic systems for battery platforms that eliminate compressor logistics.
- Residential construction velocity:Vietnam's housing permit approvals are channeling demand toward compact cordless drill drivers and impact wrenches for finishing work.
Market Restraints
- Lithium carbonate price volatility:Cell chemistry cost swings compress margin predictability for mid-tier cordless tool assemblers sourcing from Chinese refiners.
- Import concentration risk:India's western ports handle over seventy percent of power tool motor arrivals, creating single-point vulnerability during monsoon logistics disruptions.
- Pneumatic legacy infrastructure:Established Japanese fabrication shops resist full cordless conversion due to sunk compressor investments and air-line retrofit costs.
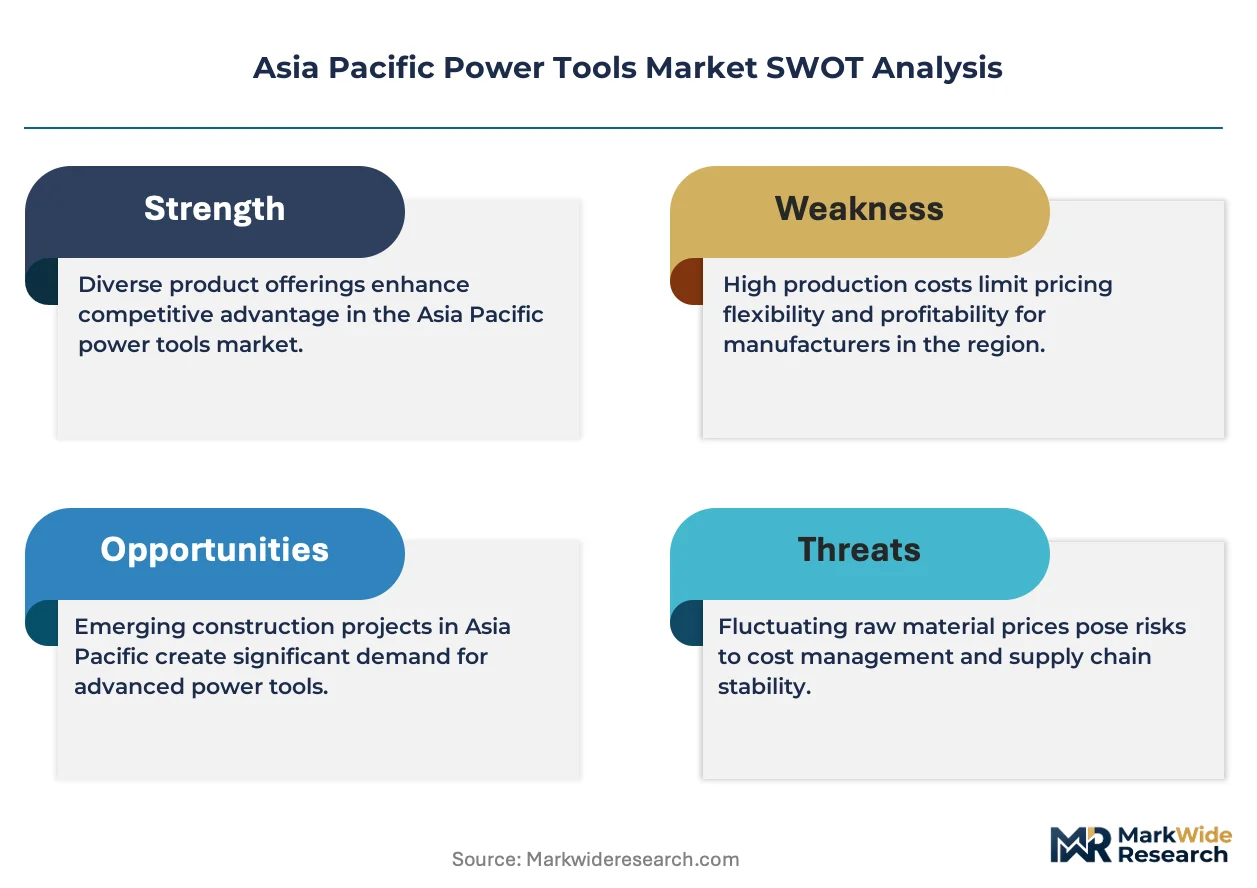
Strategic Opportunities
- Indonesia's underpenetrated home improvement channel:Online retail platforms in Jakarta and Surabaya bypass traditional wholesale markups, opening direct-to-contractor cordless tool distribution.
- Brushless-pneumatic hybrid architectures:Converging motor technologies enable tool platforms that switch between battery and compressed air power sources for mixed job sites.
- Japan's METI efficiency benchmarks:Industrial equipment mandates create regulatory tailwinds for premium brushless motor penetration in automotive assembly plants.
Industry Challenges
- Multi-jurisdiction certification timelines:China's SAMR, India's BIS, and Japan's METI operate non-harmonized testing protocols that extend product launch schedules by eight to fourteen months.
- Field technician skill gaps:Brushless motor diagnostics and battery management system troubleshooting require training investments that distributor service networks struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Power Tools Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cordless Tools, Electric Tools, Pneumatic Tools, Manual Tools End User: Construction, Automotive, Manufacturing, Home Improvement Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores Application: Drilling, Cutting, Grinding, Demolition |
| Companies Covered | Stanley Black & Decker, Inc., Robert Bosch GmbH, Techtronic Industries Co. Ltd., Makita Corporation, Hilti Corporation, Atlas Copco AB, Koki Holdings Co., Ltd., Snap-On, Inc., Apex Tool Group, LLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Power Tools Market Trends and Innovations
Power tool technology trajectories across Asia Pacific are splitting between premium efficiency platforms and cost-optimized alternatives, with regulatory pressure and channel evolution accelerating the divergence.
Brushless DC motor architecture is bifurcating the Asia Pacific power tools landscape. These electronically commutated systems eliminate mechanical brush wear while delivering twenty to thirty percent higher torque density than brushed equivalents. Japanese automotive assembly plants and Australian commercial construction firms are adopting premium brushless platforms for continuous-duty applications. The technology is bifurcating supplier tiers into German-engineered premium licensors and Asian cost-optimized imitators with diverging thermal management capabilities.
China's SAMR enforcement of GB 31241-2022 for lithium-ion battery thermal runaway containment is reshaping product development timelines. The standard mandates nail penetration and overcharge testing protocols that exceed previous industry norms. Cordless tool manufacturers targeting Chinese job sites must redesign battery pack enclosures and management circuits. Japanese and Korean brands with established Chinese assembly operations are absorbing compliance costs faster than importers relying on third-party cell suppliers.
Online retail disintermediation is compressing traditional wholesale margins across South Korean and Taiwanese home improvement channels. Contractors and serious DIY users now compare specifications and pricing across direct-to-consumer platforms before purchasing. Established distributors in Seoul and Taipei are responding with value-added services including same-day battery exchange and on-site warranty handling. The shift is most visible in compact cordless categories where specification transparency reduces brand premium capture.
Asia Pacific Power Tools Market Segmentation
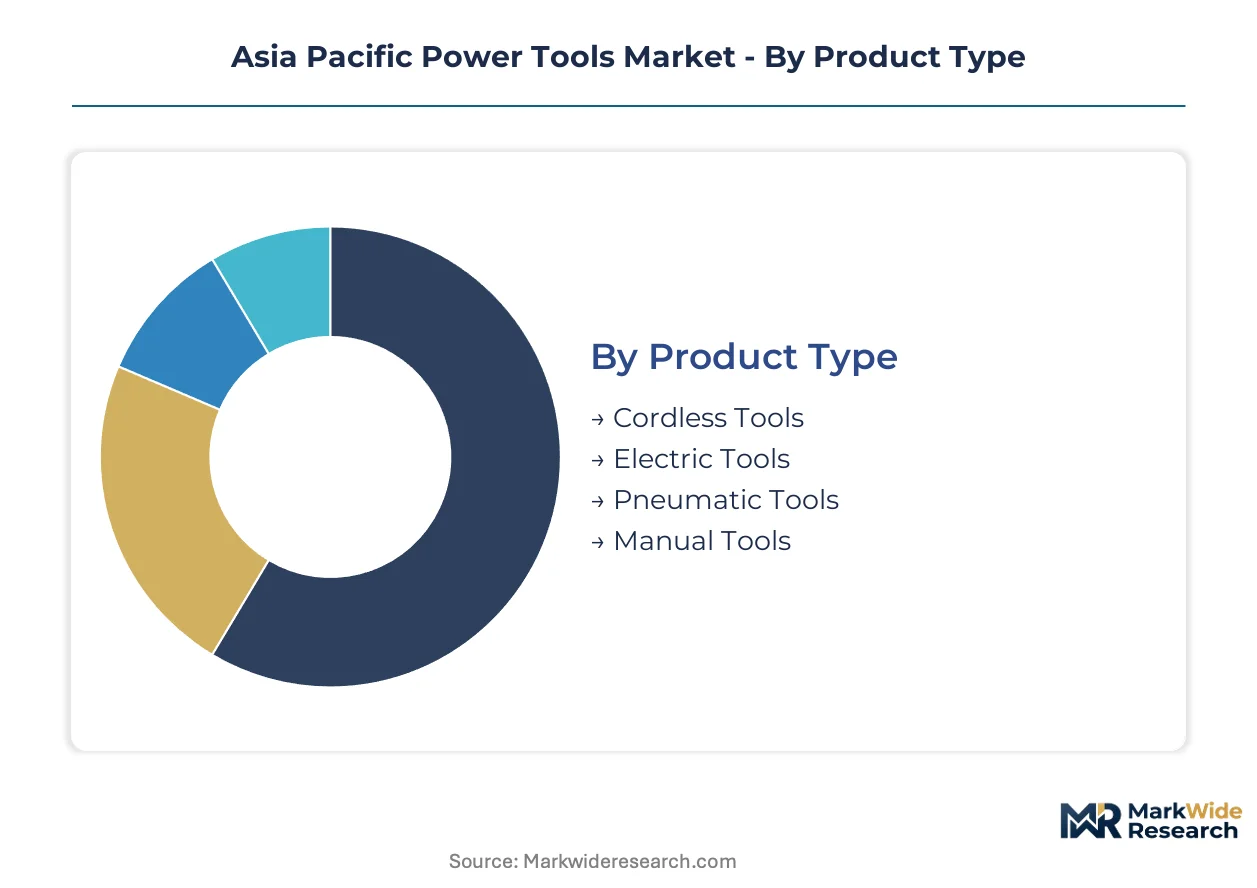
Power tool segmentation across Asia Pacific reflects divergent regulatory pressures, channel evolution, and job site mobility requirements. Manufacturers must align product architectures with certification timelines in China, India, and Japan while responding to cordless conversion patterns in Vietnamese construction and Australian commercial building.
Product Type:
China's SAMR enforces GB 31241-2022 battery safety standards that fragment certification timelines across cordless and electric platforms, while India's BIS quality control orders create parallel registration requirements for motor assemblies.
- Cordless Tools:Lithium-ion battery platforms deliver rotational force through brushless DC motors with energy densities now exceeding previous generation chemistries. Demand concentrates in Vietnam's residential construction sector where housing permit velocity channels procurement toward compact drill drivers and impact wrenches that eliminate compressor logistics. Chinese refiners supply cell chemistry that determines margin predictability for mid-tier assemblers.
- Electric Tools:Corded alternating current systems sustain continuous-duty torque output for stationary fabrication and heavy material removal. Japanese automotive assembly plants and Australian commercial construction firms specify these platforms where job site power infrastructure supports tethered operation. METI efficiency benchmarks push manufacturers toward premium motor architectures.
- Pneumatic Tools:Compressed air systems retain installed base in established Japanese fabrication shops with sunk compressor investments.
- Manual Tools:Human-actuated devices serve finishing precision and backup applications where power source reliability is constrained.
Cordless tools handle the majority of throughput; cordless platforms are the fastest mover on share.
End User:
Customer procurement patterns split between volume-contracting industrial buyers and fragmented home improvement channels where online retail disintermediation compresses traditional wholesale margins.
- Construction:General and specialty contractors specify platforms for structural assembly, finishing work, and site preparation across commercial and residential building. Vietnamese permit approvals and Australian infrastructure investment concentrate demand in this segment. Contractors in both markets are retiring pneumatic systems for battery platforms.
- Automotive:Vehicle assembly plants and aftermarket repair facilities require precision torque control and continuous-duty thermal management. Japanese OEMs specify brushless architectures under METI efficiency mandates. The segment demands diagnostic compatibility with assembly line automation.
- Manufacturing:Industrial fabrication shops across Maharashtra and Gujarat industrial corridors source tools for metalworking and assembly operations. India's BIS compulsory registration accelerates domestic assembly investments.
- Home Improvement:Serious DIY users and residential maintenance contractors in South Korea and Taiwan compare specifications across direct-to-consumer platforms.
Construction commands the dominant value pool; home improvement channels are expanding most quickly as online retail penetration deepens.
Distribution Channel:
Channel structure determines margin capture and service capability, with digital platforms bypassing traditional wholesale markups while established distributors respond with value-added logistics.
- Online Retail:Direct-to-consumer platforms in Seoul, Taipei, Jakarta, and Surabaya enable specification transparency and price comparison that reduces brand premium capture. Contractors research cordless tool specifications before purchasing. The channel compresses delivery timelines through regional fulfillment centers.
- Wholesale:Traditional distributors with inventory depth and credit relationships serve established contractor networks across Japanese and Australian markets. Seoul and Taipei distributors are adding same-day battery exchange and on-site warranty handling to defend position.
- Direct Sales:Manufacturer field teams engage large fleet operators and national construction groups with volume contracting and custom configuration.
- Specialty Stores:Focused retailers provide technical consultation and immediate product availability for professional users requiring hands-on evaluation.
Wholesale retains the largest transaction volume; online retail is climbing the fastest on channel share.
Application:
Functional use cases align with material type and precision requirements, with cordless density improvements expanding battery platform suitability across previously pneumatic-dominated tasks.
- Drilling:Rotational cutting operations for fastener installation and material penetration span wood, metal, and masonry substrates. Compact cordless drill drivers dominate Vietnamese residential finishing work. Brushless motor architectures deliver thermal durability for continuous-duty specifications.
- Cutting:Material separation through sawing, shearing, and abrasive action requires blade speed stability and debris management. Applications span construction framing and automotive aftermarket repair.
- Grinding:Surface preparation and material removal through abrasive contact demands thermal management and vibration control.
- Demolition:Structural disassembly and material breaking requires high-impact force delivery that has historically favored pneumatic or heavy electric platforms.
Drilling captures the highest transaction frequency; cutting applications are gaining share fastest as cordless platform torque density improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia Pacific power tools trade flows through a mix of export-oriented manufacturing hubs and import-dependent construction markets. China's battery cell refineries supply regional assemblers while Vietnam and Australia absorb finished cordless platforms. Regulatory divergence across SAMR, BIS, and METI jurisdictions fragments certification timelines.
China
SAMR's GB 31241-2022 battery safety mandates force redesigns of pack enclosures and management circuits for tools targeting domestic job sites. Yangtze River Delta assembly plants absorb compliance costs faster than importers relying on third-party cell suppliers. Shenzhen and Suzhou industrial clusters concentrate brushless motor manufacturing for regional export.
India
BIS compulsory registration for imported power tool motors accelerates domestic assembly investments across Maharashtra and Gujarat industrial corridors. Western ports handle concentrated motor arrivals, creating logistics vulnerability during monsoon disruptions. Mumbai and Ahmedabad fabrication shops source localized supply chains to bypass import bottlenecks.
Japan
METI industrial equipment efficiency benchmarks push automotive assembly plants toward premium brushless architectures. Kanto region fabrication shops retain pneumatic legacy infrastructure due to sunk compressor investments. Nagoya automotive clusters specify diagnostic-compatible platforms for assembly line integration.
Vietnam
Residential construction permit velocity channels procurement toward compact cordless drill drivers and impact wrenches for finishing work. Ho Chi Minh City contractors retire pneumatic systems to eliminate compressor logistics from job sites. Housing development in Binh Duong and Dong Nai provinces concentrates demand for battery platforms.
Australia
Infrastructure investment concentrates demand in commercial construction segments where contractors specify cordless lithium-ion density improvements. METI-aligned efficiency benchmarks influence procurement patterns among Japanese-affiliated automotive plants in Victoria. Sydney and Melbourne building sites drive battery platform adoption for mobility-critical applications.
Asia Pacific Power Tools Market Competitive Landscape
Listed leaders compete with private specialists across platform architecture and channel control dimensions. The vendor base stratifies into German-engineered premium licensors, Japanese channel-anchored incumbents, and Asian cost-optimized assemblers. Three archetypes dominate: technology licensors with proprietary motor platforms, distributors with deep retail control, and scale-driven battery specialists. Competitive moves concentrate on M&A for regional assembly capacity and strategic partnerships for cell chemistry access.
Within the premium engineering tier, Robert Bosch GmbH and Makita Corporation exemplify divergent market positions. Bosch leverages German-engineered platform architecture across Indian and Chinese assembly plants. Makita anchors its position through deep channel control in Japanese home improvement retail. Techtronic Industries Co. Ltd. occupies a position as a scale-driven cordless specialist competing aggressively on lithium-ion density in Southeast Asian construction markets.
| Leading Market Players |
|---|
| Stanley Black & Decker, Inc. |
| Robert Bosch GmbH |
| Techtronic Industries Co. Ltd. |
| Makita Corporation |
| Hilti Corporation |
| Atlas Copco AB |
| Koki Holdings Co., Ltd. |
| Snap-On, Inc. |
| Apex Tool Group, LLC |
| Others |
Pricing and Supply Chain Analysis
China's SAMR enforcement of GB 31241-2022 battery safety standards gates supplier qualification while simultaneously stratifying price tiers across cordless power tool portfolios. Manufacturers absorbing compliance costs faster command premium positioning against importers reliant on third-party cell certification.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on METI efficiency certification grade and brushless motor thermal management capability. Cost compression in mid-tier cordless assemblers is intensifying because Chinese lithium carbonate refiners transmit cell chemistry volatility downstream. Home improvement contractors through online retail channels exhibit highest price sensitivity; Japanese automotive assembly plants show least.
Supply Chain Analysis
Strait of Malacca transit underwrites lithium-ion cell movement from Chinese Yangtze River Delta refineries to Southeast Asian assembly plants. Supply concentrates in China for battery chemistry, Japan for precision motor components, and Vietnam for final cordless tool assembly. Raw material dependencies span lithium carbonate, neodymium rare earth magnets, and copper windings. Single-source vulnerability concentrates in Chinese cell suppliers under SAMR export licensing. Distribution runs through regional wholesale networks defending position with battery exchange services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story justified by regulatory entrenchment: multi-jurisdiction certification timelines create eight-to-fourteen-month launch barriers that protect incumbents with established compliance infrastructure.
For Market Incumbents: Consolidate brushless motor platform control through backward integration into Indian assembly capacity across Maharashtra and Gujarat corridors. Deepen channel captivity in Japanese home improvement retail against online retail disintermediation. Prioritize BIS registration completion before monsoon logistics disruptions concentrate import bottlenecks.
For New Entrants and Emerging Players: Lead with Indonesia's underpenetrated home improvement channel in Jakarta and Surabaya where wholesale markups remain bypassable through direct-to-contractor platforms. Target Vietnamese residential construction contractors retiring pneumatic systems for cordless density improvements. Anchor go-to-market through specification transparency on online retail portals.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across brushless motor manufacturing as thermal management R&D requirements deepen. Long-term viability favors vertically integrated specialists with captive cell chemistry access and multi-jurisdiction certification expertise. Acquisition target archetype: mid-tier cordless assemblers with Indian BIS registration and Chinese GB compliance already secured. Watch lithium carbonate price volatility as margin inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Investment | GB 31241-2022 and BIS registration create eight-month launch barriers protecting compliant incumbents. |
| Backward Integration into Cell Supply | Captive lithium-ion chemistry access insulates margin predictability from Chinese refiner volatility. |
| Brushless Motor Platform Standardization | METI efficiency benchmarks push automotive OEMs toward diagnostic-compatible premium architectures. |
| Direct-to-Contractor Channel Expansion | Online retail disintermediation in Jakarta and Surabaya bypasses traditional wholesale margin capture. |
| Regional Assembly Capacity Addition | Maharashtra and Gujarat domestic investments accelerate BIS compliance and monsoon logistics resilience. |
Research Methodology
Operator-level perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and distributor channel managers anchored the qualitative base. Primary interviews combined with secondary validation from customs trade records, BIS registration databases, METI efficiency filings, and SEC 10-K disclosures. Bottom-up segment sizing triangulated against top-down regional construction permit velocity data.
Sensitivity analysis framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end user industry, distribution channel structure, and application function. CAGRs derived from regression against housing permit indices, automotive production schedules, and industrial capacity utilization. Industry-specific forecast inputs span lithium-ion energy density improvement curves and brushless motor adoption rates.
Underlying assumptions cover regulatory compliance timeline stability and lithium carbonate price mean-reversion, with deviation risk concentrated in SAMR enforcement intensity and monsoon logistics disruption severity. Practitioners should keep alternative scenarios live as multi-jurisdiction certification harmonization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Turning Centers Market
Tools
Sand Control Tools Market
Tools
Bandsaw Market
Tools
Digital Levels Market
Tools
Boring-Milling Machines Market
Tools
Yard Scraper Market
Tools
Tooling Market
Tools
Tool Hammer Market
Tools
Metal Cutting Machine Market
Tools
Air Drills Market
Tools
Cordless Fillet Weld Grinder Market
Tools
Global Standard Parts for Tool Making Market
Tools
Global Sandblasting Media Market
Tools
Cordless Impact Wrench Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Bar Clamp Market