
 ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market | 2026-2036
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market Insights
Multi-source cathode procurement is hardening as the dominant sourcing pattern across ASEAN cell assemblers. Contemporary Amperex Technology Co Ltd anchors its regional position through integrated lithium-iron-phosphate cell production in Thailand. Samsung SDI Co Ltd competes on high-nickel chemistry platforms designed for tropical climate durability. BYD Company leverages captive vertical integration from mining through module pack assembly to sustain cost leadership in passenger vehicle applications.
Plug-in hybrid electric vehicle batteries store electrical energy for propulsion alongside an internal combustion engine, typically employing lithium-ion cells with nickel-manganese-cobalt or lithium-iron-phosphate cathode formulations rated between 8 and 25 kilowatt-hours to deliver pure electric ranges. These systems enable partial zero-emission operation during urban driving while eliminating range anxiety on intercity routes. Lithium-ion chemistry dominates installed capacity due to mature supply chains and declining cell costs, though solid-state architectures are attracting development capital for next-generation thermal safety performance. Passenger vehicles absorb the majority of current output, while commercial fleet vehicles represent the fastest-expanding application segment as logistics operators seek fuel cost hedging against volatile ASEAN diesel pricing.
Thailand's Board of Investment coordinates with the country's national automotive regulator to mandate local content thresholds for EV battery assembly, conditioning market access on domestic manufacturing presence. Indonesia's Ministry of Energy and Mineral Resources structures nickel processing licensing to downstream battery value chains, while the ASEAN Framework for Circular Economy for the Electrical and Electronic Sector establishes regional recycling obligations for end-of-life cells. Stakeholders must monitor how divergent national incentive schemes across Thailand, Indonesia, and Vietnam reshape competitive positioning without harmonized ASEAN-wide technical standards.
Market Dynamics
Multi-source cathode procurement is hardening as the dominant sourcing pattern across ASEAN cell assemblers, redirecting supply chain investment toward Bangkok and Eastern Economic Corridor industrial zones as Thailand's Board of Investment incentives for local cell manufacturing reshape competitive positioning.
Growth Catalysts
- Thailand's Board of Investment Incentives:Local content thresholds for EV battery assembly condition market access on domestic manufacturing presence, redirecting supply chain investment toward Bangkok and Eastern Economic Corridor industrial zones.
- ASEAN Framework for Circular Economy:Regional recycling obligations for end-of-life cells establish compliance infrastructure that favors early movers in closed-loop material recovery.
- Urban Logistics Electrification:Fleet operators across Thailand and Indonesia are expanding PHEV procurement as diesel price volatility drives fuel cost hedging strategies.
Market Restraints
- Nickel Processing Concentration:Indonesia's Ministry of Energy and Mineral Resources structures downstream licensing in ways that create single-point dependencies for cathode precursor supply.
- Tropical Climate Degradation:High-nickel chemistry platforms face accelerated electrolyte decomposition under sustained heat and humidity, compressing cycle life expectations.
- Divergent National Incentive Schemes:Non-harmonized technical standards across Thailand, Indonesia, and Vietnam fragment compliance costs without ASEAN-wide certification reciprocity.
Strategic Opportunities
- Vietnam Manufacturing Underpenetration:Cell assembly capacity remains concentrated in Thailand and Indonesia, creating first-mover positioning for facilities serving Mekong Delta automotive clusters.
- Commercial Fleet Electrification:Logistics operators seeking fuel cost hedging represent the fastest-expanding application segment for PHEV battery procurement.
- Solid-State Architecture Development:Next-generation thermal safety performance is attracting development capital for lithium-metal anode integration with sulfide electrolyte systems.
Industry Challenges
- Cell Chemistry Talent Scarcity:Electrochemists with tropical climate formulation experience remain concentrated in Northeast Asian R&D centers, constraining local product adaptation.
- Capex Intensity for Dry Electrode Production:Solvent-free coating equipment requires upfront investment that exceeds mid-tier assembler balance sheet capacity.
- Integration Complexity with Legacy Powertrains:PHEV battery management systems must interface with existing internal combustion engine control architectures that lack standardized communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market |
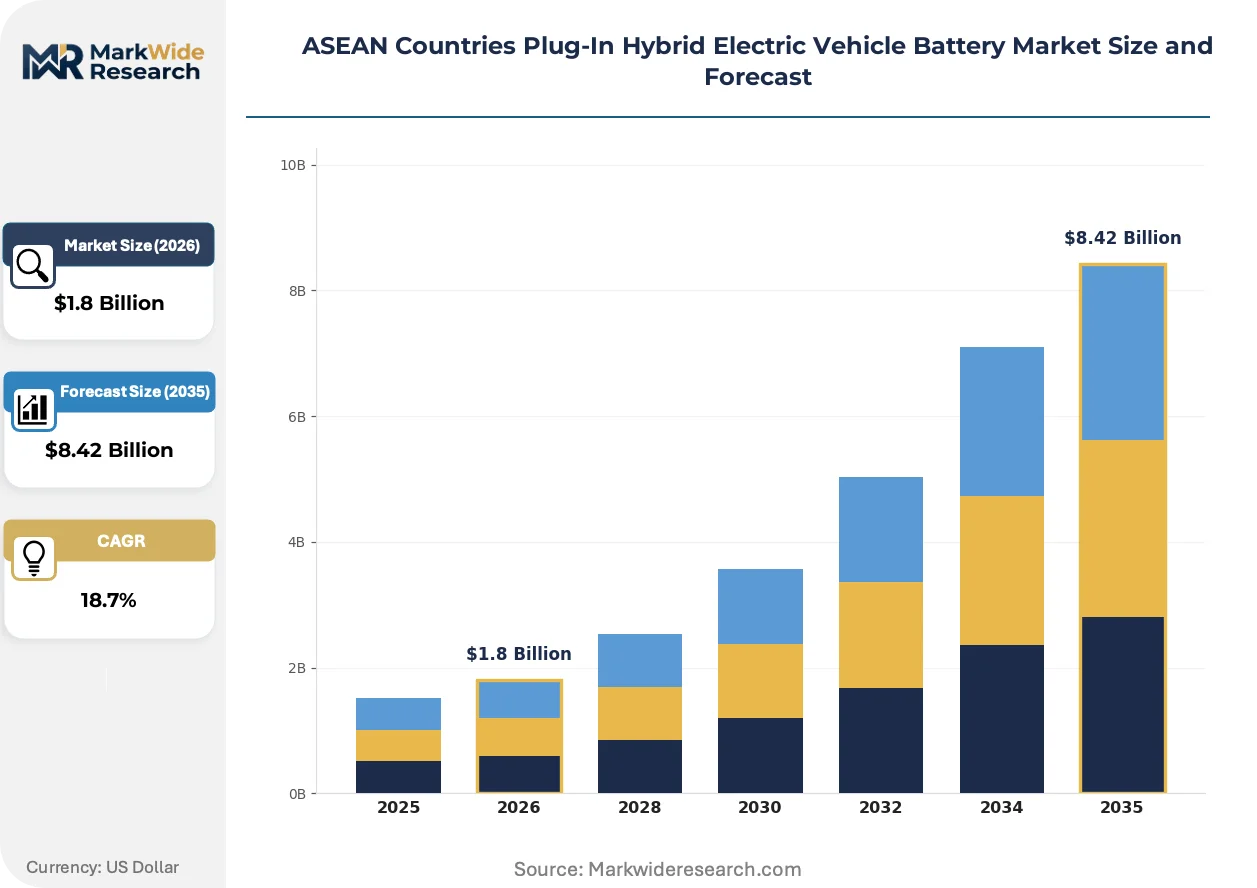
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Metal Hydride, Solid-State, Lead-Acid Charging Mechanism: AC Charging, DC Fast Charging, Wireless Charging, Supercharging Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Fleet Vehicles End User: OEMs, Aftermarket Providers, Rental Services, Government Fleets |
| Companies Covered | LG Energy Solution, Contemporary Amperex Technology Co Ltd, BYD Company, Samsung SDI Co Ltd, HDS Global Pte Ltd, 3K Battery, VinES Energy Solutions Joint Stock Company, LiRON LIB Power Pte Ltd, GS Yuasa Corporation, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market Trends and Innovations
Battery chemistry platforms are diverging across performance and cost axes as tropical climate durability requirements reshape formulation priorities. Three distinct trajectories are crystallizing competitive positioning.
Lithium-iron-phosphate cathode formulations are converging with integrated cell-to-pack architectures to compress system-level costs. Thai passenger vehicle assemblers are adopting these platforms at accelerating pace for urban duty cycles. The structural consequence is displacement of mid-nickel manganese cobalt chemistries in price-sensitive applications.
Indonesia's Ministry of Energy and Mineral Resources nickel processing licensing is downstreaming battery value chains through mandatory refining investment thresholds. Industrial consequence includes captive precursor supply for high-nickel cathode production. Commercial fleet applications across Java and Sumatra are most affected, with operators prioritizing energy density over cycle life.
Fleet procurement contracts are compressing tender cycles from annual to quarterly reviews as diesel price volatility intensifies fuel cost hedging imperatives. Direct manufacturer relationships are displacing multi-tier distribution for volume operators. Thailand's logistics corridors between Bangkok and Laem Chabang port exhibit the most visible concentration of this pattern.
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market Segmentation
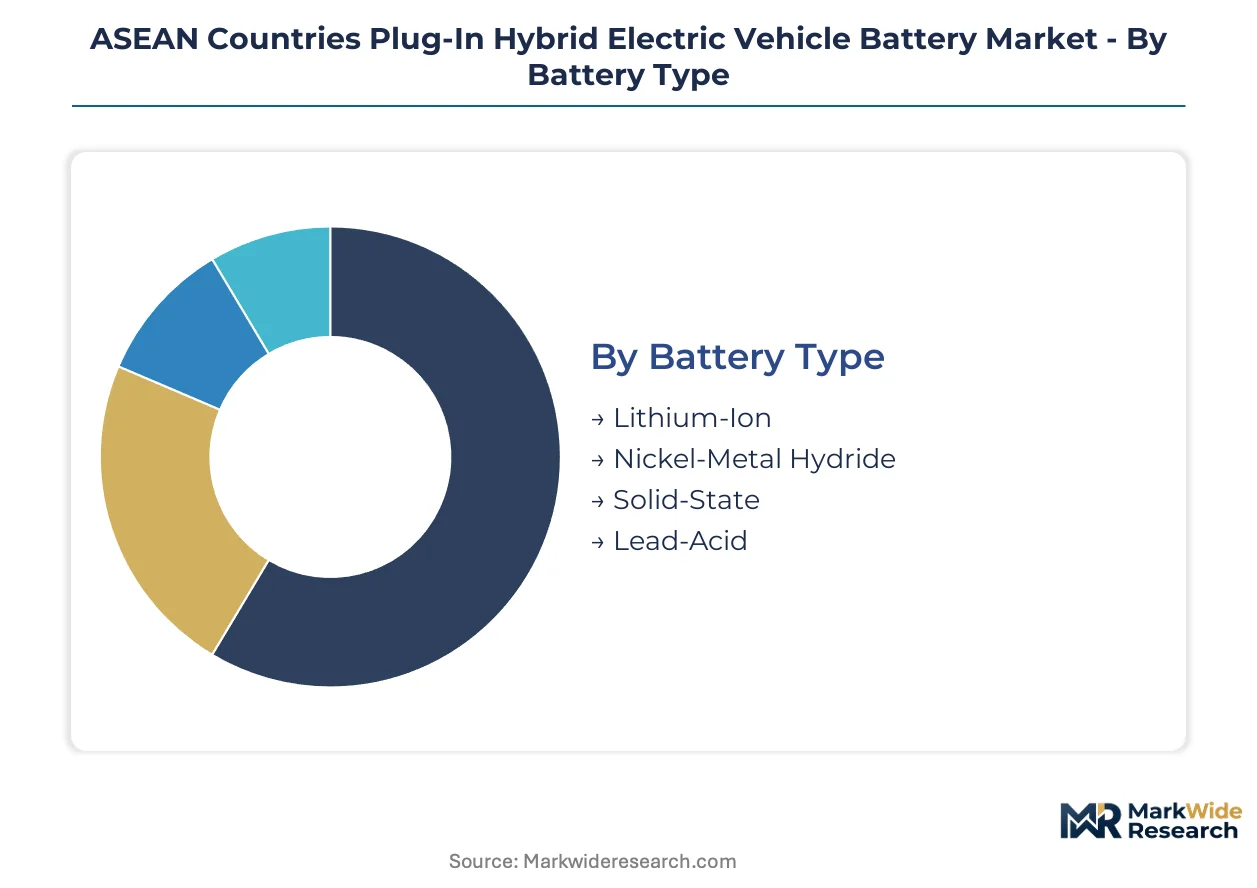
PHEV battery procurement in ASEAN diverges sharply across chemistry platforms, charging infrastructure maturity, and fleet versus retail ownership models. Cell assemblers configure product lines around these axes to capture divergent buyer priorities on cost, cycle life, and energy density.
Battery Type:
Cost sensitivity and thermal performance under tropical humidity drive chemistry selection for Thai and Indonesian assemblers.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate formulations dominate installed capacity, with LFP gaining share in Bangkok passenger vehicle production due to lower thermal runaway risk. Thai Board of Investment incentives for local cell manufacturing accelerate LFP assembly line deployment in the Eastern Economic Corridor.
- Solid-State:Sulfide electrolyte architectures with lithium-metal anodes attract development capital for next-generation thermal safety performance. Indonesian nickel processing licensing creates captive precursor supply for high-energy-density prototypes targeting commercial fleet applications.
- Nickel-Metal Hydride:Legacy chemistry retains presence in cost-constrained two-wheeler conversions where energy density requirements remain modest.
- Lead-Acid:Auxiliary power applications in commercial vehicle starter systems sustain residual demand despite displacement from traction battery roles.
Volume sits with Lithium-Ion; growth tilts toward Solid-State.
Charging Mechanism:
Infrastructure deployment patterns across Thailand, Indonesia, and Vietnam reshape procurement specifications for onboard power electronics.
- AC Charging:Overnight residential and depot charging dominates fleet operator economics, with 7-22 kilowatt onboard chargers standardizing across Thai passenger PHEVs. Bangkok condominium electrical capacity constraints limit faster AC adoption in dense urban districts.
- DC Fast Charging:50-150 kilowatt public infrastructure expansion along Indonesia's Trans-Java toll corridor enables intercity PHEV operation without range anxiety. State electricity utility PLN coordinates charging station placement with nickel processing industrial zones.
- Wireless Charging:Inductive pad systems pilot at Laem Chabang port logistics terminals for automated guided vehicle applications.
- Supercharging:Ultra-high-power stations above 250 kilowatts remain concentrated at premium retail locations in Bangkok and Jakarta.
Deployment concentrates on AC Charging; capability investment flows toward DC Fast Charging.
Application:
Duty cycle intensity and daily mileage variance segment battery specification requirements across ASEAN automotive production.
- Passenger Vehicles:8-15 kilowatt-hour packs with blended powertrain integration dominate Thai OEM output, optimized for urban congestion and occasional highway use. Eastern Economic Corridor assembly plants configure cell-to-pack architectures for cost compression.
- Fleet Vehicles:Logistics operators across Thailand and Indonesia are expanding PHEV procurement as diesel price volatility intensifies fuel cost hedging strategies. Quarterly tender reviews compress procurement cycles for volume fleet contracts.
- Commercial Vehicles:Light truck and van applications in Java and Sumatra prioritize energy density over cycle life for high-utilization delivery routes.
- Two-Wheelers:Motorcycle electrification lags passenger vehicle adoption due to battery weight constraints on vehicle dynamics.
Production volume centers on Passenger Vehicles; procurement momentum builds fastest in Fleet Vehicles.
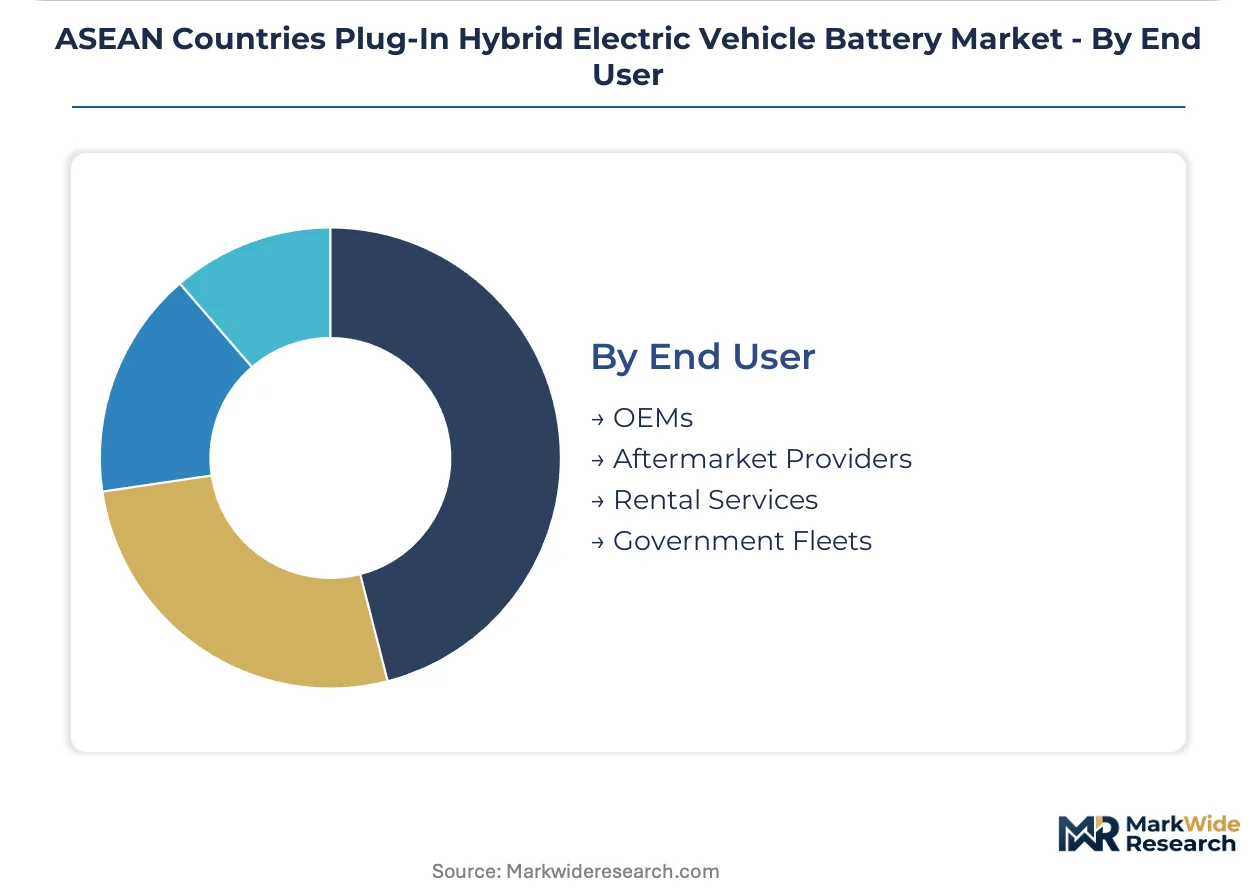
End User:
Channel structure and ownership duration determine service requirements and warranty risk allocation for cell suppliers.
- OEMs:Integrated vehicle manufacturers in Thailand source through direct cell supplier relationships, conditioning procurement on local content thresholds for Board of Investment incentive eligibility. Bangkok and Eastern Economic Corridor industrial zones concentrate assembly capacity.
- Government Fleets:State procurement mandates across ASEAN capitals prioritize domestic manufacturing presence and circular economy compliance for end-of-life cell recovery.
- Aftermarket Providers:Independent battery replacement channels serve out-of-warranty vehicles, with service networks concentrated in Jakarta and Ho Chi Minh City.
- Rental Services:Short-term vehicle providers in tourist corridors specify standardized packs for rapid swap compatibility.
Procurement scale aggregates with OEMs; policy momentum favors Government Fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's nickel laterite deposits anchor raw material supply for cathode precursor production across Southeast Asia, conditioning downstream investment patterns in cell manufacturing and recycling infrastructure deployment.
Thailand
Fleet electrification in Bangkok logistics corridors and Board of Investment incentives for local cell assembly drive procurement momentum. Thailand's national automotive regulator mandates domestic content thresholds for EV battery manufacturing eligibility. Eastern Economic Corridor industrial zones concentrate LFP assembly capacity expansion.
Indonesia
Nickel processing licensing downstreams battery value chains through mandatory refining investment thresholds. The Ministry of Energy and Mineral Resources structures cathode precursor supply dependencies for regional assemblers. Java and Sumatra industrial clusters prioritize high-nickel chemistry platforms for commercial fleet energy density requirements.
Vietnam
Underpenetrated cell assembly capacity creates positioning opportunities for Mekong Delta automotive cluster supply. The country's national industrial development framework incentivizes battery manufacturing investment through tax holidays and land allocation. Ho Chi Minh City and surrounding provinces concentrate logistics operator procurement reviews.
Singapore
Financial and trading hub functions support regional procurement contract structuring and recycling compliance coordination. The city-state's national environmental agency enforces transboundary hazardous waste protocols affecting end-of-life cell movement. Jurong Island chemical processing infrastructure enables precursor material trade facilitation.
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market Competitive Landscape
Global majors compete with regional champions across chemistry platform specialization and local content compliance capabilities. Market structure tilts toward consolidated cell supply with tiered differentiation between integrated manufacturers and module assemblers. Three archetypes dominate: Northeast Asian integrated producers with captive mineral access, ASEAN-based assemblers leveraging tariff-advantaged production, and Chinese vertically integrated firms controlling cost structures from mining through pack integration. Competitive moves concentrate on capacity expansion in Thailand and Indonesia plus strategic partnerships with national automotive champions.
Among Northeast Asian integrated producers, LG Energy Solution and Samsung SDI Co Ltd exemplify high-nickel chemistry specialization for tropical climate durability requirements. Contemporary Amperex Technology Co Ltd anchors the Chinese integrated archetype through Thailand-based LFP production serving Bangkok passenger vehicle assemblers. Regional specialists including VinES Energy Solutions Joint Stock Company occupy positions between global scale and local compliance agility.
| Leading Market Players |
|---|
| LG Energy Solution |
| Contemporary Amperex Technology Co Ltd |
| BYD Company |
| Samsung SDI Co Ltd |
| HDS Global Pte Ltd |
| 3K Battery |
| VinES Energy Solutions Joint Stock Company |
| LiRON LIB Power Pte Ltd |
| GS Yuasa Corporation |
| Others |
Pricing and Supply Chain Analysis
Dry electrode coating adoption across Thai LFP assembly lines is compressing manufacturing overhead while concentrating production capability in the Eastern Economic Corridor. This process transition simultaneously lowers unit economics and reinforces geographic supply clustering as assemblers co-locate near Bangkok port infrastructure for cathode precursor import.
Pricing Analysis
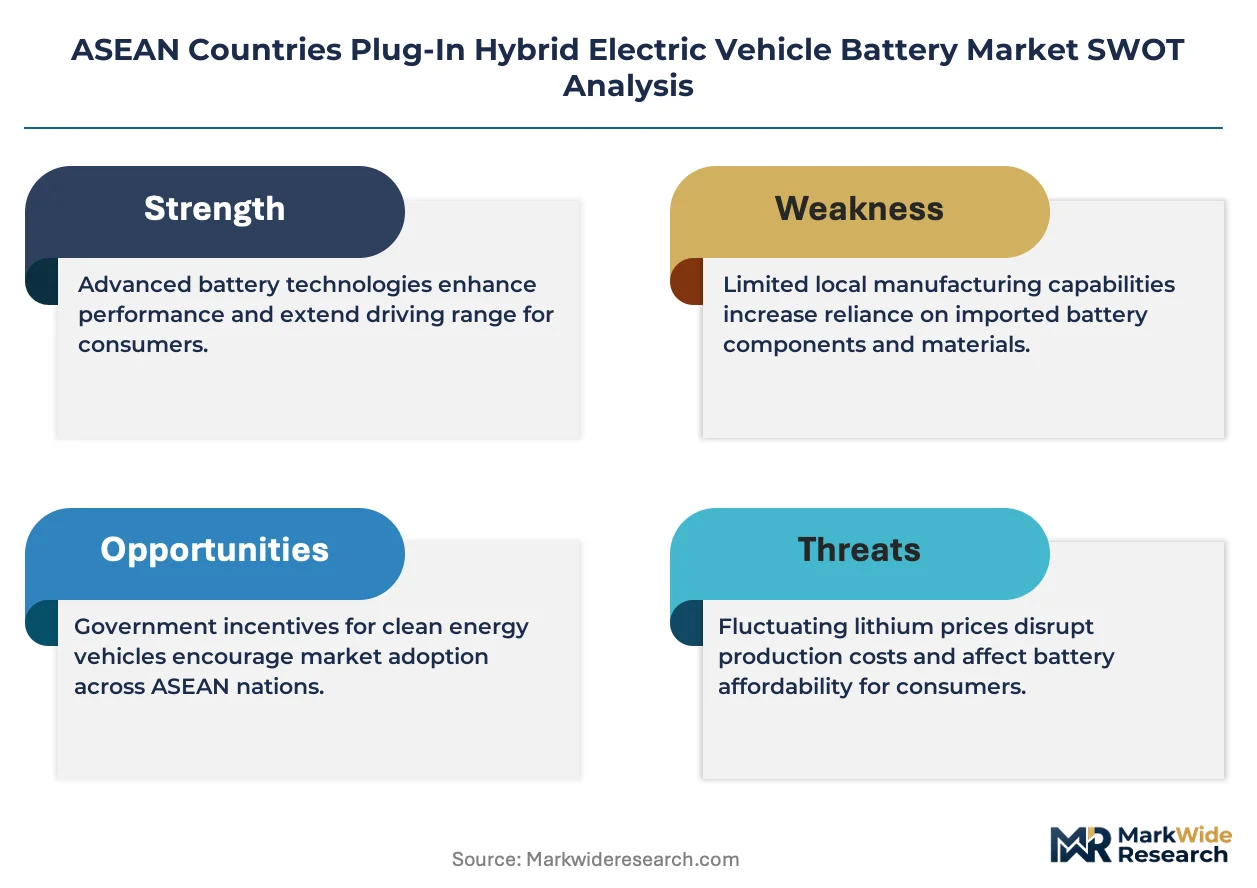
Warranty bundling separates Thai passenger vehicle OEM contracts from Indonesian commercial fleet procurement, with Bangkok assemblers demanding extended thermal performance guarantees under tropical humidity stress. Pricing stratifies across premium high-nickel chemistry, standard LFP integrated packs, and economy-tier nickel-metal hydride conversions for two-wheeler retrofits. Cost compression in standard-tier LFP is intensifying because CATL Thailand and BYD captive supply chains eliminate precursor import markups. Fleet operators in Java exhibit lowest price sensitivity, prioritizing energy density and cycle life guarantees over per-kilowatt-hour acquisition cost.
Supply Chain Analysis
Nickel laterite supply rests on Indonesian Morowali and Weda Bay processing zones, with Chinese and South Korean offtake agreements locking precursor flow for regional cathode production. Lithium carbonate feeds from Australian hard-rock and Chilean brine operations, while separator membranes and electrolyte salts draw from Japanese and South Korean specialty chemical producers. Single-source vulnerability concentrates in Indonesian nickel processing licensing, where Ministry of Energy and Mineral Resources downstreaming mandates create mandatory refining investment thresholds. Distribution runs through direct OEM relationships for volume procurement, with spot market residual for aftermarket replacement channels in Jakarta and Ho Chi Minh City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell assembly capacity scarcity across Vietnam and secondary Indonesian industrial zones props pricing power for qualified suppliers, with Mekong Delta underpenetration creating sustained supply-demand imbalance through the analysis window.
For Market Incumbents: To counter solid-state chemistry disruption from Korean and Japanese R&D centers, Thai-based LFP producers should deepen backward integration into precursor refining and secure Eastern Economic Corridor expansion permits ahead of Board of Investment incentive phase-downs. Certification investment in ASEAN Framework for Circular Economy compliance infrastructure will lock in government fleet procurement preference. For New Entrants and Emerging Players: Solid-state pilot production capability offers entry positioning into Indonesian commercial fleet segments where high-nickel energy density requirements outpace incumbent LFP optimization. Vietnam cell assembly underpenetration represents the most penetrable geography, with Ho Chi Minh City logistics operator quarterly tender reviews offering direct manufacturer relationship openings bypassing multi-tier distribution. For Investors and Strategic Acquirers: Re-rating potential sits with Vietnamese cell assembly specialists given national industrial development framework tax holidays and land allocation catalysts accelerating Mekong Delta manufacturing cluster formation. Long-term viability favors acquirers targeting captive nickel precursor supply tied to Indonesian downstream licensing. The signal to watch is quarterly diesel price volatility spikes triggering compressed fleet procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | Indonesian nickel processing licensing compliance secures cathode supply for high-nickel platforms. |
| Cell-to-Pack Architecture Standardization | Thai passenger vehicle OEMs adopt LFP integration to compress system-level cost structures. |
| Solid-State Prototype Development | Sulfide electrolyte lithium-metal anodes attract capital for tropical climate thermal safety performance. |
| Circular Economy Infrastructure Investment | ASEAN Framework compliance for end-of-life cell recovery locks government fleet procurement preference. |
| Mekong Delta Manufacturing Footprint | Vietnam tax holidays and land allocation incentives accelerate supply positioning for automotive clusters. |
Research Methodology
Independent corroboration across cell supplier procurement directors, Thai Board of Investment incentive program officers, and Indonesian Ministry of Energy and Mineral Resources licensing administrators underwrites the qualitative findings. Primary interviews with fleet operator procurement managers in Bangkok and Jakarta logistics corridors combined with secondary validation from customs trade data, national automotive production databases, and ASEAN regulatory filings established demand-side triangulation. Bottom-up cell shipment analysis and top-down vehicle registration data reconciliation anchored volume estimates.
Comparable-period anchoring linked historical production capacity utilization to forward-looking incentive program phase-out schedules across the analysis window. Segmentation modeling incorporated battery chemistry platform, charging infrastructure maturity, vehicle application duty cycle, and national regulatory cluster dimensions. CAGRs derived from production capacity expansion timelines, fleet electrification procurement cycle compression, and diesel price volatility correlation analysis. Forecast inputs included Thai Board of Investment local content threshold enforcement intensity and Indonesian nickel downstreaming licensing progression.
Several conditions sit outside the modeled scope, including unannounced solid-state chemistry commercialization timelines and potential ASEAN-wide technical standard harmonization reversals. Forecasts reflect documented assumptions regarding incentive program continuity and nickel processing licensing stability. A small set of named triggers warrants ongoing watch: quarterly diesel price volatility spikes, solid-state prototype thermal performance breakthroughs, and Vietnamese industrial land allocation acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
ASEAN E-Bike Market
Electric Vehicles
North America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Micro Electric Vehicle Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
Used EV Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Electric Vehicle Heating System Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
South Korea E-Bike Market
Electric Vehicles
Electric Vehicle Liquid-Cooled Charging Connector Market
Electric Vehicles
Europe Wireless Electric Vehicle Charging Market
Electric Vehicles
Central and Eastern Europe E-Bike Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market