
 Global Smart Insulin Pens Market | 2026-2036
Global Smart Insulin Pens Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Insulin Pens Market Foresight
The EU Medical Device Regulation is broadening the cost-of-entry calculus for connected insulin delivery systems, forcing manufacturers to rebuild clinical evidence packages for legacy platforms. Novo Nordisk A/S leverages its endocrine therapy heritage to anchor pen hardware within broader diabetes ecosystems. Medtronic competes through its pump-to-pen data continuity strategy, while Ypsomed AG specializes in modular pen platforms that accommodate multiple drug formulations.
Smart insulin pens are electromechanical drug-delivery devices that integrate dose-capture sensors, Bluetooth or NFC transmitters, and companion software to log injection timing, volume, and glucose context for diabetes management. Durable pens occupy the dominant revenue position due to recurring cartridge replacement economics, while sensor-based technology segments capture premium pricing through real-time adherence analytics. Bluetooth-enabled connectivity leads volume deployment, though mobile app integration segments are expanding fastest as payers tie reimbursement to demonstrable outcome tracking.
The FDA governs premarket submission pathways for these devices under combination product rules, while the EMA's MDR framework demands post-market surveillance for software-upgradable pen systems. Japan's PMDA adds layered pharmacovigilance requirements for devices that store patient-identifiable dosing records. Stakeholders must decide whether to build proprietary data architectures or align with emerging interoperability standards before payer contracting locks in dominant platforms.
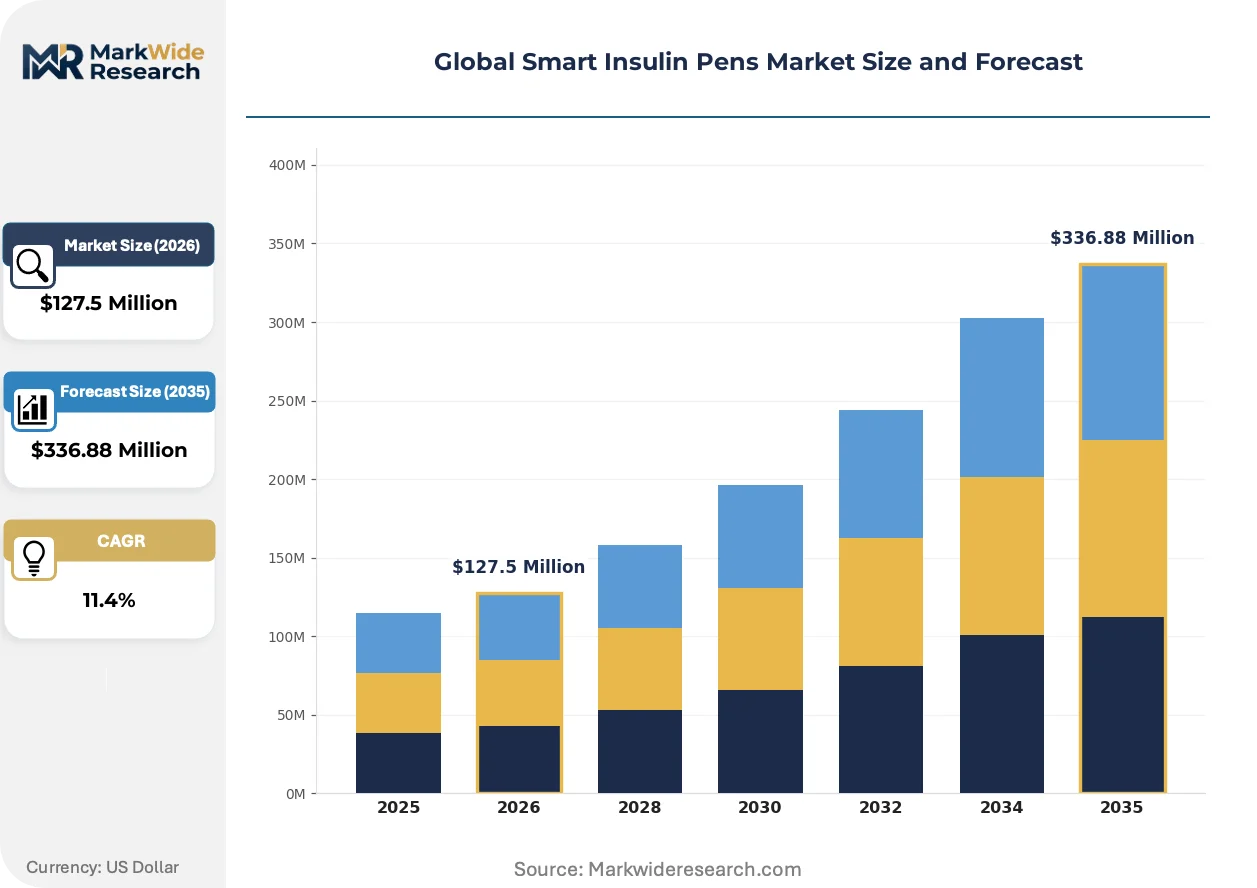
Market Dynamics
The EU Medical Device Regulation is forcing manufacturers to rebuild clinical evidence packages for legacy connected pen platforms, while home care demand accelerates self-management tool adoption across reimbursement-rich markets.
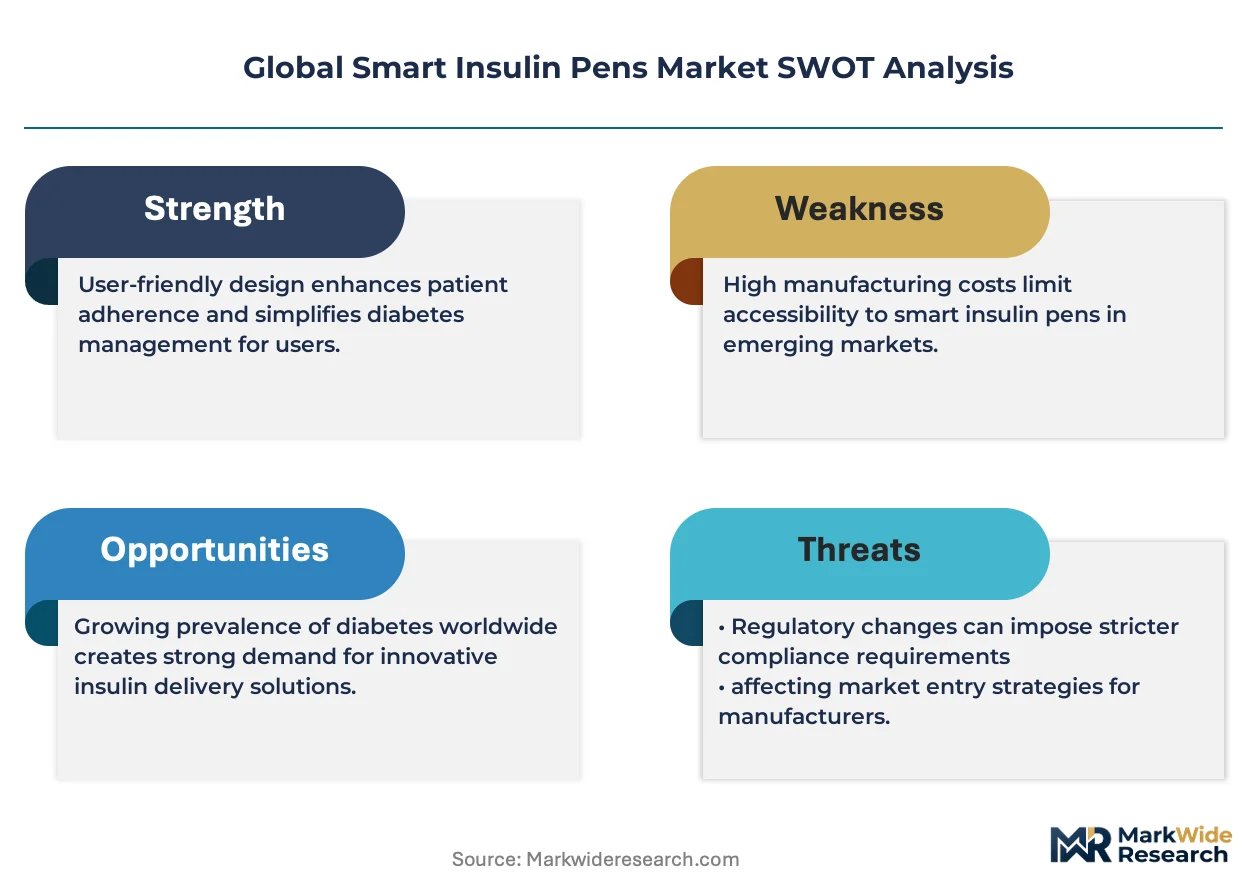
Growth Catalysts
- Home Care Migration:Patients in the United States, Germany, and Japan seek dose-capture tools that reduce clinic dependency. Reimbursement pathways for digital diabetes management are most established in these markets.
- MDR Compliance Pressure:The EU Medical Device Regulation tightens quality requirements for connected drug-delivery platforms, creating competitive moats for firms with pre-certified manufacturing systems.
- Sensor Miniaturization:Advances in micro-electromechanical systems enable real-time adherence analytics without cartridge interference, expanding premium pricing opportunities for device makers.
Market Restraints
- Silicon Supply Concentration:Taiwan-based foundries dominate Bluetooth and NFC transmitter chip fabrication, exposing pen manufacturers to geopolitical supply disruptions.
- Battery Chemistry Constraints:Lithium-ion cell sourcing faces ESG scrutiny under EU Battery Regulation due diligence rules, complicating disposable pen economics.
- Software Validation Burden:FDA combination product rules demand extensive premarket documentation for app-integrated dose logging, extending development timelines.
Strategic Opportunities
- Indian Market Penetration:India's CDSCO has streamlined medical device registration for connected drug-delivery systems, opening access to 77 million diagnosed diabetes cases.
- GLP-1 Formulation Flexibility:Modular pen platforms accommodating semaglutide and tirzepatide cartridges capture expanding obesity therapy demand.
- Interoperability Standards Alignment:HL7 FHIR integration positions devices for payer contracting in US value-based care arrangements.
Industry Challenges
- Embedded Firmware Expertise Scarcity:Pen manufacturers compete for engineers with FDA 21 CFR Part 820 software validation experience, compressing development bandwidth.
- Legacy Health Record Integration:Hospital procurement committees demand Epic and Cerner compatibility, forcing middleware investments that strain mid-tier device margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Insulin Pens Market |
| Market Size in 2026 | $127.5 Million |
| Market Size in 2035 | $336.88 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Durable Pens, Disposable Pens, Reusable Pens, Wireless Pens Technology: Bluetooth, NFC, Memory Chip, Mobile App Integration, Sensor-Based Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes End User: Pharmacies, Diabetes Clinics, Home Care, Specialty Centers |
| Companies Covered | Novo Nordisk A/S, Medtronic, Eli Lilly and Company, Ypsomed AG, Abbott Laboratories, Emperra GmbH, Pendiq, Cambridge Consultants Ltd., Companion Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Insulin Pens Market Shifts & Advancements
Three distinct vectors are reshaping competitive positioning: hardware-software convergence in dose delivery, regulatory fragmentation across major jurisdictions, and procurement model evolution toward outcome-guaranteed supply contracts.
Continuous glucose monitoring sensors are converging with insulin pen hardware to create closed-loop decision support. Endocrinology practices in Germany and the Netherlands are piloting these integrated systems for Type 1 populations. The structural consequence is compressing standalone pen margins while rewarding ecosystem orchestrators.
The EU AI Act imposes risk-classification requirements on machine learning algorithms that predict hypoglycemic events from injection patterns. Device manufacturers must implement post-market performance monitoring and human oversight protocols. Japan's PMDA is observing these developments closely, suggesting harmonized pharmacovigilance approaches for algorithm-enabled pens.
Hospital procurement committees are unbundling device supply from data analytics subscriptions, forcing manufacturers to price hardware and software separately. This shift is most visible in US integrated delivery networks where pharmacy benefit managers negotiate direct with pen vendors. German sickness funds are testing similar unbundling for regional diabetes management contracts.
Global Smart Insulin Pens Market Segmentation
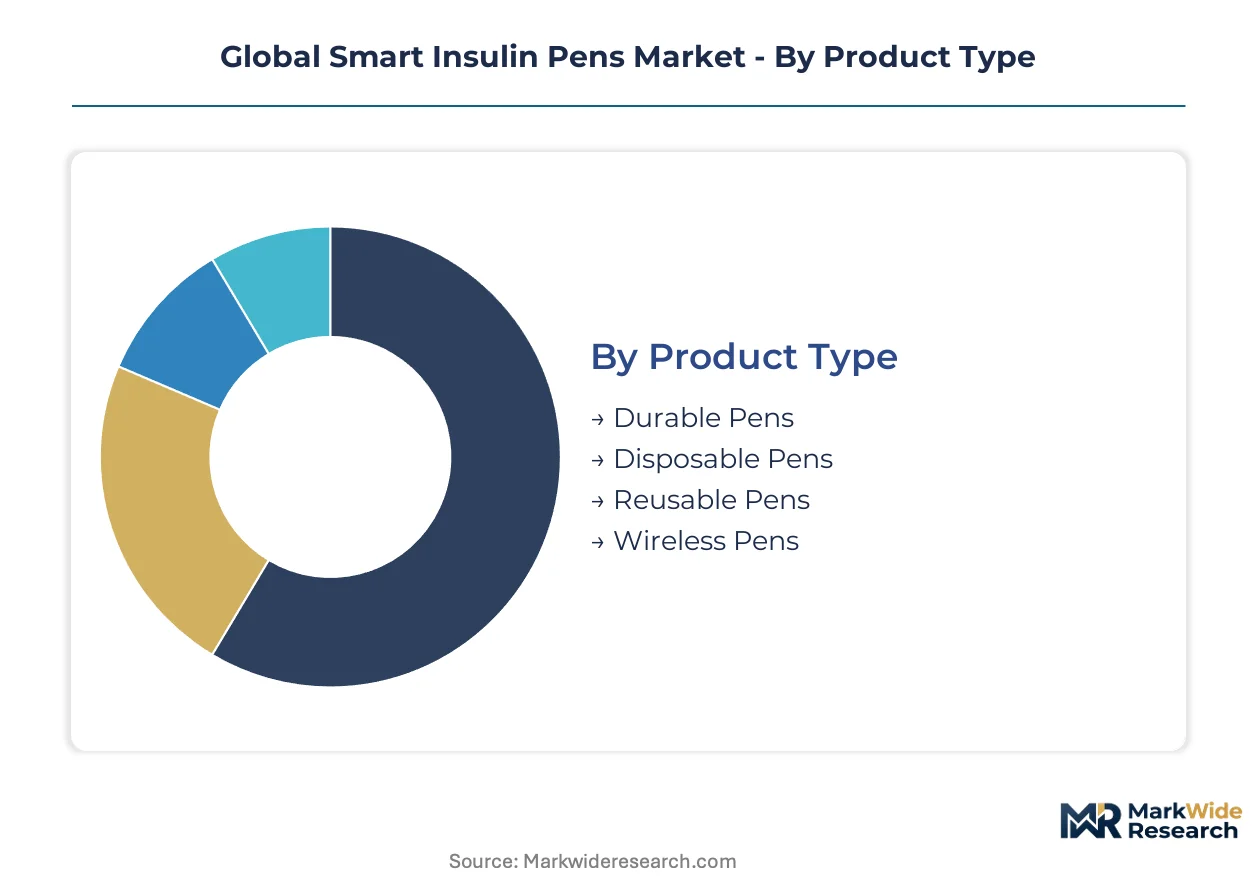
Smart insulin pen manufacturers configure their portfolios across four distinct dimensions, each demanding different capital deployment strategies and regulatory navigation. Product architecture decisions lock in manufacturing footprints for years, while technology choices determine software validation burdens and partnership requirements.
Product Type:
Capital intensity peaks with electromechanical durability engineering, where mold tooling and sensor integration drive upfront investment thresholds.
- Durable Pens:These electromechanical devices incorporate dose-capture sensors and cartridge receptacles designed for multi-year operational lifespans. Demand concentrates in Germany and Japan where sickness funds and insurers reimburse premium hardware under chronic disease management programs. The recurring cartridge replacement economics justify higher device subsidies.
- Disposable Pens:Single-use units integrate Bluetooth or NFC transmitters with pre-filled insulin cartridges, eliminating calibration burden for patients. United States pharmacy benefit managers favor these for formulary tier placement due to simplified adherence tracking and lower upfront patient costs.
- Reusable Pens:Hybrid designs separate the electronic dose-logging core from disposable insulin reservoirs, balancing sustainability mandates with digital connectivity. European Green Deal packaging regulations are accelerating engineering investment in this category.
- Wireless Pens:Fully untethered devices transmit injection data directly to cloud platforms without smartphone intermediation. Japan's PMDA has established specific radio-frequency approval pathways for these systems.
Most installed capacity flows through Durable Pens. Expansion is steepest in Disposable Pens.
Technology:
Engineering talent scarcity varies dramatically across connectivity protocols, with firmware validation expertise commanding premium compensation in Bluetooth and sensor fusion domains.
- Bluetooth:Low-energy radio modules enable real-time dose transmission to paired smartphones, dominating volume deployment across reimbursement-rich markets. FDA 21 CFR Part 820 software documentation requirements extend development timelines for these connected systems.
- NFC:Near-field communication supports passive data retrieval without battery drain, appealing to disposable pen economics. German diabetes clinics have standardized on NFC for patient education workflows where smartphone pairing complexity creates adoption friction.
- Memory Chip:Onboard storage captures injection histories for periodic clinical download, minimizing connectivity infrastructure requirements. India's CDSCO registration pathways favor these lower-complexity systems for price-sensitive market entry.
- Mobile App Integration:Companion software platforms aggregate dose logs with continuous glucose monitor data streams, expanding fastest as US payers tie reimbursement to demonstrable outcome tracking. HL7 FHIR interoperability investments are becoming table stakes for hospital procurement.
- Sensor-Based:Micro-electromechanical systems detect injection timing, volume, and anatomical placement without patient manual entry, commanding premium pricing through real-time adherence analytics.
Bluetooth-enabled systems carry the heaviest validation burden. Mobile App Integration is climbing the fastest as value-based care contracts proliferate.
Application:
Patient population heterogeneity dictates dosing algorithm complexity and clinical evidence requirements for regulatory submission.
- Type 1 Diabetes:Absolute insulin deficiency requires precise basal-bolus tracking, driving demand for closed-loop integration with continuous glucose monitors. Netherlands endocrinology practices are piloting pen-CGM convergence for this population.
- Type 2 Diabetes:Progressive beta-cell dysfunction creates variable insulin dependence, with dose-capture tools supporting therapy intensification decisions. United States integrated delivery networks prioritize these devices for population health management.
- Gestational Diabetes:Temporary hyperglycemia during pregnancy demands precise glycemic control with minimal patient training burden. Maternal-fetal medicine clinics in Germany favor simplified pen interfaces for this acute care context.
- Prediabetes:Early intervention programs leverage dose-logging for lifestyle modification reinforcement, though reimbursement pathways remain underdeveloped across most jurisdictions.
Type 1 applications command the highest per-patient device economics. Type 2 represents the largest addressable population base.
End User:
Procurement authority fragmentation across channel types forces manufacturers to maintain multiple pricing and service architectures simultaneously.
- Home Care:Direct-to-patient distribution dominates volume as self-management tools reduce clinic dependency. Reimbursement pathways in the United States, Germany, and Japan are most established for this channel.
- Diabetes Clinics:Specialty practices demand Epic and Cerner electronic health record compatibility, forcing middleware investments that strain mid-tier device margins.
- Pharmacies:Retail dispensing creates formulary placement competition where pharmacy benefit managers negotiate directly with pen vendors. US integrated delivery networks are unbundling device supply from data analytics subscriptions in this channel.
- Specialty Centers:Academic medical centers and research institutions drive early adoption of algorithm-enabled pens for hypoglycemia prediction, though procurement volumes remain limited.
Home Care channels absorb the majority of unit shipments. Specialty Centers are gaining share fastest as algorithm validation studies expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized firmware engineers with FDA 21 CFR Part 820 validation experience concentrate in Boston, Basel, and Tokyo, anchoring the geographic distribution of smart insulin pen development.
United States
Integrated delivery networks in Minnesota and California drive formulary placement negotiations for Bluetooth-enabled dose-capture devices. FDA combination product rules govern premarket submissions for app-integrated systems. The Greater Boston cluster hosts concentrated expertise in electromechanical sensor fusion for pen hardware.
Germany
Sickness funds in North Rhine-Westphalia and Bavaria reimburse premium durable pens under chronic disease management programs. EU Medical Device Regulation compliance requirements are tightening post-market surveillance obligations for connected platforms. The Mannheim-Heidelberg medical technology corridor specializes in modular pen platforms accommodating multiple drug formulations.
Japan
Endocrinology practices in Tokyo and Osaka pilot closed-loop pen-CGM integration for Type 1 populations. PMDA imposes layered pharmacovigilance requirements on devices storing patient-identifiable dosing records. The Kansai region concentrates manufacturing capacity for micro-electromechanical dose sensors.
India
Seventy-seven million diagnosed diabetes cases create addressable demand for simplified adherence tools in Maharashtra and Karnataka. CDSCO streamlined medical device registration pathways for connected drug-delivery systems. Hyderabad's medical device cluster is expanding contract manufacturing capacity for disposable NFC-enabled pens.
United Kingdom
NHS Integrated Care Boards in Greater Manchester and the West Midlands evaluate outcome-based procurement for digital diabetes management. MHRA aligns with EMA MDR frameworks for software-upgradable pen systems. The Cambridge-Oxford corridor anchors algorithm development for hypoglycemia prediction from injection pattern analysis.
Global Smart Insulin Pens Market Competitive Landscape
The competitive structure tilts toward integrated diabetes ecosystem orchestrators with endocrine therapy heritage. Consolidation pressure concentrates around firms possessing pre-certified manufacturing systems under EU MDR and FDA quality frameworks. Two strategic archetypes dominate: pharmaceutical-origin device developers leveraging drug portfolio relationships, and specialized electromechanical fabricators with modular platform expertise. Dominant competitive moves include strategic partnerships with continuous glucose monitor manufacturers and geographic expansion into India's streamlined regulatory environment.
Among pharmaceutical-origin developers, Novo Nordisk A/S and Eli Lilly and Company exemplify the ecosystem-orchestrator archetype, anchoring pen hardware within broader diabetes therapy portfolios. Specialized electromechanical fabricators occupy a distinct tier, with Ypsomed AG representing the modular platform specialist position. Medtronic sits within the data-continuity segment, bridging pump and pen ecosystems. These three patterns—pharmaceutical integration, modular specialization, and cross-device data orchestration—structure competitive positioning as reimbursement ties increasingly to demonstrable outcome tracking.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Medtronic |
| Eli Lilly and Company |
| Ypsomed AG |
| Abbott Laboratories |
| Emperra GmbH |
| Pendiq |
| Cambridge Consultants Ltd. |
| Companion Medical |
| Others |
Supply & Pricing Matrix
Hospital procurement committees unbundling device supply from data analytics subscriptions are forcing manufacturers to price hardware and software separately, compressing standalone pen margins while rewarding ecosystem orchestrators with captive cartridge economics.
Pricing Analysis
The bundled-vs-unbundled service split now structures competitive pricing across reimbursement-rich markets. Three-tier pricing stratifies across premium sensor-integrated systems, standard Bluetooth-enabled devices, and economy memory-chip pens, with FDA 21 CFR Part 820 certification tiers creating clear differentiation boundaries. Pricing pressure stems from pharmacy benefit manager formulary negotiations in US integrated delivery networks, where data analytics subscriptions face separate procurement scrutiny. Home care patients in Germany and Japan show least price sensitivity due to sickness fund hardware subsidies, while Indian CDSCO-registered entrants compete on disposable pen unit economics.
Supply Chain Analysis
Reverse-logistics flows for durable pen refurbishment and sensor recalibration are anchoring service revenue models in Germany and Japan. Taiwan-based foundries dominate Bluetooth and NFC transmitter chip fabrication, while Japanese manufacturers in the Kansai region concentrate micro-electromechanical dose sensor capacity. Lithium-ion cell sourcing draws from South Korean and Chinese suppliers, exposing disposable pen programs to EU Battery Regulation due diligence compliance costs. Single-source vulnerability in Taiwan semiconductor fabrication creates geopolitical risk exposure. Distribution runs through hospital procurement committees in the United States, sickness fund regional contracts in Germany, and pharmacy benefit manager networks in both markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on sensor miniaturization cost curves and the shift toward premium closed-loop pen-CGM systems commanding ecosystem subscription pricing.
For Market Incumbents: Hedge against algorithm-enabled pen displacement by deepening firmware validation expertise pools in Boston and Basel manufacturing clusters. Secure pre-certified EU MDR manufacturing status to create compliance moats against mid-tier competitors. Lock in continuous glucose monitor partnerships before hospital procurement committees standardize on integrated platforms. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian CDSCO-registered disposable pens offers white-space entry for NFC-enabled simplified adherence tools. Target Maharashtra and Karnataka diabetes populations with pharmacy-direct distribution bypassing hospital procurement complexity. Lead with maternal-fetal medicine clinic relationships for gestational diabetes applications where training burden sensitivity creates adoption friction for incumbent interfaces. For Investors and Strategic Acquirers: Asymmetric upside sits with modular platform specialists possessing multi-drug formulation flexibility for expanding GLP-1 obesity therapy demand. Five-to-ten year viability favors firms with pre-certified FDA 21 CFR Part 820 and EU MDR quality systems already operational. Watch for HL7 FHIR interoperability certification announcements as inflection indicators for payer contracting access in US value-based care arrangements.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Combination Product Submission | Secures premarket pathway for app-integrated dose logging under 21 CFR Part 820 quality standards. |
| EU MDR Post-Market Surveillance Buildout | Creates competitive moats through clinical evidence package reconstruction for legacy connected platforms. |
| Continuous Glucose Monitor Partnership | Positions pen hardware within closed-loop decision support systems piloting in Dutch and German endocrinology practices. |
| HL7 FHIR Interoperability Investment | Unlocks hospital procurement committee access by meeting Epic and Cerner electronic health record compatibility demands. |
| India CDSCO Registration Streamlining | Opens access to 77 million diagnosed diabetes cases through simplified connected drug-delivery device pathways. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each market anchoring demand-side validation. Primary interviews with hospital procurement managers, diabetes clinic endocrinologists, biomedical engineers, pharmacy benefit managers, and GPO contracts specialists combined with secondary sources including FDA 510(k) filings, EMA MDR technical documentation, CDSCO registration databases, CMS Medicare reimbursement schedules, and hospital procurement contract records. Bottom-up device shipment modeling and top-down therapy expenditure analysis provided triangulation checks.
Rate-of-change decomposition structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture durability, connectivity protocol technology, diabetes type application, and end-user channel. CAGRs derived from patient population growth, reimbursement pathway expansion, and technology substitution curves. Forecast inputs incorporated EU MDR compliance timeline assumptions and GLP-1 therapy penetration effects on multi-drug pen platform demand.
The model assumes a particular technology adoption path; alternative pathways for closed-loop pen-CGM convergence would alter the outlook if sensor miniaturization cost curves flatten or regulatory harmonization accelerates. Forecasts reflect base-case assumptions regarding reimbursement pathway stability in the United States, Germany, and Japan. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
North America Insulin Infusion Pumps Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Smart Glucose Monitors Market
Diabetes Care
Korea Continuous Glucose Monitoring Devices Market
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market