
 New Zealand Oral Anti-Diabetic Drug Market | 2026-2036
New Zealand Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Oral Anti-Diabetic Drug Market Outlook
Australia's parallel capacity build-out in diabetes API manufacturing is rewriting supply security calculations for New Zealand distributors. Janssen Pharmaceuticals leverages its SGLT2 inhibitor portfolio to sustain premium positioning in hospital formularies. Boehringer Ingelheim anchors its presence through fixed-dose combination therapies that integrate cardiovascular outcomes data. AstraZeneca differentiates via extended-release formulations that reduce dosing frequency for Type 2 diabetes patients.
Oral anti-diabetic drugs encompass pharmacological agents administered by mouth to reduce blood glucose in diabetes mellitus, including biguanides that suppress hepatic gluconeogenesis, sulfonylureas that stimulate pancreatic beta-cell insulin secretion, DPP-4 inhibitors that prolong incretin activity, and SGLT2 inhibitors that promote urinary glucose excretion. Their primary commercial purpose centers on chronic glycemic control for Type 2 diabetes patients who retain partial pancreatic function. SGLT2 inhibitors command the fastest growth trajectory among product types, driven by cardiovascular and renal protective indications that expand prescriber adoption beyond glucose management alone. Retail pharmacies capture deepening volume flows as Pharmac's subsidy expansions reduce patient out-of-pocket costs and shift maintenance therapy from hospital to community settings.
Pharmac, New Zealand's pharmaceutical purchasing agency, governs market access through its sole-supply tendering and reference pricing mechanisms that compress branded margins while accelerating generic penetration. Medsafe, operating under the Ministry of Health, enforces Good Manufacturing Practice standards and bioequivalence requirements that filter which formulations qualify for public reimbursement. The Health and Disability Services Act frameworks shape demand through integrated care pathways that prioritize oral therapies before insulin escalation. Stakeholders must monitor Pharmac's upcoming therapeutic group reviews for SGLT2 inhibitor subsidy expansions that would redraw competitive positioning across hospital and retail channels.
Market Dynamics
Pharmac's sole-supply tendering mechanism is compressing branded margins while accelerating generic penetration across New Zealand's oral anti-diabetic drug channels. This centralized procurement structure reshapes competitive positioning by privileging lowest-cost bioequivalent suppliers over originator portfolios.
Growth Catalysts
- Cardiovascular outcome data:SGLT2 inhibitors now carry renal and heart-failure protective indications that expand prescriber adoption beyond glucose management alone.
- Auckland's integrated care networks:These consolidated delivery systems prioritize oral therapy pathways before insulin escalation, deepening formulary commitments to combination tablets.
- Pharmac subsidy expansions:Reduced patient out-of-pocket costs shift maintenance therapy volumes from hospital outpatient clinics to community retail pharmacies.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing clusters in India and China create single-source vulnerability for New Zealand distributors.
- Reference pricing floors:Pharmac's benchmark against Australian reimbursement rates caps achievable margins regardless of clinical differentiation.
- Bioequivalence testing backlog:Medsafe's Good Manufacturing Practice verification queue delays generic entry for complex extended-release formulations.
Strategic Opportunities
- Canterbury chronic disease management programs:These regionally coordinated care pathways offer preferential access for fixed-dose combination therapies with bundled monitoring services.
- Fixed-dose cardiovascular-metabolic convergence:Dual-mechanism tablets integrating SGLT2 and DPP-4 action reduce pill burden and improve adherence metrics.
- Community pharmacy vaccination integration:Diabetes screening and medication synchronization services create stickier patient relationships and recurring prescription capture.
Industry Challenges
- Specialist endocrinologist scarcity:Rural North Island regions face prolonged appointment wait times that delay therapy optimization and complex case escalation.
- Legacy insulin escalation protocols:Hospital discharge pathways default to injectable therapy for HbA1c thresholds above 9%, undermining oral drug persistence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Oral Anti-Diabetic Drug Market |
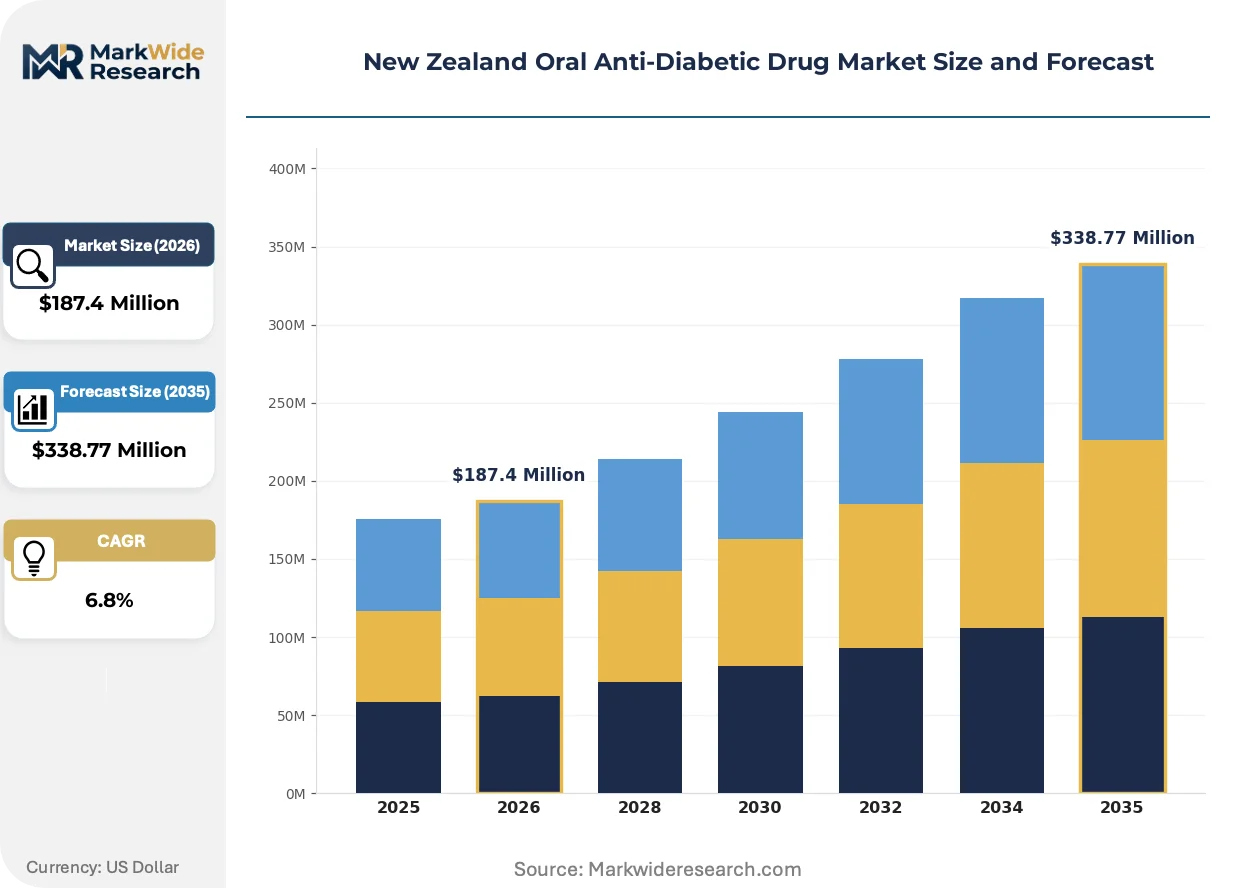
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biguanides, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors End User: Clinics, Hospitals, Retail Pharmacies, Online Pharmacies Formulation: Tablets, Extended-Release Tablets, Oral Solutions, Combination Pills Sales Channel: Prescription, Over-the-Counter, Direct-to-Consumer, Hospital Pharmacy |
| Companies Covered | Janssen Pharmaceuticals, Boehringer Ingelheim, AstraZeneca, Merck And Co Inc, Novartis, Sanofi, Astellas Pharma Inc., Takeda Pharmaceutical Company Limited, Eli Lilly and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Oral Anti-Diabetic Drug Market Strategic Shifts
Digital therapeutics and real-world evidence platforms are reshaping how prescribers evaluate oral anti-diabetic efficacy beyond traditional clinical trial endpoints. This shift compresses the feedback loop between patient monitoring and formulary decision-making.
Continuous glucose monitoring integration is digitizing prescriber workflow by feeding ambulatory glucose profile data directly into electronic health records. Endocrinology practices in Auckland and Wellington are adopting these systems fastest, enabling algorithm-assisted dose titration that reduces face-to-face consultation burden. The technology is digitizing patient-provider interaction patterns and compressing the interval between therapeutic adjustment and outcome verification.
Pharmac's therapeutic group reviews for SGLT2 inhibitors are expanding subsidy eligibility to patients with heart failure without diabetes, broadening addressable population. This regulatory recalibration redirects hospital pharmacy procurement toward cardiovascular-metabolic portfolios. Cardiology departments across New Zealand's district health boards are responding by establishing shared-care protocols with primary care networks.
Patient-initiated switching between community pharmacies is intensifying as smartphone apps compare real-time subsidy prices and stock availability. Retail chains in Christchurch and Hamilton are deploying loyalty-integrated adherence programs to reduce churn. This behavioral shift is most visible among working-age Type 2 diabetes patients managing therapy alongside employment constraints.
New Zealand Oral Anti-Diabetic Drug Market Segmentation
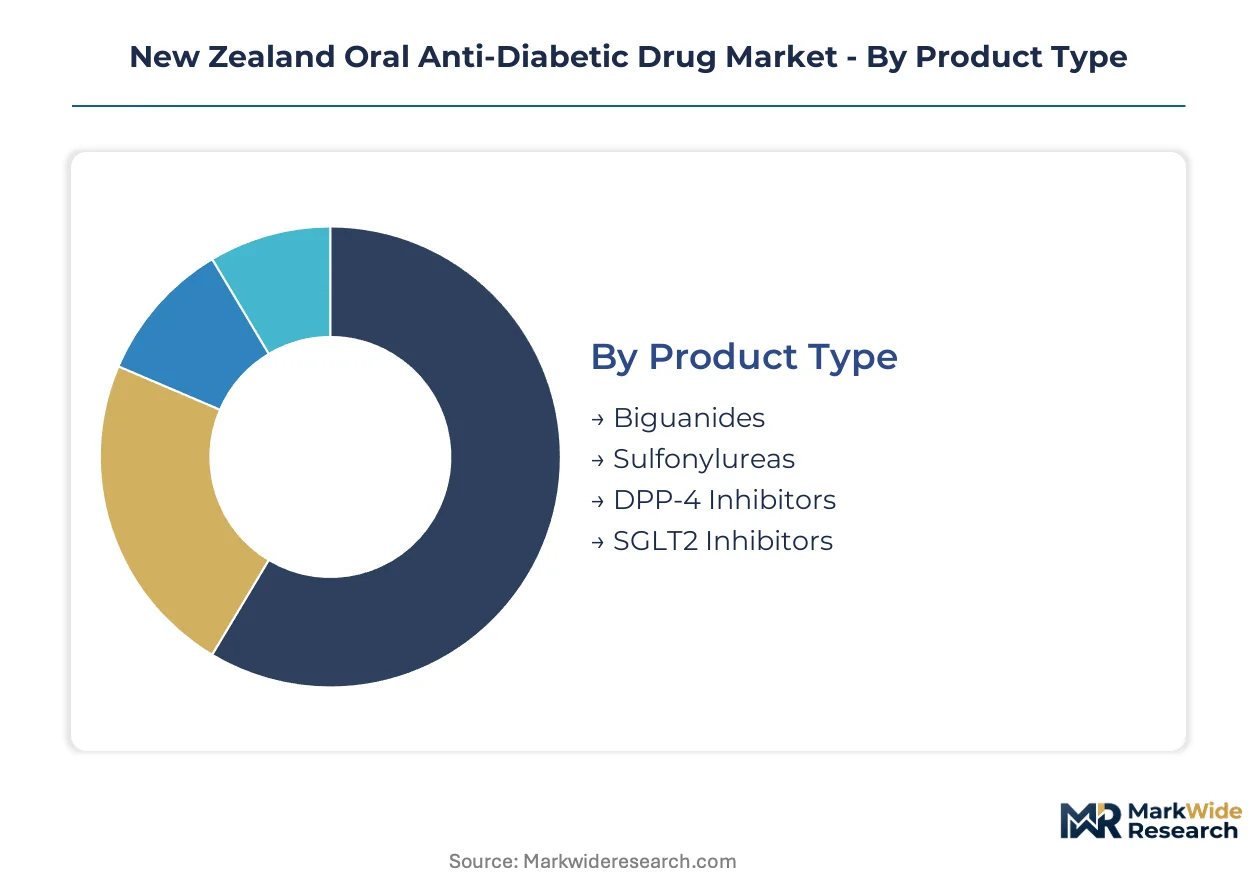
Segmentation reveals how Pharmac's procurement tiers and prescriber pathways fragment demand across mechanism classes and delivery settings. Understanding these divisions exposes where subsidy policy and clinical protocol intersect to determine volume flows.
Product Type:
Use cases span from first-line metabolic control through renal-protective cardiovascular management, with mechanism selection dictated by comorbidity profile and formulary tier.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers promote urinary glucose excretion alongside documented heart-failure and renal protective outcomes. Auckland's integrated care networks are deepening formulary commitments here as cardiovascular indications expand prescriber adoption beyond glucose management alone.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 inhibitors prolong incretin hormone activity to stimulate glucose-dependent insulin secretion. Canterbury's chronic disease management programs favor these agents for patients requiring weight-neutral therapy with low hypoglycemia risk.
- Biguanides:Metformin-class agents suppress hepatic gluconeogenesis and remain the foundational first-line therapy across New Zealand's primary care networks.
- Sulfonylureas:Pancreatic beta-cell insulin secretagogues persist in rural formularies where cost minimization overrides cardiovascular outcome considerations.
The dominant share belongs to Biguanides, while SGLT2 Inhibitors is closing the gap fastest.
End User:
Volume concentration tracks the shift from hospital-based initiation toward community maintenance as Pharmac subsidies reduce patient out-of-pocket exposure.
- Retail Pharmacies:Community-based dispensaries capture deepening volume flows as subsidy expansions shift maintenance therapy from hospital outpatient clinics. Christchurch and Hamilton chains are deploying adherence-integrated loyalty programs to reduce patient churn.
- Hospitals:District health board pharmacy procurement governs formulary placement for initiation therapy and complex case management. Cardiology departments are establishing shared-care protocols that redirect SGLT2 inhibitor prescribing toward primary care networks.
- Clinics:Primary care practices anchor chronic disease management pathways across Auckland and Wellington integrated care networks.
- Online Pharmacies:Digital dispensaries are gaining traction among working-age patients managing therapy alongside employment constraints.
Retail Pharmacies command the volume lead, though Hospitals retain control over initiation protocols that determine downstream persistence.
Formulation:
Patient adherence economics and manufacturing complexity create divergent margin structures across immediate-release and modified-delivery formats.
- Combination Pills:Fixed-dose tablets integrating SGLT2 and DPP-4 mechanisms reduce pill burden and improve adherence metrics. Boehringer Ingelheim anchors its New Zealand presence through these cardiovascular-metabolic convergence products.
- Extended-Release Tablets:Modified-release formulations reduce dosing frequency for Type 2 diabetes patients with irregular meal patterns. Medsafe's bioequivalence testing backlog delays generic entry for these complex formulations.
- Tablets:Immediate-release solid oral dosage forms dominate cost-minimized procurement tiers.
- Oral Solutions:Liquid formulations serve swallowing-impaired populations and pediatric off-label use.
Tablets maintain the installed base, while Combination Pills are expanding most quickly through hospital formulary preference.
Sales Channel:
Reimbursement pathway determines patient access cost and prescriber autonomy, with Pharmac's sole-supply tendering compressing margins across subsidized channels.
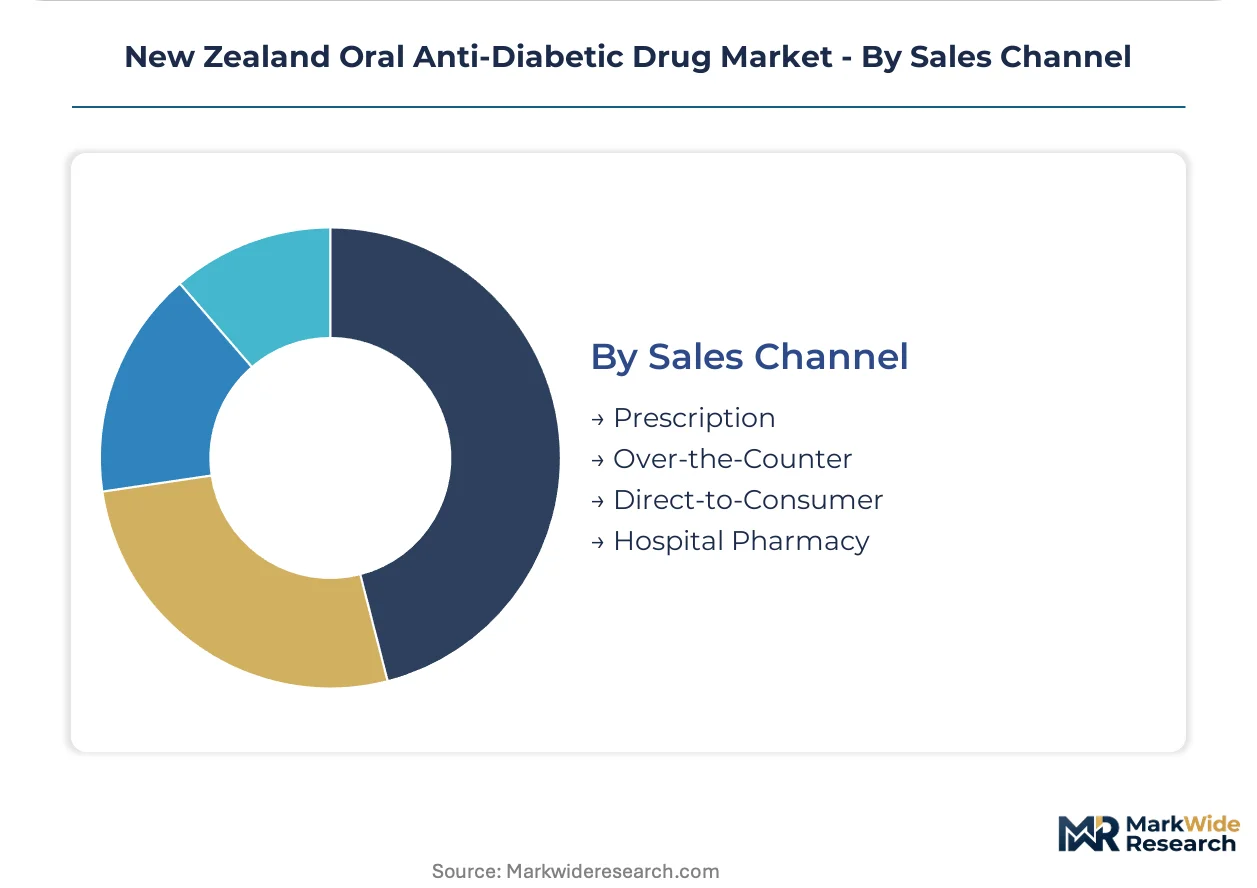
- Prescription:Pharmac-subsidized dispensing requires specialist or general practitioner authorization and captures the vast majority of oral anti-diabetic volume. Tiered subsidy frameworks reshape prescriber behavior and generic substitution rates.
- Hospital Pharmacy:District health board procurement operates under separate tendering mechanisms that privilege lowest-cost bioequivalent suppliers. SGLT2 inhibitors are deepening formulary commitments here through cardiovascular outcome data.
- Over-the-Counter:Unsubsidized pharmacy-only sales persist for metformin in limited circumstances.
- Direct-to-Consumer:Bypass channels remain marginal due to Medsafe's strict prescription medicine classification.
Prescription channels dominate volume, while Hospital Pharmacy procurement is gaining influence through integrated care pathway design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Tauranga's cold-chain logistics infrastructure underwrites distribution efficiency for temperature-sensitive oral anti-diabetic formulations across New Zealand's North Island. This maritime gateway connects Auckland's integrated care networks to international API supply routes from Australia and Asia-Pacific manufacturing clusters.
Auckland
Auckland's integrated care networks prioritize oral therapy pathways before insulin escalation, deepening formulary commitments to SGLT2 inhibitors and combination tablets. Pharmac's tiered subsidy framework reshapes prescriber behavior across the region's district health boards. Waitemata and Auckland DHBs anchor cardiovascular-metabolic convergence protocols that redirect hospital pharmacy procurement toward renal-protective agents.
Canterbury
Canterbury's chronic disease management programs offer preferential access for fixed-dose combination therapies with bundled monitoring services. The region's shared-care protocols between Christchurch Hospital and primary care networks accelerate DPP-4 inhibitor adoption for weight-neutral therapy. Medsafe's bioequivalence verification queue delays generic entry for extended-release formulations distributed through Canterbury's retail pharmacy chains.
Wellington
Wellington's endocrinology practices adopt continuous glucose monitoring integration fastest, enabling algorithm-assisted dose titration that reduces consultation burden. The Capital and Coast DHB procurement operates under Pharmac's sole-supply tendering that privileges lowest-cost bioequivalent suppliers. Porirua and Lower Hutt clinics anchor digital therapeutics pilot programs feeding real-world evidence into electronic health records.
Waikato
Waikato's rural North Island regions face prolonged endocrinologist appointment wait times that delay therapy optimization and complex case escalation. Hamilton's retail pharmacy chains deploy loyalty-integrated adherence programs to reduce patient churn among working-age Type 2 diabetes patients. The district health board's hospital discharge pathways default to injectable therapy for HbA1c thresholds above 9%, undermining oral drug persistence.
New Zealand Oral Anti-Diabetic Drug Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in API and formulation supply. New Zealand's oral anti-diabetic market structures around three tiers: originator multinationals with cardiovascular outcome data, generic bioequivalent suppliers competing on Pharmac tender pricing, and regional distributors managing cold-chain logistics. Dominant competitive moves include fixed-dose combination portfolio diversification and backward integration into API sourcing to mitigate India-China supply concentration risks.
Among multinational originators, Janssen Pharmaceuticals, Boehringer Ingelheim, and AstraZeneca occupy positions defined by their therapeutic portfolios. Janssen exemplifies the SGLT2 inhibitor-focused archetype leveraging cardiovascular and renal protective indications. Boehringer Ingelheim represents the fixed-dose combination specialist anchoring presence through cardiovascular-metabolic convergence products. AstraZeneca sits within the extended-release formulation tier, reducing dosing frequency for Type 2 diabetes patients with irregular meal patterns.
| Leading Market Players |
|---|
| Janssen Pharmaceuticals |
| Boehringer Ingelheim |
| AstraZeneca |
| Merck And Co Inc |
| Novartis |
| Sanofi |
| Astellas Pharma Inc. |
| Takeda Pharmaceutical Company Limited |
| Eli Lilly and Company |
| Others |
Value Chain & Pricing Dynamics
Auckland's integrated care networks anchor procurement concentration that compresses margins across New Zealand's oral anti-diabetic channels. Pharmac's sole-supply tendering mechanism translates upstream API cost fluctuations into rigid reference pricing floors, stripping originators of pricing autonomy while accelerating generic substitution.
Pricing Analysis
Volume-discount tiering structures separate originator cardiovascular-outcome portfolios from bioequivalent generics and subsidized standard-tier entries. Price differentiation rests on cardiovascular indication breadth and renal protective data quality, with branded SGLT2 inhibitors commanding premium positioning against commodity metformin. Cost compression in the generic tier intensifies as Indian API suppliers compete on Pharmac tender pricing. Hospital pharmacy buyers exhibit lowest price sensitivity due to formulary commitment protocols, while retail pharmacy procurement faces acute margin pressure from patient switching apps.
Supply Chain Analysis
Contract-manufacturing concentration for oral anti-diabetic APIs sits with Indian pharmaceutical clusters and Chinese chemical synthesis hubs. Active pharmaceutical ingredient supply draws from Gujarat and Zhejiang manufacturing corridors, with excipient sourcing anchored in European specialty chemical producers. Single-source vulnerability pervades the SGLT2 inhibitor precursor market, where limited qualified suppliers create bottleneck exposure. Distribution runs through Port of Tauranga cold-chain infrastructure into district health board central warehouses and community pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand's oral anti-diabetic market represents high-growth disruption as Pharmac's SGLT2 inhibitor subsidy expansion for heart-failure-without-diabetes indications rewrites addressable population calculations. This regulatory inflection redirects hospital procurement toward cardiovascular-metabolic portfolios and compresses the window for legacy mechanism repositioning.
For Market Incumbents:Entrench formulary position through fixed-dose combination portfolio depth that bundles cardiovascular outcome data with adherence-monitoring services. Backward integration into API sourcing mitigates India-China supply concentration threats. Defensive patent landscaping around extended-release formulation technologies preserves margin against bioequivalent generic entry delayed by Medsafe testing queues.
For New Entrants and Emerging Players:Establish a beachhead in Canterbury's chronic disease management programs where bundled monitoring services create stickier prescriber relationships than transactional dispensing. Rural North Island regions present underpenetrated white space where endocrinologist scarcity delays therapy optimization and creates appetite for algorithm-assisted dosing platforms. Digital therapeutics integration with community pharmacy vaccination services offers a differentiated go-to-market angle that bypasses originator hospital formulary blockades.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors cardiovascular-metabolic convergence specialists with regulatory-grade real-world evidence platforms over single-mechanism commodity plays. Long-term viability across the projection horizon hinges on Pharmac therapeutic group review timing and subsidy expansion velocity. Acquisition target archetypes include regional distributors with cold-chain logistics assets and digital health platforms feeding glucose monitoring data into electronic health records. The signal to watch is Medsafe bioequivalence testing queue clearance rates for complex extended-release formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Advancement | Pharmac subsidy eligibility for heart-failure indications expands addressable population beyond diabetes patients. |
| Fixed-Dose Combination Development | Boehringer Ingelheim's SGLT2-DPP-4 integration reduces pill burden and improves adherence metrics in hospital formularies. |
| API Supply Backward Integration | Captive production of sodium-glucose cotransporter-2 precursors mitigates India-China single-source vulnerability. |
| Continuous Glucose Monitoring Partnership | Auckland and Wellington endocrinology practices adopt algorithm-assisted dose titration reducing consultation burden. |
| Community Pharmacy Adherence Integration | Christchurch and Hamilton chains deploy loyalty-integrated programs to reduce patient churn among working-age populations. |
Study Parameters
Desk research of Pharmac subsidy schedules, Medsafe bioequivalence approval databases, and district health board procurement records preceded structured interviews with formulary directors, hospital pharmacy managers, and primary care network clinical leads. Primary fieldwork captured prescriber pathway design and integrated care network protocol implementation across Auckland, Canterbury, and Wellington regions. Secondary validation drew from Pharmaceutical Management Agency tender announcements, Ministry of Health chronic disease management framework documents, and international cardiovascular outcome trial publications. Bottom-up volume modeling triangulated against top-down expenditure projections from national pharmaceutical dispensing data.
Assumptions held fixed include Pharmac's sole-supply tendering mechanism persistence and current cardiovascular outcome trial evidence standards, while variables tested included SGLT2 inhibitor subsidy expansion velocity and generic bioequivalence approval queue clearance rates. Segmentation dimensions spanned mechanism class, formulation complexity, delivery setting, and regional integrated care network maturity. CAGRs were derived from expenditure trajectory analysis cross-referenced with patient population epidemiology and therapy escalation protocol adherence. Forecast inputs incorporated continuous glucose monitoring adoption curves and digital therapeutic platform penetration assumptions.
Stress conditions across API supply disruption scenarios, regulatory subsidy reversal, and specialist workforce shortage severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Pharmac policy continuity and Medsafe approval efficiency. Quarterly review of therapeutic group review announcements and bioequivalence testing queue metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Digital Diabetes Care Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
Middle-East and Africa Blood Glucose Monitoring Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
Italy Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
Vietnam Insulin Infusion Pump Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
Global Diabetes Pen Market