
 Furniture and Home Furnishings Market | 2026-2036
Furniture and Home Furnishings Market Size, Share, and Industry Trends Forecast 2026-2036
Furniture and Home Furnishings Market Foresight
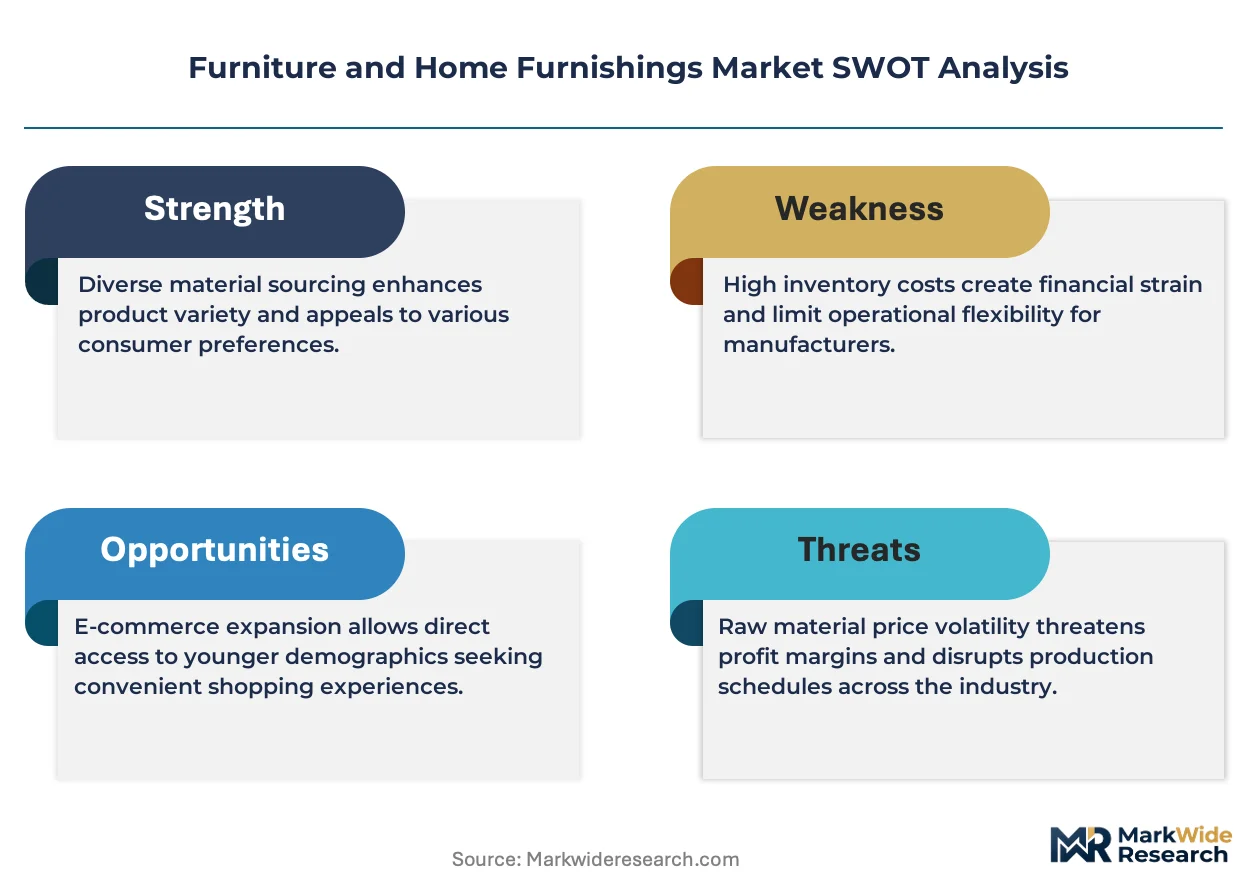
Buyer concentration in residential furniture is decoupling from traditional big-box dependency toward fragmented direct-to-consumer channels. IKEA leverages its flat-pack logistics network to sustain cost leadership across mass-market segments. Williams-Sonoma Inc. differentiates through premium lifestyle merchandising and digital-first customer engagement. Herman Miller anchors the corporate office segment with ergonomic specialization and specification-grade product development.
Furniture and home furnishings encompass movable and fixed assets designed for interior spaces, typically fabricated from wood, metal, upholstery textiles, or engineered composites through CNC machining, upholstery framing, and surface finishing processes. These products serve residential, commercial, and institutional environments by providing functional surfaces, storage, seating support, and spatial organization. Seating and beds capture the deepest margin pools due to higher material complexity and replacement frequency, while outdoor furniture registers the fastest structural expansion as climate-adapted materials improve durability. Distribution through online retailers is reshaping channel economics, though specialty stores retain dominance in premium upholstery and custom-configured storage systems.
EPA formaldehyde emission standards and California Air Resources Board (CARB) Phase 2 compliance govern composite wood products sold in the United States, directly elevating testing and certification costs for manufacturers. ECHA REACH restrictions on flame retardants and volatile organic compounds constrain upholstery chemical formulations across European markets, favoring suppliers with reformulation capabilities. ISO 14001 environmental management certification and FSC chain-of-custody tracking are becoming baseline requirements for hospitality and corporate procurement tenders. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualification gaps.
Market Dynamics
Urban residential buyers are fragmenting demand across direct-to-consumer channels while EPA formaldehyde standards and REACH chemical restrictions simultaneously elevate compliance burdens and reshape supplier qualification requirements.
Growth Catalysts
- REACH chemical restrictions:ECHA flame-retardant and VOC constraints on upholstery formulations are accelerating reformulation investments among European suppliers, creating first-mover advantages for certified producers.
- Modular manufacturing systems:CNC machining and flat-pack logistics are compressing last-mile delivery costs and enabling urban consumers to optimize limited residential square footage.
- China housing development:Tier-one city renovation cycles and new construction permits are pulling demand for space-efficient furnishings through developer procurement channels.
Market Restraints
- Composite wood input volatility:CARB Phase 2 and EPA emission testing requirements add fixed certification costs that disproportionately burden small-batch manufacturers.
- Technical limitation in climate adaptation:Outdoor furniture durability remains constrained by material degradation thresholds in high-humidity environments, limiting replacement cycle compression.
- Supply concentration risk:Engineered textile and specialty foam production clusters in specific Asian manufacturing zones expose upholstery supply chains to localized disruption.
Strategic Opportunities
- Germany renovation wave:Federal building energy retrofit mandates are unlocking replacement demand for built-in storage and space-optimized furnishings across residential units.
- Digital-first distribution:Augmented reality visualization tools are reducing return rates and enabling direct-to-consumer upholstery sales previously gated by physical showroom requirements.
- FSC chain-of-custody certification:Hospitality and corporate procurement tenders are mandating traceable wood sourcing, creating premium positioning for qualified suppliers.
Industry Challenges
- Skilled upholstery labor scarcity:Traditional framing and textile application expertise is concentrating among aging workforces in European and North American manufacturing bases.
- Multi-jurisdiction compliance timelines:Divergent formaldehyde testing protocols between EPA, CARB, and emerging state-level standards create stranded inventory risk for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furniture and Home Furnishings Market |
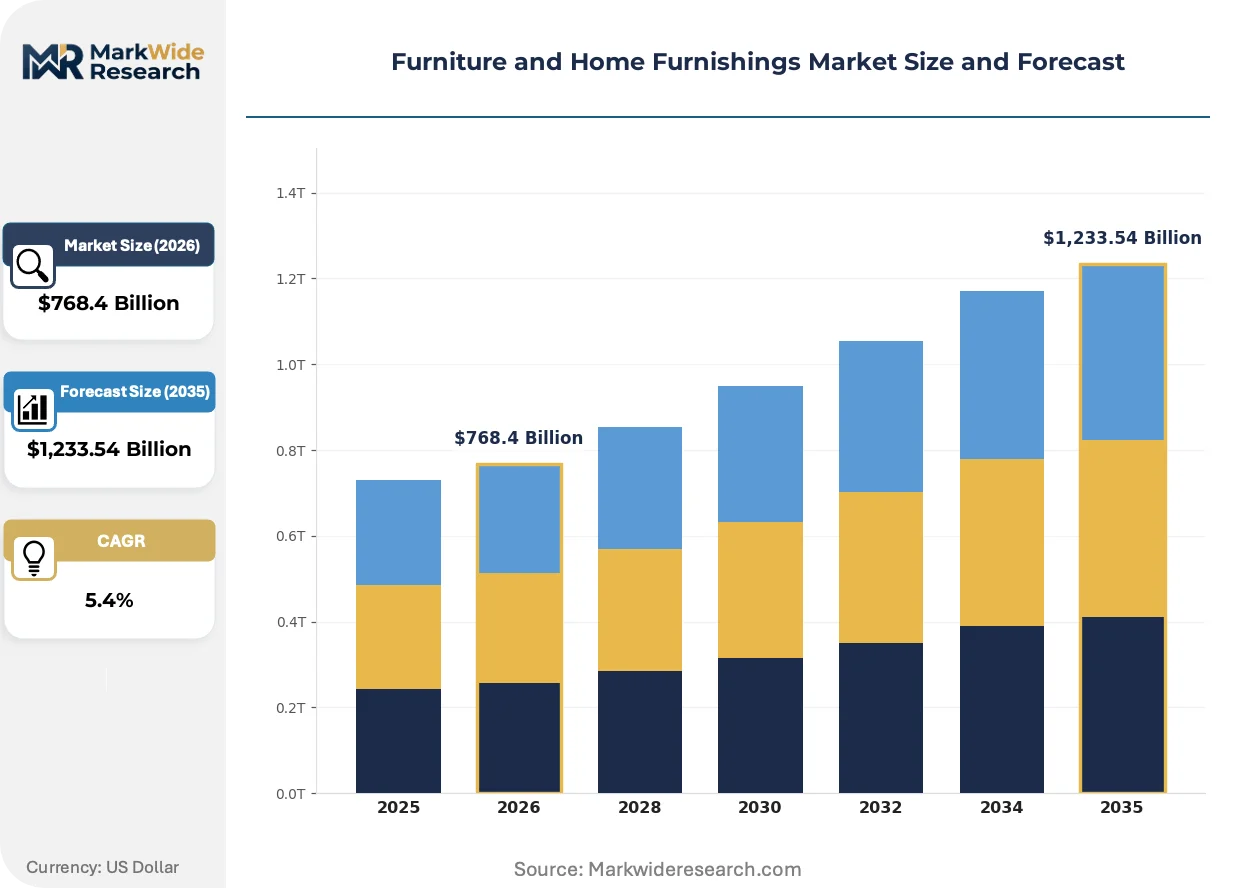
| Market Size in 2026 | $768.4 Billion |
| Market Size in 2035 | $1,233.54 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seating, Tables, Storage Units, Beds, Mattresses, Outdoor Furniture Material: Wood, Metal, Glass, Upholstery, Plastic, Rattan Distribution Channel: Specialty Stores, Online Retailers, Department Stores, Direct Sales, Warehouse Clubs End User: Residential Consumers, Hospitality, Corporate Offices, Educational Institutions, Public Facilities |
| Companies Covered | Williams-Sonoma Inc., Herman Miller, IKEA, Okamura Corporation, HNI Corporation, Ashley Furniture Industries, Steelcase Inc., RH, Wayfair Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furniture and Home Furnishings Market Shifts & Advancements
Material science advances and regulatory stringency are converging to reshape product architecture, with digital tools compressing traditional channel economics and sustainability credentials becoming non-negotiable in specification decisions.
Cross-laminated timber and engineered bamboo composites are modularizing residential furniture construction by enabling flat-pack assembly without structural compromise. Urban millennial buyers in United States and German metropolitan markets are adopting these systems at accelerated replacement frequencies. The technology is modularizing supply chain footprints by collapsing warehousing requirements and enabling direct-to-consumer fulfillment at scale previously reserved for mass-market particleboard.
California Air Resources Board Phase 2 formaldehyde standards are tightening emission thresholds for composite wood products sold in United States markets. Manufacturers face elevated third-party testing costs and documentation burdens that filter marginal producers from distribution networks. Upholstery and case goods segments serving California's housing market are responding by consolidating supplier bases around pre-certified mills with established chain-of-custody systems.
Residential buyers are unbundling after-sales service expectations from product acquisition decisions, treating furniture as disposable lifestyle accessories rather than long-term capital investments. Specialty retail channels serving premium upholstery segments are losing ground to digital-native brands offering compressed delivery windows and flexible return policies. This behavioral pivot is most visible in United States and Chinese urban centers where rental tenure shortening drives turnover velocity.
Furniture and Home Furnishings Market Segmentation
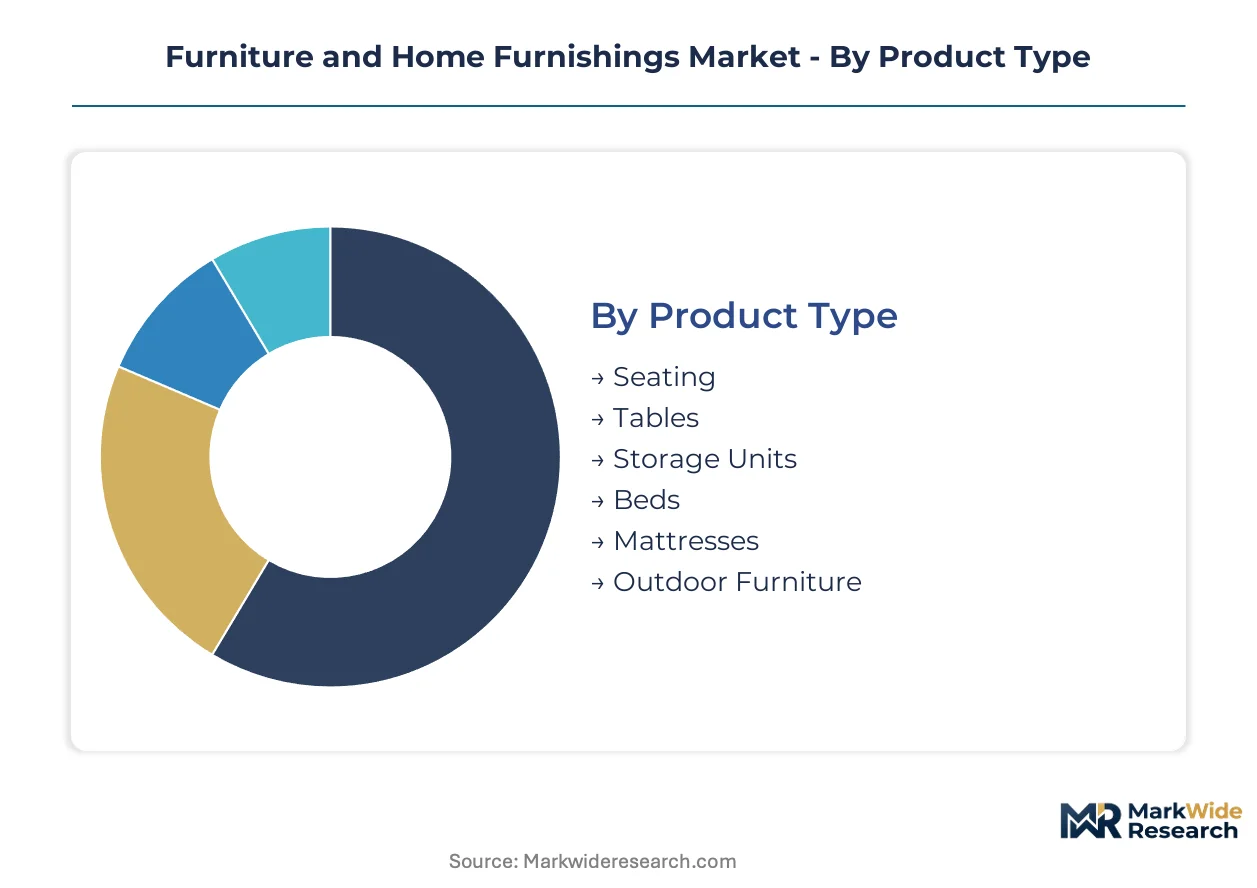
Product architecture, material specification, and channel economics fragment this market into distinct competitive arenas. Each dimension carries unique margin profiles, regulatory exposure, and buyer decision hierarchies that reshape supplier positioning.
Product Type:
Residential space constraints and replacement frequency determine which categories capture capital allocation versus operational spending.
- Seating:Upholstered frames and ergonomic shells carry the highest material complexity in residential procurement. Urban renters in United States metropolitan markets compress replacement cycles to match lease durations, prioritizing flat-pack modularity over heirloom construction.
- Beds:Mattress-in-a-box logistics and adjustable base mechanisms dominate channel innovation. German and Chinese housing developers specify integrated storage-optimized frames for new construction, pulling demand through B2B procurement rather than retail.
- Tables:Dining and work-surface units compete on dimensional flexibility for open-plan layouts.
- Storage Units:Modular closet systems and shelving respond to square-footage premiums in tier-one cities.
- Mattresses:Foam density certifications and cooling gel layers differentiate at price points.
- Outdoor Furniture:Climate-adapted wicker and powder-coated aluminum frames are expanding most quickly as humidity-resistant materials improve durability thresholds.
Volume sits with seating and beds; growth tilts toward outdoor furniture.
Material:
Compliance burden and supply chain traceability separate specification-grade inputs from commodity alternatives.
- Wood:CARB Phase 2 and EPA formaldehyde testing requirements elevate certification costs for composite substrates. Hospitality procurement in United States and Germany mandates FSC chain-of-custody documentation, filtering uncertified mills from tender participation.
- Upholstery:REACH flame-retardant restrictions and VOC emission limits constrain chemical formulations across European markets. Reformulation capabilities at textile mills in Italy and Portugal create qualification barriers for commodity suppliers.
- Metal:Powder-coating durability and weld precision define specification tiers.
- Glass:Tempered and laminated variants serve display and surface applications.
- Plastic:Recycled polymer feedstocks face performance trade-offs in structural loads.
- Rattan:Synthetic weaves displace natural cane in high-humidity climates.
Wood commands the largest procurement volumes; upholstery faces the steepest regulatory compression.
Distribution Channel:
Touchpoint requirements and return logistics determine which channels can support which product complexity tiers.
- Online Retailers:Augmented reality visualization and compressed delivery windows are displacing showroom dependency for standardized items. Digital-native brands in United States and Chinese urban centers capture millennial buyers through flexible return policies.
- Specialty Stores:Premium upholstery and custom-configured storage systems retain physical consultation requirements. Margin pools concentrate here due to specification complexity and white-glove delivery attachment.
- Department Stores:Mid-market breadth competes on convenience and financing options.
- Direct Sales:Contract furniture and built-in systems route through manufacturer representatives.
- Warehouse Clubs:Volume bundles and seasonal rotations target suburban household formation.
Specialty stores anchor premium volume; online channels are climbing the fastest.
End User:
Procurement sophistication and replacement urgency create divergent supplier qualification thresholds.
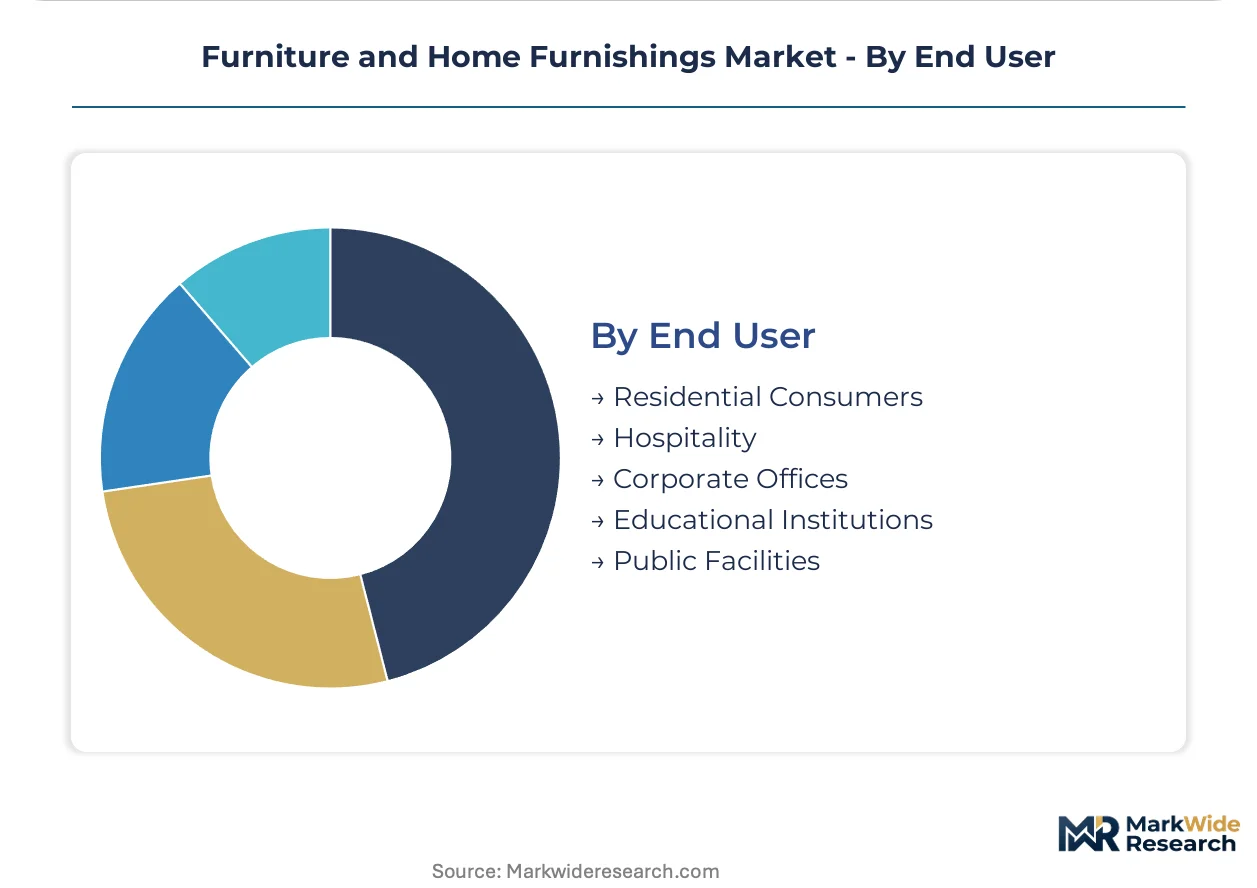
- Residential Consumers:Fragmented demand across direct-to-consumer channels treats furniture as disposable lifestyle accessories. Rental tenure shortening in United States and Chinese cities accelerates turnover velocity.
- Hospitality:ISO 14001 certification and FSC sourcing mandates filter supplier bases for hotel and restaurant fit-outs. Procurement tenders in Germany and United States prioritize traceability documentation.
- Corporate Offices:Ergonomic specification and warranty terms drive vendor consolidation.
- Educational Institutions:Durability testing and bulk pricing dominate selection criteria.
- Public Facilities:Accessibility compliance and vandal resistance shape product architecture.
Residential volume dominates; hospitality procurement is expanding most quickly on renovation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential renovation cycles and housing development permits concentrate demand in the United States, China, and Germany. Regulatory divergence between EPA formaldehyde standards, ECHA REACH restrictions, and local building codes fragments supplier qualification requirements across these markets.
United States
Urban millennial renters in New York, Los Angeles, and Chicago compress furniture replacement cycles to match lease durations. EPA formaldehyde emission standards and California Air Resources Board Phase 2 compliance govern composite wood products, elevating third-party testing costs. Manufacturing clusters in North Carolina and Mississippi face consolidation pressure as certification burdens filter marginal producers from distribution networks.
China
Tier-one city renovation cycles in Shanghai, Beijing, and Shenzhen pull demand for space-efficient furnishings through developer procurement channels. GB standards on indoor air quality and formaldehyde emissions tighten material compliance for wood-based products. The Yangtze River Delta manufacturing belt concentrates flat-pack production capacity serving both domestic and export markets.
Germany
Federal building energy retrofit mandates unlock replacement demand for built-in storage and space-optimized furnishings across residential units in Berlin, Munich, and Hamburg. ECHA REACH restrictions on flame retardants and volatile organic compounds constrain upholstery chemical formulations. The North Rhine-Westphalia industrial corridor hosts specialized textile mills with reformulation capabilities that create qualification barriers for commodity suppliers.
India
Rapid urbanization in Mumbai, Delhi-NCR, and Bangalore expands the addressable market for modular and space-efficient furnishings among middle-class households. BIS certification requirements for furniture safety and material standards are tightening import and domestic manufacturing compliance. The Gujarat industrial cluster is emerging as a production hub for engineered wood products serving domestic retail and hospitality procurement channels.
Japan
Aging residential stock in Tokyo, Osaka, and Nagoya drives renovation demand for ergonomic and accessibility-adapted furnishings. JIS standards on structural safety and chemical emissions govern product compliance. The Aichi Prefecture manufacturing base concentrates precision metalworking and upholstery framing expertise for specification-grade contract furniture.
Furniture and Home Furnishings Market Competitive Landscape
North American producers anchor the mass-market tier; European specialists hold premium positioning through certification depth and design heritage. The vendor base fragments across direct-to-consumer disruptors, legacy retail networks, and contract specification houses. Three archetypes dominate: flat-pack logistics leaders, premium lifestyle merchandisers, and ergonomic workplace specialists. Competitive moves concentrate on digital channel expansion and sustainability credential acquisition.
Among North American-based retailers, Williams-Sonoma Inc. and Herman Miller exemplify divergent positioning strategies. IKEA anchors the mass-market tier through its flat-pack logistics network and cost leadership across particleboard-dependent segments. These three companies represent the spectrum from disposable lifestyle accessories to specification-grade workplace systems, illustrating how channel economics and buyer concentration reshape competitive boundaries.
| Leading Market Players |
|---|
| Williams-Sonoma Inc. |
| Herman Miller |
| IKEA |
| Okamura Corporation |
| HNI Corporation |
| Ashley Furniture Industries |
| Steelcase Inc. |
| RH |
| Wayfair Inc. |
| Others |
Supply & Pricing Matrix
Flat-pack logistics automation and CNC machining integration are compressing production economics while simultaneously concentrating supplier power among certified mills with capital-intensive equipment footprints. This dual transformation elevates procurement barriers for uncertified producers and compresses margin pools at the mid-market tier.
Pricing Analysis
Volume concentrates in particleboard-dependent mass-market segments while margin pools deepen in specification-grade upholstery and certified wood systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost compression in mass-market flat-pack segments is intensifying because logistics automation favors scale players with dedicated distribution networks. Residential renters in tier-one cities exhibit highest price sensitivity; hospitality procurement committees demonstrate lowest sensitivity due to total-cost-of-ownership framing.
Supply Chain Analysis
Certification gating through CARB Phase 2, EPA formaldehyde standards, and FSC chain-of-custody documentation filters supplier bases and elevates qualification costs for composite wood inputs. Manufacturing gravity centers on China, Vietnam, and Poland for flat-pack assembly; North Carolina and Mississippi anchor North American upholstery framing. Raw material dependencies encompass engineered wood substrates, specialty polyurethane foams, and flame-retardant textile formulations. Single-source vulnerability concentrates in Asian textile dyeing and chemical finishing clusters. Distribution runs through direct-to-consumer digital channels for standardized items and specialty retail for premium upholstery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-laminated timber and engineered bamboo composites are displacing traditional particleboard in residential construction-adjacent furniture, creating a technology-transition window where legacy laminating capacity risks stranded asset status.
For Market Incumbents: Cement certification depth as a competitive moat by accelerating FSC chain-of-custody investments and CARB Phase 2 pre-certification for supplier mills. Consolidate procurement relationships with reformulation-capable textile mills in Portugal and Italy before REACH chemical restrictions tighten further. Vertical integration into CNC machining capacity insulates against equipment lead time volatility. For New Entrants and Emerging Players: Capture white-space in climate-adapted outdoor furniture by targeting humidity-resistant material formulations for Southeast Asian and Gulf state markets. Direct-to-consumer digital channels serving modular storage systems offer the most penetrable entry vector due to compressed showroom requirements and flexible return policy normalization. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by flat-pack logistics leaders seeking certified mill capacity. Long-term viability favors suppliers with reformulation capabilities and multi-jurisdiction compliance infrastructure. The signal to watch is divergence between EPA and emerging state-level formaldehyde testing protocols, which would trigger supplier base consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Chain-of-Custody Certification | Hospitality procurement tenders in Germany and the United States now mandate traceable wood sourcing documentation. |
| Direct-to-Consumer Digital Launch | Augmented reality visualization tools reduce return rates for upholstery previously gated by physical showroom requirements. |
| REACH Chemical Reformulation Investment | Flame-retardant and VOC constraint compliance creates qualification barriers for commodity European textile suppliers. |
| Modular Manufacturing Scale-Up | CNC machining and flat-pack logistics compress last-mile delivery costs for urban residential square-footage optimization. |
| Certified Mill Backward Integration | Pre-certified composite wood capacity insulates against CARB Phase 2 and EPA emission testing cost escalation. |
Research Methodology
Independent corroboration across primary interviews with furniture manufacturing executives, sustainability compliance officers, hospitality procurement directors, and flat-pack logistics operators underwrites the qualitative findings. Secondary validation draws from EPA emission standard filings, CARB certification databases, FSC chain-of-custody registries, and customs trade data for engineered wood substrate flows. Bottom-up demand modeling triangulates against top-down market sizing across product type, material specification, distribution channel, and end-user segments.
Comparable-period anchoring to historical renovation cycle data and housing permit issuance patterns establishes baseline demand elasticity coefficients across the projection horizon. Segmentation dimensions encompass product architecture, material compliance tier, channel economics, and procurement sophistication level. CAGRs derive from regression analysis against macroeconomic drivers and regulatory implementation timelines. Forecast inputs incorporate replacement frequency compression among urban renters and developer procurement channel pull-through in tier-one city construction cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to multi-jurisdiction regulatory divergence and climate-adapted material durability breakthroughs. Forecasts reflect documented assumptions regarding housing development permit trajectories and REACH chemical restriction implementation pacing. A model refresh is warranted upon material change in EPA formaldehyde standard enforcement intensity or California Air Resources Board Phase 2 threshold revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
Rental Furniture Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
Japan Office Furniture Market
Office Furniture
Standing Desk Market
Office Furniture
Office Furniture Edgebands Market
Office Furniture
Canada Office Furniture Market
Office Furniture
United States Home Office Furniture Market
Office Furniture
Russia Office Furniture Market
Office Furniture
Luxury Office Furniture Market
Office Furniture
US Office Furniture Market
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
Home Office Desk Market
Office Furniture
Home Office Furniture Market
Office Furniture
South Korea Office Furniture Market