
 Study Carrels Market | 2026-2036
Study Carrels Market Size, Share, and Industry Trends Forecast 2026-2036
Study Carrels Market Analytics
University procurement departments are gaining share against traditional library buyers as the Study Carrels Market is bifurcating toward collaborative and technology-integrated workspaces. Steelcase leverages its ergonomic design leadership to anchor premium contracts with research institutions. Herman Miller competes through modular system architecture that sustains reconfiguration demand across campus renovations. Haworth specializes in acoustic performance integration, differentiating its offerings in open-plan study environments.
Study carrels are self-contained, partitioned workstations engineered for individual concentration in educational and research settings, typically incorporating worksurfaces between 24 and 36 inches deep with integrated cable management and task lighting. Modular carrels command the widest specification range, while fixed carrels retain dominance in budget-constrained public library installations. Laminated engineered wood absorbs the largest material share due to cost efficiency and surface durability, though metal frames are gaining traction in high-traffic university corridors for vandal resistance. The end-user base tilts toward universities, where enrollment growth and learning space redesigns drive replacement cycles faster than K-12 or municipal library budgets permit.
EPA formaldehyde emission standards under TSCA Title VI and California Air Resources Board Phase 2 requirements constrain panel and substrate sourcing for manufacturers serving North American contracts. The EU Ecolabel and FSC chain-of-custody certification function as de facto market access filters for European public procurement tenders. BIFMA level and GREENGUARD Gold protocols increasingly appear in RFP specifications, pressuring mid-tier suppliers to upgrade testing and documentation capabilities. Stakeholders must monitor how evolving indoor air quality mandates and extended producer responsibility frameworks reshape material specification authority between manufacturers and institutional purchasing consortia.
Market Dynamics
University procurement departments are consolidating specification authority away from traditional library buyers, compressing vendor lists and elevating ergonomic certification requirements as gatekeeping criteria for contract eligibility.
Growth Catalysts
- EU Green Deal procurement mandates:Public tenders across Germany, France, and the United Kingdom now embed ECHA REACH compliance and EU Ecolabel criteria as mandatory evaluation weights, redirecting institutional budgets toward certified manufacturers.
- Ergonomic design integration:Research institutions specify adjustable worksurfaces and task-optimized lighting as standard features, accelerating replacement cycles for fixed-height legacy installations in high-traffic corridors.
- Learning space redesigns:Enrollment growth at research-intensive universities in North America and Western Europe drives faster furniture refresh schedules than municipal library budgets permit.
Market Restraints
- Engineered wood panel cost volatility:Laminated substrate prices fluctuate with resin and timber feedstock markets, squeezing margin stability for mid-tier suppliers dependent on volume contracts.
- Formaldehyde emission compliance friction:EPA TSCA Title VI and California Air Resources Board Phase 2 testing requirements extend qualification timelines for new panel sources, delaying product launches.
- Fixed carrel substitution pressure:Budget-constrained public libraries retain legacy installations rather than upgrading to modular systems, capping premium product penetration in the municipal segment.
Strategic Opportunities
- Acoustic performance specialization:Open-plan study environments at urban campuses create specification demand for sound-dampening panel integration, rewarding vendors with dedicated acoustic engineering capabilities.
- FSC chain-of-custody certification:European public procurement tenders treat forest stewardship documentation as a de facto market access filter, advantaging suppliers with verified sustainable sourcing.
- Technology-integrated workstations:Cable management and power distribution systems converge with furniture architecture, opening specification pathways for electrical integration partnerships.
Industry Challenges
- GREENGUARD Gold documentation burden:Indoor air quality certification timelines strain mid-tier supplier testing budgets, forcing resource allocation trade-offs between product development and compliance overhead.
- Modular-to-legacy integration complexity:Campus renovation projects require aesthetic and functional compatibility between new flexible systems and existing fixed installations, complicating phased rollout execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Study Carrels Market |
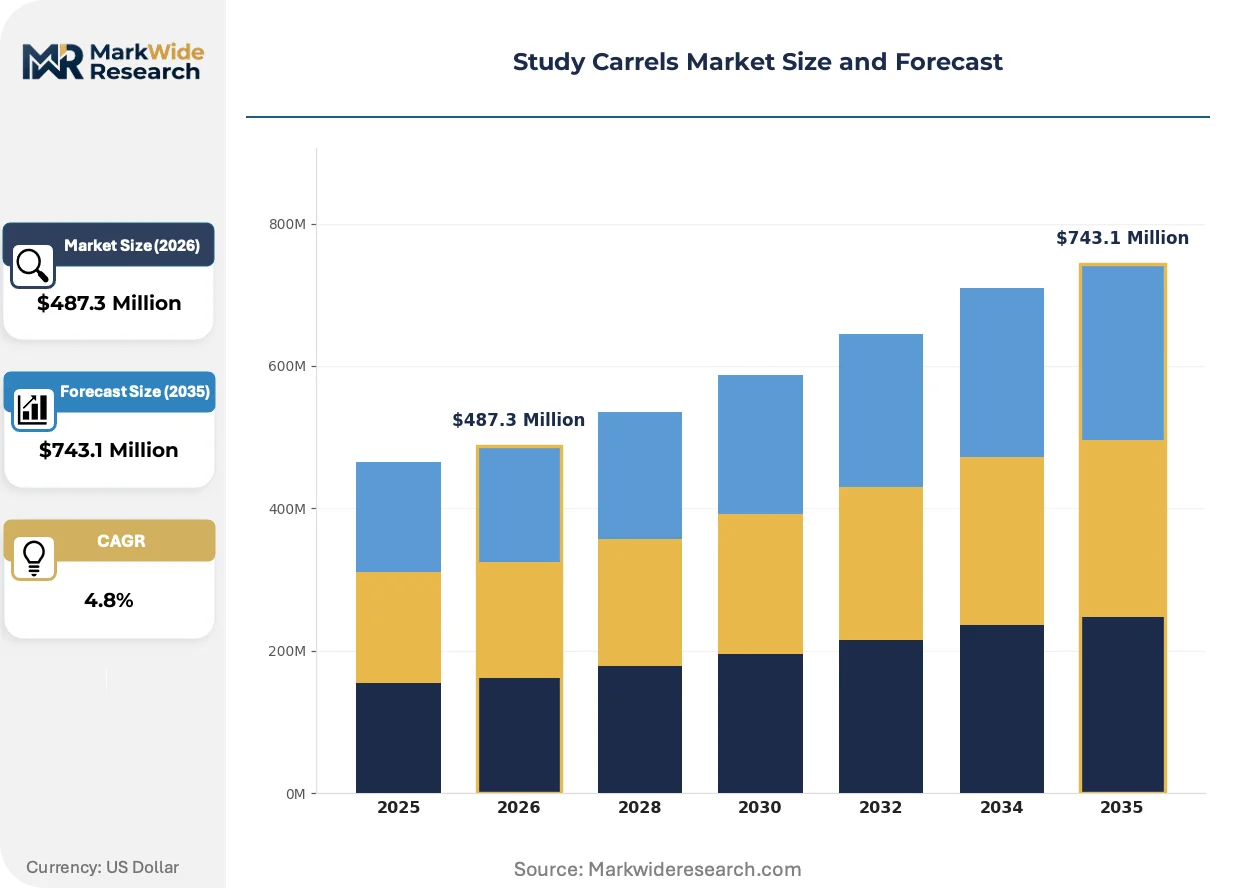
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Carrels, Fixed Carrels, Portable Carrels, Cubicle Carrels Material: Wood, Metal, Laminated Engineered Wood, Plastic End User: Schools, Libraries, Universities, Study Centers Design: Traditional, Modern, Ergonomic, Collaborative |
| Companies Covered | WB Mfg., KI, Minncor Industries, Palmieri Furniture, Versteel, Steelcase, Herman Miller, Haworth, Agati Furniture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Study Carrels Market Evolving Landscape
Material science advances and procurement digitization are restructuring how study carrel specifications translate into contract awards, with sustainability verification and acoustic engineering emerging as decisive competitive differentiators.
Metal frame construction is displacing traditional laminated engineered wood in high-traffic university corridors, where vandal resistance and extended service life justify premium first-cost outlays. Facilities managers at research-intensive institutions specify powder-coated steel substructures for durability-critical deployments. This material shift is compressing the addressable market for conventional wood-dominant suppliers without metal fabrication capabilities.
EU Ecolabel and FSC chain-of-custody requirements are tightening material sourcing transparency obligations for furniture manufacturers serving European public procurement. Tender evaluation matrices now weight environmental certification scores above unit pricing in aggregated purchasing consortia. German and French university systems have advanced fastest in embedding these criteria into binding technical specifications.
Collaborative workspace demand is fragmenting the traditional individual-study carrel specification model, with procurement committees requesting reconfigurable benching systems that accommodate both solo concentration and small-group interaction. Campus planners in the United Kingdom and the United States specify modular panel heights and movable privacy screens to enable rapid space reconfiguration. This behavioral pivot rewards vendors with agile manufacturing systems capable of mixed-configuration batch production.
Study Carrels Market Segmentation
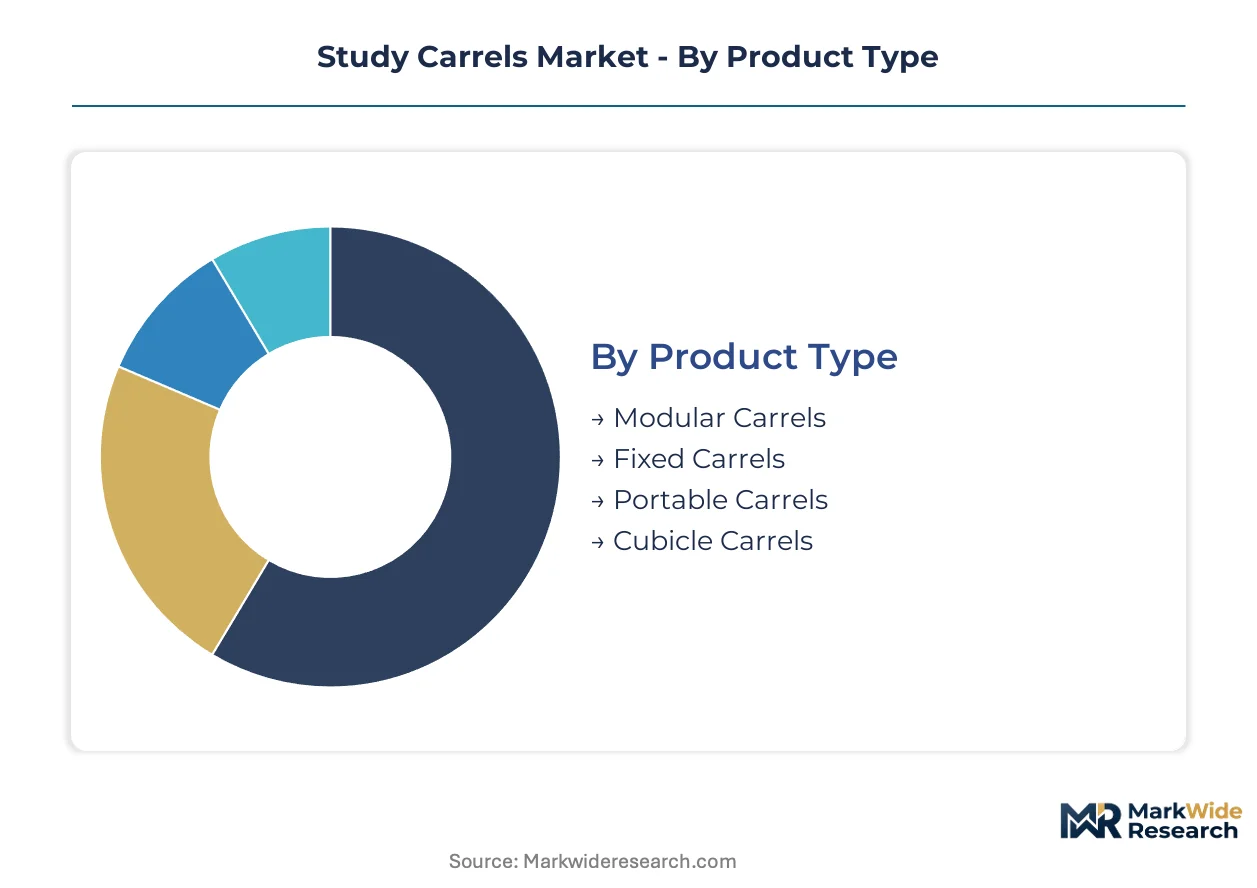
Segmentation in the study carrels market reveals how procurement priorities diverge across institutional budgets, durability requirements, and pedagogical models. Understanding these fault lines enables suppliers to align manufacturing investments with contract-winning specifications.
Product Type:
Margin pools concentrate in systems that balance reconfiguration flexibility with installation permanence, rewarding vendors who can serve both renovation and new-build campus projects.
- Modular Carrels:Panel-based systems with interchangeable worksurfaces and privacy screens enable rapid space reconfiguration. Research-intensive universities in Germany and the United Kingdom specify these for mixed-use learning commons where solo concentration and small-group interaction must coexist within hourly cycles.
- Fixed Carrels:Permanently anchored installations with integrated storage and cable management dominate budget-constrained municipal libraries. Public procurement departments in France retain these for cost predictability despite limited adaptability to evolving study behaviors.
- Portable Carrels:Lightweight, freestanding units with casters serve temporary examination halls and event-based study spaces. Facility managers at UK universities deploy these for enrollment surge accommodation.
- Cubicle Carrels:High-panel enclosures with acoustic dampening address open-plan noise complaints. Urban campuses in London and Paris specify these for graduate research zones.
The dominant share belongs to Modular Carrels, while Cubicle Carrels are gaining share fastest as acoustic engineering becomes a procurement priority.
Material:
Cost tier positioning separates premium metal fabrication from volume-engineered wood production, with certification requirements increasingly dictating sourcing decisions.
- Laminated Engineered Wood:Particleboard or MDF cores with thermally fused melamine surfaces deliver cost efficiency and surface durability. This material absorbs the largest specification volume across European university systems where EU Ecolabel compliance functions as a tender gatekeeper.
- Metal:Powder-coated steel substructures and frames provide vandal resistance and extended service life. High-traffic corridors at North American research universities specify these despite premium first-cost outlays.
- Wood:Solid hardwood or veneer-core panels serve heritage library renovations where aesthetic continuity with existing furniture matters. Limited specification volume reflects cost and maintenance constraints.
- Plastic:Injection-molded polymer shells offer moisture resistance and color customization. K-12 installations in humid climates specify these for durability against student wear.
Laminated Engineered Wood holds the largest installed base, though Metal is expanding most quickly as facilities managers prioritize lifecycle cost over acquisition price.
End User:
Volume concentration tilts toward institutions with dedicated capital refresh cycles and procurement consolidation authority.
- Universities:Research-intensive institutions with enrollment growth and learning space redesign mandates drive replacement cycles faster than other segments. Procurement departments at German and UK universities consolidate specification authority and compress vendor lists.
- Libraries:Municipal and county systems operate on extended depreciation schedules, capping premium product penetration. Budget constraints favor repair-over-replace strategies for legacy fixed installations.
- Schools:K-12 districts specify durable, low-maintenance configurations with scaled dimensions for younger students. Volume procurement through regional cooperatives dominates acquisition patterns.
- Study Centers:Private and corporate learning facilities demand technology-integrated workstations with sophisticated cable management. Smaller addressable market reflects narrower institutional type.
Universities command the dominant procurement volume, while Study Centers are climbing the fastest as corporate learning investments expand.
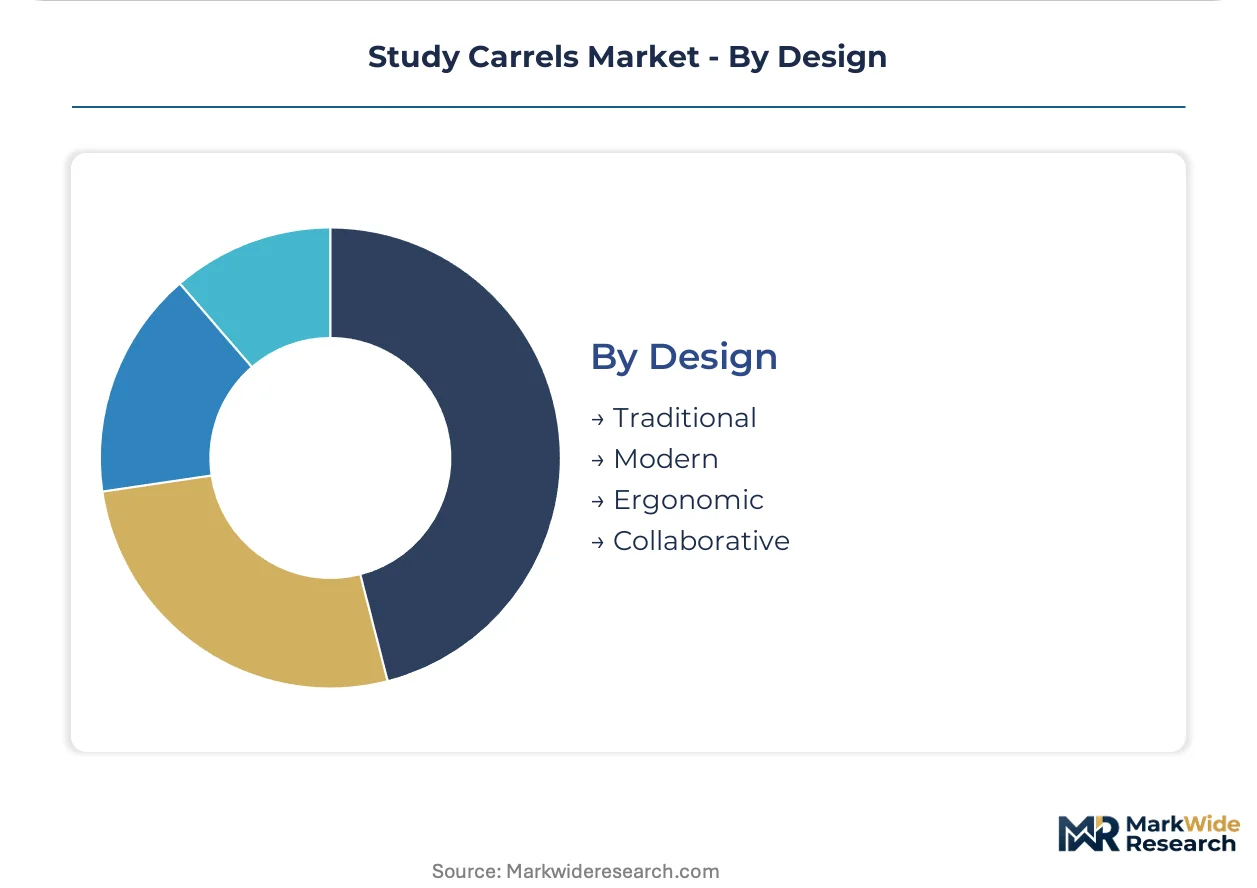
Design:
Application context determines whether aesthetic traditionalism or functional ergonomics wins specification, with procurement committees increasingly weighting health and wellness criteria.
- Ergonomic:Adjustable worksurfaces, task-optimized lighting, and monitor arm compatibility address occupational health mandates. North American universities specify these to reduce repetitive strain liability exposure.
- Collaborative:Reconfigurable benching with movable privacy screens accommodates both individual and group study modes. Campus planners in the United States and United Kingdom favor these for space utilization efficiency.
- Traditional:Fixed-height enclosed carrels with built-in shelving serve archival research and legal document review. Law libraries and special collections maintain specification for distraction elimination.
- Modern:Minimalist open-plan workstations with clean lines and neutral palettes align with contemporary architectural standards. New-build academic facilities specify these for visual coherence with atrium and common area designs.
Ergonomic designs hold the leading specification share, though Collaborative configurations are advancing most rapidly as pedagogical models shift toward active learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput connects German manufacturers to North American university procurement channels, anchoring Europe's export capacity for institutional furniture. This logistics infrastructure underwrites cross-Atlantic contract fulfillment timelines that rival domestic North American suppliers.
United States
Research-intensive universities in Massachusetts and California drive specification demand for ergonomic, technology-integrated workstations. EPA TSCA Title VI formaldehyde emission standards constrain panel sourcing for manufacturers serving federal procurement contracts. The Boston-Cambridge corridor concentrates graduate research facility investments where Steelcase and Herman Miller anchor premium specification positions.
Germany
Technical universities in Bavaria and Baden-Württemberg prioritize modular reconfiguration capabilities for mixed-use learning commons. EU Green Deal procurement mandates embed ECHA REACH compliance as mandatory tender evaluation weights. The Stuttgart-Munich industrial corridor hosts metal fabrication clusters supplying powder-coated steel substructures for high-traffic corridor installations.
United Kingdom
Russell Group universities in London and Manchester consolidate vendor lists around acoustic performance specifications for open-plan graduate research zones. UK public procurement regulations align with EU Ecolabel criteria despite post-Brexit divergence. The Greater London Authority's university estate modernization program channels capital refresh budgets toward collaborative workspace configurations.
France
Grandes écoles and research universities in Île-de-France specify fixed-height legacy installations for cost predictability in municipal library systems. ECHA REACH substance restrictions limit adhesive and coating formulations for panel manufacturers. The Paris-Saclay research cluster drives replacement cycles faster than provincial university budgets permit.
Canada
Provincial university systems in Ontario and Quebec prioritize FSC chain-of-custody certification for public tender eligibility. Health Canada indoor air quality guidelines parallel EPA formaldehyde standards, creating cross-border regulatory alignment. The Toronto-Waterloo corridor concentrates EdTech procurement consortia that aggregate demand across multiple institutional buyers.
Study Carrels Market Competitive Landscape
Concentration sits with diversified furniture conglomerates that leverage ergonomic certification and modular system architecture to compress vendor lists at research-intensive universities. Mid-tier regional fabricators compete on lead-time flexibility for municipal library budgets with extended depreciation schedules. Two strategic archetypes dominate: premium ergonomic specialists commanding specification authority through BIFMA level certification, and volume-engineered wood producers competing on unit cost for public procurement tenders. Competitive moves center on acoustic engineering capability acquisition and FSC chain-of-custody certification investment to unlock European public tender access.
Among North American-based diversified manufacturers, Steelcase, Herman Miller, and Haworth occupy positions that exemplify distinct competitive vectors within the premium tier. Steelcase represents ergonomic design leadership anchoring research institution contracts. Herman Miller exemplifies modular system architecture that sustains reconfiguration demand across campus renovation cycles. Haworth sits within acoustic performance specialization, differentiating offerings for open-plan study environments where sound dampening determines specification outcomes.
| Leading Market Players |
|---|
| WB Mfg. |
| KI |
| Minncor Industries |
| Palmieri Furniture |
| Versteel |
| Steelcase |
| Herman Miller |
| Haworth |
| Agati Furniture |
| Others |
Value Network & Pricing Analysis
Scale economies in powder-coated steel fabrication anchor supply concentration among German and North American metalworking clusters, compressing price floors for engineered wood alternatives while elevating premium tiers for vandal-resistant corridor installations. This capacity utilization dynamic funnels procurement volume toward integrated manufacturers with captive metal forming capabilities, squeezing mid-tier panel suppliers on margin stability.
Pricing Analysis
Volume-discount tiering structures separate premium ergonomic configurations with BIFMA level certification from standard modular systems and economy fixed-height installations. Price differentiation hinges on certification grade and customization depth, with GREENGUARD Gold documentation adding qualification overhead. Cost compression in the economy tier intensifies as resin and timber feedstock volatility squeezes laminated engineered wood margins. Municipal library procurement departments exhibit highest price sensitivity, while research-intensive universities prioritize lifecycle cost and acoustic performance over unit acquisition price.
Supply Chain Analysis
Baltic Sea container routing through the Port of Hamburg underwrites European manufacturers' access to North American university procurement channels. Panel substrate sourcing draws from German engineered wood clusters and North American timber processing regions, with powder-coated steel substructures feeding from Stuttgart-Munich fabrication corridors. Single-source vulnerability concentrates in formaldehyde-compliant resin formulations meeting EPA TSCA Title VI and California Air Resources Board Phase 2 requirements. Distribution runs through institutional purchasing consortia and direct university procurement departments, compressing traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation and reconfiguration services represent a faster-expanding recurring revenue layer than hardware sales, as campus renovation cycles demand ongoing space adaptation support. This service-attach dynamic repositions vendor relationships from transactional procurement to multi-year facilities partnerships.
For Market Incumbents: Compound specification authority through ergonomic certification depth and acoustic engineering capability acquisition. Defend against metal-frame substitution pressure by anchoring premium contracts with FSC chain-of-custody documentation that satisfies EU Ecolabel procurement mandates. Vertical integration into powder-coated steel fabrication secures margin control for high-traffic corridor deployments.
For New Entrants and Emerging Players: Aftermarket acoustic retrofit kits for legacy fixed installations represent an underserved service layer where incumbents under-serve municipal library budgets. Target budget-constrained public library systems in France and provincial North American markets with repair-over-replace value propositions. Pursue direct contracting with university procurement consortia rather than dealer channel dependence to bypass incumbent list compression.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with hybrid material capabilities spanning engineered wood and metal fabrication. Five-to-ten year viability hinges on indoor air quality certification infrastructure and European public tender access. Watch for EU Green Deal procurement mandate expansion beyond Germany, France, and the United Kingdom as the inflection signal for accelerated specification authority consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Acoustic Engineering Capability Acquisition | Sound-dampening panel integration commands premium specification in open-plan graduate research zones at urban campuses. |
| FSC Chain-of-Custody Certification Investment | Verified sustainable sourcing unlocks European public procurement tender access under EU Ecolabel evaluation matrices. |
| Metal Fabrication Capacity Addition | Powder-coated steel substructure production captures high-traffic corridor demand with extended lifecycle value propositions. |
| Technology-Integration Partnership Development | Cable management and power distribution convergence with furniture architecture opens electrical specification pathways. |
| Service-Layer Expansion | Installation and reconfiguration services transform transactional hardware sales into multi-year campus facilities partnerships. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, institutional procurement databases, and manufacturer certification registries to anchor volume and value estimates. Primary interviews engaged university procurement directors, facilities managers at research-intensive institutions, library system administrators, and furniture manufacturer product development leads. Secondary sources incorporated BIFMA compliance documentation, EPA TSCA Title VI certification listings, EU Ecolabel product registries, and trade flow data through the Port of Hamburg. Bottom-up triangulation across end-user segmentation and top-down validation against aggregate institutional capital expenditure patterns ensured estimate robustness.
Segmentation dimensions modeled span product type, material composition, end-user institution category, and design configuration across the projection horizon. Analytical frameworks derived CAGRs from enrollment growth trajectories, learning space redesign investment cycles, and replacement rate differentials between university and municipal library budgets. Industry-specific forecast inputs incorporated EU Green Deal procurement mandate implementation timelines and indoor air quality regulatory evolution patterns.
Forecasts assume regulatory continuity in EPA TSCA Title VI, California Air Resources Board Phase 2, and ECHA REACH substance restriction regimes; material policy shifts would require re-modeling qualification timelines and panel sourcing economics. Practitioners should keep alternative scenarios live as EU Ecolabel criteria expansion and extended producer responsibility framework adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
India Furniture Market
Furniture
United Kingdom Home Furniture Market
Furniture
Laminated Door Market
Furniture
Recliner Chair Market
Furniture
Europe Multifunctional Furniture Market
Furniture
Salon Chairs Market
Furniture
Global Furniture Fittings Market
Furniture
Vietnam Home Furniture Market
Furniture
Luxury RTA (Ready-To-Assemble) Furniture Market
Furniture
Rattan Furniture Market
Furniture
Pool Tables Market
Furniture
Armchairs with Footrest Market
Furniture
Russia Home Furniture Market
Furniture
Europe Upholstered Furniture Market
Furniture
USA and Canada Teak Veneer Sheet Market
Furniture
Furniture and Home Furnishing Store Market