
 Chair Hardware Market | 2026-2036
Chair Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Chair Hardware Market Insights
Market Context
Skilled tool-and-die labor availability is rotating toward Southeast Asian manufacturing hubs, constraining European output timelines while unlocking capacity in Vietnam and Indonesia. Hettich leverages its German engineering heritage to sustain premium positioning in soft-close hinge systems. Blum Inc anchors North American distribution through dedicated cabinetry and furniture supply channels. King Slide Works Co. Ltd dominates ball-bearing slide production at scale for Asia-Pacific OEM contracts.
Technical Definition and Segment Structure
Chair hardware encompasses the mechanical and structural components—casters, hinges, fasteners, armrests, and support mechanisms—that enable mobility, adjustability, and load-bearing function in seating products, typically manufactured through zinc die-casting, injection molding, or cold-forming processes to meet ANSI/BIFMA durability standards. Metal casters and hinges command the largest share of material value given steel and aluminum input costs, though plastic injection-molded armrests are gaining ground in ergonomic and gaming chair configurations where weight reduction and color customization matter. The hospitality end-user segment remains mature with replacement-driven demand, while ergonomic seating applications extract premium pricing through certified lumbar mechanisms and synchronized tilt hardware.
Regulatory Environment
REACH in Europe restricts heavy metal content in plated finishes and mandates substance-of-very-high-concern disclosure across the supply chain, directly elevating compliance costs for metal hardware suppliers serving EU furniture manufacturers. The EPA oversees VOC emissions from coating and finishing operations in the United States, pushing producers toward water-based alternatives or captive abatement investments. BIFMA certification and ISO 21015 durability testing function as de facto market access requirements for commercial office furniture channels, filtering out uncertified component vendors. Stakeholders must monitor how evolving extended producer responsibility frameworks in the EU and California reshape end-of-life obligations for metal and plastic hardware recovery.
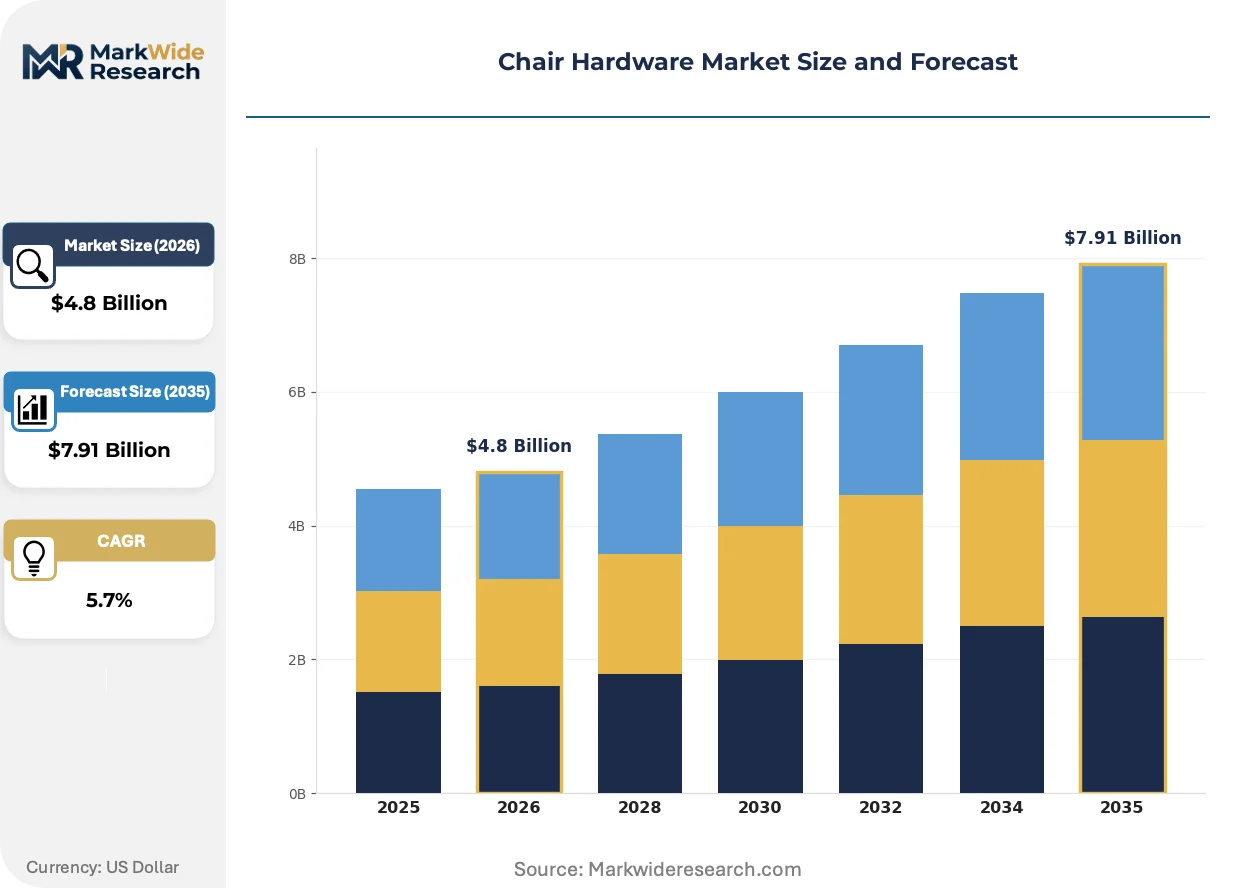
Market Dynamics
Ergonomic certification mandates from BIFMA and synchronized tilt mechanism patents are compressing supplier margins while elevating technical barriers to entry in commercial seating channels.
Growth Catalysts
- REACH substance disclosure:European ECHA mandates on SVHC reporting are filtering out non-compliant Asian metal finishers, consolidating EU-bound volume among certified suppliers.
- Gaming chair configuration:RGB-integrated armrests and 4D adjustable mechanisms are pulling injection-molded component demand from esports furniture assemblers in Guangdong and Taichung.
- Workplace wellness programs:Corporate procurement of ANSI-certified lumbar hardware is accelerating replacement cycles in North American and German office fit-outs.
Market Restraints
- Zinc alloy input volatility:Die-cast caster and hinge producers face margin compression from LME zinc price swings and energy-intensive smelting costs.
- Ball-bearing slide concentration:Taiwan and mainland China control 70%+ of precision slide manufacturing, creating single-source vulnerability for North American OEMs.
- Chrome VI plating substitution:Trivalent chromium and PVD alternatives carry 15-25% cost premiums and reduced wear resistance in high-cycle seating applications.
Strategic Opportunities
- Vietnam manufacturing clusters:Skilled tool-and-die labor migration from Dongguan to Hai Phong is unlocking lower-cost zinc die-casting capacity for EU export.
- Extended producer responsibility:EU WEEE and emerging California frameworks are creating first-mover advantage for hardware vendors with closed-loop metal recovery systems.
- Smart furniture convergence:Integration of pressure sensors and motorized adjustment into chair bases is opening OEM partnerships with IoT actuator suppliers.
Industry Challenges
- Tool-and-die apprenticeship gaps:Germany and Austria face 8-12 month delays in precision mold fabrication due to retiring master craftsmen and insufficient vocational pipeline.
- BIFMA X5.1 certification timelines:14-18 week testing cycles for new tilt mechanisms delay product launches and freeze R&D budgets during validation.
- Legacy ERP integration:Southeast Asian contract manufacturers struggle to synchronize production data with Tier-1 furniture brands' SAP and Oracle procurement portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chair Hardware Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casters, Hinges, Fasteners, Armrests Material: Metal, Plastic, Wood, Upholstery End User: Office Furniture, Residential, Hospitality, Educational Application: Home Use, Commercial Use, Ergonomic Seating, Gaming Chairs |
| Companies Covered | Hettich, Blum Inc, Accuride, DTC, Taiming, Jusen, ADAMS, King Slide Works Co. Ltd, ASSA ABLOY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chair Hardware Market Trends and Innovations
Seating hardware is fragmenting into two performance tiers: precision-engineered mechanisms for certified ergonomic products and commodity components for price-driven mass retail.
Magnetic levitation lumbar support systems are bifurcating the premium seating segment. Herman Miller and Steelcase specification teams have adopted electromagnetic adjustment for flagship task chairs. This technology is compressing traditional spring-and-pawl mechanism volumes into mid-market and entry-level SKUs.
EPA VOC emission rules for coating operations are forcing metal finishers toward water-based pretreatments and powder coating lines. Capital expenditure for compliant facilities runs $2-4 million per plant. California-based furniture assemblers now require supplier documentation of EPA Method 24 compliance before contract award.
Direct procurement from component foundries is displacing distributor-mediated purchasing among large seating OEMs. Haworth and Knoll sourcing teams now negotiate annual zinc die-casting contracts with Dongguan and Ningbo suppliers, bypassing traditional hardware distributors. This pattern is most visible in North American commercial furniture channels where procurement teams have built direct supplier audit capabilities.
Chair Hardware Market Segmentation
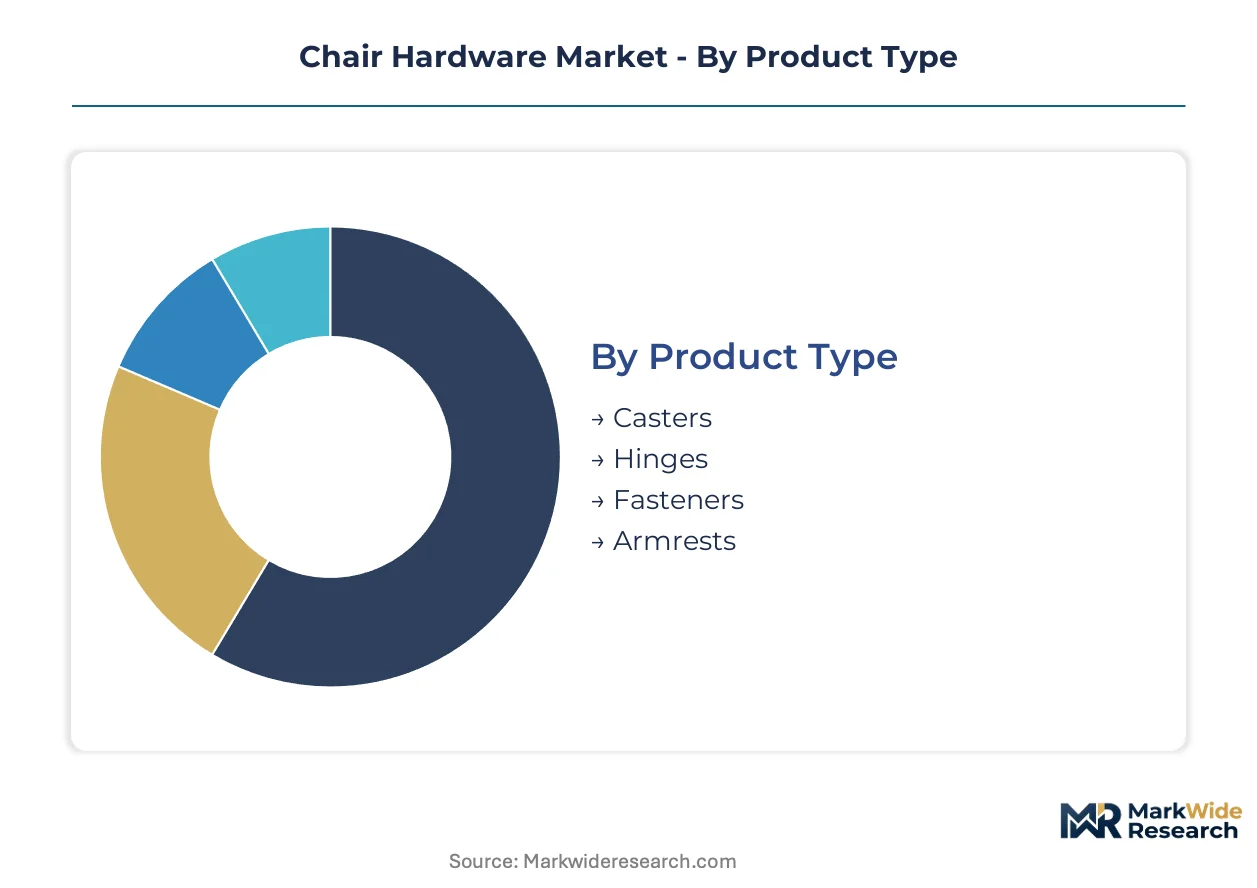
Chair hardware segmentation reveals divergent technical requirements across seating categories. Component specifications vary dramatically between certified ergonomic mechanisms and commodity residential hardware. Understanding these fault lines exposes where substitution threats and margin compression concentrate most intensely.
Product Type:
Casters face the most acute substitution pressure from low-cost pneumatic glide alternatives in residential and hospitality channels, while precision-engineered mechanisms command defensive positioning in certified commercial seating.
- Casters:Zinc die-cast or stamped steel wheel assemblies with ball-bearing or sleeve-bearing swivel mechanisms, typically rated for 75-150 kg dynamic load per ANSI/BIFMA standards. Demand concentrates in Guangdong manufacturing clusters serving North American office furniture OEMs, where REACH-compliant plating specifications filter out uncertified finishers.
- Hinges:Cold-formed steel or brass pivot assemblies enabling backrest recline and seat pan articulation, ranging from simple riveted joints to complex synchronized tilt hardware. German and Austrian tool-and-die shops retain premium positioning for soft-close and free-stop mechanisms specified by Steelcase and Herman Miller engineering teams.
- Fasteners:Grade 8.8 steel bolts, T-nuts, and cam-lock fittings securing frame joints and component attachment points.
- Armrests:Injection-molded polypropylene or polyurethane pads mounted on steel or aluminum support brackets, increasingly integrating 4D adjustment in gaming and ergonomic configurations.
Casters retain volume leadership across all product categories; hinges hold the steepest expansion curve as synchronized tilt mechanisms penetrate mid-market office seating.
Material:
Cost tier stratification separates commodity inputs from performance-grade alloys and engineered polymers, with regulatory compliance costs widening the gap between compliant and non-compliant suppliers.
- Metal:Zinc alloys for die-cast components, cold-rolled steel for stamped brackets, and aluminum extrusions for lightweight bases. REACH SVHC disclosure mandates in Europe elevate compliance costs for chrome-plated finishes, consolidating EU-bound volume among certified plating houses in Taiwan and Vietnam.
- Plastic:Glass-filled nylon for structural brackets, ABS for cosmetic covers, and thermoplastic elastomers for grip surfaces. Taichung injection molders dominate RGB-integrated armrest production for esports furniture assemblers.
- Wood:Hardwood laminates and solid timber components in premium residential and hospitality seating, primarily sourced from sustainable forestry certification programs.
- Upholstery:Fabric, leather, and synthetic covering materials integrated with underlying foam and support hardware in finished seating systems.
Metal maintains revenue dominance through raw material value density; plastic is climbing the fastest as weight reduction and color customization penetrate gaming and ergonomic segments.
End User:
Application maturity varies sharply, with replacement-driven hospitality contrasting against specification-intensive commercial furniture channels where certification gates filter supplier pools.
- Office Furniture:ANSI/BIFMA X5.1-certified task seating, conference chairs, and workstations requiring 10-year durability ratings. Corporate wellness procurement in Germany and the United States accelerates replacement cycles for certified lumbar mechanisms.
- Residential:Mass-market dining, living room, and home office seating prioritizing cost efficiency over technical performance. Dongguan contract manufacturers supply commodity hardware for flat-pack furniture retailers.
- Hospitality:Hotel guest room, restaurant, and event venue seating with replacement cycles driven by renovation schedules rather than functional failure.
- Educational:K-12 and university classroom furniture subject to institutional procurement standards emphasizing durability and vandal resistance.
Office furniture commands the highest value per unit; educational represents the most price-sensitive institutional channel with compressed supplier margins.
Application:
Customer type differentiation separates specification-driven commercial procurement from discretionary consumer purchase, with ergonomic certification creating a distinct premium tier.
- Home Use:Residential seating purchased through retail and e-commerce channels, where aesthetic preference dominates technical specification.
- Commercial Use:Workplace, healthcare, and institutional seating procured through contract furniture dealers with mandatory certification documentation.
- Ergonomic Seating:Certified task chairs with adjustable lumbar support, synchronized tilt, and armrest articulation meeting BIFMA G1 guidelines. Magnetic levitation lumbar systems from Herman Miller and Steelcase specification teams are compressing traditional spring mechanism volumes into lower tiers.
- Gaming Chairs:Esports-oriented seating with 4D armrests, recline locks, and RGB integration, assembled primarily in Guangdong and Taichung for global distribution.
Commercial use retains procurement volume leadership; gaming chairs are expanding most quickly as esports infrastructure investment accelerates component demand from injection molders and actuator suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance from ECHA anchors European procurement specifications, while manufacturing gravity shifts toward Vietnam and Indonesia as tool-and-die labor migrates from legacy Chinese clusters. Demand concentration spans four distinct national markets with divergent regulatory and supply chain configurations.
China
Guangdong and Zhejiang manufacturing clusters supply die-cast zinc components and injection-molded armrests for North American office furniture OEMs. GB standards from SAMR govern domestic product safety, though export-oriented producers prioritize BIFMA certification for US-bound shipments. Dongguan tool-and-die shops face labor attrition as skilled workers relocate to Vietnam.
United States
Corporate wellness procurement accelerates replacement cycles for ANSI-certified lumbar mechanisms in commercial office fit-outs. EPA Method 24 compliance documentation is now mandatory for California-based furniture assemblers awarding hardware contracts. Grand Rapids and High Point furniture manufacturing corridors source directly from Asian foundries, bypassing traditional distributors.
Germany
Ergonomic seating specification teams at Steelcase and Herman Miller European divisions demand synchronized tilt hardware with 10-year durability ratings. REACH SVHC disclosure mandates from ECHA filter supplier pools to certified plating houses. Baden-Württemberg and Bavaria retain premium positioning for soft-close hinge engineering despite apprentice pipeline shortages.
Vietnam
Hai Phong and Ho Chi Minh City manufacturing zones capture zinc die-casting capacity migrating from Dongguan. Skilled mold fabrication labor availability unlocks lower-cost production for EU export markets. The government offers investment incentives for precision metalworking facilities serving furniture component supply chains.
Japan
METI industrial standards emphasize precision engineering for high-cycle seating applications in corporate and healthcare environments. Osaka and Nagoya manufacturing bases specialize in ball-bearing slide systems and precision fasteners. Domestic OEMs maintain strict supplier qualification protocols that favor established component vendors with JIS certification.
Chair Hardware Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where German engineering heritage commands premium positioning against Asian scale manufacturers. The vendor base separates into three strategic archetypes: precision mechanism specialists, high-volume die-casting operators, and integrated slide system producers. Consolidation pressure concentrates among mid-tier zinc alloy fabricators facing REACH compliance cost escalation. Dominant competitive moves include backward integration into captive plating operations and direct procurement contracts with Tier-1 furniture OEMs.
Within the precision mechanism tier, Hettich GmbH and Blum Inc exemplify engineering-led positioning through heritage European tool-and-die capabilities. King Slide Works Co. Ltd occupies the scale-driven vector for ball-bearing slide production serving Asia-Pacific OEM contracts. These three anchors demonstrate how geographic origin and corporate structure map to distinct competitive archetypes in component supply.
| Leading Market Players |
|---|
| Hettich |
| Blum Inc |
| Accuride |
| DTC |
| Taiming |
| Jusen |
| ADAMS |
| King Slide Works Co. Ltd |
| ASSA ABLOY |
| Others |
Pricing and Supply Chain Analysis
REACH SVHC disclosure mandates from ECHA simultaneously gate supplier qualification and stratify price tiers, compressing margins for uncertified Asian finishers while rewarding certified plating houses with premium positioning in EU-bound commercial seating channels.
Pricing Analysis
China-Vietnam spreads of 15-25 percent separate premium synchronized tilt mechanisms from commodity zinc die-cast alternatives. Pricing stratifies across premium, standard, and economy tiers based on BIFMA certification grade and volume scale. Cost compression in mid-market hinges is intensifying because Dongguan labor attrition drives mold fabrication delays. Educational procurement teams exhibit highest price sensitivity; Herman Miller specification engineers show lowest.
Supply Chain Analysis
Taiwan Strait transit underwrites precision ball-bearing slide flows to North American OEMs, creating single-source vulnerability for seating mechanism assemblers. Production gravity centers on China, Vietnam, and Taiwan for die-casting and injection molding. The chain draws from LME zinc ingots, cold-rolled steel strip, and glass-filled nylon pellets. Distribution runs through direct procurement contracts with Tier-1 furniture brands, bypassing traditional hardware distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery as corporate office fit-out budgets rebound from pandemic-era deferrals, with workplace wellness procurement accelerating replacement cycles for certified lumbar mechanisms.
For Market Incumbents: Fortify positioning through captive plating investments in Vietnam to neutralize REACH compliance cost escalation, and deepen direct OEM contracts with Grand Rapids and High Point furniture corridors to lock out distributor-mediated rivals. For New Entrants and Emerging Players: Differentiate on RGB-integrated armrest engineering for Guangdong esports assemblers, targeting the gaming chair segment where specification intensity remains low and 4D adjustment mechanisms command fastest volume growth. For Investors and Strategic Acquirers: Extended producer responsibility frameworks in the EU and California reshape the acquisition landscape toward hardware vendors with closed-loop metal recovery systems. Long-term viability favors mid-scale zinc alloy fabricators with certified plating operations. Watch California SB-54 implementation timelines as inflection signal for circular economy compliance premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Plating Facility Investment | REACH SVHC compliance secures EU market access against uncertified Asian competitors. |
| Direct OEM Contract Negotiation | Bypassing distributors captures margin previously absorbed by hardware intermediaries in North America. |
| Tool-and-Die Apprenticeship Program | Germany and Austria face 8-12 month mold fabrication delays from retiring master craftsmen. |
| Closed-Loop Metal Recovery System | EU WEEE frameworks create first-mover advantage for end-of-life hardware recovery capabilities. |
| Smart Furniture Sensor Integration | Pressure sensor and motorized actuator partnerships open OEM channels with IoT suppliers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, BIFMA certification registries, and ECHA substance-of-concern disclosures. Conversations with furniture OEM procurement directors, zinc alloy foundry operators, tool-and-die shop managers, and contract manufacturer quality leads informed demand-side and supply-side calibration. Bottom-up component volume estimates triangulate against top-down furniture production data from national statistical offices.
Segmentation dimensions modeled include product type, material grade, end-user application, and geographic manufacturing cluster across the analysis window. CAGRs derive from regression analysis of historical shipment data and forward projection of replacement cycle dynamics. Forecast inputs incorporate REACH compliance cost trajectories and workplace wellness procurement penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained corporate real estate investment and stable zinc alloy pricing would require recalibration. Forecasts reflect documented assumptions regarding BIFMA certification adoption and tool-and-die labor migration patterns. Practitioners should keep alternative scenarios live as EU extended producer responsibility enforcement and China-Vietnam labor arbitrage evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Europe Luxury Furniture Market
Furniture
Global Smart Furniture Market
Furniture
India Luxury Furniture Market
Furniture
Contract Furniture and Furnishing Market
Furniture
United States Upholstered Furniture Market
Furniture
GCC Multifunctional Furniture Market
Furniture
Piano Stools Market
Furniture
Chaises Longue Market
Furniture
Europe Wood Decorative Wall Panel Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
Global Folding Furniture Market
Furniture
China Furniture Market
Furniture
Armchairs with Footrest Market
Furniture
Portering Chair Market
Furniture
Vietnam Furniture Market
Furniture
Unfinished Wood Furniture Market