
 Global Free Standing Electrical Height-Adjustable Tables Market | 2026-2036
Global Free Standing Electrical Height-Adjustable Tables Market Size, Share, and Industry Trends Forecast 2026-2036
Global Free Standing Electrical Height-Adjustable Tables Market Foresight
Direct-to-commercial distribution is tilting toward online retailers and office equipment suppliers as procurement teams bypass traditional furniture showrooms. Steelcase Inc. leverages its integrated manufacturing network to control lead times on dual-motor configurations. FlexiSpot competes aggressively through digital-native positioning and configurable checkout workflows. Haworth Inc. anchors its presence via specification relationships with architectural and design firms.
Free standing electrical height-adjustable tables incorporate linear actuators, steel or aluminum telescoping legs, and programmable control boxes that enable motorized surface elevation between seated and standing positions. These units typically support load capacities of 150-350 pounds and operate at noise levels below 50 decibels, serving the primary purpose of reducing sedentary behavior in knowledge-work environments. Dual motor configurations command the largest installed base due to superior stability at full extension, while memory height adjustable variants capture expanding margin pools from premium corporate rollouts. Corporate offices dominate end-user volume, though co-working spaces represent the fastest-growing demand segment as operators retrofit for tenant flexibility.
The EPA and OSHA in the United States, alongside the EU Green Deal and CE marking requirements in Europe, shape product compliance through electromagnetic compatibility testing, material substance restrictions, and energy efficiency benchmarks. Japan's METI enforces standby power regulations that directly influence control box design specifications for export-bound manufacturers. Stakeholders must monitor evolving building certification schemes and procurement mandates that embed ergonomic furniture into lease agreements and workplace standards.
Market Dynamics
Dual-motor configurations with programmable memory presets are compressing replacement cycles as corporate procurement teams embed ergonomic furniture mandates into lease agreements and workplace standards across Germany, Japan, and the United States.
Growth Catalysts
- EU Green Deal procurement mandates:Building certification schemes across European member states now embed adjustable workplace equipment into public sector tender requirements, accelerating specification of electrically actuated sit-stand furniture in government and institutional fit-outs.
- Co-working space retrofit cycles:Flexible workspace operators in Singapore, Australia, and the United Kingdom are replacing static desks with height-adjustable units to differentiate tenant offerings and command premium lease rates.
- Linear actuator efficiency gains:Brushless DC motor architectures with integrated Hall sensors have reduced per-unit power consumption and noise signatures below 45 decibels, expanding deployment into open-plan and library environments previously hostile to motorized furniture.
Market Restraints
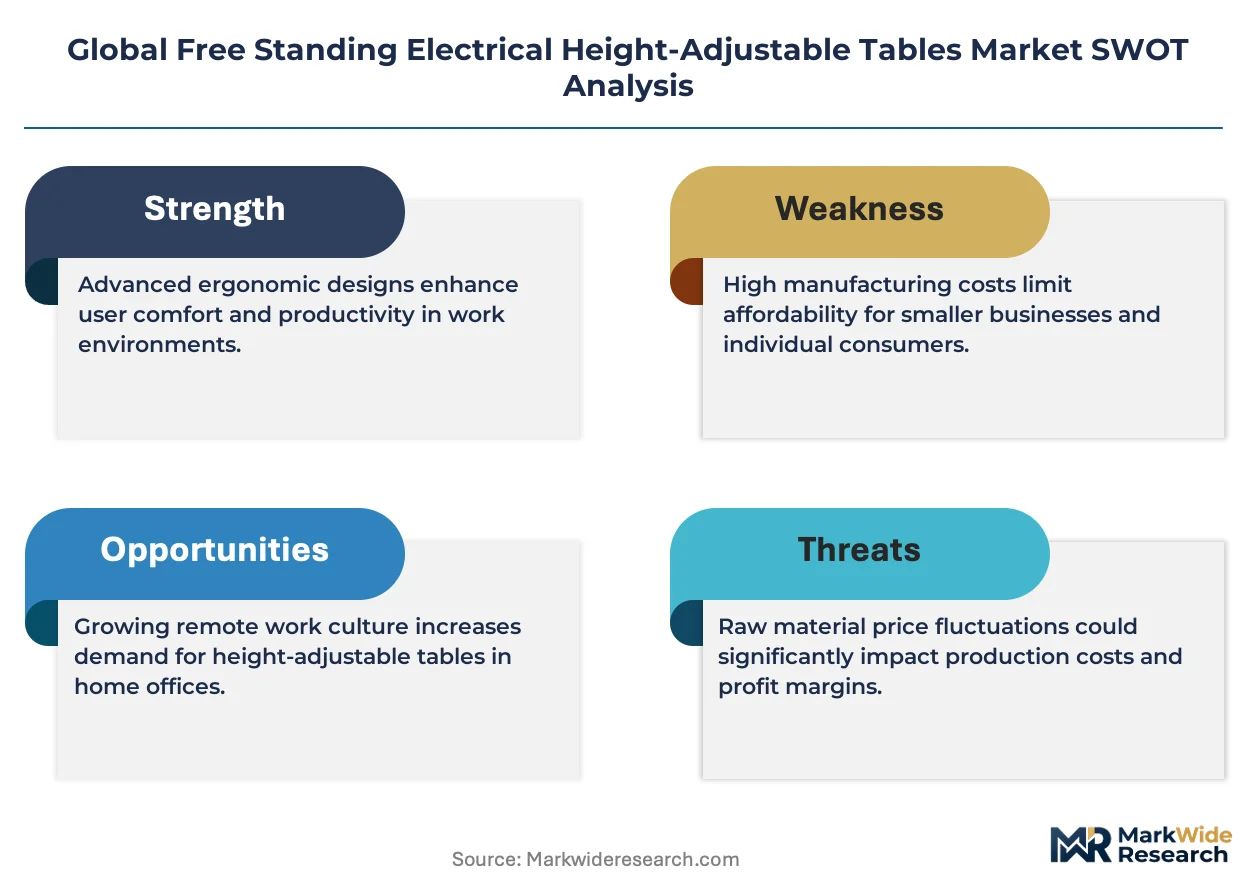
- Steel and aluminum input volatility:Telescoping leg assemblies depend on cold-rolled steel and extruded aluminum pricing that fluctuates with energy-intensive smelting costs, compressing margin stability for manufacturers without captive metalworking capacity.
- Control box supply concentration:Programmable logic modules with electromagnetic compatibility certification cluster among Taiwanese and Chinese electronics suppliers, creating single-source vulnerability for brands lacking backward integration into PCB assembly.
- Manual crank substitute persistence:Budget-conscious educational institutions and municipal purchasers continue specifying hand-crank height-adjustable tables, capping price realization for electrically actuated alternatives in public sector segments.
Strategic Opportunities
- India commercial real estate expansion:Bangalore, Hyderabad, and Mumbai office construction is incorporating smart building infrastructure that accommodates motorized furniture integration, creating first-mover positioning for brands establishing local assembly or distribution partnerships.
- Healthcare administrative workstation conversion:Hospital systems and outpatient clinic networks are recognizing sedentary behavior risks among billing, scheduling, and records staff, opening a vertical adjacent to traditional corporate demand.
- ISO 9241-5 ergonomic certification leverage:Third-party validation of surface height range, stability, and adjustability speed is becoming a procurement filter in Nordic and German enterprise accounts, rewarding investment in testing and documentation.
Industry Challenges
- Embedded firmware cybersecurity:Control boxes with Bluetooth and Wi-Fi connectivity for app-based height programming face emerging scrutiny under NIST IoT guidelines and EU cybersecurity labeling requirements, demanding engineering resources unfamiliar to traditional furniture manufacturers.
- Dual certification timeline compression:Simultaneous pursuit of UL 962B electrical safety and BIFMA G1 ergonomic compliance for North American enterprise accounts extends product development cycles and strains testing laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Free Standing Electrical Height-Adjustable Tables Market |
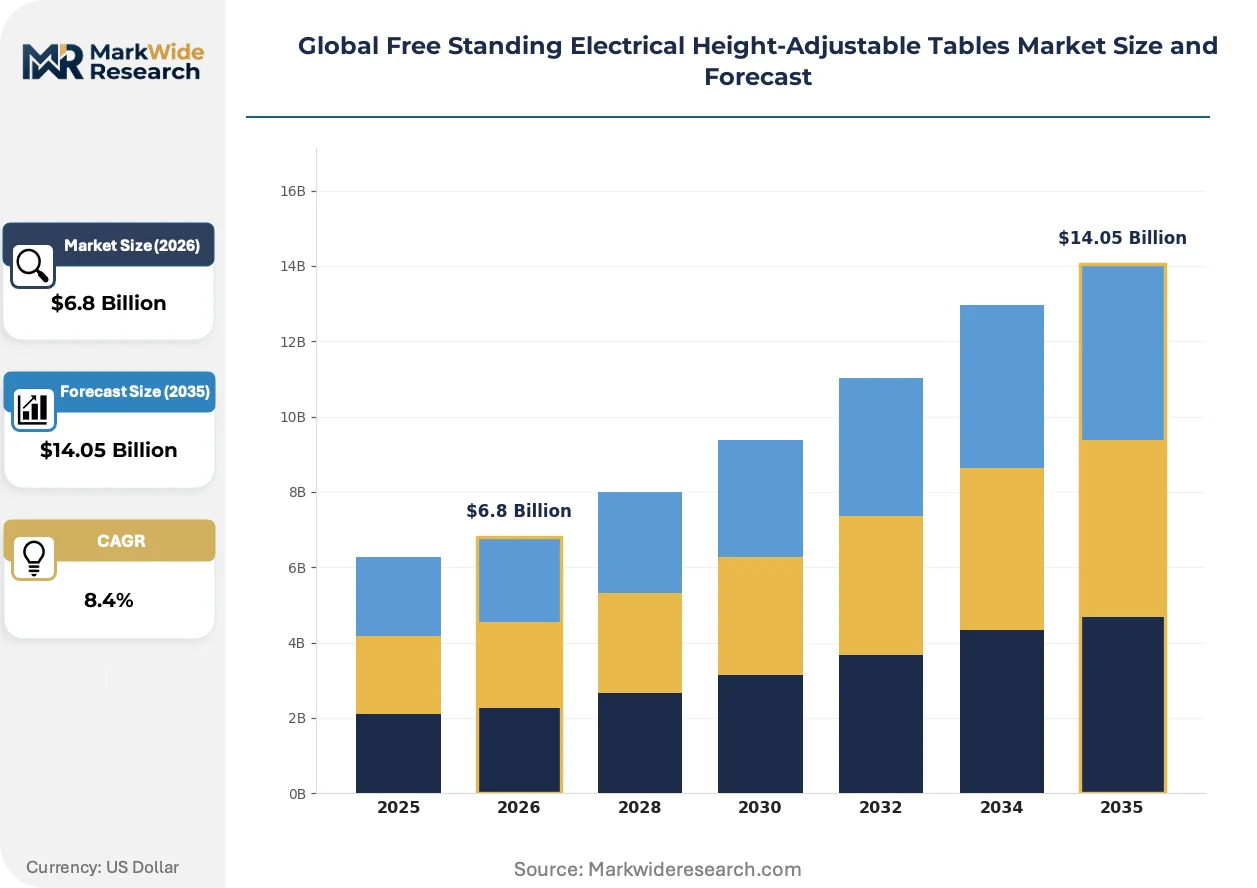
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Motor, Dual Motor, Three Motor, Memory Height Adjustable, Convertible Technology: Electric, Pneumatic, Hydraulic, Manual, Hybrid End User: Corporate Offices, Educational Institutions, Co-working Spaces, Home Offices, Design Studios Distribution Channel: Direct Sales, Online Retailers, Specialty Furniture Stores, Office Equipment Suppliers |
| Companies Covered | Steelcase Inc., Herman Miller, Haworth Inc., Uplift Desk, Vari, FlexiSpot, Global Furniture Group, HNI Corporation, Ergotron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Free Standing Electrical Height-Adjustable Tables Market Shifts & Advancements
Antimicrobial surface coatings, occupancy-sensor integration, and AI-driven usage analytics are converging to reposition height-adjustable tables from passive furniture to active workplace infrastructure nodes.
Capacitive touch controls with OLED height displays and smartphone app pairing are rendering obsolete mechanical push-button interfaces that dominated early-generation electric desks. Fortune 500 headquarters and technology sector fit-outs in Seattle, Austin, and Toronto are specifying these interfaces as baseline requirements. The shift is compressing price premiums for basic motorized units while concentrating margin in software-enabled, data-generating configurations.
Japan's METI standby power regulations have forced redesign of control box power management circuits to achieve sub-0.5-watt idle consumption, directly influencing export-bound product architectures for manufacturers serving multiple jurisdictions. The industrial consequence is modular power supply platforms that satisfy Japanese, EU ErP, and US DOE requirements through firmware rather than hardware variants. European enterprise buyers are capturing the benefit through simplified SKU management and reduced compliance documentation burden.
Enterprise procurement teams now specify furniture-as-a-service arrangements with bundled installation, preventive maintenance, and end-of-life takeback, displacing traditional capital purchase and ownership models. Channel intermediaries including facility management integrators and workplace strategy consultancies are capturing this relationship, particularly in London, Frankfurt, and Sydney financial services deployments. The shift rewards manufacturers with captive service networks and circular logistics capabilities over pure production specialists.
Global Free Standing Electrical Height-Adjustable Tables Market Segmentation
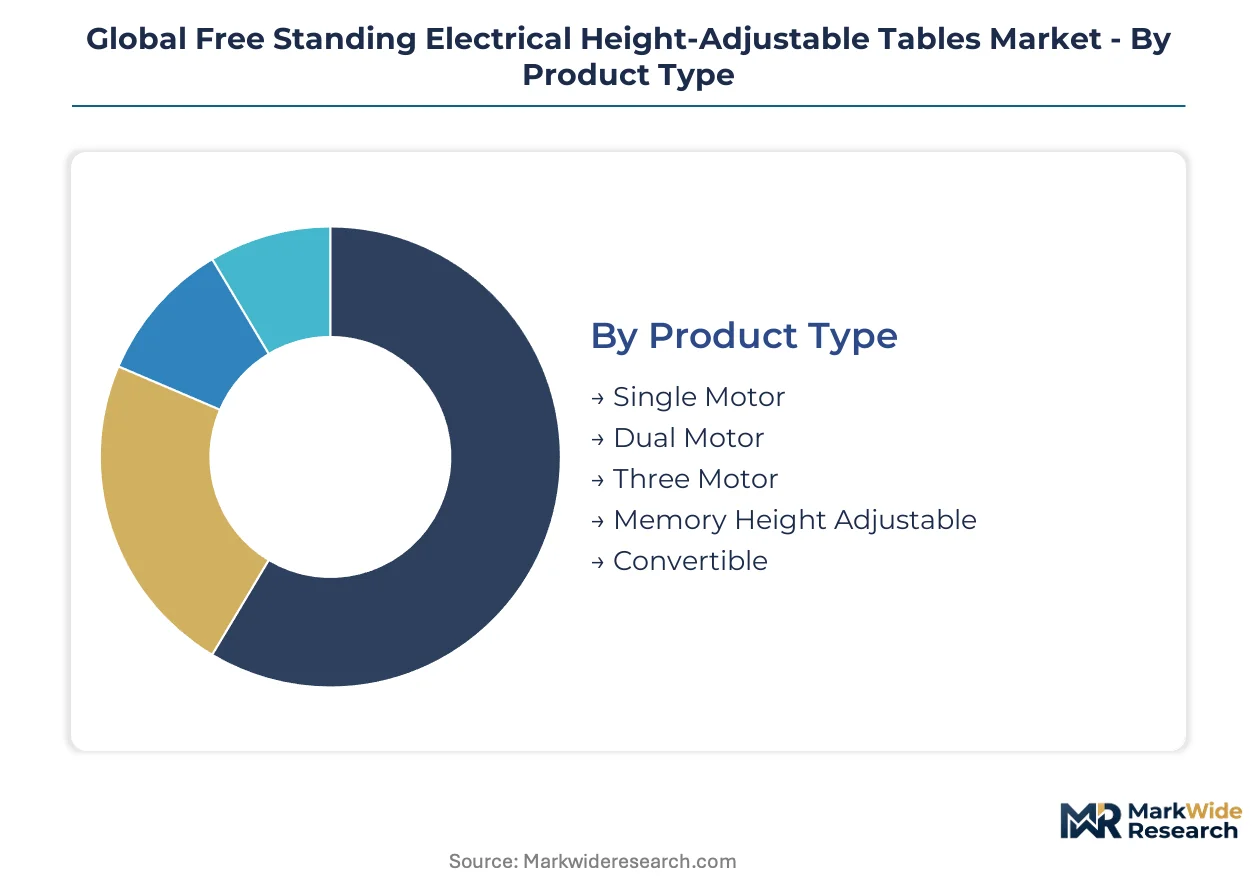
Segmentation in free standing electrical height-adjustable tables reveals divergent service and margin profiles. Motor configuration drives technical complexity and warranty exposure, while distribution channel determines installation support requirements and customer lifetime value capture.
Product Type:
After-sales-service intensity varies sharply across motor configurations, with multi-motor units demanding preventive maintenance programs and control box firmware updates that single-motor alternatives rarely require.
- Dual Motor:Two synchronized linear actuators deliver superior load distribution and wobble-free extension to 48 inches, commanding specification in German automotive headquarters and Seattle technology campuses where stability at standing height is non-negotiable. Preventive maintenance contracts and actuator replacement programs generate recurring revenue streams that offset compressed hardware margins.
- Memory Height Adjustable:Programmable presets with OLED displays and smartphone pairing capture premium positioning in Fortune 500 fit-outs, particularly Austin and Toronto financial services towers where user personalization drives tenant satisfaction metrics. Firmware update cycles and control box replacement logistics create ongoing vendor engagement beyond initial sale.
- Single Motor:Centralized drive mechanisms serve budget-conscious educational and municipal procurement in Japan and the United States with simpler mechanical failure modes and lower service overhead.
- Three Motor:Lateral and vertical actuation combinations address corner workstations and extended surface configurations in London and Frankfurt trading floors.
- Convertible:Modular frames accommodating surface swaps between sitting, standing, and treadmill configurations target wellness-focused Silicon Valley and Copenhagen deployments.
By volume, Single Motor leads. By growth pace, Memory Height Adjustable is ahead.
Technology:
Cost tier stratification separates precision electromechanical systems from compressed-air alternatives, with electric configurations absorbing the majority of corporate specification budgets while pneumatic variants defend position in moisture-prone environments.
- Electric:Brushless DC architectures with Hall sensor feedback dominate specification in OSHA-regulated US corporate environments and EU Green Deal procurement mandates, offering sub-45 decibel operation and programmable height memory. Integrated control boxes with Bluetooth connectivity command hardware premiums that expand with software-enabled analytics subscriptions.
- Pneumatic:Counterbalance systems using compressed gas cylinders serve healthcare administrative stations and laboratory settings across Germany and Japan where electromagnetic interference concerns or washdown requirements exclude electric alternatives.
- Hydraulic:Fluid-power elevation survives in heavy-industry adjacent applications and military procurement with extreme load requirements exceeding 400 pounds.
- Manual:Hand-crank mechanisms persist in Indian educational institutions and Italian municipal purchasing where capital constraints override ergonomic mandates.
- Hybrid:Electric-pneumatic combinations address niche specifications in Australian mining sector remote offices and UAE construction site trailers with unreliable grid power.
Electric configurations absorb the majority of revenue. Pneumatic alternatives are expanding most quickly in healthcare verticals.
End User:
Application context dictates performance specifications, with corporate procurement teams prioritizing aesthetic integration and warranty terms while co-working operators emphasize rapid reconfiguration and theft-resistant controls.
- Corporate Offices:Enterprise fit-outs across Germany, Japan, and the United States specify dual-motor units with 10-year frame warranties and same-day actuator replacement service level agreements, embedding ergonomic furniture mandates into lease agreements and workplace standards.
- Co-working Spaces:Flexible workspace operators in Singapore, Australia, and the United Kingdom retrofit static desks with height-adjustable units to differentiate tenant offerings, prioritizing lockable control interfaces and durable finishes that withstand 3-5 year replacement cycles.
- Educational Institutions:Universities and K-12 districts in India and the United States balance ergonomic guidelines against capital constraints, often specifying manual or single-motor alternatives with extended lead times and minimal service support.
- Home Offices:Remote workers in Canadian and Australian suburbs drive direct-to-consumer volume through online retailers, accepting self-assembly and limited warranty terms for price accessibility.
- Design Studios:Architecture and creative agencies in Milan, Copenhagen, and Brooklyn specify customizable surface materials and frame finishes as brand expression elements.
Corporate Offices generate the largest revenue pool. Co-working Spaces are climbing the fastest as retrofit cycles accelerate.
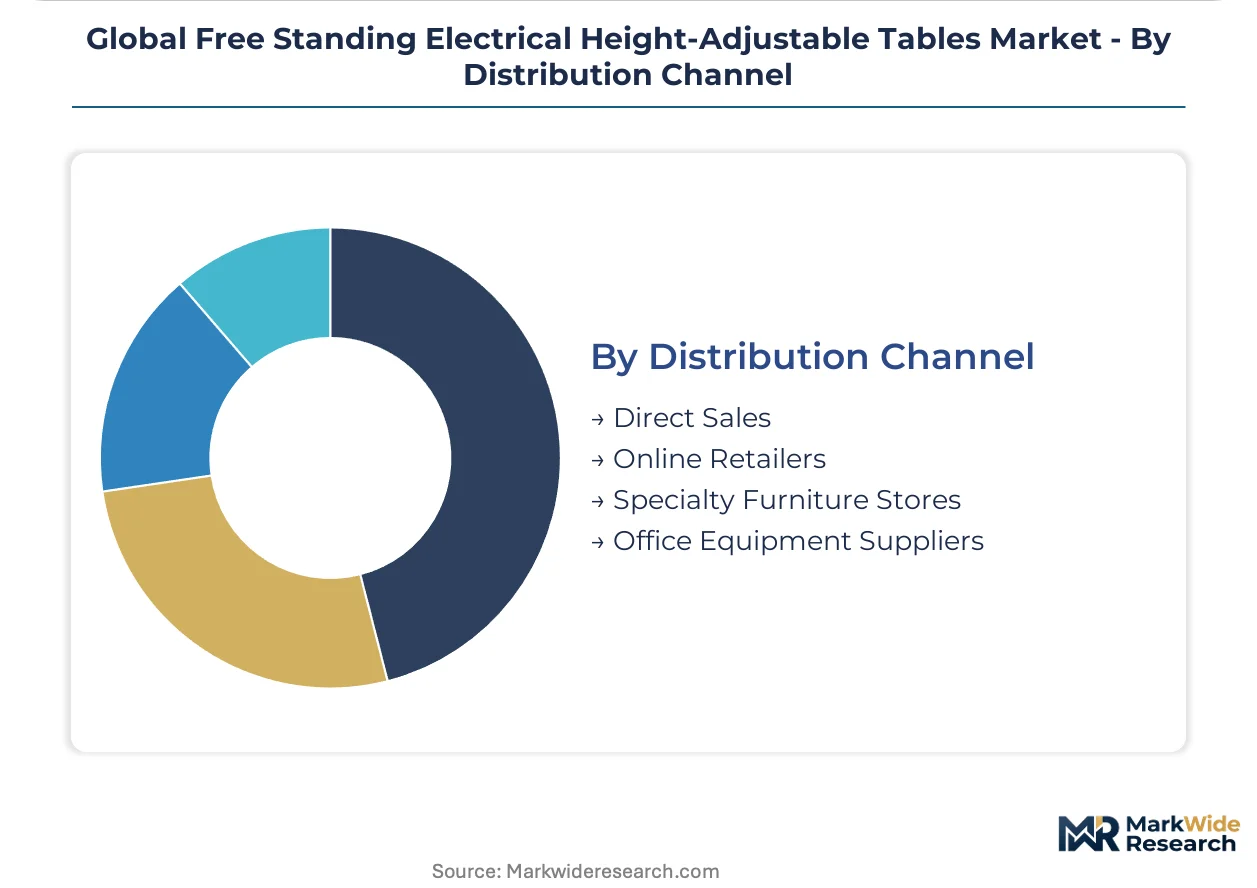
Distribution Channel:
Customer type concentration shapes channel economics, with enterprise procurement teams bypassing traditional showrooms for integrated facility management relationships while residential buyers fragment across digital-native platforms.
- Direct Sales:Manufacturer field teams specification relationships with architectural and design firms in Frankfurt, London, and Sydney financial services deployments, capturing furniture-as-a-service arrangements with bundled installation and preventive maintenance.
- Online Retailers:Digital-native platforms with configurable checkout workflows serve home office buyers and small business purchasers across the United States and Canada, compressing delivery timelines through regional fulfillment center networks.
- Specialty Furniture Stores:Showroom-based consultation retains relevance in Japanese and German markets where tactile evaluation of surface materials and stability testing precedes specification.
- Office Equipment Suppliers:Facility management integrators and workplace strategy consultancies capture enterprise relationship ownership in Nordic and Australian markets, bundling height-adjustable tables with broader workspace transformation contracts.
Direct Sales commands the highest average transaction value. Online Retailers are gaining share fastest in sub-enterprise segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European distribution capacity for electrically actuated furniture, while the Trans-Pacific cable systems connecting Los Angeles to Yokohama enable real-time inventory coordination across the three dominant procurement zones.
United States
Enterprise fit-outs in Seattle, Austin, and Manhattan drive dual-motor specification for technology and financial services headquarters. OSHA workplace ergonomics guidelines and emerging state-level procurement mandates in California and New York embed adjustable furniture into public sector tender requirements. The Pacific Northwest corridor concentrates manufacturing integration with West Asian electronics suppliers.
Germany
Automotive headquarters in Stuttgart and Munich specify stability-certified units with extended warranty terms for engineering workstations. The EU Green Deal procurement directives and national ergonomics standards under the Arbeitsschutzgesetz accelerate replacement of static desks in public administration. The Rhine-Main logistics cluster enables rapid fulfillment across Central European enterprise accounts.
Japan
METI standby power regulations below 0.5 watts force control box redesigns for export-bound manufacturers serving multiple jurisdictions. Corporate procurement in Tokyo and Osaka prioritizes sub-45 decibel operation for open-plan environments. The Kanto manufacturing belt hosts assembly partnerships linking Taiwanese electronics suppliers with domestic furniture fabricators.
Australia
Flexible workspace operators in Sydney and Melbourne retrofit static desks to command premium lease rates in competitive commercial real estate markets. Building certification schemes under the Green Star rating system embed ergonomic furniture into tenant improvement specifications. The Port Botany container terminal supports direct import distribution bypassing traditional wholesale channels.
India
Commercial construction in Bangalore, Hyderabad, and Mumbai incorporates smart building infrastructure accommodating motorized furniture integration. Central Public Works Department guidelines and state-level IT park regulations in Karnataka and Telangana create procurement filters favoring electrically actuated alternatives. The Delhi-Mumbai Industrial Corridor logistics network enables regional distribution hub establishment for first-mover brands.
Global Free Standing Electrical Height-Adjustable Tables Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying linear actuators, control boxes, and telescoping leg assemblies to multiple downstream brands. The vendor base stratifies across three tiers: integrated manufacturers with captive metalworking and electronics assembly; specification-driven brands leveraging architectural relationships; and digital-native retailers compressing margin through direct-to-consumer fulfillment. Dominant competitive moves include backward integration into PCB assembly to reduce Taiwanese supplier dependency, and furniture-as-a-service arrangements bundling installation with preventive maintenance contracts.
Within the integrated manufacturing tier, Steelcase Inc. and Haworth Inc. exemplify platform control through specification relationships with architectural and design firms. FlexiSpot occupies a position representing digital-native competitive pressure through configurable checkout workflows and regional fulfillment center networks. These three anchors illustrate the structural tension between traditional enterprise procurement channels and emerging direct-to-commercial distribution patterns.
| Leading Market Players |
|---|
| Steelcase Inc. |
| Herman Miller |
| Haworth Inc. |
| Uplift Desk |
| Vari |
| FlexiSpot |
| Global Furniture Group |
| HNI Corporation |
| Ergotron |
| Others |
Supply & Pricing Matrix
The Port of Rotterdam's container throughput cost dynamics compress margin buffers for European-bound shipments while amplifying price differentiation between captive-metalworking manufacturers and assembly-dependent brands sourcing Taiwanese control boxes. Steel and aluminum input volatility feeds directly into telescoping leg pricing, with dual-motor configurations commanding premiums that single-motor alternatives cannot sustain in municipal procurement.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise, co-working, and educational buyer archetypes, with Fortune 500 procurement teams extracting 15-20 point spreads through furniture-as-a-service bundling. Certification grade—specifically UL 962B electrical safety and BIFMA G1 ergonomic compliance—drives the steepest price differentiation, while customization level and after-sales service intensity separate premium from standard positioning. Pricing pressure stems from manual crank substitutes capping electric unit realization in budget segments. Educational institutions exhibit highest price sensitivity; healthcare administrative networks show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for control box procurement, with Taiwanese electronics suppliers absorbing displaced demand. Manufacturing concentrates in China, Taiwan, and Vietnam for PCB assembly and linear actuator production, while Germany and the United States retain captive metalworking for telescoping leg fabrication. Cold-rolled steel and extruded aluminum dependencies rest on energy-intensive smelting operations vulnerable to commodity price swings. Single-source vulnerability clusters in programmable logic modules with electromagnetic compatibility certification. Distribution runs through direct sales for enterprise accounts and online retailers for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, with EU Green Deal procurement mandates embedding ergonomic furniture into public sector tender requirements and accelerating penetration beyond traditional corporate fit-outs.
For Market Incumbents: Build certification moats through simultaneous UL 962B and BIFMA G1 pursuit, compressing development timelines that smaller competitors cannot match. Backward integration into PCB assembly reduces Taiwanese supplier dependency, while furniture-as-a-service bundling locks in enterprise relationships against digital-native entrants. Threat: FlexiSpot's configurable checkout workflows eroding mid-market share. Lever: captive service networks with circular logistics capabilities. For New Entrants and Emerging Players: Pursue healthcare administrative workstation conversion as the most penetrable vertical adjacent to saturated corporate demand. India's commercial real estate expansion in Bangalore and Hyderabad offers geographic white space with smart building infrastructure accommodating motorized furniture integration. Go-to-market angle: ISO 9241-5 ergonomic certification as procurement filter leverage in Nordic and German enterprise accounts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform integrators with specification relationships over pure component specialists. Five-to-ten year viability hinges on firmware-enabled analytics subscriptions transforming hardware margins into recurring revenue. Acquisition target archetype: digital-native retailers with regional fulfillment networks compressing delivery timelines. Signal to watch: embedded firmware cybersecurity scrutiny under NIST IoT guidelines as margin compression trigger for non-compliant brands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PCB Assembly | Reduces Taiwanese supplier dependency for control box sourcing. |
| Furniture-as-a-Service Launch | Captures enterprise relationships through bundled installation and maintenance. |
| ISO 9241-5 Certification Investment | Unlocks Nordic and German procurement filters favoring validated ergonomics. |
| Healthcare Vertical Expansion | Targets hospital billing and records staff sedentary risk awareness. |
| India Distribution Partnership | Establishes regional hub presence ahead of commercial construction peak. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade records, BIFMA compliance databases, and EU tender documentation. Primary interviews engaged furniture procurement managers at Fortune 500 headquarters, facility management integrators in London and Sydney, control box engineering leads at Taiwanese electronics suppliers, and workplace strategy consultants specifying ergonomic mandates. Bottom-up unit economics modeling triangulates against top-down market sizing from regional construction permits and enterprise fit-out expenditure tracking.
Forecast inputs span motor configuration segmentation, distribution channel economics, and end-user adoption curves across corporate, co-working, healthcare, and educational verticals. The analytical framework projects volume and value across the analysis window using penetration rate assumptions tied to regulatory mandate timelines and building certification scheme evolution. CAGRs derive from fitted growth curves calibrated to historical replacement cycle compression in Germany, Japan, and the United States. Industry-specific inputs include METI standby power regulation compliance costs and EU Green Deal procurement mandate implementation schedules.
Sensitivities concentrate around steel and aluminum price volatility, Taiwanese control box supply disruption, and cybersecurity labeling requirement acceleration. Forecasts reflect assumptions regarding regulatory mandate enforcement consistency and enterprise procurement team ergonomic furniture embedding velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
United Kingdom Furniture Market
Furniture
Piano Stools Market
Furniture
United Kingdom Home Furniture Market
Furniture
Global Multifunctional Home Furniture Market
Furniture
Furniture & Cabinet Hardware Market
Furniture
Indonesia Home Furniture Market
Furniture
UAE Luxury Furniture Market
Furniture
Italy Furniture Retail Market
Furniture
Europe Sustainable Mattress Market
Furniture
Wood Furniture Market
Furniture
US School Furniture Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
India Luxury Furniture Market
Furniture
UK Sustainable Office Furniture Market
Furniture
Germany Furniture Market
Furniture
UK Multifunctional Furniture Market