
 School Furniture Market | 2026-2036
School Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
School Furniture Market Analysis
Multi-source procurement among public school districts is expanding as administrators seek supply chain resilience against raw material volatility. Virco leverages domestic manufacturing capacity to sustain bid competitiveness in large district contracts. HNI Corporation anchors its position through backward integration into metal fabrication, controlling cost structures in institutional seating. MillerKnoll differentiates via design-forward collections that compete for premium university and private school placements.
School furniture encompasses desks, chairs, tables, and storage systems engineered to ergonomic standards with load-bearing specifications typically rated for commercial durability cycles exceeding institutional use thresholds. Manufacturing processes integrate powder-coated steel framing, engineered wood substrates, and high-density polyethylene surfaces to achieve fire-resistance and impact-resistance parameters mandated for educational occupancy codes. The wood material segment leads volume owing to established supply chains and aesthetic preferences in North American and European institutions, while the composite material category is gaining fastest as manufacturers pursue lighter weight profiles and enhanced recyclability credentials. Application demand concentrates in classrooms, where flexible configurations supporting collaborative pedagogies command margin premiums over fixed-installation auditorium and laboratory furnishings.
The U.S. Environmental Protection Agency regulates formaldehyde emissions through TSCA Title VI certification requirements that shape panel and composite material selection across supplier portfolios. The Consumer Product Safety Commission maintains flammability standards under 16 CFR Part 1633 that directly influence upholstery foam and textile specifications in seating products. California's Department of Public Health extends additional indoor air quality protocols through its Section 01350 standard, creating a de facto national compliance threshold for manufacturers distributing across state lines. Stakeholders must monitor evolving procurement mandates tied to green building certifications and circular economy criteria as school districts increasingly embed sustainability scoring into competitive bidding frameworks.
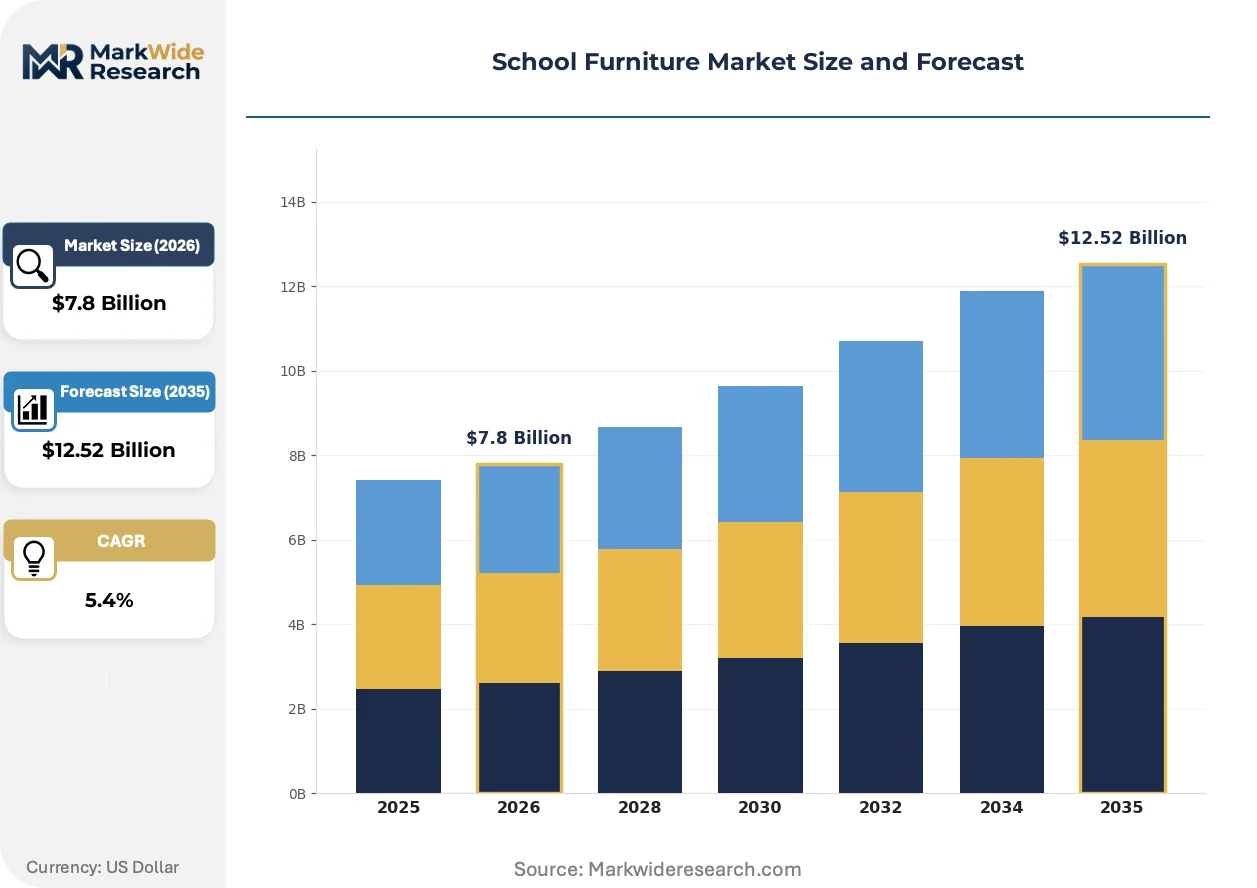
Market Dynamics
Federal education funding cycles and state procurement mandates are compressing replacement timelines while elevating sustainability scoring as a bid determinant. Districts now weight indoor air quality certifications and domestic content thresholds alongside unit pricing in competitive evaluations.
Growth Catalysts
- TSCA Title VI Compliance:The EPA's formaldehyde emission standards for composite wood products are accelerating panel material upgrades across supplier portfolios. Manufacturers achieving third-party certification gain preferential placement in district bid shortlists.
- Ergonomic Workstation Demand:K-12 institutions are specifying adjustable-height desks and collaborative seating configurations to support active learning pedagogies. Flexible furniture commands margin premiums over fixed-installation alternatives.
- Steel Framing Integration:Powder-coated steel substructures are displacing all-wood construction in high-traffic seating applications. The shift improves fire-resistance ratings and extends product replacement cycles.
Market Restraints
- Lumber Price Volatility:Engineered wood substrate costs fluctuate with North American softwood supply disruptions. Manufacturers without captive forestry relationships face margin compression during commodity spikes.
- Supply Concentration in Asia:High-density polyethylene component sourcing clusters in specific coastal manufacturing zones. Geopolitical friction or shipping congestion creates inventory risk for just-in-time production models.
- Flammability Testing Burden:The Consumer Product Safety Commission's 16 CFR Part 1633 upholstery standards impose extended certification timelines. Small fabricators struggle to absorb third-party testing costs relative to volume scale.
Strategic Opportunities
- Circular Economy Procurement Mandates:California's Section 01350 indoor air quality protocols are spreading to adjacent states as de facto national standards. Manufacturers with closed-loop material recovery programs capture sustainability-scored contracts.
- Modular Reconfiguration Services:Subscription-based furniture refresh models are emerging in university and private school channels. Revenue shifts from unit sales to ongoing spatial planning and redeployment services.
- High-Density Polyethylene Advancement:Recycled-content surface materials are converging with antimicrobial additive technologies. The combination addresses both sustainability credentials and post-pandemic hygiene expectations.
Industry Challenges
- Certification Timeline Compression:Green building certification requirements are multiplying faster than testing laboratory capacity. Manufacturers face bid disqualification when documentation lags procurement deadlines.
- Legacy Inventory Integration:Districts with mixed-vendor installations struggle to achieve unified warranty coverage and replacement part availability. Interoperability gaps complicate multi-phase modernization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | School Furniture Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Tables, Storage Units Material: Wood, Metal, Plastic, Composite End User: Primary Schools, Secondary Schools, Colleges, Universities Application: Classrooms, Libraries, Laboratories, Auditoriums |
| Companies Covered | Virco, Smith System, VS America, Fleetwood Group, Hertz Furniture, MillerKnoll, HNI Corporation, Paragon Furniture, Scholar Craft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
School Furniture Market Emerging Trajectories
Active learning pedagogies are reconfiguring spatial requirements while material science advances and procurement digitization reshape competitive positioning. Three developments are altering how furniture is specified, manufactured, and deployed.
Antimicrobial surface treatments are expanding into educational seating and worksurface applications. Private schools and healthcare-affiliated institutions are specifying copper-ion or silver-based additives at accelerated rates. The technology is expanding into mid-tier product lines previously limited to premium collections, compressing differentiation windows for early adopters.
The EPA's enhanced enforcement of TSCA Title VI certification is tightening composite wood supply chains. Panel manufacturers must maintain chain-of-custody documentation from forest origin through fabrication. California's Department of Public Health Section 01350 protocols are extending to VOC testing for adhesives and finishes, affecting seating upholstery specifications most acutely.
District purchasing cooperatives are consolidating specification authority away from individual schools. National intermediaries now aggregate demand across hundreds of districts, compressing vendor counts and standardizing SKU requirements. The concentration is most visible in the southwestern United States, where regional purchasing alliances dominate public institution procurement.
School Furniture Market Segmentation
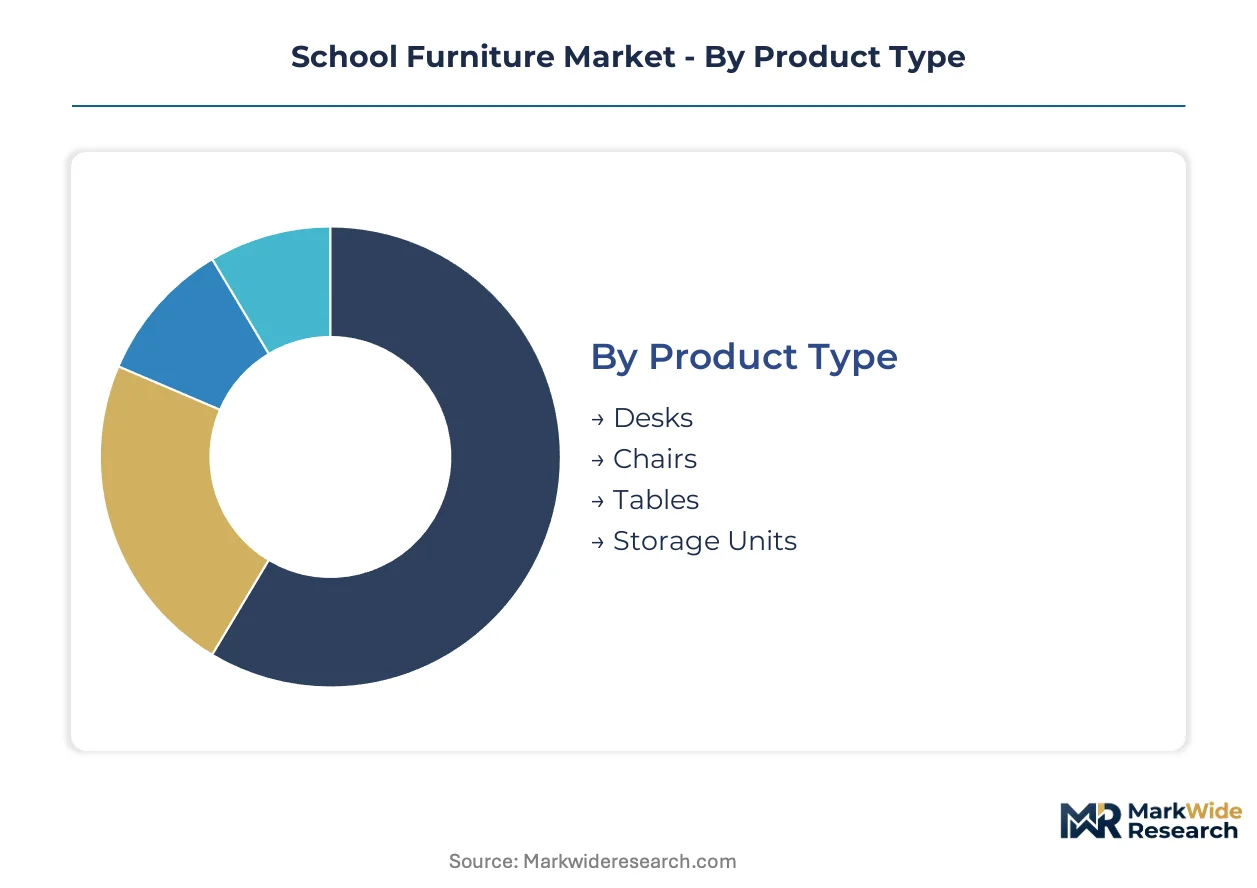
Segmentation in school furniture reveals how procurement priorities diverge across institutional tiers and spatial requirements. District purchasing patterns vary sharply between standardized K-12 specifications and the design-flexible demands of higher education. Understanding these divides enables suppliers to align manufacturing investments with bid-winning segments.
Product Type:
Standalone seating and worksurface units dominate procurement volumes, while integrated systems command premium positioning in modernization contracts.
- Desks:Single-student and collaborative configurations incorporate height-adjustable mechanisms and cable management channels. Primary schools in the United States specify these for ergonomic compliance under state procurement mandates, with flexible models capturing margin premiums over fixed-height alternatives.
- Chairs:Shell seating with polypropylene or high-density polyethylene surfaces pairs with steel or hardwood frames for durability cycles exceeding institutional thresholds. Secondary schools concentrate demand here, driven by replacement timelines compressed by federal funding cycles and active learning pedagogies requiring mobile, stackable designs.
- Tables:Modular conference and cafeteria surfaces support reconfigurable layouts.
- Storage Units:Mobile cubbies and fixed cabinetry address classroom organization and material security.
Volume placements concentrate in Chairs; the faster expansion belongs to Desks.
Material:
Cost tier stratification separates commodity-grade inputs from certified low-emission alternatives that score sustainability points in competitive bidding.
- Wood:Engineered substrates—particleboard, MDF, and plywood—form the structural core of desks and storage systems. North American softwood supply chains serve established institutional preferences, though price volatility pressures manufacturers without captive forestry relationships or long-term supplier contracts.
- Metal:Powder-coated steel framing improves fire-resistance ratings and extends replacement cycles in high-traffic seating applications. The EPA's TSCA Title VI compliance requirements favor metal-intensive construction where composite wood certification documentation lags procurement deadlines.
- Plastic:High-density polyethylene surfaces deliver impact resistance and antimicrobial integration.
- Composite:Hybrid material systems combine structural metal with engineered wood or recycled-content surfaces.
Wood captures the largest procurement volumes; composite materials are climbing the fastest as manufacturers pursue lighter weight profiles and enhanced recyclability credentials.
End User:
Customer type determines specification complexity, with public district procurement differing fundamentally from private institution flexibility.
- Primary Schools:Standardized, durable furniture with rounded edges and lower height profiles dominates. United States federal Title I funding sustains replacement cycles, with districts prioritizing unit pricing and domestic content thresholds in competitive evaluations.
- Secondary Schools:Science laboratories and vocational workshops drive specialized furnishing requirements. State-level career and technical education initiatives in the United States accelerate demand for chemical-resistant surfaces and heavy-duty seating in workshop environments.
- Colleges:Community colleges and two-year institutions balance cost constraints with modernization pressures.
- Universities:Research-intensive and residential campus environments specify design-forward collections.
Procurement volumes cluster in Primary Schools; Universities show the steepest expansion trajectory for premium ergonomic and collaborative configurations.
Application:
Spatial function dictates durability specifications and reconfiguration frequency, with high-occupancy areas requiring distinct material treatments.
- Classrooms:Flexible furniture supporting active learning pedagogies commands margin premiums over fixed-installation alternatives. K-12 institutions in the United States specify adjustable-height desks and mobile seating to accommodate collaborative group work and individual instruction modes.
- Libraries:Individual carrels, collaborative tables, and soft seating zones serve evolving media center functions. The shift from book storage to maker spaces and digital learning hubs drives demand for power-integrated worksurfaces and reconfigurable furnishings in United States school districts.
- Laboratories:Chemical-resistant surfaces and specialized seating meet safety codes.
- Auditoriums:Fixed seating with fire-resistant upholstery dominates high-capacity performance spaces.
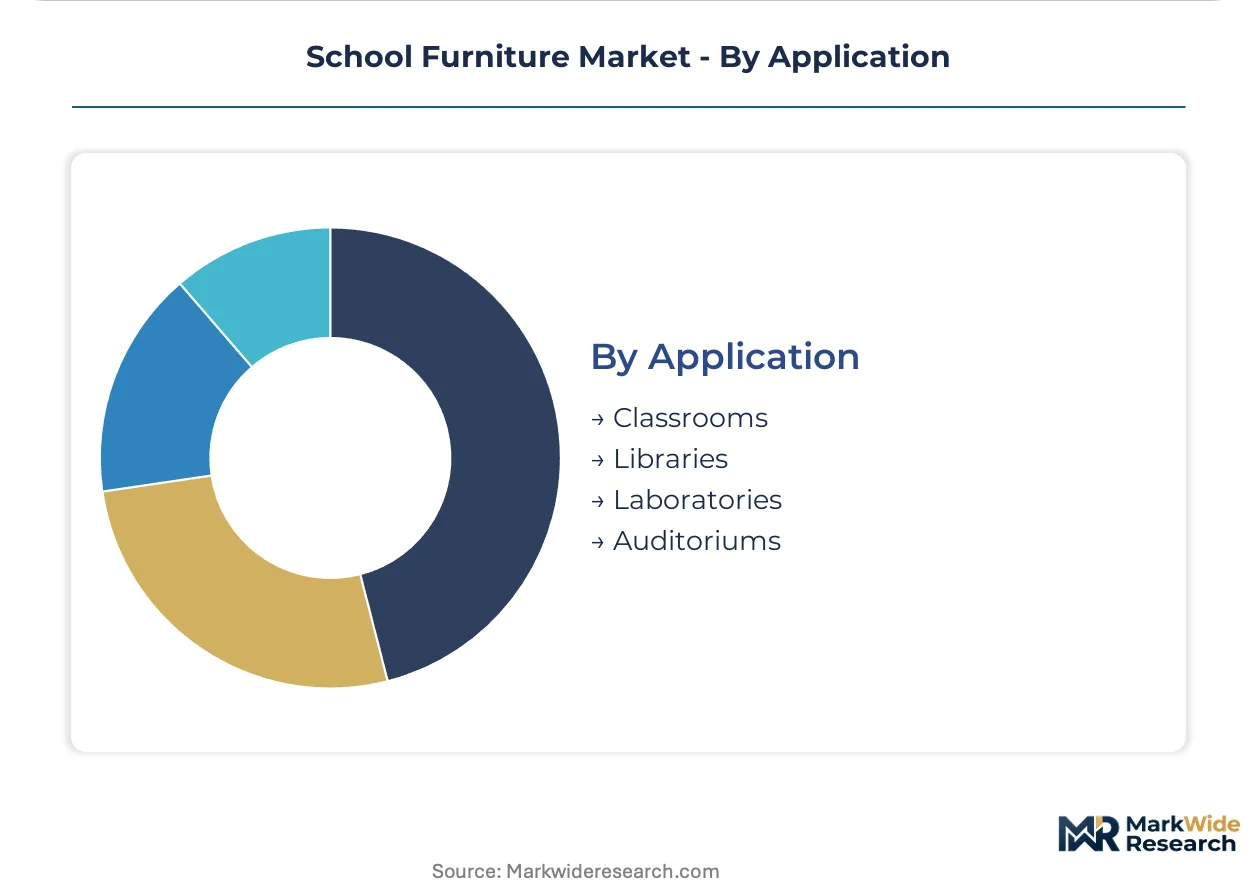
Classroom applications anchor procurement volumes; Libraries are gaining share fastest as institutions repurpose traditional media centers for collaborative digital learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American softwood forests and Great Lakes metal fabrication clusters anchor the school furniture industry's material base, with procurement patterns diverging sharply between federal funding cycles in the United States and provincial standardization in Canada.
United States
Elementary and secondary school districts drive replacement demand through Title I allocations and ESSER fund deployment. The EPA's TSCA Title VI certification requirements filter supplier participation in federal procurement pools. Domestic manufacturing concentrates in Tennessee and Ohio, where powder-coating and metal-stamping facilities serve bid-responsive production timelines.
Canada
Provincial ministries of education coordinate bulk purchasing through Ontario and British Columbia buying consortia. Health Canada's PMRA regulates antimicrobial additive claims in surface treatments. Quebec's engineered wood panel producers supply cross-border districts seeking low-emission certification chains.
Germany
Vocational school modernization programs accelerate demand for chemical-resistant workshop furnishings. ECHA's REACH compliance obligations shape adhesive and finish specifications for exported components. Baden-Württemberg's precision metalworking clusters fabricate height-adjustable desk mechanisms for European distribution.
China
High-density polyethylene molding capacity concentrates in Guangdong and Zhejiang provinces for global component supply. The MIIT's GB standards for plastic furniture structural integrity create export documentation requirements. Yangtze River Delta manufacturers balance domestic education infrastructure investment against overseas contract manufacturing.
India
Midday meal scheme expansion and Sarva Shiksha Abhiyan implementation multiply classroom furniture requirements in rural districts. BIS certification mandates for school desk structural safety delay import clearance timelines. Gujarat's polymer processing hubs and Punjab's metal fabrication centers compete for government tender participation.
School Furniture Market Vendor Landscape
Global majors compete with regional champions across certification compliance and bid responsiveness. The market structure shows moderate consolidation at the top tier with fragmented mid-market participation. Three archetypes dominate: domestic vertically integrated fabricators controlling cost structures, design-forward premium specialists capturing university placements, and purchasing cooperative-aligned volume suppliers. Competitive moves center on backward integration into metal fabrication and geographic expansion through district cooperative penetration.
Among domestically anchored manufacturers, Virco and HNI Corporation exemplify scale-driven production models. MillerKnoll occupies a position within the design-specialist tier. These three represent distinct strategic postures: Virco exemplifies cooperative-aligned volume supply, HNI Corporation anchors backward-integrated cost control, and MillerKnoll sits within the premium specification segment.
| Leading Market Players |
|---|
| Virco |
| Smith System |
| VS America |
| Fleetwood Group |
| Hertz Furniture |
| MillerKnoll |
| HNI Corporation |
| Paragon Furniture |
| Scholar Craft |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between TSCA Title VI-compliant panel systems and uncertified commodity alternatives manifests in both procurement premiums and supplier qualification barriers. Districts weighting indoor air quality scoring in competitive bids create pricing power for manufacturers with documented chain-of-custody compliance, while non-certified fabricators face exclusion from federal funding pools regardless of unit cost advantages.
Pricing Analysis
Warranty and installation service bundling separates full-service district contracts from unbundled commodity transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with EPA-compliant collections commanding placement premiums in ESSER-funded modernization programs. Pricing pressure stems from lumber price volatility compressing margins on wood-intensive product lines. Primary school districts exhibit highest price sensitivity, while universities prioritize design flexibility over unit economics.
Supply Chain Analysis
Regional distribution centers in Tennessee and Ohio anchor hub-and-spoke fulfillment patterns for bid-responsive delivery timelines. Manufacturing concentration in the United States, China, and Canada shapes component sourcing, with high-density polyethylene molding clustered in Guangdong and Zhejiang provinces. Raw material dependencies include North American softwood, powder-coated steel substrates, and engineered wood panels. Single-source vulnerability in Asian polymer supply creates inventory risk during shipping congestion. Distribution runs through purchasing cooperative networks that aggregate demand across multi-district territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EPA TSCA Title VI certification creates a barrier-to-entry moat that rewards documented investment in chain-of-custody systems and third-party laboratory relationships.
For Market Incumbents: To counter margin compression from lumber price volatility, prioritize backward integration into captive steel fabrication capacity and locked-in softwood supply contracts. Consolidate position by acquiring regional distributors with established purchasing cooperative relationships, converting transactional accounts into exclusive service agreements.
For New Entrants and Emerging Players: Purchasing cooperative procurement managers represent the most accessible channel partners for bypassing incumbent district relationships. White-space opportunities concentrate in antimicrobial surface treatments for private school segments and subscription-based furniture refresh models for university clients. Target secondary school science laboratory furnishings where state career and technical education initiatives accelerate replacement cycles.
For Investors and Strategic Acquirers: Re-rating potential sits with domestic vertically integrated fabricators given federal domestic content threshold expansion in education infrastructure procurement. Long-term viability favors manufacturers with closed-loop material recovery programs aligned to circular economy scoring in competitive bidding. Monitor California Section 01350 protocol adoption rates in adjacent states as inflection indicator for sustainability-premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| TSCA Title VI Certification Investment | EPA compliance documentation unlocks federal procurement pool participation and district bid shortlist placement. |
| Backward Integration into Steel Fabrication | In-house powder-coating capacity insulates margin structures from commodity metal pricing cycles. |
| Antimicrobial Surface Technology Licensing | Copper-ion additive integration addresses post-pandemic hygiene specifications in private school segments. |
| Purchasing Cooperative Partnership Expansion | Regional alliance penetration consolidates demand aggregation and compresses vendor counts in southwestern districts. |
| Closed-Loop Material Recovery Program | California Section 01350 alignment captures sustainability-scored contracts in circular economy procurement mandates. |
Methodological Framework
Independent corroboration across district procurement officers, furniture manufacturing executives, and third-party certification laboratory directors underwrites the qualitative findings in this study. Primary fieldwork encompassed structured interviews with K-12 facilities planners, university space management directors, and purchasing cooperative administrators. Secondary validation drew from EPA TSCA Title VI certification databases, Consumer Product Safety Commission flammability testing records, and state-level education procurement disclosure filings. Bottom-up demand modeling triangulated against top-down federal funding allocation analysis.
Comparable-period anchoring to historical ESSER fund deployment patterns and Title I replacement cycle data established the forecast reference baseline. Segmentation modeling spanned product type, material composition, end-user institution tier, and application environment across the projection horizon. CAGRs derived from unit shipment trajectories and average selling price movements by certification tier. Industry-specific inputs included district modernization pipeline tracking and green building certification adoption rates.
Caveats apply where federal education funding reauthorization delays or raw material supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding procurement mandate evolution and commodity price stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
North America Slide Rails Market
Furniture
Outdoor Furniture and Grills Market
Furniture
Indonesia Home Furniture Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Europe Sustainable Office Furniture Market
Furniture
Study Carrels Market
Furniture
Saudi Arabia Home Furniture Market
Furniture
GCC Smart Furniture Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
Netherlands Home Furniture Market
Furniture
Italy Furniture Market
Furniture
Australia Smart Furniture Market
Furniture
Vietnam Home Furniture Market
Furniture
Plastic Furniture Market
Furniture
United States Upholstered Furniture Market
Furniture
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market