
 United Kingdom Kitchen Furniture Market | 2026-2036
United Kingdom Kitchen Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Kitchen Furniture Market Analytics
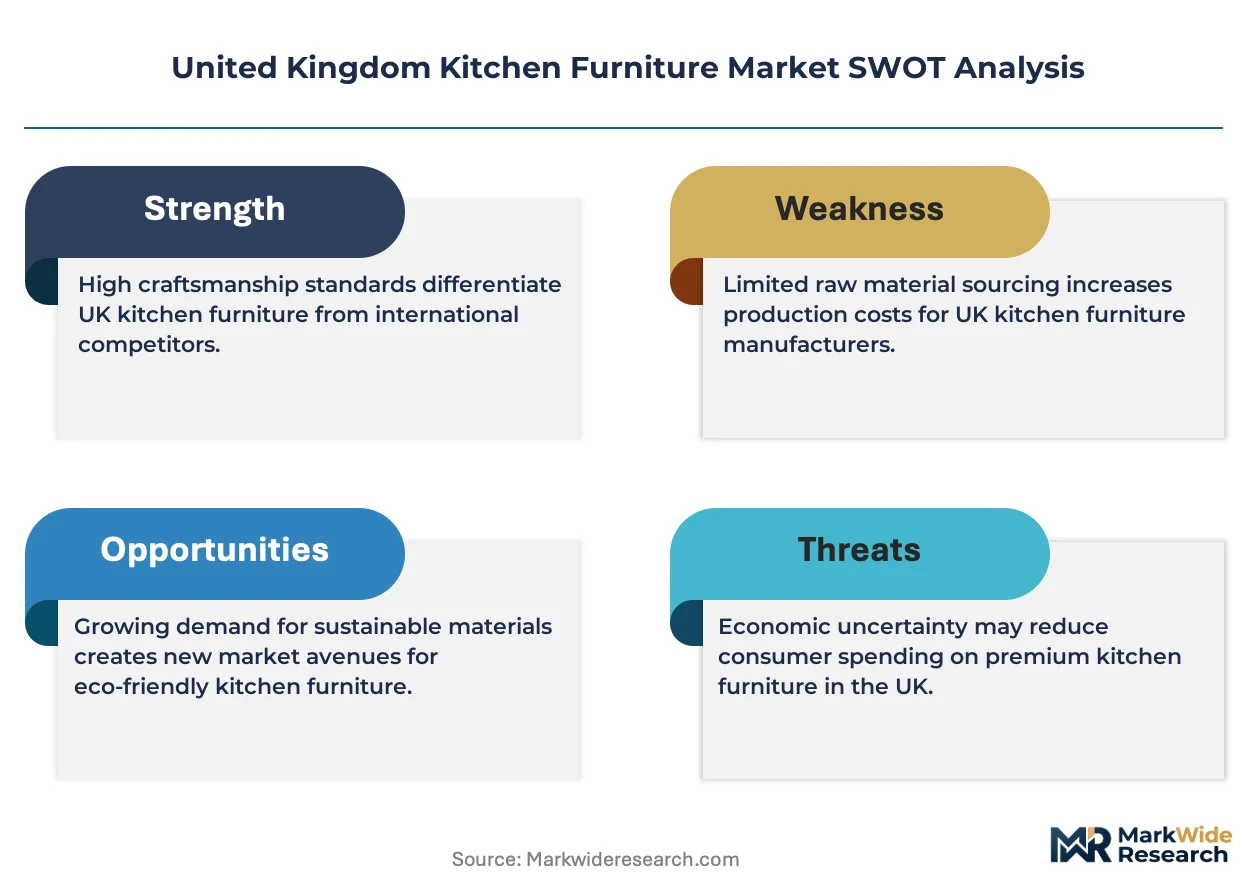
Building Regulations Part L is realigning the cost-of-entry calculus for kitchen furniture suppliers across England and Wales. Howdens Joinery Group leverages its trade-only distribution model to sustain margin control in a compliance-heavy environment. Wren Kitchens anchors its competitive stance through vertical manufacturing ownership in its Thetford facility. IKEA navigates price-sensitive segments while extending its flat-pack logistics expertise to meet tighter building standards.
Kitchen furniture encompasses fixed and movable storage units, work surfaces, and integrated appliances designed for food preparation and domestic utility, typically manufactured from engineered wood panels with melamine or lacquer finishes and requiring moisture-resistant edge banding. Cabinets dominate volume throughput as the foundational install element, while stone countertops command disproportionate margin pools due to fabrication complexity and premium positioning. Flat-pack installation retains share in first-time buyer and rental markets, though custom-built solutions gain traction among homeowners pursuing Part L-aligned energy retrofits.
The British Standards Institution certifies dimensional tolerances and material safety, while the UK Timber Regulation enforces chain-of-custody documentation for imported wood substrates. These frameworks elevate compliance burdens for smaller importers while rewarding domestic manufacturers with verified supply chains. Stakeholders must monitor proposed amendments to Part F ventilation standards, which would mandate extract hood performance ratings that reshape appliance-integrated cabinet specifications.
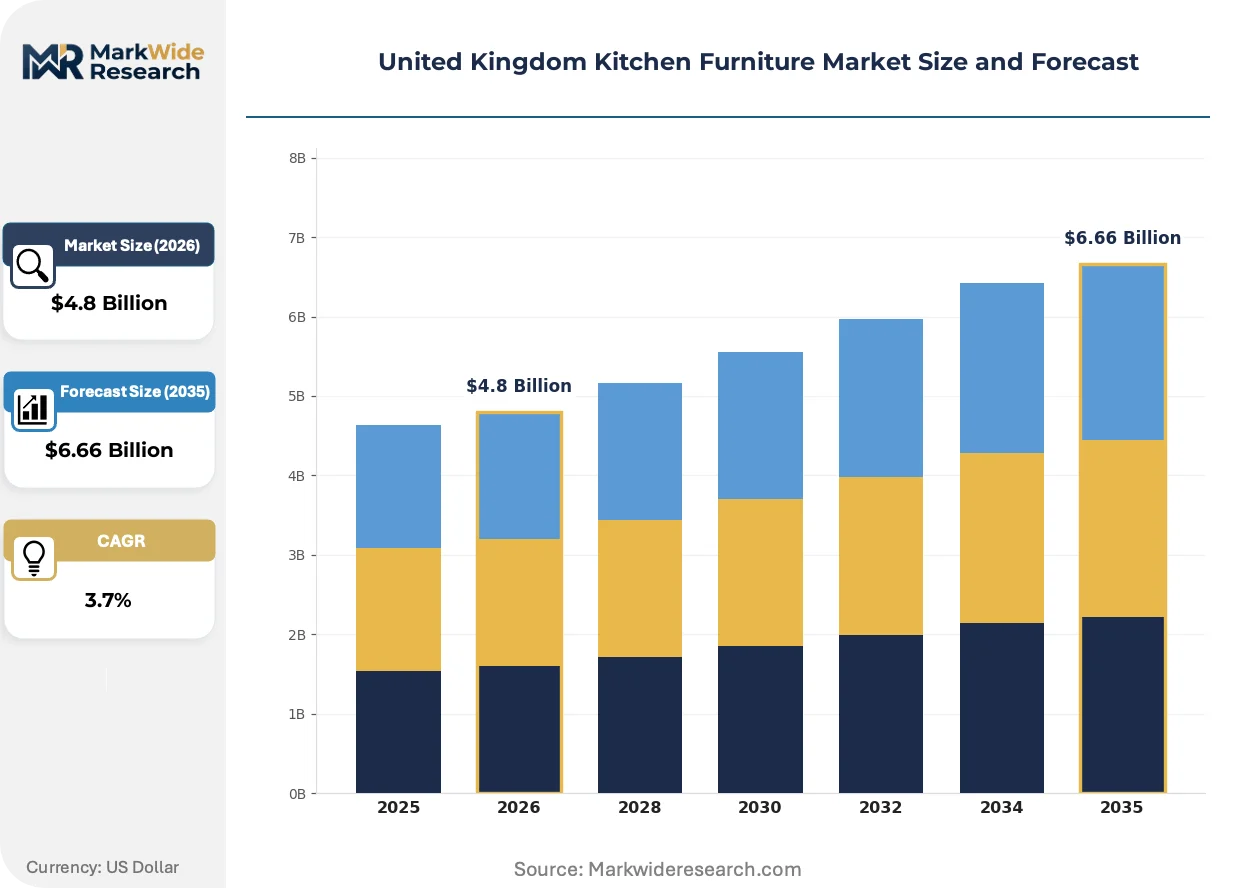
Market Dynamics
Building Regulations Part L is compressing kitchen replacement cycles across England and Wales by mandating energy-efficiency retrofits that bundle appliance upgrades with cabinet replacement. This regulatory pressure is rewiring supplier-customer relationships and procurement patterns.
Growth Catalysts
- Part L retrofit mandates:Homeowners undertaking energy-efficiency upgrades must replace kitchen units to accommodate new appliance specifications, creating forced replacement demand.
- Stone countertop fabrication:Premium material adoption in Greater London and the South East is pulling average transaction values upward through complex bespoke worktop orders.
- Social housing decarbonisation:Local authority retrofit programmes are generating volume demand for standardized cabinet configurations across municipal housing stock.
Market Restraints
- Engineered wood panel volatility:Import dependency for MFC substrates exposes margins to Baltic supply fluctuations and shipping rate spikes.
- UK Timber Regulation compliance:Chain-of-custody documentation requirements for imported wood substrates create administrative friction for smaller distributors lacking verified supply chains.
- Flat-pack substitution ceiling:First-time buyer price sensitivity caps margin expansion in the volume segment despite material cost pressures.
Strategic Opportunities
- Part F ventilation amendments:Proposed extract hood performance ratings will mandate appliance-integrated cabinet specifications, creating specification capture opportunities for compliant suppliers.
- Custom-built retrofit solutions:Energy retrofit alignment is opening premium positioning for made-to-measure kitchens that accommodate insulation and ventilation requirements.
- Trade-only channel deepening:Builder and installer networks represent underexploited routes to homeowner decision-makers in compliance-driven replacement cycles.
Industry Challenges
- Moisture-resistant edge banding certification:British Standards Institution dimensional tolerance enforcement requires capital investment in upgraded fabrication equipment.
- Skilled installer availability:Complex Part L-aligned retrofit installations demand trained fitters capable of integrating ventilation, insulation, and cabinet systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Kitchen Furniture Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Sinks, Countertops, Islands Material: Wood, Laminate, Metal, Stone Style: Modern, Traditional, Minimalist, Rustic Installation Type: Pre-assembled, Flat-pack, Custom-built, Modular |
| Companies Covered | Howdens Joinery Group, Wren Kitchens, B&Q, Wickes, Magnet, IKEA, Symphony Group, Omega, Neptune, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Kitchen Furniture Market Evolving Landscape
Digital configuration tools and modular manufacturing systems are compressing lead times and enabling mass-customization at scale. Three distinct developments are altering competitive positioning.
Modular cabinet systems with standardized connection hardware are decentralizing kitchen design authority from specialist retailers to direct-to-consumer platforms. Homeowners in the South East are configuring layouts online at accelerating rates. This shift is fragmenting traditional showroom-dependent distribution models.
Building Regulations Part L is mandating thermal bridging reduction through improved cabinet sealing and appliance integration. Kitchen suppliers must redesign carcass construction to accommodate continuous insulation layers. The retrofit segment is responding with deeper service offerings that bundle energy assessment with furniture specification.
Installer-led specification is displacing homeowner-driven selection in compliance-heavy replacement cycles. Builders and retrofit coordinators are gatekeeping product choices through packaged renovation services. This pattern concentrates in Greater London where Part L enforcement is strictest and project complexity highest.
United Kingdom Kitchen Furniture Market Segmentation
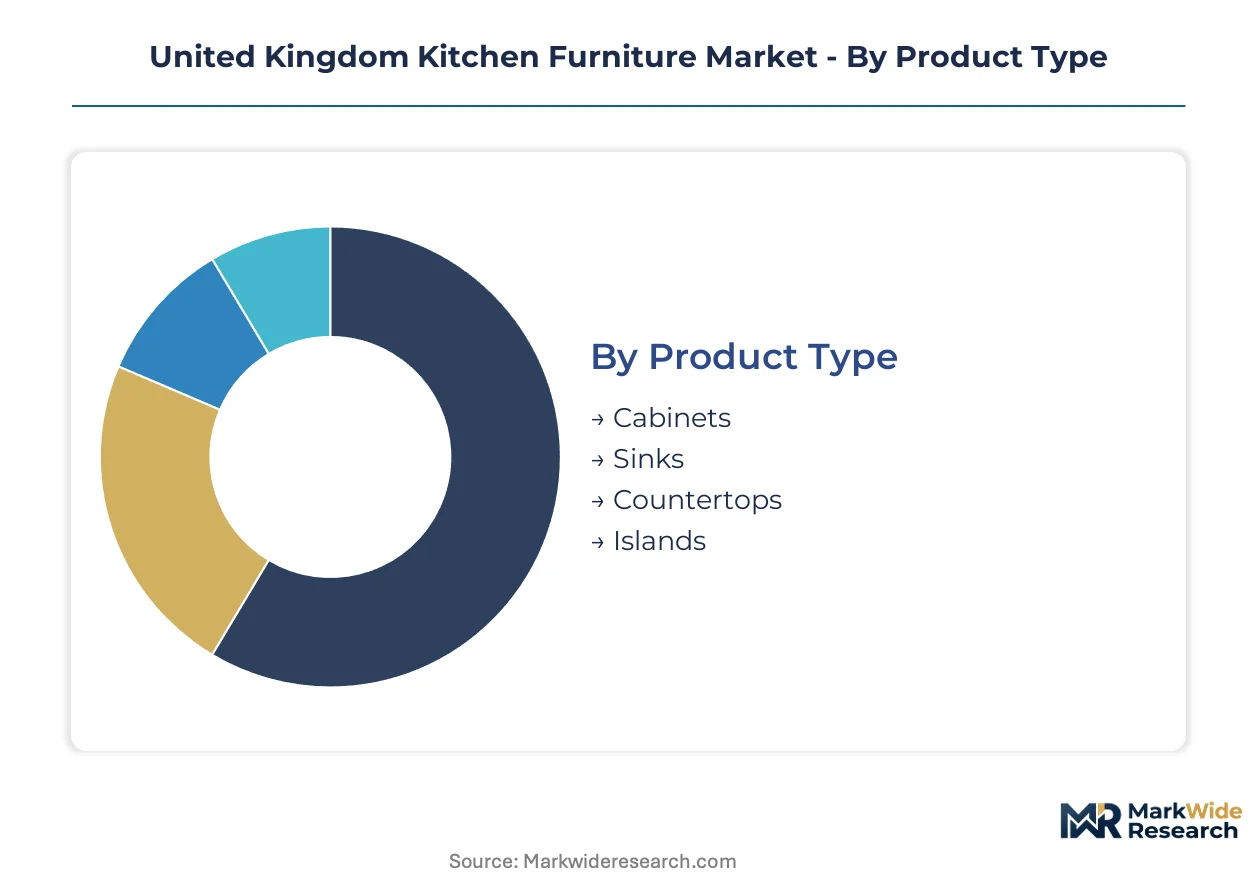
Kitchen furniture segmentation in the United Kingdom tracks divergent replacement cycles across housing tenures and renovation intensities. Part L retrofit mandates are compressing upgrade timelines for certain product configurations while elongating decision horizons for others.
Product Type:
Upgrade cycle intensity varies sharply by install element, with forced replacement from energy-efficiency retrofits hitting some categories harder than others.
- Cabinets:Engineered wood carcasses with moisture-resistant edge banding form the foundational install layer. Demand concentrates in social housing decarbonisation programmes across municipal stock in Greater London, where standardized box configurations dominate procurement.
- Countertops:Stone fabrication commands premium positioning through complex bespoke cutting and sealing. South East homeowners pursuing Part L-aligned renovations are specifying thicker worktops with integrated drainage grooves at accelerating rates.
- Sinks:Stainless steel and ceramic basin configurations align with cabinet replacement cycles in retrofit scenarios.
- Islands:Freestanding centrepiece units gain traction in open-plan renovations where ventilation ducting requires spatial reconfiguration.
Cabinets sit at the top of the volume ranking, with countertops climbing the fastest.
Material:
Cost tier positioning determines supplier margin exposure to Baltic substrate volatility and UK Timber Regulation compliance burdens.
- Wood:Solid timber and veneered substrates face chain-of-custody documentation requirements that reward domestic manufacturers with verified supply chains. Oak and walnut species dominate premium retrofit specifications in the South East.
- Laminate:Melamine-faced chipboard offers moisture resistance at entry price points. First-time buyers in rental conversion markets select high-pressure laminate for durability despite flat-pack margin compression.
- Metal:Stainless steel and powder-coated aluminium serve commercial kitchen specifications and industrial-style residential conversions.
- Stone:Granite and quartz composites require specialized fabrication equipment certified to British Standards Institution tolerances.
Laminate leads absolute volume throughput, with stone gaining share fastest in value terms.
Style:
Customer type and housing vintage dictate aesthetic selection, with period property renovations pulling toward heritage configurations.
- Modern:Handleless slab doors with high-gloss or super-matte finishes align with new-build specifications and contemporary extensions. Greater London apartment developments specify this configuration for rental fit-outs.
- Traditional:Framed shaker and raised-panel doors serve Victorian and Edwardian property renovations. Homeowners in conservation areas must navigate planning constraints that preserve external character while upgrading internal utility.
- Minimalist:Concealed hardware and integrated appliances respond to compact urban dwellings where visual continuity matters.
- Rustic:Distressed finishes and visible grain patterns appeal to barn conversions and rural refurbishment projects.
Modern styling dominates new-build specification, with traditional configurations expanding most quickly in heritage retrofit.
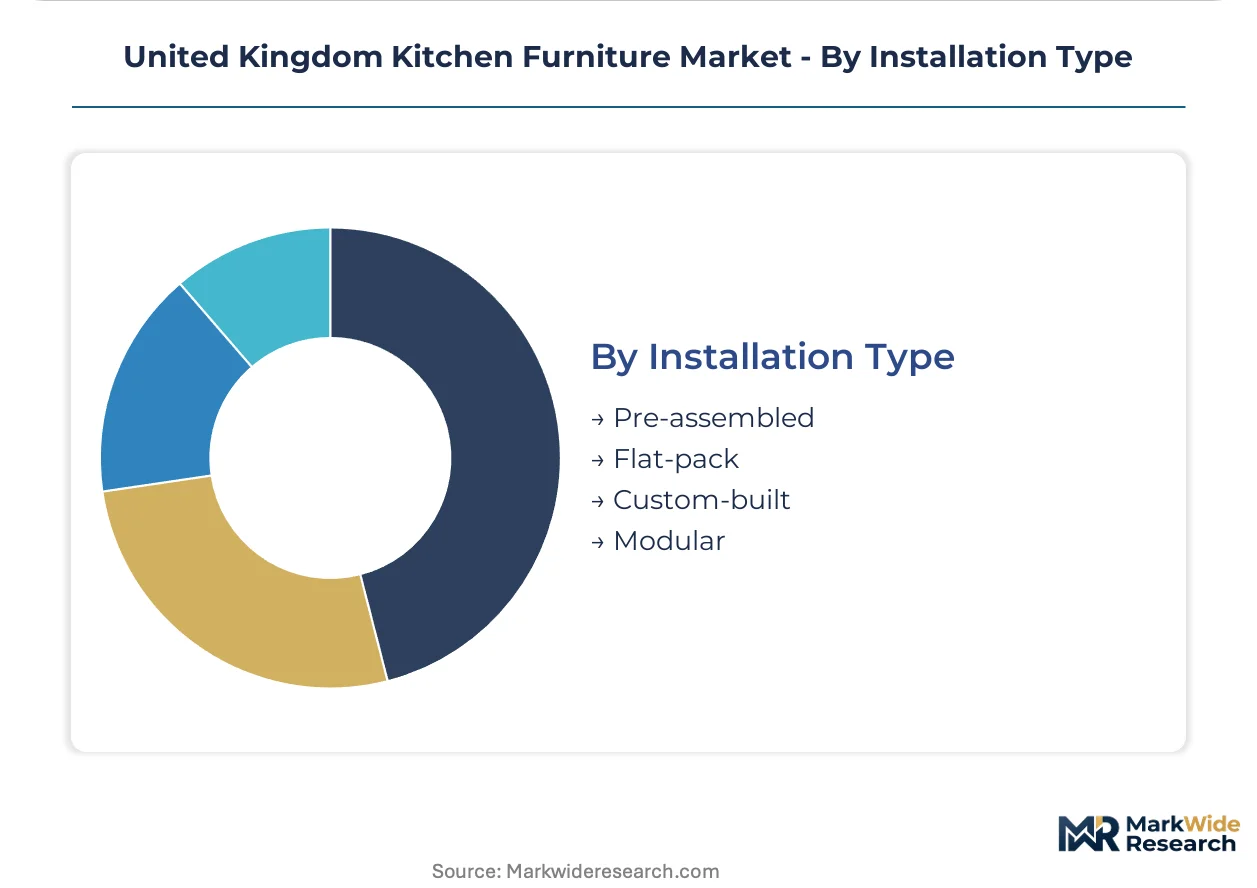
Installation Type:
Supply concentration and installer capability requirements create divergent competitive dynamics across fitting methodologies.
- Flat-pack:Particleboard components with cam-and-dowel hardware enable self-assembly and trade-installer flexibility. Price-sensitive segments in first-time buyer markets sustain volume despite material cost pressures.
- Custom-built:Made-to-measure carcasses accommodate irregular room dimensions and Part L insulation integration. Skilled fitter scarcity in Greater London constrains expansion despite premium positioning.
- Pre-assembled:Factory-finished units reduce on-site labour requirements for developer bulk orders.
- Modular:Standardized connection hardware enables mass-customization through digital configuration platforms.
Flat-pack retains volume leadership, with custom-built solutions climbing the fastest as retrofit complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled kitchen installers and retrofit coordinators concentrate disproportionately in Greater London and the South East, where Part L enforcement is strictest and project complexity demands certified fitters capable of integrating ventilation, insulation, and cabinet systems.
Greater London
Social housing decarbonisation programmes and private landlord retrofit mandates drive cabinet replacement cycles across municipal and rental stock. Building Regulations Part L enforcement by local authorities accelerates kitchen upgrade timelines. Installers in Tower Hamlets and Southwark report backlog pressures from bundled energy-efficiency renovations.
South East England
Homeowners in Surrey and Kent pursue premium stone countertop specifications alongside Part L-aligned kitchen renovations. The UK Timber Regulation elevates compliance burdens for imported wood substrates entering through Dover and Southampton ports. Fabrication workshops in Brighton and Guildford specialize in complex bespoke worktop cutting.
Midlands
Manufacturing employment clusters around Thetford and Birmingham anchor engineered wood panel processing and cabinet assembly operations. British Standards Institution certification requirements for moisture-resistant edge banding necessitate capital investment in upgraded fabrication equipment. Coventry-based suppliers serve social housing retrofit programmes across the West Midlands.
North England
Price-sensitive first-time buyer markets in Manchester and Leeds sustain flat-pack volume despite material cost pressures. Local authority retrofit funding allocations lag southern regions, elongating replacement cycles for municipal housing stock. Sheffield fabricators compete on entry-level laminate configurations.
Scotland
Building standards divergence from England creates distinct compliance pathways for kitchen suppliers operating across the border. Edinburgh and Glasgow heritage property renovations pull toward traditional shaker configurations constrained by conservation area planning rules. Scottish installers develop specialized expertise in stone worktop specifications for period properties.
United Kingdom Kitchen Furniture Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The supplier base fragments across trade-only, retail, and direct-to-consumer channels with divergent margin structures. Three archetypes dominate: vertically integrated manufacturers controlling upstream panel supply, trade-specialist distributors leveraging builder relationships, and flat-pack retailers optimizing logistics scale. Competitive moves concentrate on installer network capture and compliance-forward product certification.
Among UK-based specialists, Howdens Joinery Group exemplifies trade-channel concentration, Wren Kitchens occupies a position as a vertically integrated manufacturer with captive production facilities, and IKEA anchors the flat-pack logistics archetype. These three represent distinct strategic postures toward Part L compliance burdens and retrofit cycle capture.
| Leading Market Players |
|---|
| Howdens Joinery Group |
| Wren Kitchens |
| B&Q |
| Wickes |
| Magnet |
| IKEA |
| Symphony Group |
| Omega |
| Neptune |
| Others |
Value Network & Pricing Analysis
Baltic birch plywood futures and MFC substrate spot indices cascade through UK kitchen furniture supply chains, compressing margins at entry-tier price points while premium stone fabrication retains pricing power through bespoke complexity and certified installer scarcity.
Pricing Analysis
The bundled-vs-unbundled service split separates project-based kitchen renovation contracts from component-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales installation bundling. Cost compression in the flat-pack tier is intensifying because Baltic engineered wood panel volatility feeds directly into particleboard input costs. First-time buyers in northern England exhibit highest price sensitivity, while South East homeowners pursuing Part L retrofits demonstrate lowest sensitivity to premium stone countertop specifications.
Supply Chain Analysis
UK Timber Regulation enforcement and domestic-content documentation mandates are reshaping sourcing patterns for imported wood substrates. Supply concentrates in Estonia, Latvia, and Poland for engineered wood panels, with Italian and Spanish quarries feeding stone fabrication demand. Raw material dependencies rest on melamine-faced chipboard, moisture-resistant edge banding resins, and quartz composite resins. Single-source vulnerability runs through Baltic MFC substrate concentration exposed to shipping rate spikes. Distribution runs through trade-only builder merchant channels, direct-to-consumer retail showrooms, and flat-pack logistics networks serving self-install segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK kitchen furniture market reads as a late-cycle quality story, justified by the demand-shift toward Part L-aligned custom-built retrofit specifications that reward certified fabrication and skilled installation bundling.
For Market Incumbents: Anticipate margin compression from flat-pack substitution ceilings by deepening trade-only channel control through builder network exclusivity agreements. Prioritize British Standards Institution certification investment for moisture-resistant edge banding equipment to defend positioning against emerging direct-to-consumer modular platforms. Vertical integration into captive stone fabrication capacity anchors premium tier retention. For New Entrants and Emerging Players: Direct-to-consumer configuration platforms represent the most penetrable route into South East homeowner segments underserved by traditional showroom-dependent distribution. Target social housing decarbonisation programme procurement through standardized cabinet volume contracts. White-space exists in Part F ventilation-integrated cabinet specifications pending regulatory amendment. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated mid-cap specialists controlling captive engineered wood panel supply and certified fabrication capacity. Long-term viability favors suppliers with verified UK Timber Regulation chain-of-custody documentation and installer network density in Greater London. Watch Part F extract hood performance rating amendments as the inflection signal for specification capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Part L Compliance Certification Investment | British Standards Institution edge banding certification creates barrier against unverified imports. |
| Trade Channel Deepening | Builder and retrofit coordinator network exclusivity captures compliance-driven replacement cycles. |
| Stone Fabrication Capacity Expansion | Bespoke countertop complexity in South East and Greater London sustains premium positioning. |
| Digital Configuration Platform Launch | Direct-to-consumer modular systems fragment traditional showroom-dependent distribution models. |
| Social Housing Procurement Positioning | Local authority decarbonisation programmes generate volume demand for standardized configurations. |
Research Methodology
Multiple input streams — primary interviews with kitchen manufacturer executives, trade channel distributors, and certified installation contractors; secondary validation through British Standards Institution certification databases, UK Timber Regulation compliance filings, and social housing procurement records; plus customs data on engineered wood panel imports — were reconciled through bottom-up and top-down triangulation to construct market size and segmentation estimates.
Data-stream reconciliation across product type, material grade, installation methodology, and regional housing tenure patterns shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle modeling against Part L retrofit mandate timelines and social housing decarbonisation programme rollout assumptions. Forecast inputs incorporated Baltic substrate price volatility indices and skilled installer availability metrics by UK region.
The model assumes a particular technology adoption path; alternative pathways for digital configuration and modular manufacturing would alter the outlook if mass-customization platforms accelerate faster than projected. Forecasts reflect assumptions regarding Building Regulations enforcement consistency and supply chain documentation compliance costs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Exam Tables Market
Furniture
Canada Home Furniture Market
Furniture
Pedicure Chair Market
Furniture
Study Carrels Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market
Furniture
United States Home Furniture Market
Furniture
Asia Pacific Multifunctional Furniture Market
Furniture
Wood Furniture Market
Furniture
Massive Wood Slabs Market
Furniture
Vietnam Home Furniture Market
Furniture
Plastic Furniture Market
Furniture
Luxury RTA (Ready-To-Assemble) Furniture Market
Furniture
Germany Furniture Market
Furniture
Fireplace Mantels Market
Furniture
Armchair on Casters Market
Furniture
Eco-Friendly Furniture Market