
 Contract Furniture Market | 2026-2036
Contract Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Contract Furniture Market Analysis
Modular workstation bundling is realigning how corporate buyers evaluate total cost of ownership against piecemeal procurement. Steelcase leverages integrated systems thinking to anchor its position in enterprise accounts. MillerKnoll sustains design credibility through R&D intensity across seating and architectural interiors. Haworth competes on manufacturing scale in North American commercial real estate corridors.
Contract furniture encompasses durable, specification-grade furnishings engineered for commercial environments, typically meeting ANSI/BIFMA performance standards for load capacity, cycle durability, and flame resistance. These products serve workplaces, healthcare settings, educational campuses, and hospitality venues where intensive use demands structural integrity beyond residential grades. Seating commands the largest value pool among product types, while lounge furniture represents the fastest-growing category as collaborative office layouts displace traditional cubicle arrangements. Wood and metal materials dominate current specification volumes, though upholstery is gaining share in premium hospitality and executive office segments.
The EPA oversees formaldehyde emissions standards under TSCA Title VI, affecting composite wood substrates used in desks and tables. BIFMA level and GREENGUARD certifications shape procurement eligibility for federal and institutional buyers across the United States. The EU Ecodesign Directive and REACH chemical restrictions constrain material choices for European contract furniture imports. Stakeholders must monitor evolving extended producer responsibility frameworks and embodied-carbon disclosure rules that will soon determine specification access in major commercial construction markets.
Market Dynamics
Workplace retrofit cycles across North America and Europe are compressing replacement timelines as hybrid occupancy models force rapid reconfiguration of floorplates. Corporate real estate teams now prioritize furniture systems that adapt to fluctuating density rather than fixed installations.
Growth Catalysts
- LEED Certification Requirements:Federal and institutional procurement mandates in the United States now require GREENGUARD or BIFMA level credentials. This redirects specification volume toward certified manufacturers with verified supply chains.
- Ergonomic Workstation Mandates:Corporate offices across Germany and the United States are expanding procurement of adjustable-height desks and task seating. Insurance liability frameworks now reward employers who document musculoskeletal risk reduction.
- Non-Residential Construction Recovery:China, Germany, and the United States lead commercial building permits and adaptive reuse projects. These markets concentrate demand for specification-grade furnishings in hospitality, healthcare, and education verticals.
Market Restraints
- Composite Wood Substrate Costs:EPA formaldehyde emissions standards under TSCA Title VI constrain panel sourcing. Domestic certified substrate capacity remains concentrated among a limited supplier base in the southeastern United States.
- REACH Chemical Restrictions:The EU Ecodesign Directive and ECHA substance limitations block certain flame retardants and surface treatments. European contract furniture imports face compliance verification delays at port of entry.
- Steel and Aluminum Volatility:Frame and base components remain exposed to commodity price swings. Long-term procurement contracts for metal-intensive seating and table systems carry margin compression risk.
Strategic Opportunities
- Healthcare-Acquired Infection Standards:Antimicrobial surface specifications are expanding in hospital and clinic furnishings. Copper-infused laminates and non-porous solid surfaces command premium positioning in patient room and waiting area applications.
- Extended Producer Responsibility Frameworks:Emerging take-back mandates in California and the European Union create service revenue streams. Manufacturers who establish refurbishment and material recovery infrastructure secure preferred vendor status.
- Collaborative Lounge Systems:Hospitality and technology campus clients in China and the United States are displacing traditional workstations with soft seating clusters. Modular upholstery platforms with integrated power and data distribution capture specification share.
Industry Challenges
- Embodied-Carbon Disclosure Requirements:Environmental product declarations and lifecycle assessments now determine eligibility for major commercial construction projects. Smaller manufacturers lack capital to fund third-party verification and database integration.
- Fire-Safety Standard Harmonization:Divergent test methods between CAL 133, NFPA 260, and EN 1021 create redundant certification costs. Upholstery suppliers must maintain parallel testing protocols for multi-national accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract Furniture Market |
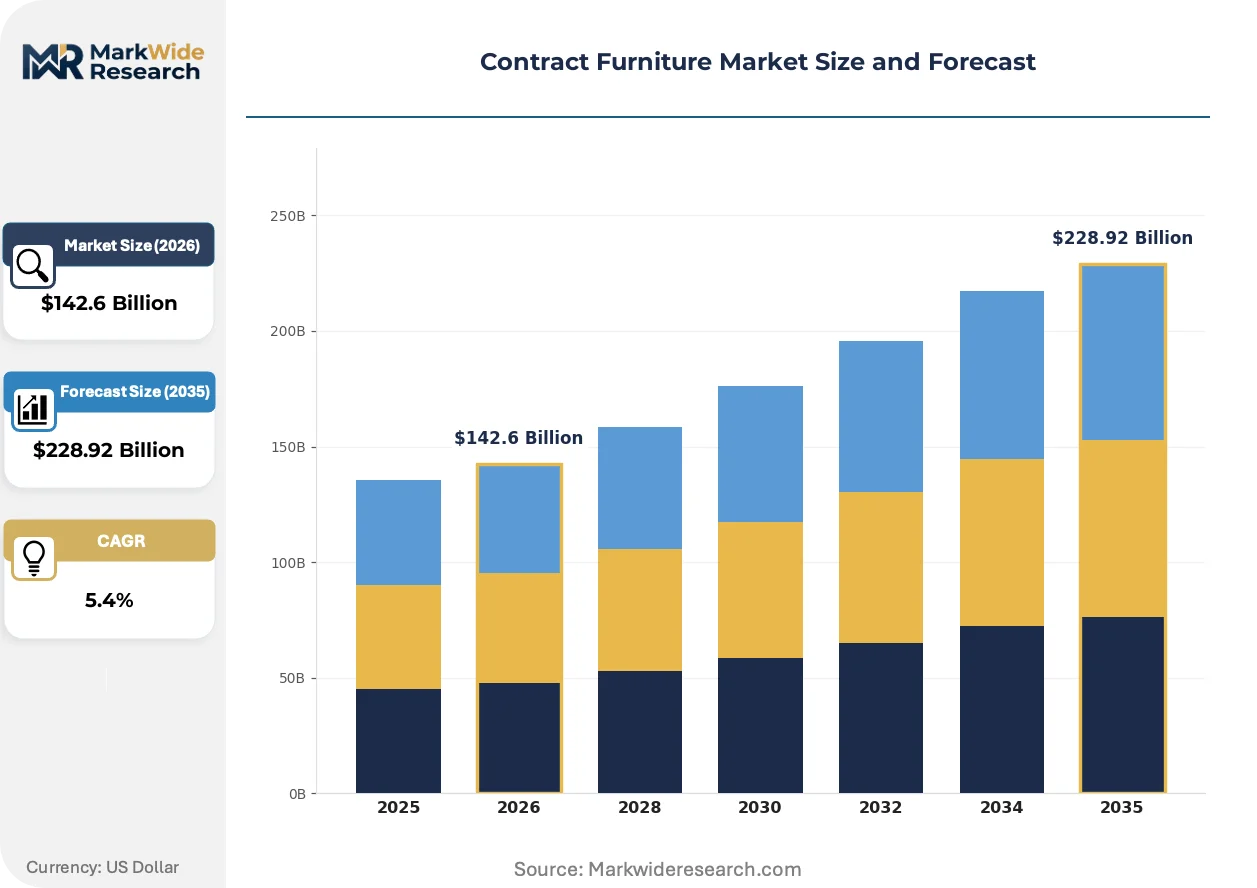
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $228.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Desks, Lounge Furniture End User: Corporate Offices, Educational Institutions, Healthcare Facilities, Hotels Material: Wood, Metal, Plastic, Upholstery Distribution Channel: Direct Sales, Online Retail, Showrooms, Wholesalers |
| Companies Covered | HNI Corporation, Kinnarps AB, Steelcase, OFS Brands Holdings, Teknion Corporation, MillerKnoll, Kimball International, Global Furniture Group, Haworth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract Furniture Market Emerging Trajectories
Material science advances and procurement digitization are restructuring how contract furniture moves from specification to installation. Three developments merit particular attention.
Smart furniture systems with embedded occupancy sensors and environmental monitors are overtaking passive furnishings in premium workplace deployments. Technology companies and financial services firms in the United States and Germany now specify desks and meeting tables with integrated IoT infrastructure. These installations generate real estate utilization data that justifies furniture expenditure through space optimization metrics rather than aesthetic or durability claims alone.
The EU Ecodesign Directive's expanding scope now covers furniture durability and repairability requirements. Manufacturers serving European markets must design for disassembly and component replacement rather than obsolescence. Upholstery and seating categories face the most stringent documentation burdens, with modular construction becoming a de facto compliance strategy for market access.
Enterprise buyers are consolidating vendor relationships around integrated workplace ecosystem contracts. Single-source accountability for seating, architectural interiors, and technology-integrated furniture is displacing fragmented specification across multiple suppliers. This concentration is most visible in United States corporate headquarters relocations and China technology campus developments, where facilities teams prioritize simplified project management over brand diversity.
Contract Furniture Market Segmentation
Contract furniture procurement follows distinct specification pathways that vary by facility type, material compliance requirements, and channel access. Understanding these segment boundaries clarifies where manufacturers must build certification depth versus where price competition dominates.
Product Type:
Replacement cycles differ sharply across product categories, with seating and workstations facing accelerated refresh timelines as hybrid work models destabilize traditional floorplate assumptions.
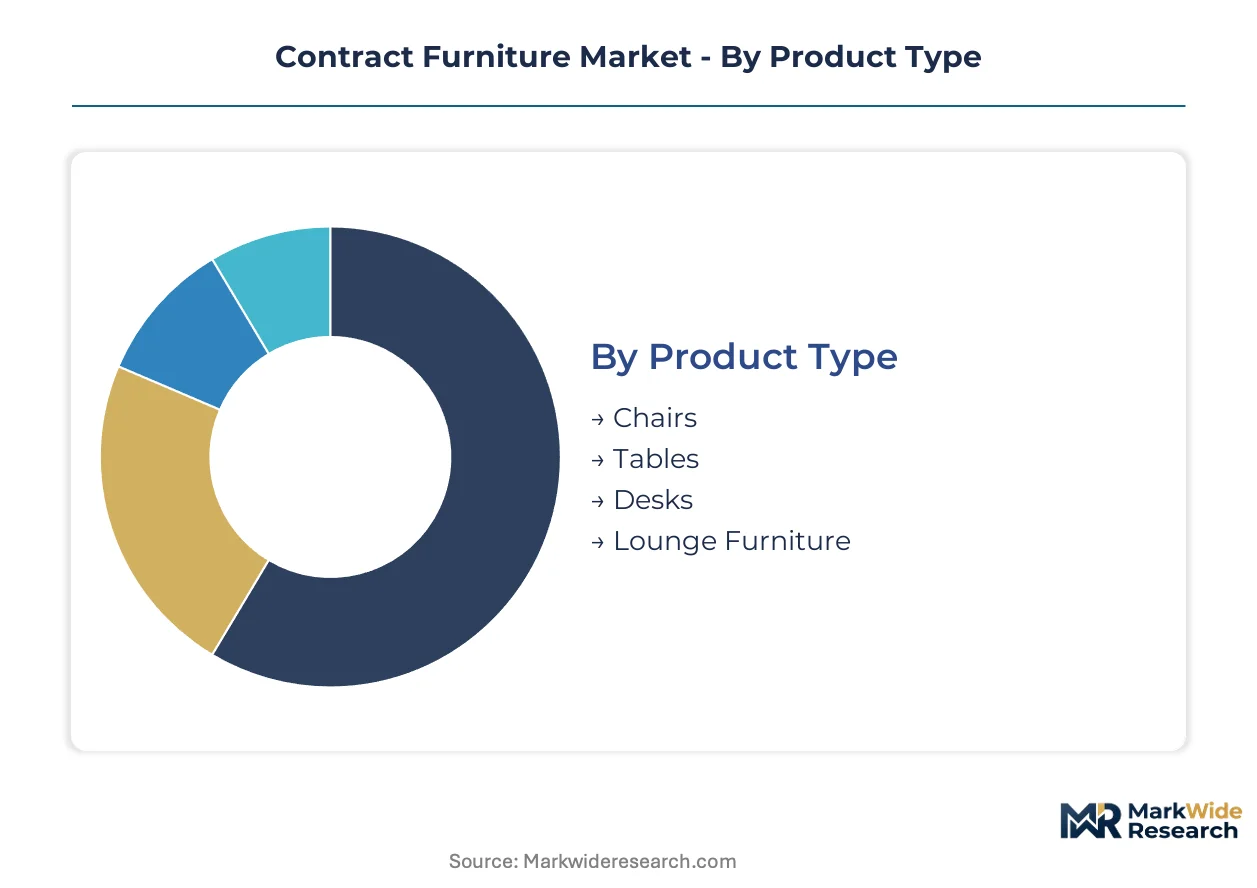
- Chairs:Task and executive seating engineered to ANSI/BIFMA X5.1 standards for cycle durability and load capacity. Corporate offices in the United States and Germany are expanding procurement of adjustable ergonomic models as insurance frameworks reward documented musculoskeletal risk reduction.
- Lounge Furniture:Soft seating systems with integrated power and data distribution for collaborative zones. Technology campuses in China and hospitality venues across the United States are displacing traditional workstations with modular upholstery platforms.
- Tables:Conference and training surfaces spanning laminate, veneer, and solid substrate constructions.
- Desks:Height-adjustable workstations and fixed-height casegoods for individual and shared occupancy.
Chairs sits at the top of the volume ranking, with Lounge Furniture climbing the fastest.
End User:
Cost tier differentiation separates specification-grade procurement from commodity purchasing, with federal and institutional buyers facing mandatory certification thresholds that premium manufacturers exploit.
- Corporate Offices:Enterprise accounts consolidating vendor relationships around integrated workplace ecosystem contracts. United States headquarters relocations and China technology campus developments prioritize single-source accountability for seating, architectural interiors, and technology-integrated furniture.
- Healthcare Facilities:Patient room, waiting area, and clinical furnishings subject to antimicrobial surface specifications. Copper-infused laminates and non-porous solid surfaces command premium positioning as infection control standards tighten.
- Educational Institutions:K-12 and higher education campuses with extended replacement cycles and competitive bidding requirements.
- Hotels:Guest room and public area furnishings balancing durability claims with aesthetic differentiation for brand positioning.
Corporate Offices commands the largest revenue pool, while Healthcare Facilities is expanding most quickly on infection-control specification premiums.
Material:
Supply concentration for certified substrates constrains specification access, with EPA formaldehyde emissions standards under TSCA Title VI limiting domestic panel sourcing to a concentrated southeastern United States supplier base.
- Wood:Composite panels, veneers, and solid lumber meeting emissions and fire-safety standards. Desks and tables in corporate and education verticals dominate consumption, though substrate cost volatility pressures margin structures.
- Upholstery:Fabric, leather, and synthetic coverings for seating and lounge applications. Premium hospitality and executive office segments are gaining share as tactile quality becomes a specification differentiator.
- Metal:Steel and aluminum frame and base components exposed to commodity price swings.
- Plastic:Polymer shells, glides, and component parts for cost-optimized product lines.
Wood retains the highest specification volume, with Upholstery gaining share fastest on premium segment expansion.
Distribution Channel:
Customer type fragmentation separates enterprise direct relationships from project-based specification, with facilities teams and design firms operating through distinct procurement pathways.
- Direct Sales:Manufacturer-employed specification consultants serving enterprise accounts and major projects. Steelcase, MillerKnoll, and Haworth anchor positions through integrated systems thinking and R&D intensity.
- Showrooms:Physical specification centers where tactile evaluation and space planning services support design firm relationships. Urban concentrations in Chicago, New York, and Los Angeles serve North American commercial real estate corridors.
- Wholesalers:Regional distributors stocking standard configurations for accelerated delivery timelines.
- Online Retail:Digital specification platforms capturing small-project and replacement-part demand.
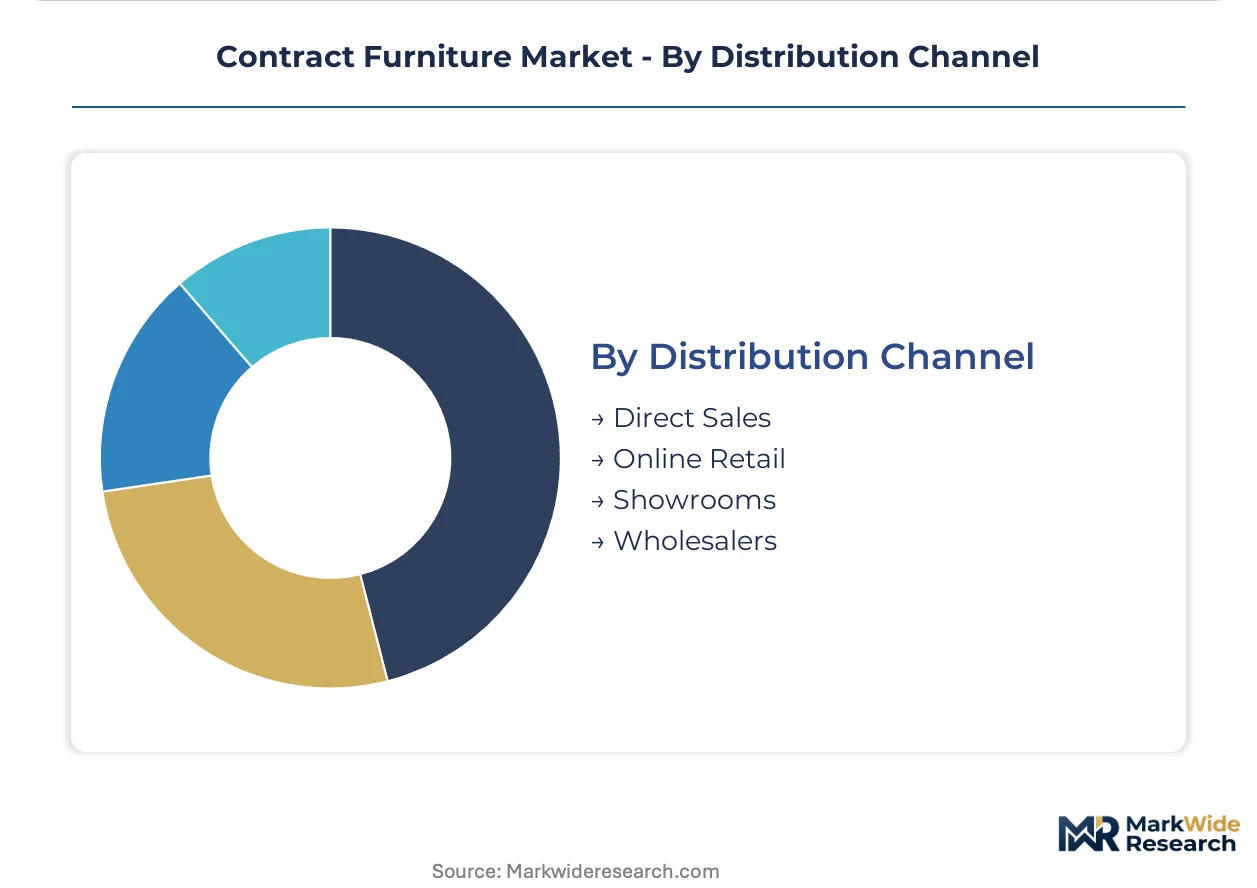
Direct Sales captures the highest-value transactions, with Showrooms retaining specification influence in design-driven segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The contract furniture industry traces its modern origins to Grand Rapids, Michigan, where mass-production techniques for commercial-grade wood furnishings emerged in the early twentieth century. This manufacturing heritage established durable construction standards that now govern specification-grade procurement across corporate, healthcare, and educational facilities worldwide.
United States
Corporate headquarters relocations and technology campus developments in Austin, Seattle, and Raleigh-Durham are compressing furniture replacement cycles. EPA formaldehyde emissions standards under TSCA Title VI constrain panel sourcing to certified southeastern suppliers. The Chicago metropolitan area anchors North American specification activity through concentrated showroom infrastructure and design firm relationships.
Germany
Ergonomic workstation mandates from employer liability insurers are accelerating adjustable-height desk procurement across Frankfurt, Munich, and Berlin corporate offices. The EU Ecodesign Directive's durability requirements are redirecting specification toward modular, repairable systems. Baden-Württemberg's precision manufacturing cluster supplies metal frame components to contract seating producers serving European institutional buyers.
China
Technology campus developments in Shenzhen, Hangzhou, and Chengdu are displacing traditional workstations with collaborative lounge systems. National dual carbon goals are pressuring manufacturers toward embodied-carbon disclosure compliance. The Yangtze River Delta concentration of composite panel fabricators faces tightening MEE environmental enforcement on substrate emissions.
United Kingdom
Adaptive reuse of commercial buildings in London, Manchester, and Birmingham is generating retrofit-driven furniture demand. REACH chemical restrictions through ECHA constrain upholstery flame retardant specifications. The Southeast England logistics corridor enables rapid-response distribution for project-based procurement timelines.
Canada
Federal government procurement mandates requiring GREENGUARD certification are filtering specification volume toward verified supply chains. Toronto and Vancouver commercial construction permits are concentrating demand for healthcare and educational furnishings. Health Canada guidance on indoor air quality influences material selection for institutional interiors.
Contract Furniture Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and specification consulting capability. The vendor base organizes into three tiers: integrated systems providers with direct sales infrastructure, regional fabricators competing on accelerated delivery, and import-dependent distributors serving price-sensitive segments. Dominant competitive moves include enterprise account consolidation around single-source ecosystem contracts and backward integration into certified substrate production.
Within the integrated systems tier, Steelcase and MillerKnoll exemplify specification-grade positioning through R&D intensity and architectural interior capabilities. Haworth occupies a scale-driven position in North American commercial real estate corridors. These three entities represent the archetype of manufacturer-employed consulting teams serving enterprise facilities decisions.
| Leading Market Players |
|---|
| HNI Corporation |
| Kinnarps AB |
| Steelcase |
| OFS Brands Holdings |
| Teknion Corporation |
| MillerKnoll |
| Kimball International |
| Global Furniture Group |
| Haworth |
| Others |
Supply Flow & Price Mechanics
Enterprise consolidation around single-source ecosystem contracts is forcing manufacturers to absorb certification and compliance costs that previously fragmented across multiple vendors, compressing margin structures in standard-tier seating and workstation categories while premium integrated systems retain pricing power through specification consulting depth.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract furniture procurement, with certification grade and volume scale as the primary differentiation drivers. GREENGUARD and BIFMA level credentials command 15-25% premiums in federal and institutional accounts. Pricing pressure stems from steel and aluminum commodity volatility feeding into frame and base component costs. Educational institutions and small-project buyers exhibit highest price sensitivity, while corporate headquarters relocations and technology campus developments prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Domestic-content mandates in United States federal procurement and emerging European Union extended producer responsibility frameworks are reshaping sourcing toward certified southeastern panel fabricators and Baden-Württemberg metal component suppliers. Composite wood substrates, steel tubing, and upholstery textiles draw from concentrated supplier bases in the United States, Germany, and China. Single-source vulnerability runs through EPA TSCA Title VI certified substrate capacity. Distribution runs through manufacturer-direct specification consultants for enterprise accounts, with showrooms and regional wholesalers serving project-based procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in manufacturers who capture premium-tier specification share through certification depth while standard-tier players face cost-down pressure from commodity volatility and buyer consolidation.
For Market Incumbents: Lock in enterprise account retention by deepening backward integration into certified composite panel production and expanding architectural interior capabilities beyond seating. Emerging regional fabricators with accelerated delivery models threaten mid-market share in North American commercial real estate corridors. Prioritize GREENGUARD and BIFMA level credential maintenance as federal procurement gates tighten. For New Entrants and Emerging Players: Embedded sensor infrastructure for smart furniture systems offers a technology-first wedge into premium workplace deployments in United States technology corridors and German financial services centers. Healthcare-acquired infection standards present the most penetrable specification pathway, with antimicrobial surface credentials still sparse among mid-tier manufacturers. Pursue copper-infused laminate partnerships and non-porous solid surface distribution agreements as go-to-market anchors. For Investors and Strategic Acquirers: Asymmetric upside sits with regional fabricators possessing certified substrate access and refurbishment infrastructure positioning for extended producer responsibility mandate capture. Five-to-ten year viability hinges on embodied-carbon disclosure compliance capabilities as major commercial construction projects gate specification eligibility. Watch for California and European Union take-back mandate implementation timelines as inflection signals for service revenue model validation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Substrate Production | EPA TSCA Title VI compliance secures specification access in federal and institutional procurement. |
| Smart Furniture Systems Development | Embedded IoT infrastructure captures premium workplace specification in technology and financial services sectors. |
| Antimicrobial Surface Certification | Copper-infused laminates command premium positioning as healthcare infection control standards tighten. |
| Refurbishment Infrastructure Buildout | Extended producer responsibility mandates in California and the European Union create recurring service revenue streams. |
| Architectural Interior Capability Expansion | Single-source ecosystem contracts favor manufacturers spanning seating, workstations, and architectural product categories. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facilities directors at Fortune 500 headquarters, healthcare procurement managers, educational institution purchasing officers, and contract furniture specification consultants with secondary validation through EPA regulatory filings, BIFMA certification databases, United States Census Bureau construction permits, and EU Ecodesign Directive documentation. Bottom-up product category volume estimates and top-down macroeconomic construction indicators underwent iterative triangulation.
Historical reference periods anchored the projection horizon to pre-pandemic baseline utilization patterns and post-hybrid-work reconfiguration cycles. Segmentation modeling spanned product type, end-user vertical, material specification, and distribution channel dimensions. CAGRs derived from regression analysis against non-residential construction indices and workplace retrofit cycle frequencies. Steel and aluminum commodity price trajectories, formaldehyde emissions compliance cost curves, and embodied-carbon disclosure adoption rates served as industry-specific forecast inputs.
The model holds under steady regulatory enforcement and continued hybrid work normalization; deviation in commodity price spikes or accelerated extended producer responsibility implementation would shift volume and value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Outdoor Furniture and Grills Market
Furniture
Global Multifunctional Furniture Market
Furniture
Upholstered Furniture Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market
Furniture
Netherlands Home Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
Armchair on Casters Market
Furniture
Kids Furniture Market
Furniture
Europe Home Furniture Market
Furniture
Europe Sustainable Furniture Market
Furniture
Europe Multifunctional Furniture Market
Furniture
France Furniture Market
Furniture
Europe School Furniture Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
Kids and Nursery Furniture Market