
 Italy Office Furniture Market | 2026-2036
Italy Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Office Furniture Market Foresight
UNI EN 527 certification for office desks and workstations is reorganizing competitive access in the Italy office furniture sector. Poltrona Frau leverages its heritage leathercraft expertise to dominate premium executive seating. Frezza anchors its position through modular system specialization for open-plan environments. Pedrali competes via advanced polymer engineering and automated manufacturing scale.
Italy office furniture encompasses desks, chairs, storage systems, and spatial partitions engineered for ergonomic performance, durability, and aesthetic integration within commercial interiors. Products typically incorporate steel frames, engineered wood substrates, upholstery foams rated for fire resistance, and surface finishes meeting scratch and chemical exposure thresholds for intensive daily use. Desks and chairs represent the volume core, with partitions capturing expanding margin pools as hybrid-work floorplans demand reconfigurable spatial solutions. Metal and wood materials sustain dual leadership, though plastic components gain share in cost-optimized and lightweight product lines.
Italy's Ministry of Enterprise and Made in Italy enforces product safety through UNI standards alignment, while EU Ecodesign requirements and REACH chemical restrictions shape material sourcing and finish specifications. BIS compliance for imported components adds a secondary compliance layer for supply chains sourcing hardware from outside the European Economic Area. Stakeholders must monitor evolving EU taxonomy criteria for sustainable products, as these will increasingly gate public procurement eligibility and large corporate RFP access.
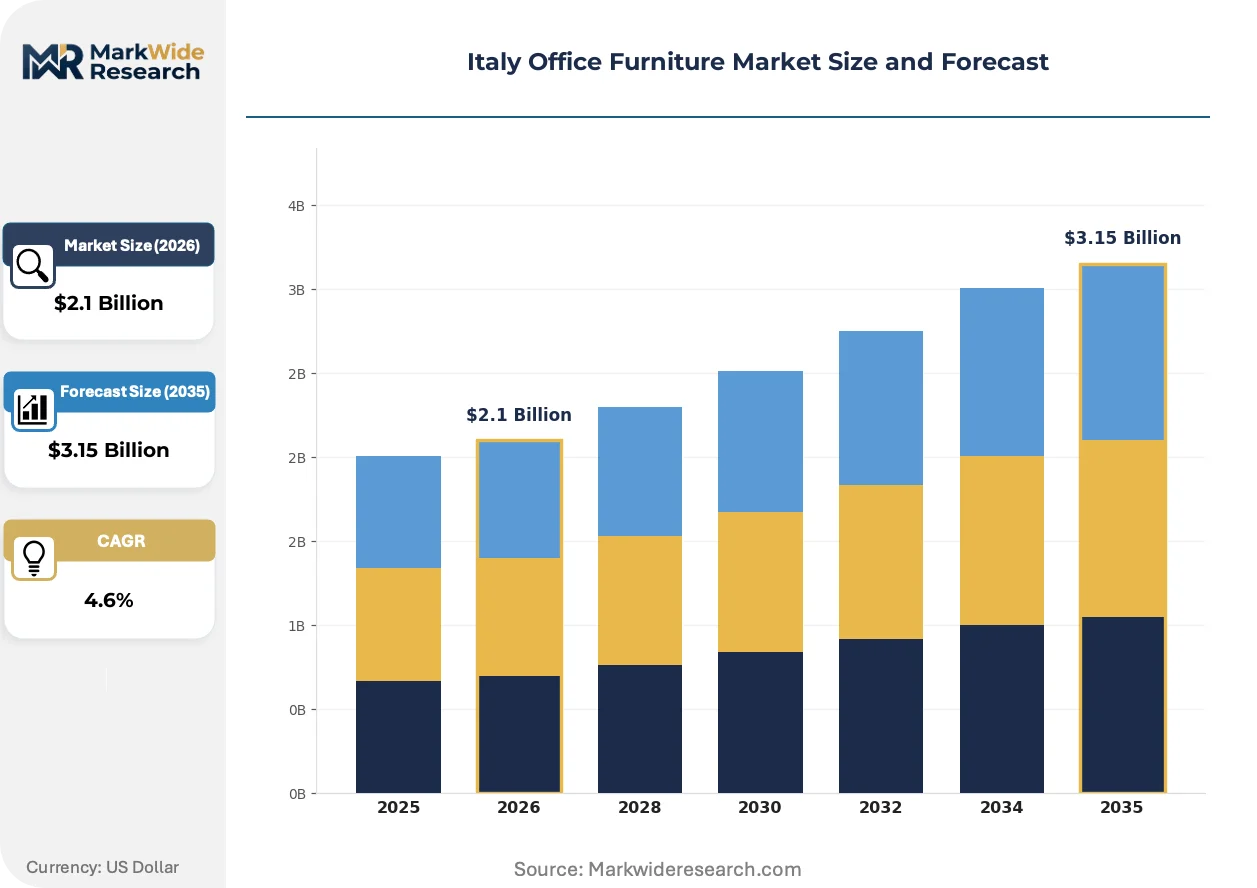
Market Dynamics
Corporations across Lombardy and Emilia-Romagna are dismantling fixed cubicle layouts in favor of reconfigurable spatial systems, compressing replacement cycles from ten-year horizons to three-to-five-year refresh mandates.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Certification requirements for recycled content and carbon footprint disclosure are unlocking public procurement contracts for compliant Italian manufacturers.
- Hybrid work floorplan redesign:Milan-based corporate headquarters are procuring modular workstation systems that accommodate alternating in-office schedules.
- Biophilic material integration:Engineered wood substrates with FSC chain-of-custody certification are displacing conventional particleboard in premium seating and desk lines.
Market Restraints
- Steel and aluminum input volatility:Frame-grade metal pricing fluctuations compress margin stability for mid-tier producers dependent on spot-market sourcing.
- Polymer feedstock concentration:Specialized engineering plastics for ergonomic components rely on a narrow supplier base concentrated in Northern European petrochemical corridors.
- REACH chemical restriction compliance:Flame-retardant upholstery foam reformulation timelines extend product development cycles by eight to fourteen months.
Strategic Opportunities
- Southern Italy commercial real estate expansion:Naples and Bari office construction pipelines remain undersupplied with design-certified furniture relative to Northern saturation.
- Leasing-as-a-service models:Corporate clients in Rome are piloting subscription-based workstation provisioning with maintenance and refresh guarantees.
- Digital fabrication convergence:Parametric design software paired with CNC routing equipment enables batch-one customization at near-mass-production economics.
Industry Challenges
- UNI EN 527 certification backlog:Testing laboratory capacity constraints delay market entry for new workstation designs by four to seven months.
- Legacy ERP integration friction:Established manufacturers struggle to synchronize automated production lines with customer-configurator platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Office Furniture Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Cabinets, Partitions Material: Wood, Metal, Plastic, Glass End User: SMEs, Corporations, Government, Startups Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Leyform, Poltrona Frau, Frezza, Prof, Cavallini1920, ICF, UniFor, Pedrali, Quinti, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Office Furniture Market Shifts & Advancements
Active workspace technologies and circular material flows are compressing traditional product lifecycles while elevating performance specifications for durability and adaptability.
Sensor-embedded furniture is bifurcating the seating and desk categories into connected and passive product lines. Large corporate buyers in Milan are specifying occupancy-tracking chairs and height-adjustable desks with usage analytics for space optimization. This technology is bifurcating procurement decisions between premium connected suites and cost-optimized standard configurations.
Italy's Ministry of Enterprise alignment with EU taxonomy criteria for sustainable products is mandating environmental performance declarations for public tenders. Manufacturers must document recycled content percentages and end-of-life recyclability pathways to qualify for institutional contracts. The workstation and storage system segments are responding fastest, with several Lombardy-based producers achieving PEFCR-compliant product footprints ahead of enforcement deadlines.
Facility managers are consolidating vendor relationships to reduce specification complexity and streamline maintenance protocols. Single-source contracts covering seating, desking, and spatial partitioning are displacing multi-supplier arrangements in Rome and Turin corporate campuses. This concentration is most visible among financial services and professional services tenants renewing five-year lease terms.
Italy Office Furniture Market Segmentation
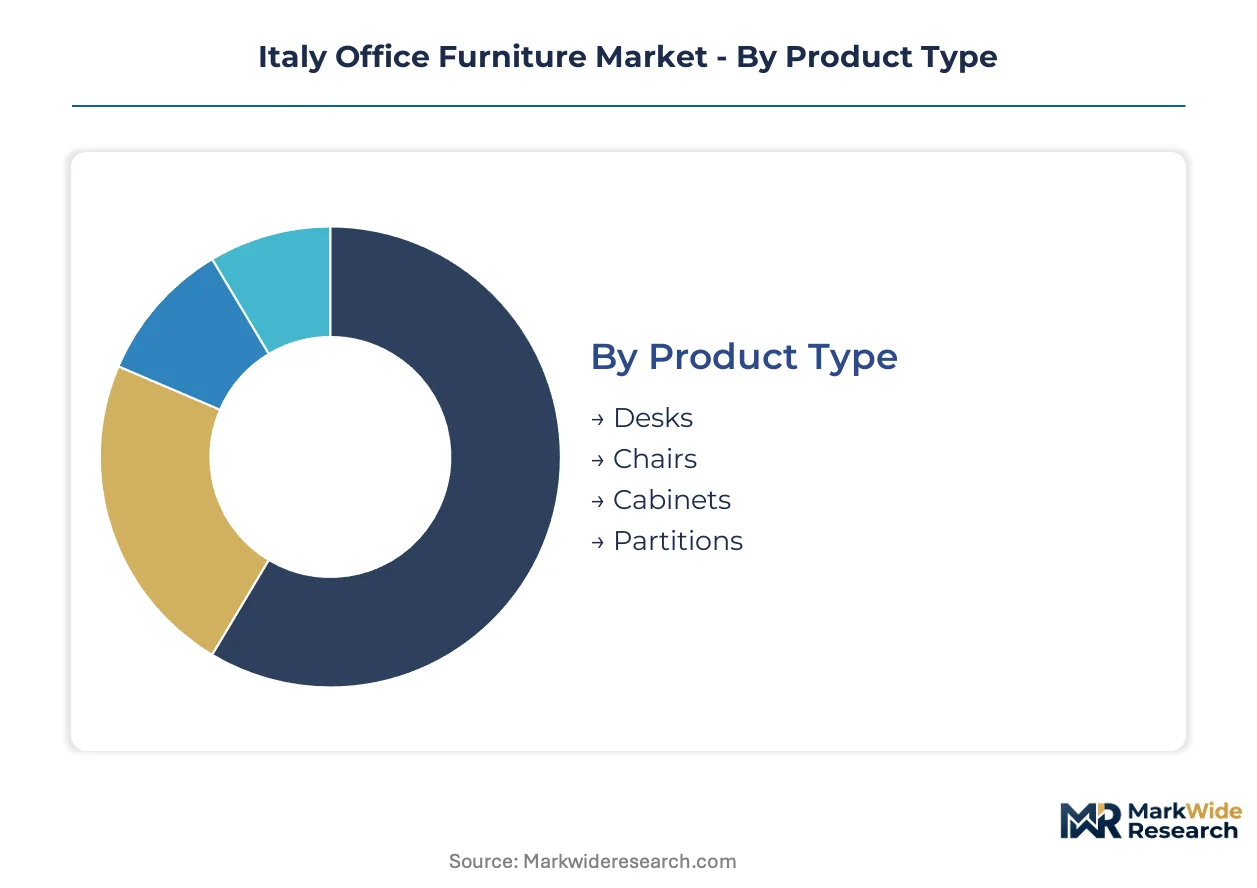
Segmentation in the Italy office furniture sector exposes how procurement decisions split across certification tiers, material sourcing constraints, and workspace configuration mandates. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer positioning.
Product Type:
UNI EN 527 certification requirements and ergonomic performance standards create divergent compliance burdens across workstation categories.
- Desks:Height-adjustable and fixed-height configurations incorporating steel frames and engineered wood substrates dominate procurement volumes. Corporations in Milan's Lombardy district are specifying sit-stand mechanisms with integrated cable management to accommodate hybrid work schedules.
- Chairs:Executive seating with leather upholstery and task chairs with polymer frames represent distinct price-performance tiers. Poltrona Frau's heritage leathercraft expertise anchors premium executive demand, while ergonomic task seating concentrates in open-plan corporate renewals across Rome and Turin.
- Cabinets:Vertical storage and lateral filing systems with steel construction and fire-resistant finishes serve compliance-intensive sectors. Government tenders in Naples require BIS-certified hardware for institutional installations.
- Partitions:Reconfigurable spatial systems with aluminum frames and fabric or glass infill panels capture expanding specification in hybrid floorplans. Frezza's modular specialization targets this segment through rapid-deployment mounting systems.
Desks handle the majority of throughput; partitions are expanding most quickly on share.
Material:
REACH chemical restrictions and EU Ecodesign recycled-content mandates are restructuring material sourcing economics across the supply base.
- Wood:Engineered substrates with FSC chain-of-custody certification are displacing conventional particleboard in premium lines. Pedrali's automated manufacturing scale leverages certified wood sourcing for batch-one customization at competitive unit economics.
- Metal:Frame-grade steel and aluminum provide structural integrity for workstations and storage systems. Steel input volatility compresses margin stability for mid-tier producers dependent on spot-market sourcing rather than contracted volumes.
- Plastic:Advanced polymer engineering enables lightweight ergonomic components and cost-optimized product lines. Specialized engineering plastics rely on a narrow supplier base concentrated in Northern European petrochemical corridors.
- Glass:Tempered and laminated glass infill panels serve aesthetic and acoustic partitioning requirements in executive environments. Glass integration elevates specification in Milan corporate headquarters seeking spatial transparency.
Metal sustains volume leadership; wood is climbing the fastest on certified-sourcing demand.
End User:
Procurement scale and specification complexity vary sharply across organizational types, with public tenders imposing distinct compliance layers.
- SMEs:Cost-optimized configurations with shorter replacement cycles and standardized dimensions dominate. Regional furniture distributors in Emilia-Romagna serve this segment through catalog-based specification and rapid fulfillment.
- Corporations:Large-scale renewals with integrated facility management contracts and multi-year refresh guarantees. Milan-based financial services tenants are consolidating vendor relationships to single-source arrangements covering seating, desking, and partitioning.
- Government:Public procurement eligibility gated by EU taxonomy criteria for sustainable products and PEFCR-compliant environmental performance declarations. Italy's Ministry of Enterprise alignment mandates recycled content documentation for institutional contracts.
- Startups:Flexible leasing-as-a-service models with maintenance-inclusive provisioning. Rome-based pilot programs are testing subscription-based workstation arrangements with guaranteed refresh cycles.
Corporations anchor procurement value; government contracts are gaining share fastest on regulatory-driven compliance demand.
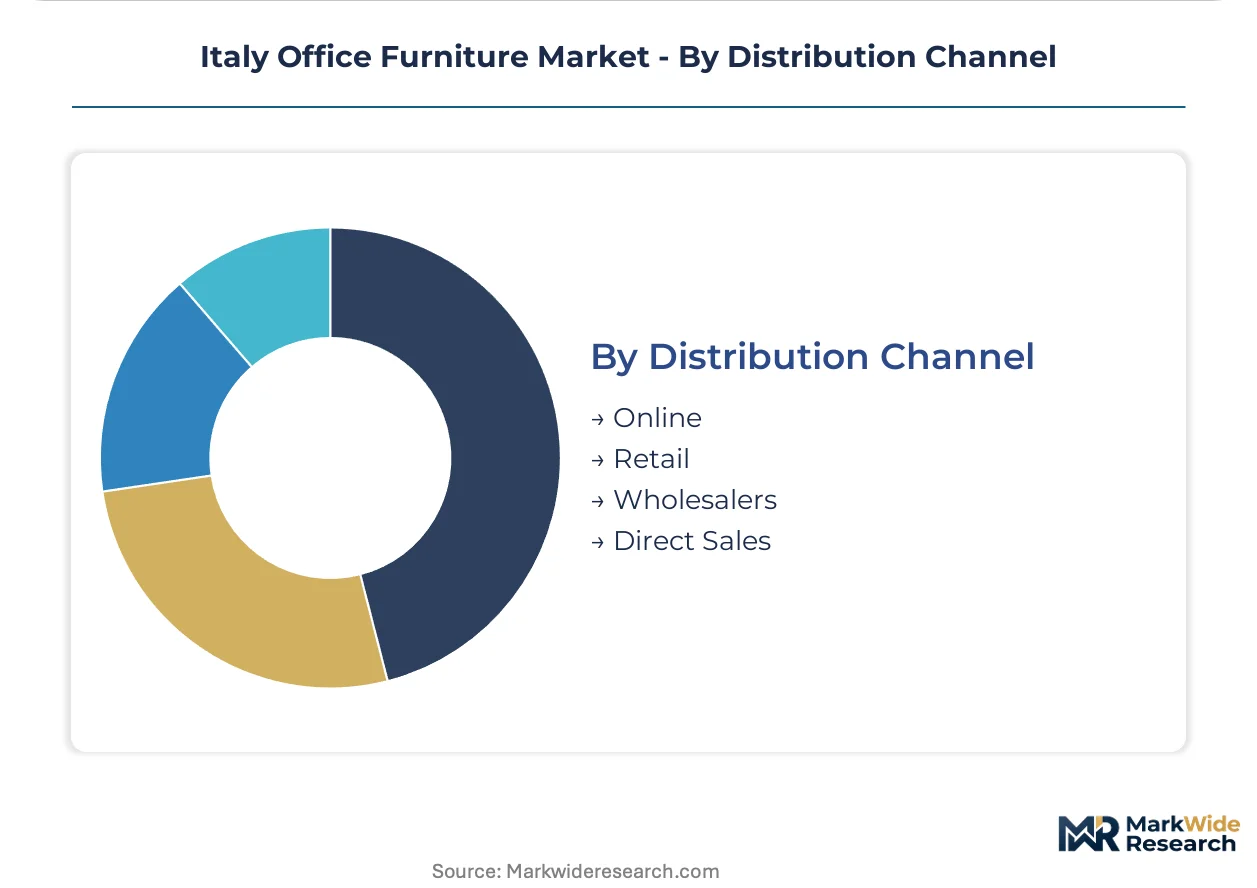
Distribution Channel:
Channel configuration determines specification control, with direct relationships capturing complex hybrid-workfloor configurations.
- Online:Catalog-based procurement for standardized SKUs with configuration tools and volume pricing. Digital platforms serve SME segments with shorter decision cycles and limited customization requirements.
- Retail:Showroom-based specification with tactile evaluation for seating comfort and surface finish quality. Northern Italy design clusters leverage retail presence for architect and designer specification influence.
- Wholesalers:Inventory-holding intermediaries serving regional contractors and facility managers with consolidated logistics. Southern Italy commercial real estate expansion in Naples and Bari remains undersupplied relative to wholesale distribution capacity.
- Direct Sales:Manufacturer-led specification for large-scale corporate and government contracts with integrated project management. Direct relationships capture sensor-embedded furniture and connected workspace technology deployments.
Direct sales command the highest-value contracts; online channels are expanding most rapidly on SME procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Brenner Base Tunnel and Milan-Rome high-speed rail corridor compress logistics cycles between Northern manufacturing clusters and Central-Southern commercial real estate developments. Italy's port system at Genoa and Trieste anchors Mediterranean distribution for engineered wood substrates and steel frame components. This infrastructure underwrites differentiated demand patterns across five sub-regional markets.
Lombardy
Milan's corporate headquarters concentration drives specification for sensor-embedded workstations and modular spatial systems. The Lombardy region enforces UNI EN 527 certification through its regional quality infrastructure, with testing laboratories in Brescia handling workstation compliance. Design clusters around Milan's Porta Nuova and CityLife districts concentrate architect-led procurement for premium executive environments.
Emilia-Romagna
Automotive and machinery corporate offices in Bologna and Modena generate demand for durable task seating and reconfigurable floorplans. The region aligns with EU Ecodesign recycled-content mandates through its industrial waste recovery networks. Furniture distributors in Reggio Emilia serve SME segments with catalog-based rapid fulfillment from consolidated logistics hubs.
Veneto
Tourism and hospitality headquarters in Venice and Verona procure aesthetic-forward partitioning systems for mixed-use office developments. Regional building codes incorporate seismic resistance standards that influence storage system anchoring specifications. The Treviso furniture manufacturing belt supplies cost-optimized seating lines to Northeastern European markets.
Lazio
Rome's government procurement offices gate institutional contracts through EU taxonomy sustainability criteria. The capital's startup ecosystem pilots subscription-based workstation leasing with maintenance-inclusive provisioning. Facility managers in EUR and Tiburtina business districts consolidate vendor relationships to single-source arrangements.
Piedmont
Turin's financial services tenants drive demand for connected workspace technology and premium executive seating. The region's heritage leathercraft infrastructure supports specialized upholstery capacity for contract markets. Corporate renewals in the Lingotto and Aurora districts specify FSC-certified engineered wood substrates for ESG reporting compliance.
Italy Office Furniture Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and distribution channels, producing a bifurcated structure where scale-driven manufacturers anchor volume segments while craftsmanship-based ateliers capture premium specification. The vendor base organizes around three strategic archetypes: heritage leathercraft houses, modular system specialists, and polymer engineering scale players. Competitive moves concentrate on direct sales force expansion for large corporate accounts and automated manufacturing investments to compress batch-one customization economics.
Within the heritage leathercraft tier, Poltrona Frau occupies a position exemplifying premium executive seating specification through craft-based positioning. Modular system specialists include Frezza, which represents rapid-deployment spatial partitioning for open-plan environments. At the polymer engineering end, Pedrali anchors cost-optimized and lightweight product lines through automated manufacturing scale. These three companies illustrate the competitive spectrum from artisanal positioning to industrial efficiency.
| Leading Market Players |
|---|
| Leyform |
| Poltrona Frau |
| Frezza |
| Prof |
| Cavallini1920 |
| ICF |
| UniFor |
| Pedrali |
| Quinti |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for frame-grade steel deliveries from Northern European mills compress margin buffers for mid-tier Italian manufacturers while amplifying pricing power for integrated producers with contracted volumes. This inventory pressure concentrates procurement leverage among Lombardy-based design houses that pre-position engineered wood substrates through Genoa port channels.
Pricing Analysis
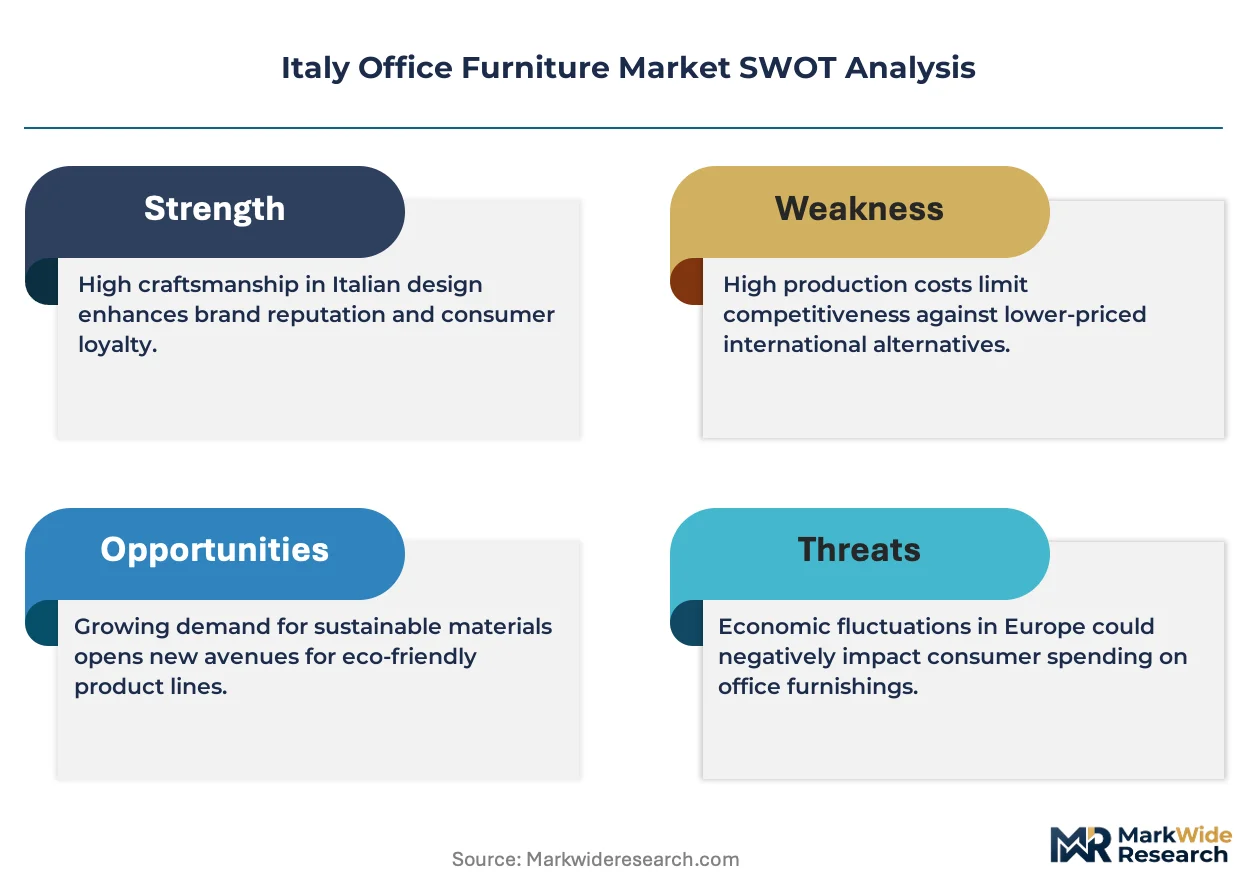
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with certification grade and volume scale as primary differentiation drivers. Premium executive seating from heritage leathercraft houses commands substantial brand premiums, while cost-optimized polymer lines face intensifying compression from steel input volatility. SMEs exhibit highest price sensitivity through catalog-based specification, whereas Milan corporate headquarters prioritize performance bundling over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for BIS-certified hardware sourced outside the European Economic Area. Manufacturing concentration in Italy, Germany, and Poland feeds from steel frame components, engineered wood substrates, and specialized polymer feedstocks. Single-source vulnerability in Northern European petrochemical corridors for engineering plastics creates structural exposure, while distribution runs through direct sales forces for large corporate accounts and wholesale intermediaries for regional SME coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy office furniture sits in a cyclical recovery phase driven by post-pandemic workspace renewal mandates compressing replacement cycles from ten-year to three-to-five-year horizons.
For Market Incumbents: Consolidate vendor relationships through single-source facility management contracts covering seating, desking, and partitioning to defend against emerging leasing-as-a-service entrants. Deepen backward integration into FSC-certified engineered wood substrates to secure margin stability against steel price volatility, while accelerating UNI EN 527 certification investments to gate public procurement access. For New Entrants and Emerging Players: UNI EN 527 certification fast-track programs unlock institutional contract eligibility currently constrained by testing laboratory backlogs. Southern Italy commercial real estate expansion in Naples and Bari presents the most penetrable white space, with subscription-based workstation provisioning offering a differentiated go-to-market angle against established ownership models. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because facility manager vendor concentration trends favor scaled platforms with integrated project management capabilities. Target automated manufacturing specialists with parametric design capabilities for batch-one customization. Watch Southern Italy construction pipeline announcements as the inflection signal for geographic demand shift.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Wood Sourcing | FSC chain-of-custody control secures EU Ecodesign compliance and insulates margin from substrate price volatility. |
| Direct Sales Force Expansion | Manufacturer-led specification captures sensor-embedded furniture deployments in Milan corporate headquarters. |
| Leasing-as-a-Service Model Launch | Subscription provisioning with maintenance guarantees aligns with Rome startup ecosystem pilot programs. |
| Automated Manufacturing Scale-Up | CNC routing investments enable batch-one customization at competitive unit economics for SME segments. |
| UNI EN 527 Certification Investment | Testing laboratory capacity access accelerates market entry and gates public procurement eligibility. |
Research Methodology
A spread of perspectives from furniture manufacturing executives, facility management procurement leads, architect specification directors, and wholesale distribution operators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against UNI standards documentation, EU Ecodesign regulatory filings, and Italian Ministry of Enterprise procurement databases. Bottom-up product segmentation data triangulated against top-down regional construction pipeline indicators.
Segmentation dimensions modeled encompass product type, material certification tier, end-user organization scale, and distribution channel configuration across the projection horizon. CAGRs derived from historical replacement cycle compression patterns and hybrid work floorplan adoption curves, with specific inputs from steel frame pricing indices and engineered wood substrate availability schedules.
Decision-makers should treat outputs as directional under sustained post-pandemic workspace renewal demand and stable EU regulatory enforcement; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
US Contract Furniture and Furnishing Market
Furniture
Italy Furniture Retail Market
Furniture
Mexico Home Furniture Market
Furniture
GCC Furniture Market
Furniture
India Upholstered Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Europe Sustainable Furniture Market
Furniture
North America Free Standing Electrical Height-Adjustable Tables Market
Furniture
School Furniture Market
Furniture
Japan Furniture Market
Furniture
Middle East and Africa Wood Based Panel Market
Furniture
Chaises Longue Market
Furniture
Pedicure Chair Market
Furniture
Entryway Furniture Market
Furniture
Europe Multifunctional Furniture Market
Furniture
Europe Sustainable Mattress Market