
 Special Mission Aircraft Market | 2026-2036
Special Mission Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Special Mission Aircraft Market Intelligence
Aftermarket services and systems integration is reconfiguring the profit landscape for special mission aircraft manufacturers. Prime contractors are shifting focus from one-time platform sales to long-term support contracts and technology upgrades. Lockheed Martin Corporation leverages its deep expertise in advanced sensor platforms to secure high-value contracts for sophisticated ISR missions. In contrast, Textron Aviation Inc. specializes in modifying its proven commercial airframes for a diverse range of surveillance and utility missions, offering cost-effective solutions to a wider customer base.
Special mission aircraft are commercial or military airframes modified to perform specific tasks beyond standard transport or combat. These platforms integrate specialized payloads, including synthetic aperture radar and communication relay systems, into their avionics and structural architecture. The primary purpose is to deliver persistent intelligence and situational awareness for military forces and government agencies. Surveillance and reconnaissance applications constitute the largest mission type, with fixed-wing platforms holding the dominant share due to their superior endurance and payload flexibility compared to rotary-wing alternatives.
Aircraft certification and operational approvals are governed by bodies like the U.S. Federal Aviation Administration (FAA) for civil-derived platforms and specific national military airworthiness authorities. These regulations, alongside ISO quality standards for manufacturing, dictate design, testing, and maintenance protocols, ensuring safety and system interoperability. For vendors and operators, the critical decision point involves balancing investment in next-generation unmanned platforms against the modernization of existing manned fleets for complex mission environments.
Market Dynamics
The central dynamic shaping the special mission aircraft market is the convergence of persistent geopolitical instability with the escalating need for climate-related disaster response, driving parallel demand from both military and civil government agencies for advanced, multi-role aerial platforms.
Growth Catalysts
- Border Security Mandates:Heightened national security focus in regions like Eastern Europe and the South China Sea drives government investment in persistent airborne surveillance platforms for border monitoring and maritime patrol.
- Sensor Miniaturization:Advances in shrinking high-performance payloads, such as synthetic aperture radar, permit integration onto smaller, more cost-effective airframes, expanding the market to new government agencies with limited budgets.
- Disaster Resilience Funding:Increased public investment in disaster preparedness, particularly in countries like Japan and Australia, supports the acquisition of aircraft for roles including aerial firefighting command and control and post-event damage assessment.
Market Restraints
- High Integration Costs:The complexity of integrating bespoke sensor suites and communication systems into existing airframes results in significant non-recurring engineering expenses, which can be prohibitive for budget-constrained operators.
- Stringent Airworthiness Certification:Extensive modifications to civil-derived airframes require lengthy and expensive supplemental type certification processes with bodies like the U.S. FAA or EASA, delaying platform deployment.
- Specialized Payload Scarcity:The supply of mission-critical components, such as advanced electro-optical and infrared sensor turrets, is concentrated among a few specialized vendors, creating potential supply chain bottlenecks.
Strategic Opportunities
- Southeast Asian Maritime Patrol:Nations across Southeast Asia are modernizing maritime surveillance capabilities to monitor exclusive economic zones, presenting an opportunity for vendors offering multi-role patrol aircraft.
- Environmental Monitoring Missions:The expansion of environmental regulations, such as those tracking illegal deforestation in Brazil or monitoring arctic ice melt, creates demand for aircraft equipped with specialized atmospheric and multispectral sensors.
- Unmanned-Manned Teaming:Developing systems for manned-unmanned teaming allows special mission aircraft to serve as command hubs for autonomous systems, creating a new operational paradigm and upgrade pathway for existing fleets.
Industry Challenges
- Sensor Operator Skill Gap:A shortage of trained intelligence analysts and sensor operators capable of managing the data flow from modern ISR platforms limits the operational effectiveness of fielded systems.
- Legacy System Interoperability:Ensuring secure and seamless data exchange between new special mission platforms and existing ground-based command and control infrastructure is a persistent technical hurdle for defense agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Special Mission Aircraft Market |
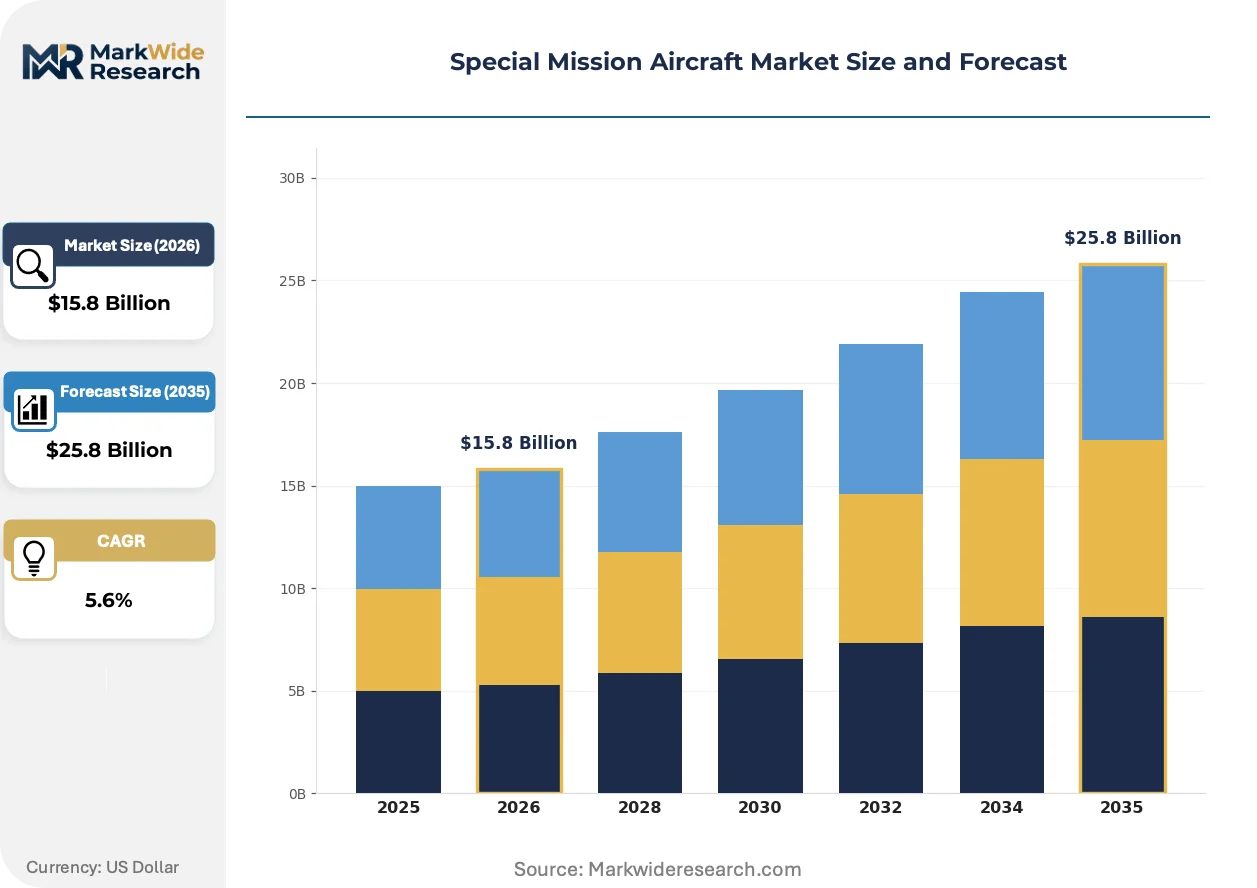
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $25.8 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Fixed Wing, Rotary Wing, Tiltrotor, Unmanned Aerial Vehicle, Lighter-than-Air Mission Type: Surveillance, Reconnaissance, Electronic Warfare, Search and Rescue, Communication Relay End User: Military Forces, Paramilitary Units, Government Agencies, Emergency Responders, Private Security Firms Technology: Radar Systems, Infrared Sensors, Signal Intelligence, Synthetic Aperture Radar, Electronic Countermeasures |
| Companies Covered | The Boeing Company, Lockheed Martin Corporation, Northrop Grumman Corporation, Airbus Defence and Space, Dassault Aviation SA, Textron Aviation Inc., BAE Systems, Leonardo S.p.A., Israel Aerospace Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Special Mission Aircraft Market Strategic Shifts & Innovations
The convergence of digital engineering and modular open systems architecture is transforming how special mission aircraft are designed, sustained, and upgraded. This evolution shifts long-term value from the initial platform sale to through-life capability management and technology insertion.
Digital twin technology creates a virtual replica of an aircraft and its mission systems, enabling predictive maintenance and simulation of potential upgrades. Defense agencies and prime contractors are adopting this approach to reduce physical prototyping requirements and shorten testing timelines. The application of these virtual models is digitizing the entire aircraft lifecycle, from initial design and certification through to operational support and fleet modernization.
Adoption of the Modular Open Systems Approach (MOSA) by the U.S. Department of Defense is a significant architectural driver. This mandate requires new programs to use open, consensus-based interface standards, which prevents vendor lock-in for critical subsystems like radar and communications arrays. Aircraft manufacturers are most affected, compelled to redesign their integration strategies to accommodate components from a wider range of third-party suppliers.
Government customers are increasingly favoring contracting models where they pay for guaranteed flight hours and mission data rather than owning and operating the aircraft. This disrupts the traditional equipment sales model, with specialized service providers fielding contractor-owned, contractor-operated fleets. This trend is most visible in the intelligence, surveillance, and reconnaissance segment for governments that lack the indigenous capacity to manage such complex assets internally.
Special Mission Aircraft Market Segmentation
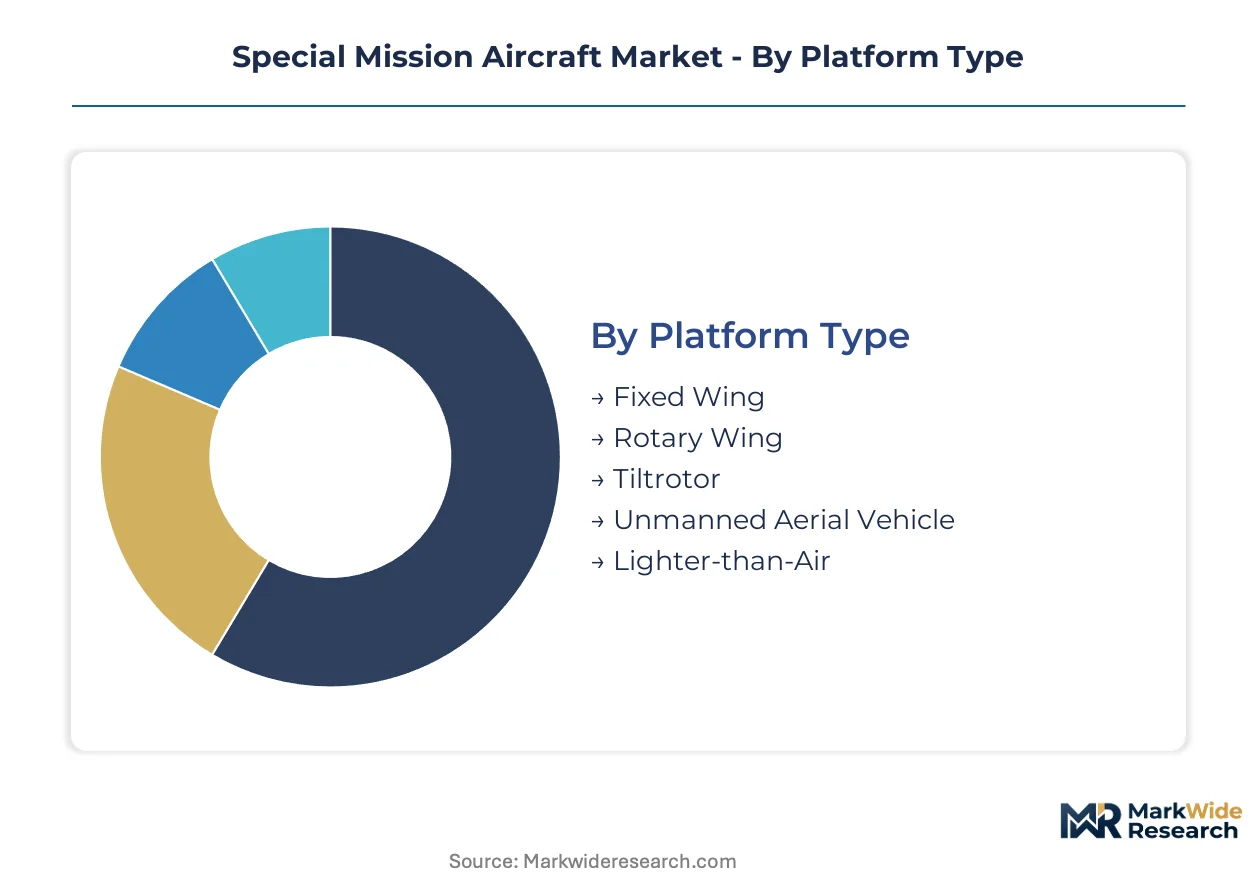
Understanding the distinct segments within the special mission aircraft market is essential for manufacturers and service providers to align their offerings with evolving operational requirements. Specific mission profiles dictate platform choice, payload integration, and maintenance strategies, directly influencing long-term profitability.
Platform Type:
The intensity of after-sales service and ongoing support often varies significantly across different platform types, impacting total cost of ownership for operators.
- Fixed Wing:These platforms, typically modified commercial or military transport aircraft, offer superior endurance, range, and payload capacity for persistent intelligence, surveillance, and reconnaissance (ISR) missions. Demand is strong from military forces in the United States and Australia for wide-area maritime patrol.
- Unmanned Aerial Vehicle:UAVs range from tactical drones to high-altitude, long-endurance systems, providing persistent, often stealthy, surveillance without human risk. Geopolitical instability in Eastern Europe drives procurement of advanced UAVs for border monitoring and target acquisition.
- Rotary Wing:Helicopters provide vertical take-off and landing capabilities, crucial for rapid deployment in search and rescue operations and disaster response.
- Tiltrotor:These aircraft combine the vertical flight capabilities of helicopters with the speed and range of fixed-wing planes, offering unique operational flexibility for specialized forces.
- Lighter-than-Air:Blimps and aerostats offer extremely long endurance and stable platforms for persistent surveillance or communication relay, often at lower operational costs.
Fixed Wing holds the largest share; momentum sits with Unmanned Aerial Vehicle.
Mission Type:
The application focus of special mission aircraft directly shapes the required sensor suites and airframe modifications, influencing design complexity and integration costs.
- Surveillance:This mission involves monitoring activities over land or sea, often utilizing electro-optical, infrared, and radar sensors to gather visual and electronic intelligence. National security mandates in the South China Sea drive investment in advanced surveillance capabilities.
- Reconnaissance:Reconnaissance missions focus on gathering specific intelligence about enemy forces, terrain, or infrastructure, requiring highly specialized sensors and data analysis capabilities. Military modernization programs in India and Japan prioritize sophisticated reconnaissance platforms.
- Electronic Warfare:EW aircraft jam enemy communications, radar, and other electronic systems, or collect electronic intelligence, demanding advanced signal processing and countermeasures.
- Search and Rescue:SAR platforms locate and assist individuals in distress, often equipped with advanced radar, thermal imaging, and communication systems for maritime or terrestrial environments.
- Communication Relay:These aircraft act as airborne communication hubs, extending network range and capacity for ground forces or disaster response teams in remote areas.
Surveillance missions represent the largest segment, with Electronic Warfare showing significant expansion due to evolving military doctrines.
End User:
The customer type significantly influences procurement cycles, budget constraints, and the specific regulatory frameworks governing aircraft operation and data handling.
- Military Forces:National militaries procure special mission aircraft for intelligence, surveillance, reconnaissance (ISR), electronic warfare, and maritime patrol, often requiring highly customized and secure platforms. The United States Department of Defense drives substantial procurement for fleet recapitalization.
- Government Agencies:Non-military government entities, such as border patrol, coast guard, and environmental protection agencies, utilize these aircraft for law enforcement, resource monitoring, and regulatory compliance. Agencies in Canada and Germany invest in platforms for environmental monitoring.
- Paramilitary Units:These units, including national guard and gendarmerie forces, deploy special mission aircraft for border security, internal security, and counter-narcotics operations.
- Emergency Responders:Fire departments, emergency management organizations, and disaster relief agencies use aircraft for aerial firefighting command, damage assessment, and search and rescue.
- Private Security Firms:Specialized private companies offer contract ISR and security services to governments or corporations, often operating contractor-owned, contractor-operated fleets.
Military Forces account for the dominant share, while Emergency Responders exhibit rising demand for disaster resilience funding.
Technology:
Supply concentration and innovation within specific technology areas dictate the performance capabilities and upgrade pathways for special mission aircraft platforms.
- Radar Systems:These include Synthetic Aperture Radar (SAR) and Ground Moving Target Indicator (GMTI) systems, providing all-weather, day-night imaging and tracking capabilities. Integration of advanced radar systems is critical for maritime patrol aircraft in Southeast Asia.
- Infrared Sensors:Electro-optical/infrared (EO/IR) turrets provide high-resolution visual and thermal imaging, essential for detailed surveillance and target identification. Miniaturized IR sensors enable integration onto smaller, more cost-effective airframes.
- Signal Intelligence:SIGINT systems intercept and analyze electronic signals, providing crucial information on enemy communications and radar emissions.
- Synthetic Aperture Radar:SAR creates high-resolution images of the ground regardless of weather conditions or time of day, offering detailed terrain mapping and object detection.
- Electronic Countermeasures:ECM systems actively jam or deceive enemy radar and communication systems, providing self-protection for the aircraft or support for other assets.
Radar Systems currently lead in market adoption, with Infrared Sensors demonstrating rapid technological advancements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for special mission aircraft exhibits varying elasticity across regions. Highly customized military platforms in developed nations command premium pricing, while cost-effective solutions for civil government agencies show greater price sensitivity. Geopolitical tensions and climate-related emergencies drive procurement cycles globally.
United States
Demand for advanced ISR platforms remains strong due to ongoing military modernization programs. The U.S. Department of Defense continually funds fleet recapitalization efforts for its special mission aircraft. Major defense contractors in areas like Fort Worth, Texas, and Palmdale, California, develop and integrate cutting-edge systems.
Japan
Japan prioritizes maritime surveillance and reconnaissance capabilities to monitor its extensive coastlines. The country's Ministry of Defense actively invests in advanced multi-role patrol aircraft to enhance regional security. Major aerospace hubs in Nagoya and Tokyo focus on integrating sophisticated sensor suites into modified commercial airframes.
Germany
Germany focuses on upgrading its special mission fleet for both intelligence gathering and disaster response within Europe. The German Air Force adheres to European Union Aviation Safety Agency (EASA) regulations for its modified civil-derived platforms. Aerospace companies in Bavaria and Hamburg contribute to the development of new electronic warfare and communication relay aircraft.
Australia
Australia requires sophisticated maritime patrol and border surveillance aircraft to protect its vast exclusive economic zone. The Australian Defence Force procures long-endurance platforms under its ongoing defense acquisition programs. Aerospace facilities near Adelaide and Melbourne specialize in modifying COTS aircraft for persistent ISR missions.
India
India's military modernization initiatives drive significant demand for advanced reconnaissance and electronic warfare aircraft. The Ministry of Defence implements policies to boost indigenous defense manufacturing and technology transfer. Public sector undertakings in Bengaluru and Hyderabad are developing and integrating complex mission systems.
Special Mission Aircraft Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the special mission aircraft market. The market structure is highly tiered, with a few large prime contractors dominating the high-end, complex platform integration. Mid-tier specialists focus on niche modifications or specific sensor integrations, while smaller firms often provide component-level technologies. Strategic partnerships and portfolio diversification represent dominant competitive moves among these players.
Among the established prime contractors, Lockheed Martin Corporation exemplifies deep expertise in advanced sensor platforms and securing high-value ISR contracts, particularly within the United States. Textron Aviation Inc. occupies a position as a specialist in modifying proven commercial airframes for diverse surveillance and utility missions, offering cost-effective solutions to a wider customer base. Airbus Defence and Space, a European entity, represents a major player in integrating specialized payloads onto both military and commercial platforms, serving a broad international customer base. These companies collectively anchor the market's capabilities across complex platform development and mission system integration, navigating stringent certification processes.
| Leading Market Players |
|---|
| The Boeing Company |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Airbus Defence and Space |
| Dassault Aviation SA |
| Textron Aviation Inc. |
| BAE Systems |
| Leonardo S.p.A. |
| Israel Aerospace Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Aerospace facilities in Fort Worth, Texas, with their substantial manufacturing capacity, exert significant influence over downstream pricing power for highly customized special mission aircraft platforms. The concentration of advanced integration capabilities within a few prime contractors shapes the cost structure for complex mission systems.
Pricing Analysis
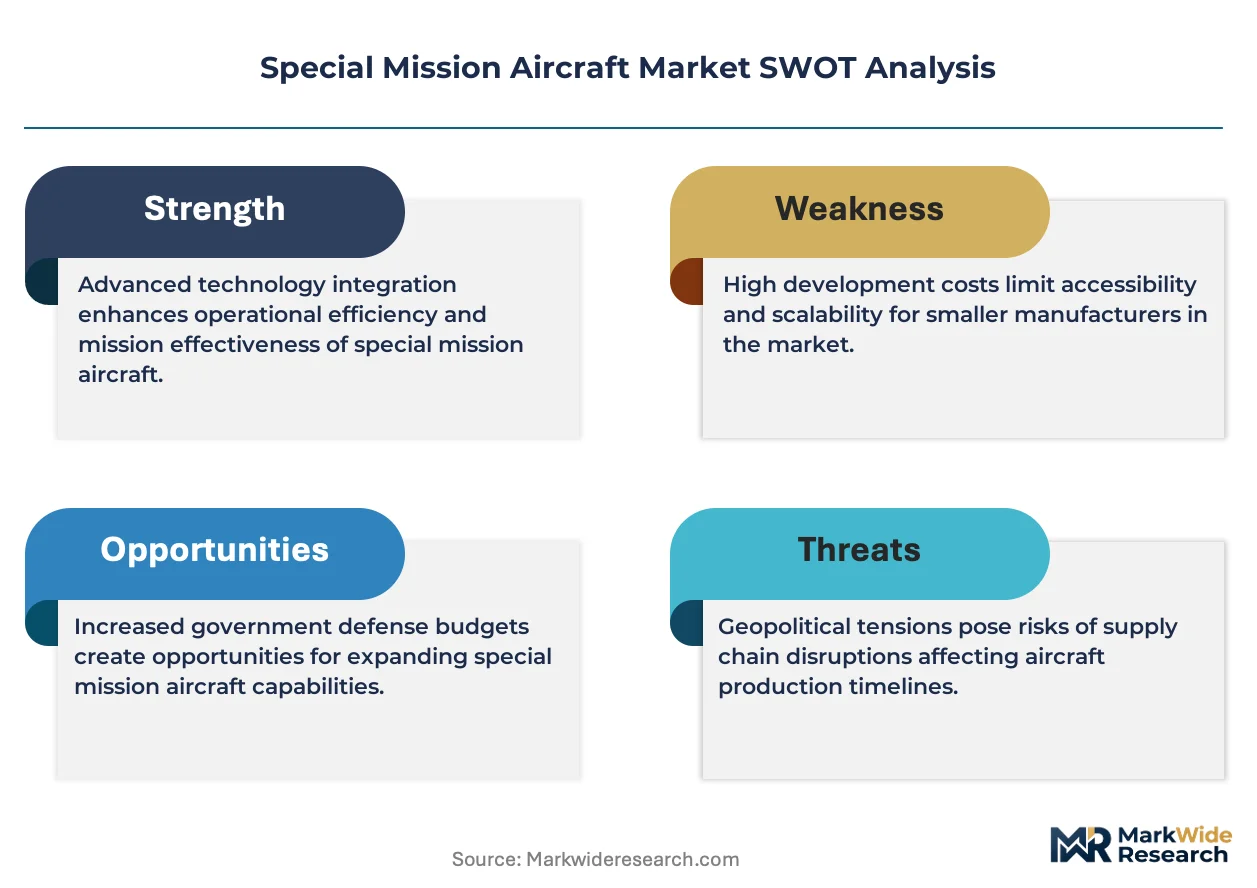
Aftermarket services and technology upgrades drive significant lifetime value for special mission aircraft manufacturers. The dominant pricing structure involves long-term, contract-based agreements for platform acquisition and ongoing support. Price differentiation stems from the level of bespoke customization and stringent airworthiness certification requirements for specialized payloads. Pricing pressure emerges from government customers favoring outcome-based contracts for guaranteed flight hours. Military forces typically demonstrate lower price sensitivity, while government agencies with limited budgets require more cost-effective solutions.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are critical for managing the high upfront costs associated with specialized component procurement. Supply concentration for critical components primarily resides in the United States, Europe, and Israel. Key dependencies include advanced electro-optical/infrared sensor turrets and synthetic aperture radar systems. Single-source vulnerability for these mission-critical components represents a significant structural risk. Distribution primarily occurs through direct sales channels to military forces and government agencies, alongside specialized service providers operating contractor-owned fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The special mission aircraft market is experiencing a shift in buyer power, driven by government agencies increasingly opting for contractor-owned, contractor-operated fleets. This trend consolidates demand among specialized service providers, impacting traditional platform sales models.
For Market Incumbents: Entrench core capabilities in advanced sensor fusion and secure data links to counter threats from next-generation unmanned platforms. Invest heavily in Modular Open Systems Architecture (MOSA) to prevent vendor lock-in and streamline technology upgrades. Deepen vertical integration into critical component manufacturing to mitigate specialized payload scarcity. Prioritize long-term support contracts and digital twin technology for predictive maintenance, ensuring through-life capability management.
For New Entrants and Emerging Players: Establish a beachhead in underserved segments by offering cost-effective solutions based on modified commercial airframes. Target Southeast Asian nations modernizing maritime patrol capabilities and environmental monitoring missions in regions like Brazil. Focus on developing miniaturized sensor payloads that can integrate onto smaller, more affordable platforms. A go-to-market angle emphasizing rapid deployment and flexible contract models for specific surveillance needs will resonate with budget-constrained government agencies.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors firms specializing in sensor fusion, secure data links, and MOSA-compliant subsystems, indicating long-term viability over the next decade. Target acquisition archetypes include agile technology providers capable of integrating advanced payloads onto diverse airframes. The increasing adoption of unmanned-manned teaming solutions will serve as a critical inflection indicator, signaling readiness for next-generation operational paradigms.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Modular Open Systems Architecture (MOSA) | MOSA prevents vendor lock-in for critical subsystems, accommodating components from a wider range of third-party suppliers. |
| Develop Unmanned-Manned Teaming Capabilities | Manned aircraft serve as command hubs for autonomous systems, creating a new operational paradigm for defense agencies. |
| Expand Aftermarket Services and Systems Integration | Long-term support contracts and technology upgrades reconfigure the profit landscape for special mission aircraft manufacturers. |
| Specialize in Cost-Effective Platform Modifications | Modifying proven commercial airframes offers cost-effective solutions, appealing to government agencies with limited budgets. |
| Pursue Sensor Miniaturization R&D | Shrinking high-performance payloads permits integration onto smaller, more cost-effective airframes, expanding market access. |
Research Approach
The analysis maps platform types, mission types, and end-user segments, each validated through extensive primary interviews with defense procurement officers, aerospace engineers, and airworthiness certification specialists. Secondary validation involved cross-referencing military acquisition reports, FAA and EASA certification records, and aerospace industry journals. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy and consistency.
Assumptions regarding geopolitical stability and technological advancements were held fixed across the analysis window, while variations in defense spending and regulatory environments were modeled. Segmentation dimensions included platform type, mission type, end user, technology, and operational environment. Compound annual growth rates were derived from historical data analysis and projected market dynamics, incorporating forecast inputs such as defense budget allocations and climate-related disaster frequency.
Sensitivities concentrate around geopolitical shifts and the pace of regulatory changes in airworthiness certification processes. Forecasts reflect these documented assumptions, but any significant supply chain disruptions for specialized payloads or shifts in national security priorities would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
North America Commercial Aircraft Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
Wind Tunnel Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Cargo Compartment Latches Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Japan Aviation Market
Aircraft
Europe Military Helicopters Market
Aircraft
Aircraft Strut Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
Helicopter Flight Management System Market
Aircraft
US Business Jet Market
Aircraft
Latin America General Aviation Market