
 Europe Light and Very Light Jets Market | 2026-2036
Europe Light and Very Light Jets Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Light and Very Light Jets Market Foresight
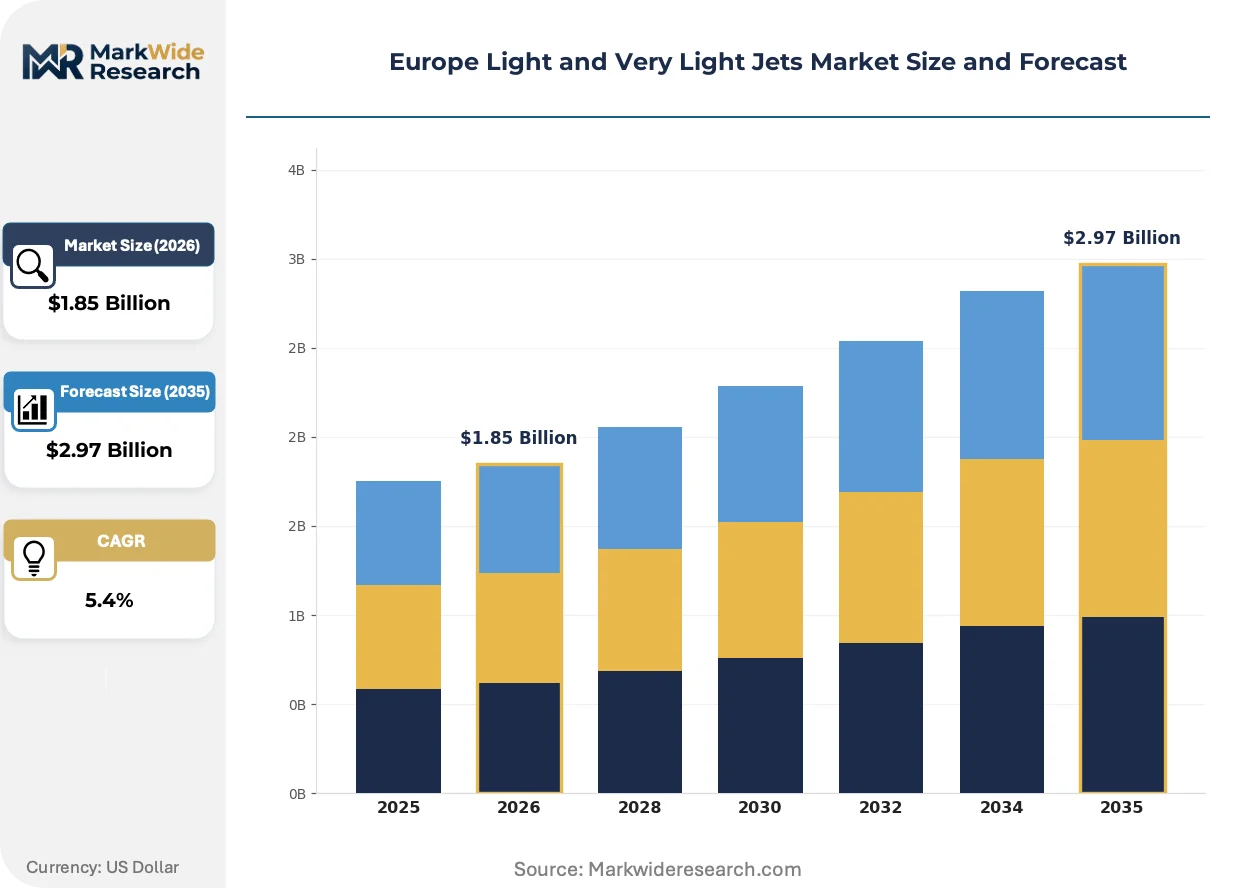
Lease-to-own financing and fractional ownership models is narrowing the capital barrier for new entrants in European business aviation. Pilatus Aircraft Ltd. leverages its PC-24 platform to anchor the super-light segment with rough-field capability. Embraer S.A. competes through its Phenom family, sustaining manufacturing scale across multiple Brazilian and European facilities. Cirrus Design Corporation differentiates with its single-engine Vision Jet, dominating the personal aviation niche with whole-aircraft parachute systems.
Europe Light and Very Light Jets comprise turbine-powered aircraft with maximum takeoff weights below roughly 10,000 kg, typically seating four to eight passengers and operating at altitudes up to 45,000 feet with ranges between 1,000 and 2,500 nautical miles. These aircraft serve point-to-point business travel, medical evacuation, and emerging air taxi missions where commercial airline schedules prove inefficient. Light Jets occupy the mature volume core of the market, while Very Light Jets capture expanding demand from owner-operators seeking lower direct operating costs. Single Engine Jets represent the fastest-growing structural category as EASA Part 23 certification pathways for turbine singles have streamlined market entry. Charter Services within the Delivery Model dimension concentrate margin pools through utilization-based revenue rather than asset-heavy ownership.
EASA airworthiness standards, EU ETS carbon pricing mechanisms, and national noise quota regimes at airports like London City and Geneva shape aircraft specifications, operational economics, and fleet renewal timelines across Europe. CSRD disclosure requirements now extend to corporate flight departments, pressuring operators toward newer, more efficient airframes. Stakeholders must weigh single-engine efficiency gains against residual value uncertainty as secondary markets for these platforms remain thinly traded.
Market Dynamics
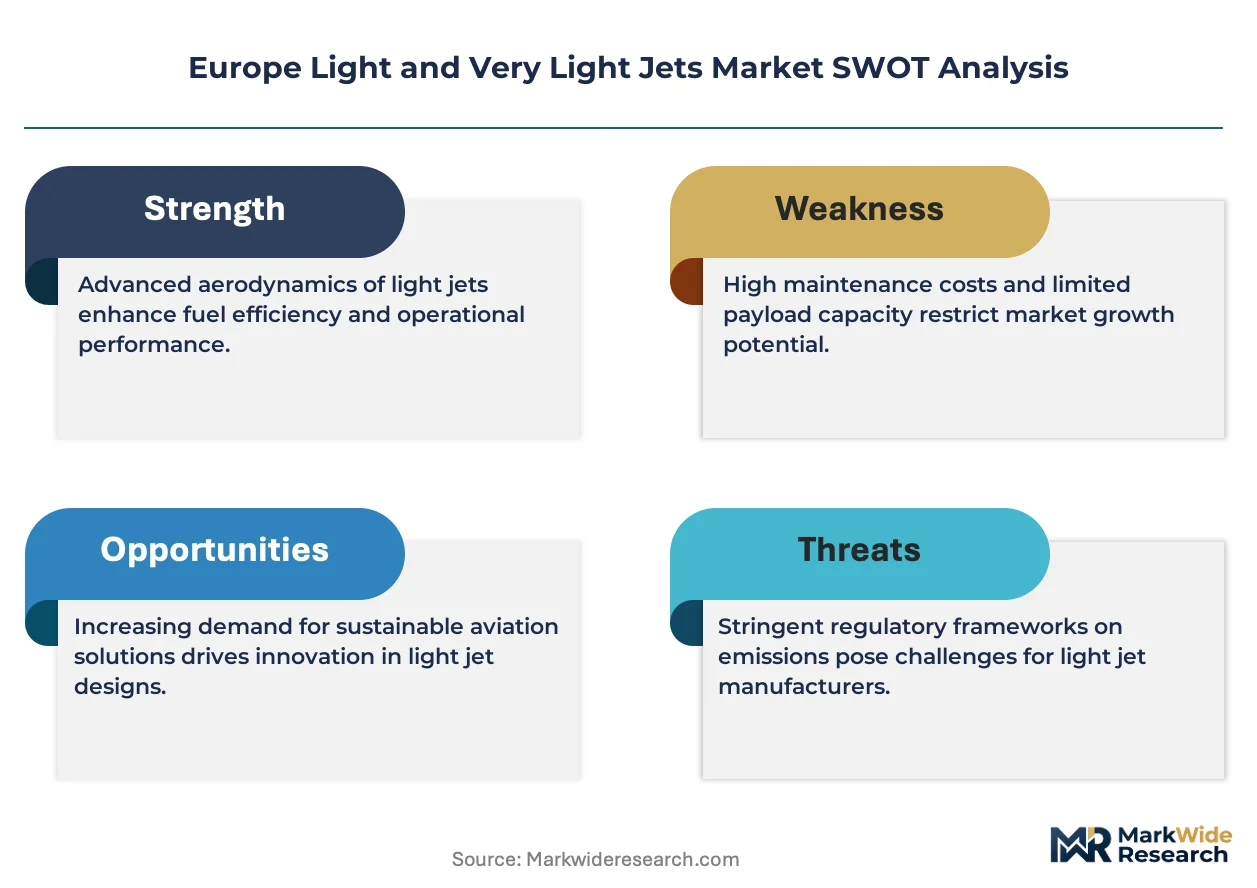
EASA certification pathways for single-engine turbine aircraft are compressing development timelines and redistributing competitive advantage toward lighter airframe architectures. This structural shift is reshaping fleet renewal decisions across European charter operators and owner-pilot segments.
Growth Catalysts
- EU ETS Carbon Pricing:Corporate flight departments face escalating compliance costs for older aircraft, accelerating replacement cycles with more efficient light jet platforms.
- Medical Evacuation Services:Point-to-point aeromedical transport demand is expanding runway-inflexible missions that favor very light jet range-payload economics.
- France-Germany-UK Infrastructure Concentration:Dense FBO networks and MRO capacity in these markets reduce operational friction for new fleet entrants.
Market Restraints
- Residual Value Uncertainty:Thin secondary market liquidity for single-engine turbine aircraft depresses asset-backed financing availability.
- Jet A1 Price Volatility:Direct operating cost exposure to refined kerosene markets constrains price-competitive charter pricing.
- London City Noise Quotas:Strict acoustic limits at premium business aviation airports exclude several current-generation light jet types from slot access.
Strategic Opportunities
- CSRD Disclosure Requirements:Mandatory sustainability reporting for corporate flight departments creates preference for newer, lower-emission airframes with verifiable carbon intensity data.
- Emerging Air Taxi Networks:Urban and regional on-demand aviation platforms represent untapped utilization models for very light jet economics.
- Spain and Italy Charter Penetration:Underdeveloped business aviation infrastructure in Mediterranean markets offers first-mover positioning for fractional ownership expansion.
Industry Challenges
- Single-Pilot Type Rating Scarcity:Flight training capacity for advanced turbofan single-pilot operations lags fleet delivery schedules.
- Part 23 Certification Timelines:EASA validation procedures for novel avionics architectures extend time-to-market for technology-forward platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Light and Very Light Jets Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Light Jets, Very Light Jets, Twin Jets, Single Engine Jets End User: Private Owners, Charter Operators, Corporate Clients, Government Agencies Application: Business Travel, Air Taxi Services, Medical Evacuations, Cargo Transport Delivery Model: Owned Aircraft, Leased Aircraft, Fractional Ownership, Charter Services |
| Companies Covered | Textron Inc., Bombardier Inc., Pilatus Aircraft Ltd., Embraer S.A., Gulfstream Aerospace Corporation, Honda Aircraft Company, Dassault Aviation, Cirrus Design Corporation, Diamond Aircraft Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Light and Very Light Jets Market Shifts & Advancements
Propulsion efficiency and avionics integration are compressing operating cost structures while expanding mission flexibility for European operators. These shifts are redrawing competitive boundaries between established OEM platforms and emerging architectures.
Digital engine control systems are migrating from hydro-mechanical fuel metering to full-authority digital engine control across the light jet installed base. Owner-operator segments in Germany and the United Kingdom are adopting these architectures fastest, driven by maintenance predictability and fuel burn optimization. This technology migration from analog to digital control is enabling extended-range operations with reduced pilot workload and lower direct operating costs.
CSRD corporate sustainability reporting mandates now extend to Scope 3 emissions from business aviation activities. Flight departments must disclose verified carbon intensity per flight hour, pressuring operators toward newer airframes with documented efficiency improvements. Very light jet categories face the most acute compliance pressure, as older fleet segments lack manufacturer-supported emissions certification data.
Charter procurement is consolidating around utilization-based models that unbundle aircraft ownership from flight-hour access. European fractional ownership platforms are displacing traditional whole-aircraft acquisition among mid-market corporate users. France and Switzerland exhibit the fastest behavioral shift, where capital-light structures now dominate new market entry decisions.
Europe Light and Very Light Jets Market Segmentation
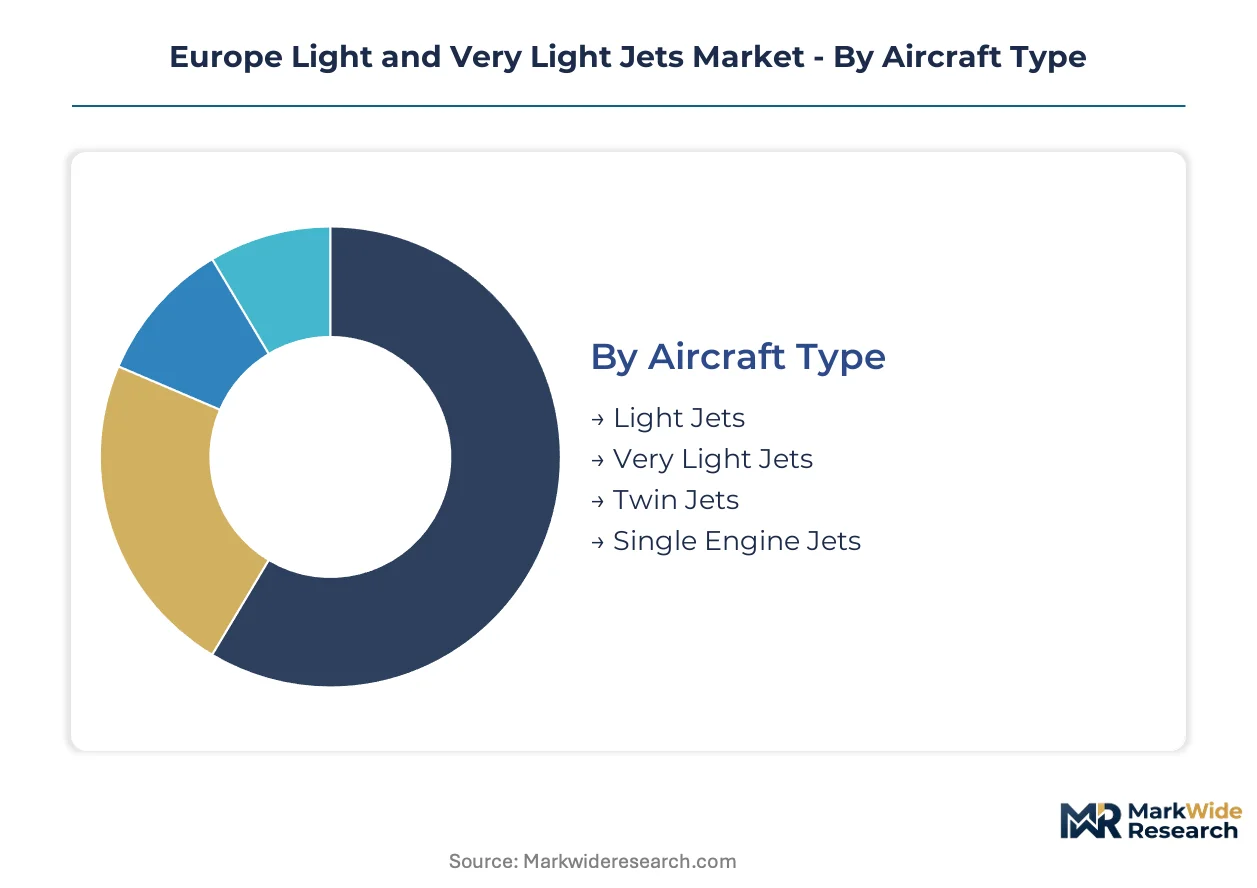
Segmentation in the Europe Light and Very Light Jets Market reveals how mission requirements, capital structures, and regulatory frameworks reshape procurement patterns across owner-operators and fleet managers. Understanding these dimensions exposes where EASA certification pathways and carbon pricing mechanisms concentrate competitive advantage.
Aircraft Type:
The use-case spectrum spans from owner-flown personal transport to high-utilization charter operations, with each architecture trading payload, range, and operating economics against acquisition cost and pilot qualification requirements.
- Light Jets:Twin-turbofan aircraft with maximum takeoff weights between 9,000 and 10,000 kg dominate charter fleet rotations across France, Germany, and the United Kingdom. EASA Part 25 certification requirements preserve residual value predictability that asset-backed financing demands.
- Very Light Jets:Entry-level platforms seating four to five passengers capture owner-operator demand in Switzerland and Austria where single-pilot operations reduce crew costs. Range limitations below 1,500 nautical miles restrict utility for transcontinental missions.
- Twin Jets:Redundant propulsion architectures remain mandatory for London City Airport operations where steep approach profiles and strict noise quotas exclude most single-engine alternatives.
- Single Engine Jets:Turbine singles certified under EASA CS-23 amendments achieve operating cost reductions of roughly thirty percent versus comparable twins, though thin secondary markets constrain financing availability.
Established volume favors Light Jets; emerging adoption favors Single Engine Jets.
End User:
Customer economics diverge sharply between asset-heavy ownership models and utilization-based access structures, reshaping how OEMs configure avionics suites and support programs.
- Private Owners:Individual pilots operating under EASA Part-NCO rules prioritize Garmin G3000-equipped cockpits with synthetic vision and autothrottle reduction of workload. Personal aviation demand concentrates in Bavaria and the English Home Counties where aerodrome density supports point-to-point flexibility.
- Charter Operators:Fleet managers at TAG Aviation and Jet Aviation require aircraft with documented EU ETS compliance data and predictable maintenance intervals to sustain utilization rates above eight hundred hours annually.
- Corporate Clients:Flight departments subject to CSRD disclosure mandates select newer airframes with manufacturer-verified carbon intensity metrics per flight hour.
- Government Agencies:State procurement across border patrol, customs, and judicial transport functions favors twin-engine redundancy for over-water and mountainous terrain missions.
Charter Operators command the largest fleet volumes; Corporate Clients are climbing the fastest under sustainability reporting pressure.
Application:
Mission profiles determine payload-range tradeoffs, with medical and air taxi applications driving specialized equipment integration and operational approval requirements.
- Business Travel:Point-to-point executive transport between secondary airports consumes the majority of flight hours, with demand clustering around Frankfurt, Geneva, and Milan Linate where commercial airline schedules prove inefficient.
- Air Taxi Services:On-demand regional platforms in Germany and France are expanding utilization models for very light jet economics, though Part-SPA operational specifications limit scalability.
- Medical Evacuations:Aeromedical configurations with stretcher systems and pressurized cabin isolation dominate Italian and Spanish markets where terrain and island geography constrain ground ambulance access.
- Cargo Transport:Quick-change interior configurations for time-critical logistics represent a niche application concentrated in express courier networks serving Nordic archipelagos.
Business Travel sustains the installed base; Medical Evacuations are gaining share fastest as healthcare decentralization accelerates.
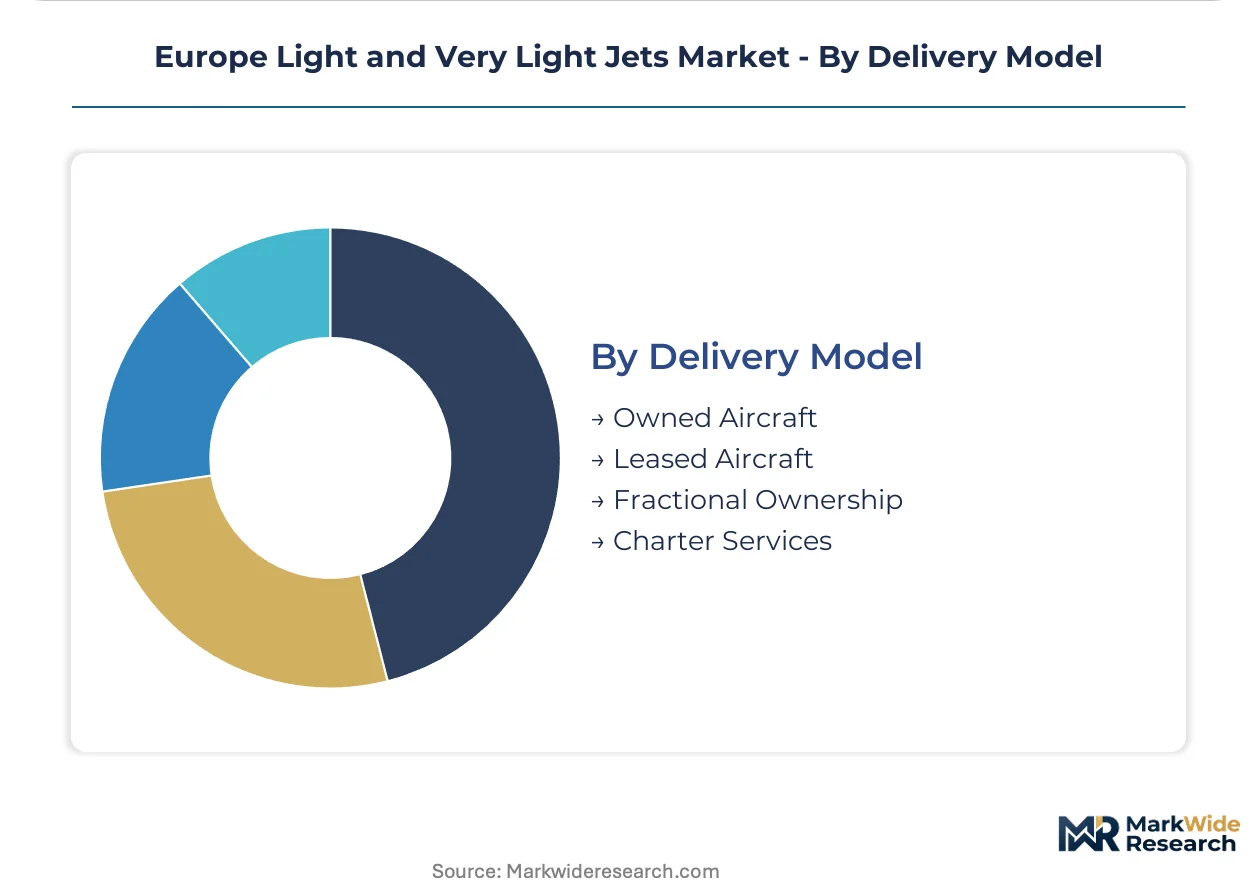
Delivery Model:
Capital structure preferences are fragmenting traditional ownership patterns, with fractional and lease-to-own structures displacing whole-aircraft acquisition among mid-market entrants.
- Owned Aircraft:Full acquisition remains concentrated among ultra-high-net-worth individuals and sovereign entities where depreciation shelters and control priorities outweigh capital efficiency considerations.
- Leased Aircraft:Operating leases from providers like Global Jet Capital reduce balance-sheet exposure for charter operators managing fleet renewal cycles under EU ETS compliance pressure.
- Fractional Ownership:Programs such as NetJets Europe and Flexjet expand access for corporate users requiring fifty to four hundred annual flight hours without asset management burden.
- Charter Services:Pure ad-hoc procurement dominates occasional users in Spain and Italy where business aviation infrastructure penetration remains below Northern European levels.
Owned Aircraft retains the highest asset values; Fractional Ownership is expanding most quickly as capital-light structures penetrate Mediterranean markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Charter rate premiums in Switzerland exceed those in Spain by roughly forty percent, reflecting infrastructure density asymmetries that concentrate pricing power in Alpine and Northern European corridors. This divergence shapes fleet renewal timelines and OEM market entry sequencing across the continent.
Germany
Corporate flight departments in Bavaria and Baden-Württemberg drive demand for EU ETS-compliant airframes with documented carbon intensity metrics. The country's national aviation regulator enforces strict noise abatement procedures at Frankfurt Egelsbach and Munich Oberpfaffenhofen. Stuttgart and Mannheim host dense MRO clusters where charter operators coordinate fleet rotations across Central European routes.
France
Fractional ownership penetration in Île-de-France exceeds any other European metro, with Paris-Le Bourget serving as the continent's busiest business aviation hub. REACH chemical regulations and EU Green Deal alignment pressure operators toward newer turbine architectures with lower NOx profiles. The Provence-Alpes-Côte d'Azur corridor concentrates seasonal demand spikes that strain FBO capacity at Nice Côte d'Azur.
United Kingdom
CSRD disclosure mandates for listed corporations headquartered in London accelerate replacement of pre-2010 fleet segments with verifiable emissions data. The Civil Aviation Authority maintains steep approach certifications that exclude most single-engine jets from London City Airport. The Home Counties aerodrome network supports point-to-point flexibility for owner-operators seeking alternatives to commercial schedules.
Switzerland
High-net-worth individual density in Geneva and Zurich sustains the continent's highest per-capita business aviation utilization rates. Swissmedic-equivalent aviation oversight through FOCA enforces rigorous maintenance documentation standards that preserve residual values. The Basel-Mulhouse-Freiburg tri-border region anchors cross-border charter operations serving pharmaceutical and private banking clients.
Italy
Medical evacuation missions across the Apennine spine and island territories drive specialized aeromedical configurations with pressurized cabin isolation. ANAC compliance pathways for single-pilot turbine operations lag Northern European timelines, delaying new platform introductions. Milan Linate and Rome Ciampino concentrate business traffic where slot constraints favor light jet flexibility over commercial alternatives.
Europe Light and Very Light Jets Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying avionics, propulsion, and interior subsystems. The European light and very light jet market exhibits moderate consolidation, with five to seven OEMs capturing the majority of annual deliveries. Two strategic archetypes dominate: diversified aerospace conglomerates leveraging cross-program scale, and specialist airframers betting on single-engine efficiency. Competitive moves center on EASA certification timing for new architectures and lease-to-own financing partnerships with European charter platforms.
Within the specialist airframer tier, Pilatus Aircraft Ltd. and Cirrus Design Corporation exemplify divergent bets on mission flexibility versus owner-pilot simplicity. Embraer S.A. anchors the scale-driven end with Brazilian manufacturing footprint and European final assembly options. These three occupy positions that map cleanly onto the fractional ownership, charter operator, and personal aviation demand segments respectively.
| Leading Market Players |
|---|
| Textron Inc. |
| Bombardier Inc. |
| Pilatus Aircraft Ltd. |
| Embraer S.A. |
| Gulfstream Aerospace Corporation |
| Honda Aircraft Company |
| Dassault Aviation |
| Cirrus Design Corporation |
| Diamond Aircraft Industries |
| Others |
Supply & Pricing Matrix
Brazilian final assembly lines for Embraer Phenom aircraft anchor upstream manufacturing concentration, directing margin capture toward European MRO networks and fractional ownership platforms that control utilization-based revenue pools. Jet A1 price exposure and EASA certification timelines compress pricing power at the OEM tier while amplifying returns for downstream operators managing fleet rotations.
Pricing Analysis
Configured-to-order premiums for aeromedical interiors and rough-field landing gear packages spread fifteen to twenty percent above standard cabin configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, avionics generation, and after-sales service bundling. Pricing pressure stems from EU ETS compliance costs that accelerate replacement cycles and depress residual values for pre-2010 airframes. Charter operators exhibit highest price sensitivity due to utilization-rate dependencies, while sovereign buyers and ultra-high-net-worth individuals show lowest sensitivity to acquisition premiums.
Supply Chain Analysis
Extended payment terms from sixty to ninety days characterize supplier-finance arrangements for avionics and propulsion subsystems, with supply-chain finance facilities concentrated among tier-one component integrators. Manufacturing concentration centers on Brazil, the United States, and Switzerland for final assembly, while engine and avionics sourcing draws from the United States and France. Single-source vulnerability for full-authority digital engine control systems and synthetic vision avionics creates chokepoint exposure. Distribution runs through factory-direct sales for owner-operators and fleet-leasing intermediaries for charter operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among fractional ownership platforms and large charter operators, with NetJets Europe and Flexjet consolidating procurement volume that fragments across smaller owner-operator segments.
For Market Incumbents: Pre-empt emerging single-engine turbine entrants by accelerating EASA CS-23 certification for next-generation avionics architectures that reduce pilot workload. Secure backward integration into carbon-offset verification services to defend against CSRD disclosure mandates that threaten residual values for older fleet segments. Lock in exclusive MRO partnerships at Stuttgart and Mannheim clusters to constrain competitor access to dense service networks. For New Entrants and Emerging Players: Pursue white-space positioning in Mediterranean charter markets where Spain and Italy exhibit fractional ownership penetration below Northern European benchmarks. Target aeromedical configurations for Italian island and Apennine terrain missions where pressurized cabin isolation commands specialized premiums. Establish lease-to-own financing partnerships with regional charter platforms to bypass asset-heavy ownership barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed charter operators holding pre-2010 fleet segments facing EU ETS compliance cliffs. Long-term viability over the next decade hinges on EASA certification timing for single-engine architectures that achieve operating cost reductions versus twin-turbofan alternatives. Monitor EASA Part 23 validation timelines for novel avionics platforms as the critical inflection signal for technology-forward positioning.| Strategic Initiative | Industry Significance |
|---|---|
| EASA CS-23 Certification Investment | Streamlined approval pathways for Pilatus and Cirrus compress time-to-market for turbine singles. |
| Fractional Ownership Platform Expansion | Capital-light structures at NetJets Europe penetrate Mediterranean markets previously excluded by asset barriers. |
| Carbon-Offset Verification Integration | Manufacturer-backed emissions data satisfies CSRD Scope 3 disclosure mandates for corporate flight departments. |
| Rough-Field Capability Development | PC-24 super-light positioning captures medical evacuation missions beyond paved runway infrastructure. |
| Single-Pilot Training Capacity Buildout | Flight school partnerships at German and UK aerodromes address type-rating scarcity constraining fleet deliveries. |
Research Methodology
Desk research of EASA certification databases, EU ETS compliance registries, and OEM delivery disclosures preceded structured interviews with charter fleet managers, fractional ownership executives, MRO operations directors, and corporate flight department procurement leads. Primary fieldwork combined with secondary validation from SEC filings of listed aerospace conglomerates, trade flow data from Eurostat, and business aviation utilization statistics from EBAA. Bottom-up aircraft delivery forecasts triangulated against top-down market sizing from installed base analysis and replacement cycle modeling.
Assumption sets held EASA regulatory timelines and EU carbon pricing trajectories fixed while varying Jet A1 price scenarios and interest rate conditions across the projection horizon. Segmentation dimensions modeled include aircraft type, end-user archetype, application mission profile, and delivery model structure, with additional granularity on single-engine versus twin-engine certification pathways. CAGRs derived from logistic growth curve fitting to historical delivery volumes, adjusted for fleet age distributions and ETS compliance deadlines. Industry-specific inputs incorporated FBO network density indices and noise quota constraints at London City and Geneva airports.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments, Jet A1 price volatility, or EASA certification timeline extensions would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and carbon pricing continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Light Electric Aircraft Market
Aircraft
Heavy-Lift Helicopter Market
Aircraft
America Freighter Aircraft Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
Asia-Pacific Turboprop Aircraft Market
Aircraft
India Aviation Market
Aircraft
Asia-Pacific Aviation Market
Aircraft
Tanker Aircraft Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
LAMEA Aircraft Band Clamps Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
Aero Wing Market
Aircraft
Glider Aircraft Market