
 Canada Robotic Fruit Picker Market | 2026-2036
Canada Robotic Fruit Picker Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Robotic Fruit Picker Market Intelligence
Modular platform designs is pivoting buyer preference across the Canadian robotic fruit picker landscape. Abundant Robotics, Inc. leverages computer vision integration to sustain its technology leadership in autonomous apple harvesting systems. FFRobotics anchors its position through specialized gripper mechanisms optimized for delicate stone fruits. Harvest CROO Robotics competes on manufacturing scale with its multi-arm strawberry harvesting platforms designed for large commercial operations.
A robotic fruit picker integrates computer vision algorithms, pneumatic or electromechanical end-effectors, and sensor arrays to identify ripe produce, calculate grasp vectors, and execute damage-free detachment from plants. These systems operate at speeds of 1-2 seconds per fruit with positioning accuracy within millimeters, replacing seasonal manual labor in orchards and berry fields. Automatic picker configurations currently dominate installed base volumes due to their integration with existing farm management platforms, while drone-based picker segments represent the fastest-growing category as aerial platforms overcome terrain constraints in British Columbia's steep orchard slopes. Sensor technology deployments generate the deepest margin pools through recurring calibration and firmware update contracts tied to precision agriculture ecosystems.
Health Canada's PMRA sets maximum residue limits that robotic harvesting helps satisfy by reducing bruising and secondary contamination pathways during peak labor windows. Provincial occupational safety regulators and the Canadian Agricultural Partnership framework shape equipment certification requirements and cost-share eligibility for automation investments. Stakeholders must monitor evolving carbon accounting rules under the federal Clean Fuel Regulations, as robotic fleet electrification metrics increasingly influence cooperative purchasing decisions and export market access protocols.
Market Dynamics
Provincial minimum wage escalations under British Columbia and Ontario labor codes are compressing operating margins for seasonal harvest labor, forcing commercial orchards toward capital-intensive automation faster than depreciation cycles would otherwise justify.
Growth Catalysts
- PMRA Residue Compliance:Health Canada's pesticide maximum residue limits incentivize robotic harvesting to eliminate bruising contamination pathways during compressed peak windows.
- Okanagan Valley Labor Scarcity:Large-scale apple and blueberry operations face chronic seasonal worker shortfalls that automation addresses through 24-hour operational capacity.
- Canadian Agricultural Partnership:Federal-provincial cost-share frameworks reduce capital barriers for equipment certification and precision agriculture integration.
Market Restraints
- Capital Intensity:Multi-arm harvesting platforms require seven-figure upfront investment that mid-scale growers cannot finance without cooperative purchasing structures.
- Topography Constraints:Steep orchard slopes in British Columbia's interior valleys limit wheeled platform deployment and necessitate specialized aerial or tracked configurations.
- Input Cost Volatility:Lithium-ion battery pack and precision sensor component pricing fluctuates with global semiconductor supply chain disruptions.
Strategic Opportunities
- Niagara Peninsula Expansion:Ontario's stone fruit corridor remains underpenetrated by autonomous systems relative to apple-dominant British Columbia installations.
- Clean Fuel Regulations Alignment:Federal carbon accounting protocols create preference for electrified robotic fleets in export-oriented cooperative purchasing decisions.
- Drone-Agnostic Platforms:Aerial picker segments converge with computer vision advances to access terrain-constrained acreage previously excluded from automation.
Industry Challenges
- Mechatronics Talent Gap:Agricultural equipment servicers lack training in pneumatic end-effector calibration and sensor fusion troubleshooting.
- Certification Timelines:Provincial occupational safety equipment approval processes delay commercial deployment by 8-14 months after technical validation.
- Legacy Integration Friction:Existing farm management software platforms require custom API development to ingest robotic harvest telemetry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Robotic Fruit Picker Market |
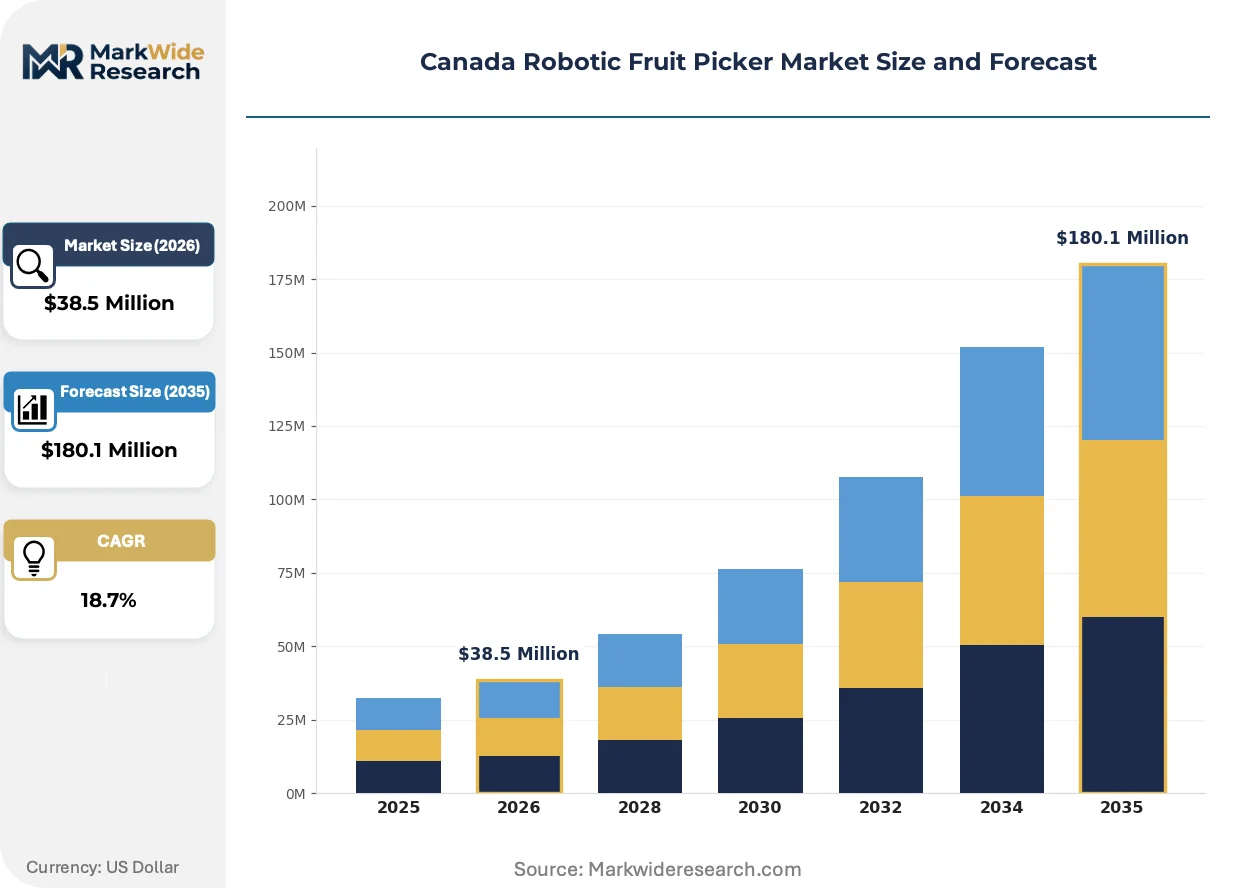
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $180.1 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Picker, Semi-Automatic Picker, Handheld Device, Drone-Based Picker Technology: Computer Vision, Machine Learning, Artificial Intelligence, Sensor Technology End User: Commercial Farms, Research Institutions, Agricultural Cooperatives, Private Growers Deployment: On-Premises, Cloud-Based, Hybrid Solution, Standalone |
| Companies Covered | Neupeak Robotics, Abundant Robotics, Inc., FFRobotics, Octinion BVBA, Harvest CROO Robotics, Dogtooth Technologies Inc., Root AI Inc., Augean Robotics, Agrobot, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Robotic Fruit Picker Market Strategic Shifts & Innovations
Computer vision integration is compressing the gap between laboratory accuracy and field reliability, enabling real-time ripeness classification under variable lighting conditions that previously demanded human judgment.
Sensor fusion architectures combining spectral imaging and tactile feedback arrays are electrifying damage-free detachment capabilities. British Columbia's large-scale apple operations are deploying these systems at commercial velocity after three years of pilot validation. The technology is compressing acceptable bruise rates below the thresholds required for premium export grades to Asian markets.
Health Canada's PMRA is tightening maximum residue limit enforcement protocols for export-bound produce. The regulatory pressure is accelerating grower investment in closed-loop harvesting systems that eliminate human contact contamination vectors. British Columbia's export-oriented cooperatives are responding with fleet electrification roadmaps tied to carbon accounting requirements.
After-sales service contracts are unbundling from equipment purchases as buyers seek performance-based calibration guarantees. Niagara Peninsula blueberry cooperatives are negotiating firmware update subscriptions separate from hardware financing. Ontario's larger operations are driving this shift through volume purchasing leverage and internal technical staffing capabilities.
Canada Robotic Fruit Picker Market Segmentation
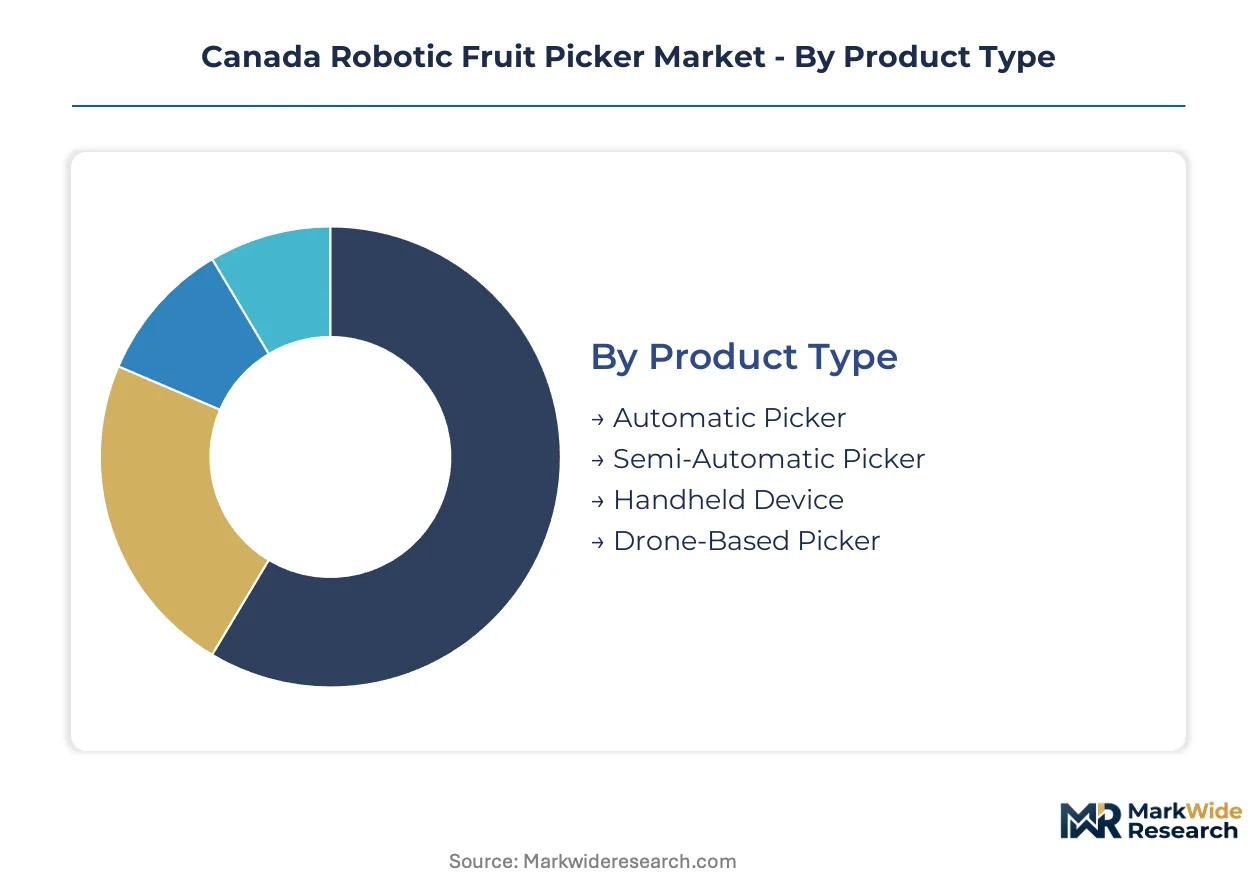
Segmentation in the Canada robotic fruit picker market reveals how equipment specifications align with British Columbia's steep orchard topography and Ontario's cooperative purchasing structures. Buyers select configurations based on labor cost pressure intensity, export certification requirements, and integration complexity with existing farm management platforms.
Product Type:
Customization intensity varies sharply across this category, from fully integrated autonomous platforms to operator-assisted handheld units.
- Automatic Picker:These systems integrate computer vision, pneumatic end-effectors, and sensor arrays for fully autonomous identification and detachment. Demand concentrates among large-scale apple operations in the Okanagan Valley where 24-hour operational capacity offsets seven-figure capital outlays under rising British Columbia minimum wage codes.
- Drone-Based Picker:Aerial platforms overcome terrain constraints in British Columbia's interior valleys where wheeled configurations cannot navigate slopes exceeding 15 degrees. Expansion accelerates where steep orchard acreage previously excluded from automation now becomes accessible through computer vision-guided aerial grasp mechanisms.
- Semi-Automatic Picker:Operator-supervised systems reduce capital barriers for mid-scale Niagara Peninsula stone fruit growers.
- Handheld Device:Portable units serve research institutions and small private growers with intermittent harvesting needs.
Most installed capacity flows through Automatic Picker configurations. Expansion is steepest in Drone-Based Picker segments.
Technology:
Cost tier separation distinguishes commodity sensor packages from precision agriculture ecosystems generating recurring service revenue.
- Sensor Technology:Spectral imaging and tactile feedback arrays enable real-time ripeness classification and damage-free detachment. Health Canada PMRA residue compliance protocols drive adoption where bruise rate thresholds determine premium export grade eligibility to Asian markets.
- Computer Vision:Algorithms process variable lighting conditions for grasp vector calculation with millimeter positioning accuracy. British Columbia's large-scale operations deploy these systems after multi-year pilot validation compressed laboratory-to-field reliability gaps.
- Machine Learning:Adaptive models improve harvest accuracy through seasonal data accumulation.
- Artificial Intelligence:Advanced decision architectures optimize fleet coordination across multi-acre operations.
Sensor Technology deployments generate the deepest margin pools through calibration and firmware update contracts. Computer Vision is climbing the fastest as accuracy thresholds satisfy premium export requirements.
End User:
Volume scale and technical staffing capabilities determine procurement patterns across buyer categories.
- Commercial Farms:Large-scale operations in the Okanagan Valley and Niagara Peninsula drive equipment certification timelines and negotiate performance-based service contracts separate from hardware financing.
- Agricultural Cooperatives:Federated purchasing structures aggregate mid-scale grower demand to access capital-intensive multi-arm platforms. Canadian Agricultural Partnership cost-share frameworks reduce barriers for these entities.
- Research Institutions:Pilot validation partnerships shape technology roadmaps before commercial deployment.
- Private Growers:Individual operations below cooperative scale rely on handheld or semi-automatic configurations.
Agricultural Cooperatives concentrate the most procurement leverage for fleet electrification roadmaps. Commercial Farms are expanding most quickly as depreciation cycles accelerate under labor cost compression.
Deployment:
Maturity gradients separate legacy on-site installations from emerging cloud-integrated precision agriculture ecosystems.
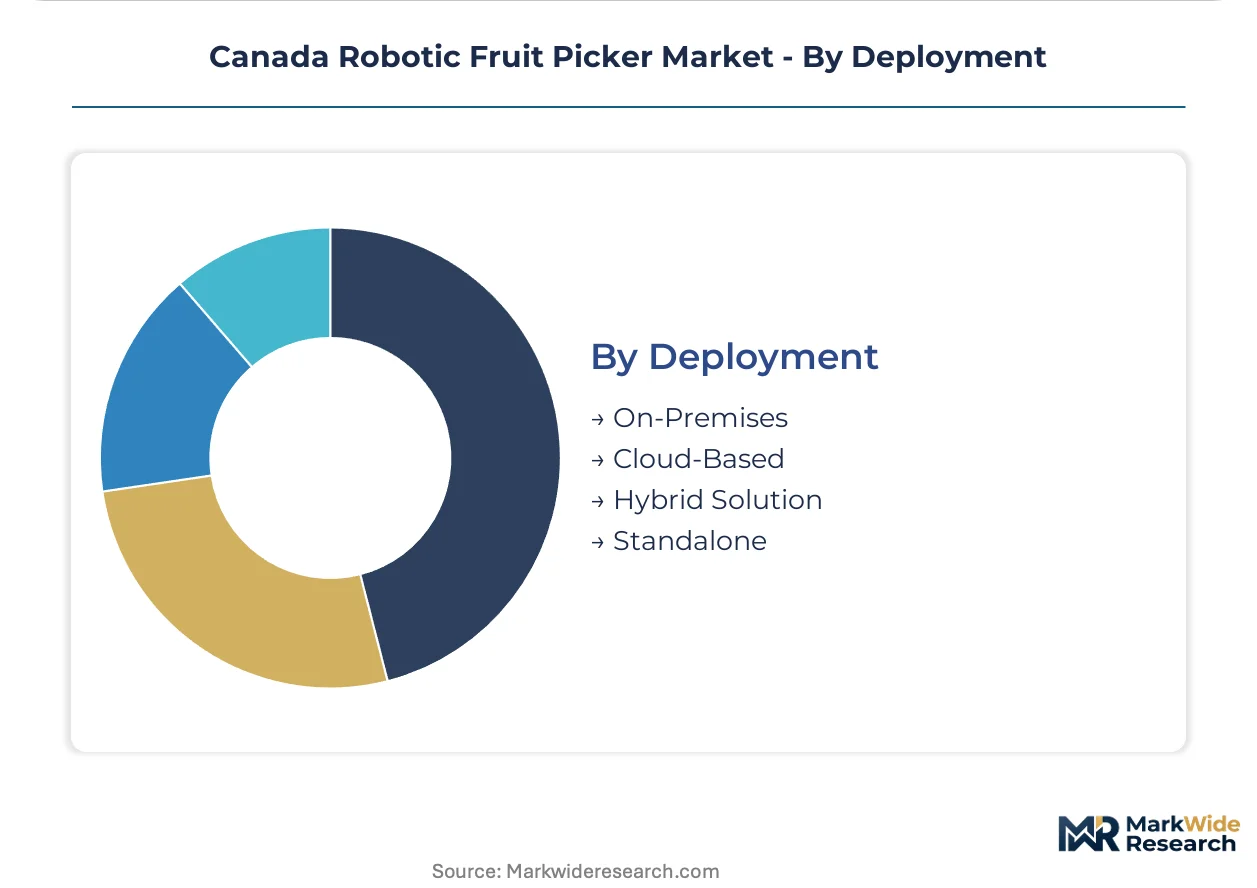
- On-Premises:Localized control systems dominate current installed base where farm management software lacks API compatibility for robotic telemetry ingestion. Niagara Peninsula blueberry cooperatives maintain these configurations where connectivity infrastructure remains uneven.
- Hybrid Solution:Edge-computing architectures with cloud synchronization balance real-time autonomy with centralized fleet management. British Columbia's export-oriented operations favor these models where carbon accounting metrics under federal Clean Fuel Regulations require consolidated reporting.
- Cloud-Based:Fully centralized processing enables predictive maintenance and remote calibration.
- Standalone:Disconnected units serve isolated acreage without network infrastructure.
On-Premises configurations retain the largest installed base. Hybrid Solution architectures are gaining share fastest as API development resolves legacy integration friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian orchard automation emerged from British Columbia's Okanagan Valley, where steep terrain and labor scarcity forced early mechanization experiments that now anchor national deployment patterns.
British Columbia
Okanagan Valley apple and blueberry operations drive national adoption velocity. Health Canada PMRA residue compliance protocols tighten export-grade requirements. Kelowna-based cooperatives deploy drone-agnostic platforms across slopes exceeding 15 degrees where wheeled systems fail.
Ontario
Niagara Peninsula stone fruit growers face acute seasonal labor shortfalls under provincial minimum wage escalations. Canadian Agricultural Partnership cost-share frameworks reduce capital barriers for mid-scale operations. Grimsby-area cooperatives negotiate unbundled service contracts separate from hardware financing.
Quebec
Provincial labor codes accelerate depreciation cycles for automation investments beyond natural replacement timelines. Health Canada PMRA enforcement protocols for export-bound produce intensify closed-loop harvesting requirements. Montérégie berry operations pilot hybrid deployment architectures with cloud synchronization.
Alberta
Greenhouse tomato and cucumber producers experiment with modified gripper mechanisms for vine-crop applications. Provincial occupational safety regulators extend equipment certification timelines for novel configurations. Lethbridge research partnerships validate computer vision accuracy under variable artificial lighting conditions.
Atlantic Canada
Wild blueberry barrens in Nova Scotia present terrain fragmentation challenges for platform standardization. Federal Clean Fuel Regulations carbon accounting protocols influence cooperative fleet electrification roadmaps. Oxford-area operations test handheld-to-autonomous upgrade pathways for intermittent harvest windows.
Canada Robotic Fruit Picker Market Key Industry Players
The competitive structure tilts toward technology-integrated specialists rather than diversified agricultural equipment conglomerates. Vendor concentration remains moderate, with regional leaders commanding Okanagan Valley and Niagara Peninsula installations through localized service networks. Three archetypes dominate: computer vision-anchored autonomous platform developers, specialized end-effector designers, and multi-arm scale manufacturers. Consolidation pressure manifests through strategic partnerships between sensor technology providers and harvesting platform builders, plus geographic expansion via provincial distributor acquisitions.
Within the autonomous systems tier, Abundant Robotics, Inc. and Harvest CROO Robotics occupy positions exemplifying divergent scale strategies—single-crop precision versus multi-arm commercial throughput. FFRobotics anchors the specialized end-effector segment where delicate stone fruit handling requirements create defensible technical moats. These three entities collectively represent the competitive vectors—vision integration, manufacturing scale, and mechanical specialization—shaping procurement decisions across British Columbia and Ontario cooperative structures.
| Leading Market Players |
|---|
| Neupeak Robotics |
| Abundant Robotics, Inc. |
| FFRobotics |
| Octinion BVBA |
| Harvest CROO Robotics |
| Dogtooth Technologies Inc. |
| Root AI Inc. |
| Augean Robotics |
| Agrobot |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between Health Canada PMRA-compliant sensor arrays and commodity vision packages manifests in both pricing spreads and supplier consolidation patterns across British Columbia and Ontario procurement channels. Premium-tier computer vision systems with integrated firmware update contracts command substantial markups over baseline pneumatic picker configurations, while supply chain sourcing for spectral imaging components clusters in jurisdictions with established precision agriculture manufacturing ecosystems.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Canadian robotic fruit picker procurement, with differentiation anchored in Health Canada PMRA certification status and after-sales service bundling intensity. Premium tiers incorporate recurring calibration subscriptions and carbon accounting compliance modules demanded by Okanagan Valley export cooperatives. Cost compression in standard-tier automatic picker configurations is intensifying because lithium-ion battery pack volatility feeds through to OEM pricing. Niagara Peninsula mid-scale growers exhibit highest price sensitivity, while large-scale British Columbia apple operations prioritize performance guarantees over upfront capital outlays.
Supply Chain Analysis
Health Canada provincial equipment certification timelines function as qualification gates that filter supplier eligibility and concentrate procurement leverage among pre-approved vendors. Component manufacturing draws from China, South Korea, and Germany for precision sensors, pneumatic actuators, and machine vision processors. Single-source vulnerability persists in spectral imaging array supply where specialized agricultural optics production rests on two dominant foundries. Distribution runs through Canadian Agricultural Partnership-certified dealer networks with provincial service territories aligned to Okanagan Valley and Niagara Peninsula cooperative purchasing structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's robotic fruit picker market offers margin expansion pathways through labor cost compression premiums and electrified fleet upgrade cycles. Health Canada PMRA compliance requirements and provincial minimum wage escalations create structural pricing power for certified autonomous platform vendors.
For Market Incumbents: Acquire specialized end-effector design capabilities to defend against modular platform competitors entering stone fruit segments. Consolidate provincial service networks in British Columbia's interior valleys where terrain-constrained deployments demand localized technical response capacity. Health Canada certification timeline acceleration represents the priority defensive investment area.
For New Entrants and Emerging Players: Capture Niagara Peninsula blueberry cooperative procurement cycles where incumbent penetration lags Okanagan Valley apple installations. Drone-agnostic aerial picker configurations for slopes exceeding 15 degrees present the most penetrable white space. Lead with unbundled firmware subscription models that separate hardware financing from performance-based calibration guarantees.
For Investors and Strategic Acquirers: Asymmetric upside sits with computer vision-anchored autonomous platform developers possessing Health Canada pre-certification status and established British Columbia cooperative relationships. Five-to-ten-year viability hinges on electrified fleet carbon accounting alignment under federal Clean Fuel Regulations. Watch for provincial minimum wage indexation announcements as inflection indicators accelerating depreciation cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada PMRA Pre-Certification Investment | Accelerates commercial deployment timelines by 8-14 months in British Columbia and Ontario markets. |
| Drone-Agnostic Platform Development | Unlocks steep orchard acreage previously excluded from automation in Okanagan Valley interior valleys. |
| Unbundled Service Contract Structuring | Separates firmware update subscriptions from hardware financing to match Niagara Peninsula cooperative procurement preferences. |
| Electrified Fleet Carbon Accounting Integration | Aligns robotic picker specifications with federal Clean Fuel Regulations for export-oriented cooperative purchasing decisions. |
| Provincial Service Network Consolidation | Captures recurring calibration revenue pools through localized pneumatic end-effector maintenance capabilities. |
Research Approach
Coverage spans British Columbia, Ontario, Quebec, Alberta, and Atlantic Canada, with primary inputs from each region's agricultural cooperative procurement officers, orchard operations managers, provincial occupational safety equipment certifiers, and precision agriculture integration specialists. Secondary validation draws from Health Canada PMRA residue limit databases, Canadian Agricultural Partnership cost-share disbursement records, provincial labor code minimum wage schedules, and federal Clean Fuel Regulations carbon accounting protocols. Bottom-up equipment shipment tallies triangulate against top-down cooperative purchasing survey aggregates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type configuration, technology tier, end-user scale category, and deployment architecture maturity. CAGRs derive from logistic diffusion curves fitted to cooperative adoption patterns and labor cost elasticity estimates. Industry-specific forecast inputs incorporate Health Canada certification pipeline visibility and provincial minimum wage indexation trajectories.
Provincial regulatory delays, lithium-ion supply chain disruptions, and mechatronics talent scarcity are the dominant revision risks to modeled adoption velocities. Forecasts reflect assumptions regarding Health Canada PMRA enforcement intensity and cooperative purchasing aggregation effectiveness. A model refresh is warranted upon material change in federal Clean Fuel Regulations carbon accounting stringency or British Columbia minimum wage indexation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
Power Tiller Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
Agricultural Unit Heaters Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
Global Crop Harvesting Robots Market
Agricultural Machinery
Global Tractor Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
Agricultural Forestry Machinery Market
Agricultural Machinery
China Agricultural Machinery Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market