
 High-Temperature Furnace Refractory Lining Inspection Systems Market | 2026-2036
High-Temperature Furnace Refractory Lining Inspection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
High-Temperature Furnace Refractory Lining Inspection Systems Market Insights
China is tilting toward robotic inspection deployment across its steel belt. Vesuvius leverages its refractory service footprint to bundle inspection with lining supply contracts. RHI Magnesita anchors its position through integrated digital monitoring platforms tied to magnesia-carbon installations. Saint-Gobain competes by extending ceramic sensor expertise into high-temperature furnace diagnostics.
High-temperature furnace refractory lining inspection systems encompass non-destructive testing equipment that detects thermal gradients, crack propagation, and wear depth in alumina-silica or magnesia-based linings operating above 1,500 degrees Celsius, primarily to prevent catastrophic furnace failure and unplanned shutdowns in continuous process industries. Infrared thermography leads deployment in steel making applications where real-time hot spot detection governs campaign life extension decisions. Robotic systems represent the fastest-growing deployment mode as foundries eliminate human exposure to molten metal zones and toxic fume environments. Laser scanning captures margin concentration in glass production where dimensional accuracy of regenerator walls determines fuel efficiency compliance.
OSHA process safety management standards and EPA hazardous air pollutant rules in the United States mandate documented refractory integrity programs for petrochemical crackers and incinerators. China's MEE enforces emissions-linked production permits that require proof of furnace seal integrity through certified inspection records. Stakeholders must monitor how carbon border adjustment mechanisms in Europe and North America reshape inspection frequency requirements for imported steel and cement.
Market Dynamics
The steel industry's transition toward automated furnace monitoring under tightening carbon accounting rules is compressing inspection cycles from annual to continuous, forcing capital redeployment from manual thermography toward robotic deployment models.
Growth Catalysts
- EU Green Deal carbon intensity protocols:German steel producers now mandate automated refractory integrity documentation to verify emissions claims, creating pull-through demand for certified inspection systems.
- Blast furnace rebuild cycles in China:The concentration of furnace rebuilds in Hebei and Jiangsu provinces is accelerating replacement of manual inspection protocols with robotic thermography systems.
- Infrared thermography maturation:Real-time hot spot detection capabilities now enable campaign life extension decisions that were previously impossible with periodic manual surveys.
Market Restraints
- High-purity sensor material costs:Indium antimonide and mercury cadmium telluride detector substrates face price volatility from limited semiconductor-grade refining capacity.
- Specialized technician scarcity:The intersection of thermal engineering, robotics programming, and refractory metallurgy creates a narrow talent pipeline that constrains deployment velocity.
- Legacy furnace architecture incompatibility:Pre-1990s furnace designs lack standardized access ports and power infrastructure for robotic crawler installation.
Strategic Opportunities
- India's secondary steel expansion:Electric arc furnace capacity additions in Gujarat and Odisha present greenfield inspection system deployment without legacy equipment displacement costs.
- Glass regenerator wall monitoring:Laser scanning applications for dimensional accuracy compliance in container glass production remain underpenetrated relative to steel.
- Carbon border adjustment mechanism documentation:EU CBAM implementation creates demand for auditable furnace seal integrity records that automated inspection systems can generate continuously.
Industry Challenges
- Multi-physics simulation expertise gaps:Interpreting thermographic data requires simultaneous competence in heat transfer modeling, refractory degradation mechanics, and furnace operational parameters.
- Integration complexity with distributed control systems:Proprietary protocols from incumbent automation vendors create friction when connecting inspection hardware to plant-wide monitoring architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Temperature Furnace Refractory Lining Inspection Systems Market |
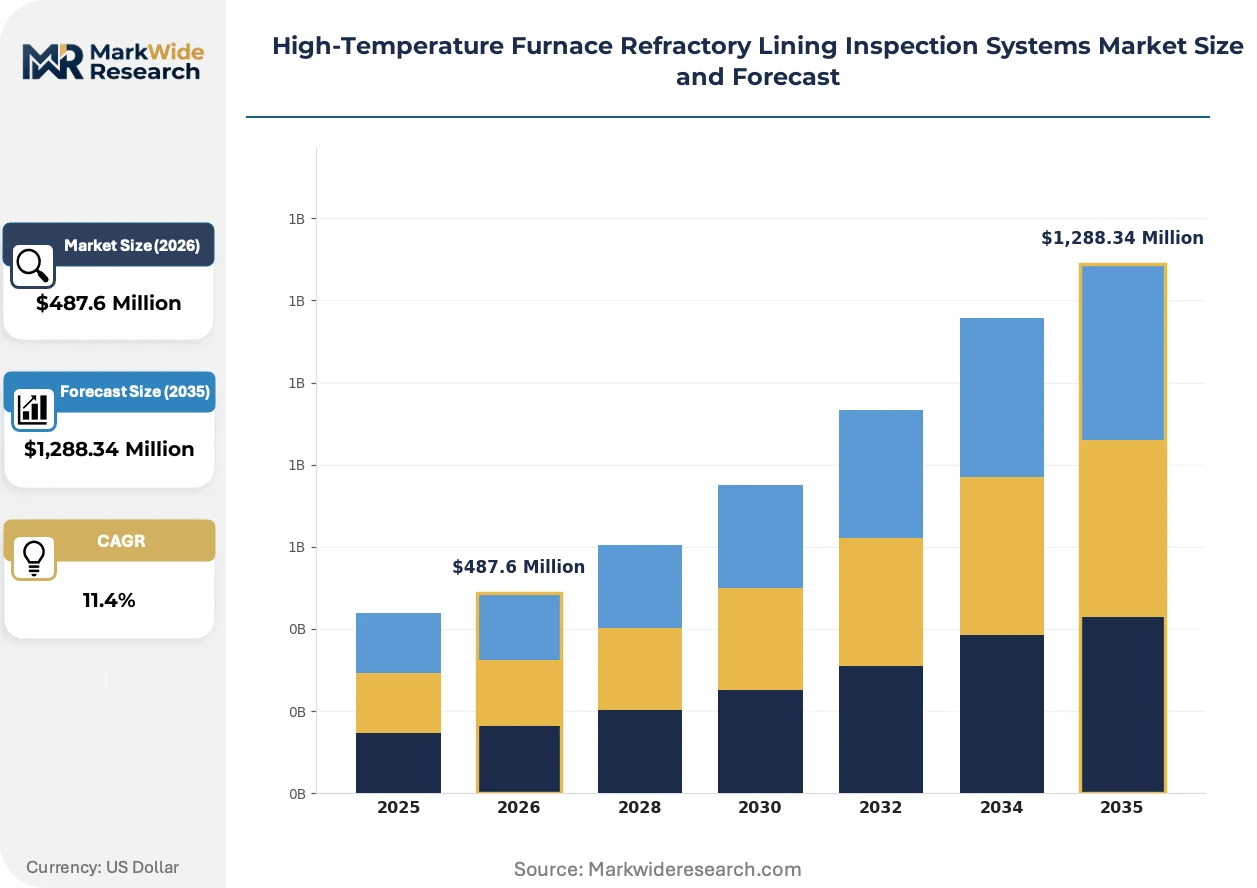
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Infrared Thermography, Ultrasonic Testing, Laser Scanning, Eddy Current Testing, Acoustic Emission Application: Steel Making, Glass Production, Cement Manufacturing, Petrochemical Processing, Power Generation End User: Metal Foundries, Glass Plants, Cement Plants, Refining Units, Power Plants Deployment: Portable Devices, Fixed Installations, Robotic Systems, Manual Inspection Tools, Remote Monitoring Platforms |
| Companies Covered | Vesuvius, RHI Magnesita, Saint-Gobain, Morgan Advanced Materials, HarbisonWalker International, Shinagawa Refractories, Krosaki Harima, Imerys, CoorsTek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Temperature Furnace Refractory Lining Inspection Systems Market Trends and Innovations
Robotic deployment architectures and AI-augmented thermal analytics are converging to transform furnace monitoring from episodic maintenance activity into continuous process intelligence, compressing the feedback loop between defect detection and operational response.
Multi-spectral infrared arrays with embedded edge computing are rendering obsolete the practice of manual thermographic surveys conducted during scheduled furnace cooldowns. Steel producers in South Korea and Japan are deploying these systems at pilot scale, with full adoption timelines compressing from five-year replacement cycles to eighteen-month retrofit programs. The structural consequence is a collapse in demand for portable thermal camera rental services and third-party inspection contracting.
China's MEE emissions-linked production permit system now requires certified furnace seal integrity documentation as a condition of operating license renewal. This policy mechanism forces continuous monitoring adoption regardless of furnace age or capital budget constraints. Petrochemical crackers and hazardous waste incinerators face the most immediate compliance pressure, with inspection frequency mandates tightening from annual to quarterly documentation cycles.
Service unbundling is disrupting the traditional model of bundled refractory supply and inspection contracts. End-users in the cement and non-ferrous metals sectors now procure inspection hardware separately from lining materials, forcing equipment vendors to establish direct commercial relationships with plant engineering departments. This pattern is most pronounced in Turkey and Mexico, where independent inspection service providers are capturing share from refractory manufacturers' captive service arms.
High-Temperature Furnace Refractory Lining Inspection Systems Market Segmentation
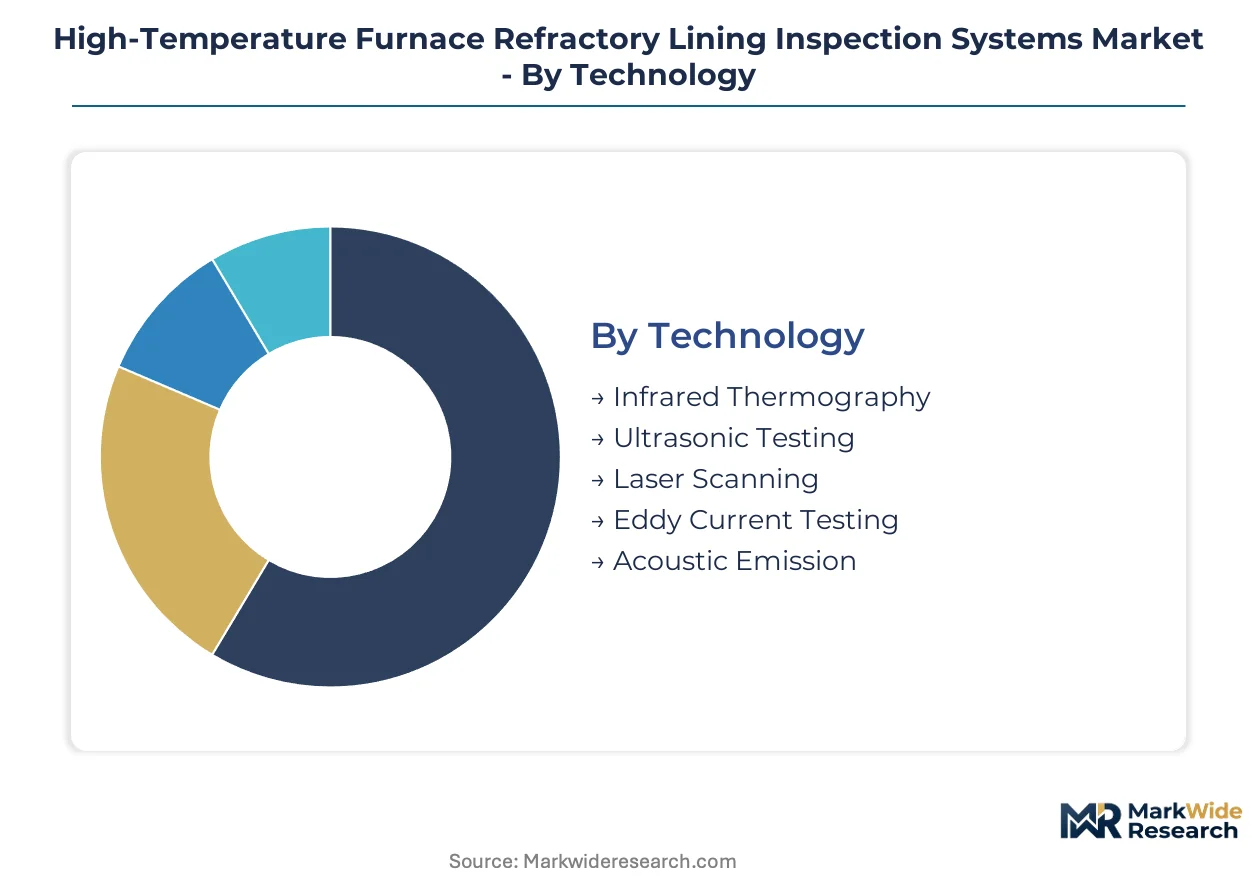
Segmentation in this market reveals how inspection technology selection maps directly to furnace operating parameters and capital deployment constraints. Technology maturity, deployment architecture, and end-use thermal intensity create distinct purchasing patterns across steel, glass, and cement verticals.
Technology:
Mature infrared platforms dominate revenue while emerging multi-spectral arrays reshape competitive positioning in high-temperature steel applications.
- Infrared Thermography:Non-contact thermal imaging using indium antimonide or mercury cadmium telluride detectors captures surface temperature distributions above 1,500 degrees Celsius. Steel makers in Germany deploy these systems for real-time hot spot detection under EU Green Deal carbon intensity documentation requirements.
- Laser Scanning:Structured light and time-of-flight sensors measure dimensional accuracy of regenerator walls and refractory thickness with sub-millimeter precision. Glass producers in South Korea adopt laser systems to verify fuel efficiency compliance in container glass manufacturing.
- Ultrasonic Testing:Pulse-echo and through-transmission methods assess internal crack propagation and wear depth in alumina-silica linings.
- Eddy Current Testing:Electromagnetic induction detects surface-breaking defects in conductive refractory anchors and metallic furnace components.
- Acoustic Emission:Stress-wave monitoring identifies micro-crack formation during thermal cycling in magnesia-carbon installations.
Infrared Thermography retains volume leadership; Laser Scanning holds the steepest expansion curve.
Application:
Cost tier segmentation separates continuous process industries with campaign life economics from batch operations with shorter furnace cycles.
- Steel Making:Blast furnace and electric arc furnace operations require continuous refractory monitoring to prevent catastrophic failure and unplanned shutdowns. Hebei and Jiangsu provinces in China drive robotic thermography adoption during concentrated rebuild cycles.
- Glass Production:Regenerator wall integrity directly determines fuel efficiency and emissions compliance in container and flat glass manufacturing.
- Cement Manufacturing:Rotary kiln nose ring and cooler inspection focuses on alkali attack detection and coating thickness measurement.
- Petrochemical Processing:Fluid catalytic cracker and steam methane reformer refractory integrity programs satisfy OSHA process safety management and EPA hazardous air pollutant documentation mandates.
- Power Generation:Coal and biomass boiler refractory monitoring addresses slag buildup and tube leakage prevention in high-ash fuel environments.
Steel Making commands the largest installed base; Glass Production shows the most rapid technology refresh rates.
End User:
Customer type determines procurement authority—integrated steel mills bundle inspection with refractory supply contracts while independent foundries procure hardware directly.
- Metal Foundries:Ferrous and non-ferrous casting operations deploy portable thermography for ladle and tundish lining assessment. Turkish and Mexican foundries increasingly unbundle inspection hardware from refractory material supply agreements.
- Glass Plants:Container, flat, and specialty glass manufacturers prioritize regenerator wall dimensional accuracy for fuel efficiency optimization.
- Cement Plants:Clinker production facilities focus on kiln shell temperature monitoring and cooler refractory thickness measurement.
- Refining Units:Petrochemical crackers and hydrogen production units face tightening inspection frequency mandates from emissions-linked operating permits.
- Power Plants:Utility and industrial boilers require slag detection and tube shield integrity assessment in high-temperature combustion zones.
Metal Foundries generate the highest unit volume; Glass Plants lead in average system value per installation.
Deployment:
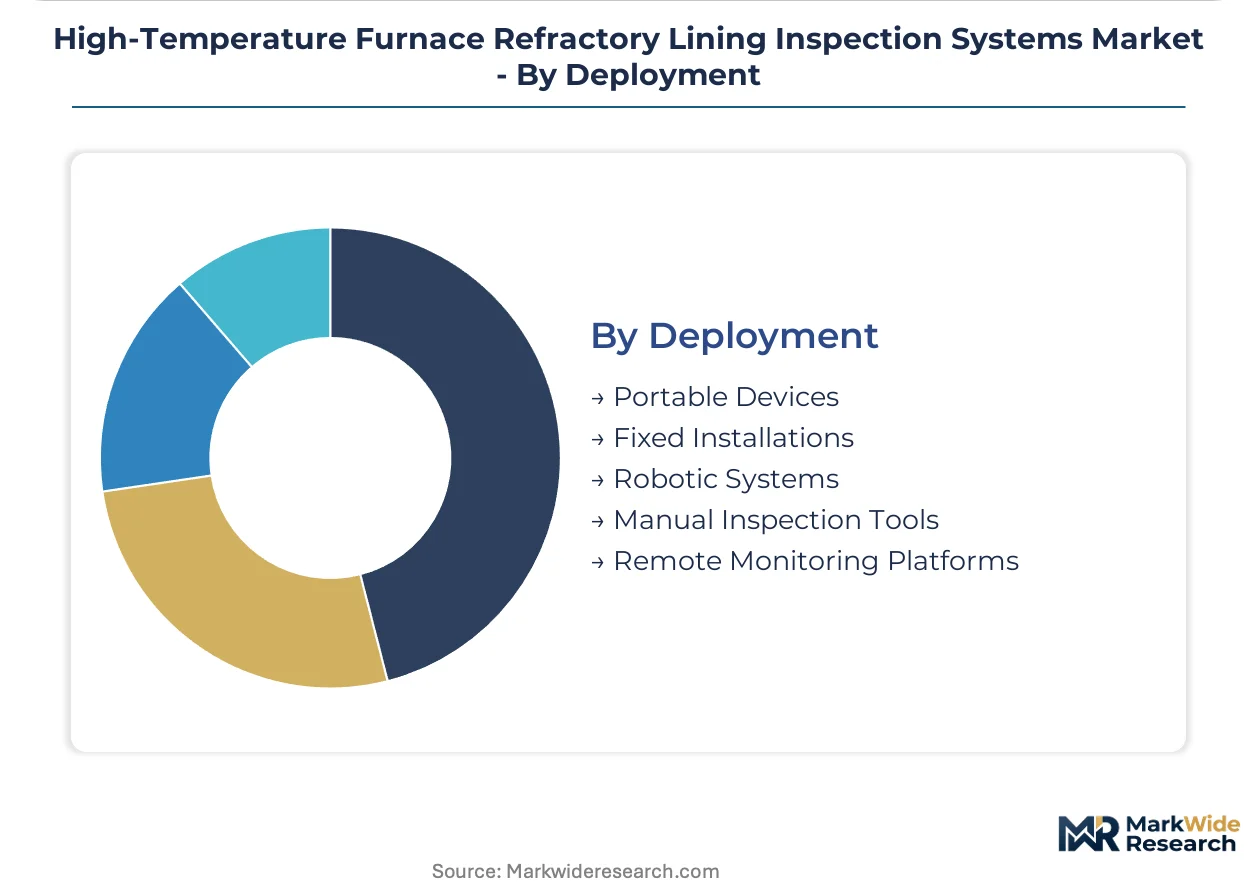
Supply concentration in sensor manufacturing constrains pricing flexibility while integration complexity varies sharply across deployment modes.
- Robotic Systems:Autonomous crawlers and drones eliminate human exposure to molten metal zones and toxic fume environments while enabling continuous monitoring. Japanese and South Korean steel producers compress adoption timelines from five-year replacement cycles to eighteen-month retrofit programs.
- Fixed Installations:Permanently mounted multi-spectral infrared arrays with embedded edge computing render manual surveys obsolete.
- Portable Devices:Handheld thermal cameras face collapsing rental demand as continuous monitoring displaces periodic inspection contracting.
- Manual Inspection Tools:Borescope and hammer testing methods persist in legacy furnace architectures lacking standardized access ports.
- Remote Monitoring Platforms:Cloud-connected sensor networks aggregate thermal data across multiple furnace assets for predictive maintenance analytics.
Portable Devices still account for the largest installed population; Robotic Systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor fabrication concentrates in Germany and Japan, while system integration and deployment scale cluster in China and South Korea. Demand geography diverges sharply from supply geography.
China
Blast furnace rebuild cycles in Hebei and Jiangsu provinces drive replacement of manual inspection with robotic thermography systems. The Ministry of Ecology and Environment enforces emissions-linked production permits requiring certified furnace seal integrity documentation. Tangshan steel clusters compress adoption timelines from five-year replacement cycles to eighteen-month retrofit programs.
Germany
Steel producers mandate automated refractory integrity documentation to verify emissions claims under EU Green Deal carbon intensity protocols. The KBA and federal environmental regulators coordinate furnace monitoring standards with carbon border adjustment mechanisms. Ruhr Valley integrated mills bundle inspection systems with refractory supply contracts.
United States
Petrochemical crackers and hazardous waste incinerators face tightening inspection mandates from OSHA process safety management and EPA hazardous air pollutant rules. Gulf Coast refining corridors deploy continuous monitoring to satisfy quarterly documentation cycles. Houston-area engineering firms integrate inspection hardware with distributed control systems.
Japan
METI industrial efficiency standards accelerate robotic crawler deployment in Kansai and Chubu steel regions. JIS certification requirements for furnace safety systems create procurement preference for domestic platform integrators. Nagoya automotive steel suppliers pilot multi-spectral infrared arrays with embedded edge computing.
South Korea
POSCO and Hyundai Steel compress technology refresh timelines for blast furnace monitoring systems. Korean industrial safety regulations mandate documented refractory integrity for high-temperature process equipment. Pohang and Gwangyang steel complexes represent the fastest pilot-to-production adoption curves globally.
High-Temperature Furnace Refractory Lining Inspection Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in detector substrates and sensor modules. The vendor base splits between refractory manufacturers extending into diagnostics and pure-play inspection technology firms. Three archetypes dominate: refractory-captive service arms, autonomous robotics specialists, and thermal sensor platform vendors. Competitive moves concentrate on unbundling service contracts and backward integration into high-purity detector materials.
Within the refractory-captive tier, Vesuvius and RHI Magnesita exemplify players leveraging installed lining footprints to attach inspection service contracts. Saint-Gobain occupies a position bridging ceramic materials expertise with high-temperature diagnostic platforms. These three anchors represent contrasting geographic origins and corporate structures while competing for the same plant engineering procurement budgets.
| Leading Market Players |
|---|
| Vesuvius |
| RHI Magnesita |
| Saint-Gobain |
| Morgan Advanced Materials |
| HarbisonWalker International |
| Shinagawa Refractories |
| Krosaki Harima |
| Imerys |
| CoorsTek |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on semiconductor-grade indium antimonide and mercury cadmium telluride detector substrates determines both pricing tier spreads and supply chain shape in high-temperature furnace refractory lining inspection systems. Tariff exposure on Japanese and German sensor imports compresses margins for mid-tier platform integrators while reinforcing premium positioning for vendors with captive detector supply.
Pricing Analysis
EU Green Deal carbon intensity protocols dictate the pricing tier structure across the European steel belt. Three-tier pricing structure across premium, standard, and economy levels separates vendors with JIS-certified robotic platforms from regional integrators and rental service providers. Price differentiation hinges on after-sales service bundling and emissions documentation automation. Cost compression in the economy tier is intensifying because Turkish and Mexican foundries unbundle inspection hardware from refractory supply contracts. Independent metal foundries exhibit highest price sensitivity; integrated steel mills in Germany and Japan show lowest sensitivity due to campaign life economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now standard among Japanese sensor substrate suppliers are reshaping working capital requirements for Korean and Chinese system integrators. Detector fabrication concentrates in Germany and Japan; robotic crawler assembly clusters in South Korea and China. Raw material dependencies include indium antimonide wafers, mercury cadmium telluride crystals, and high-temperature ceramic sensor housings. Single-source vulnerability in semiconductor-grade refining capacity for detector substrates threatens component availability. Distribution runs through refractory manufacturers' captive service arms in Europe and independent inspection service providers in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous monitoring platforms are displacing periodic manual inspection contracts, forcing incumbents to defend against substitution by unbundled hardware vendors and independent service providers.
For Market Incumbents: Build data moats through continuous monitoring platform integration with plant distributed control systems. Incumbents must deepen backward integration into high-purity detector materials to offset substrate price volatility. Certification investment in EU CBAM-compliant documentation automation protects against emerging pure-play inspection technology firms. For New Entrants and Emerging Players: India's secondary steel expansion in Gujarat and Odisha represents the most penetrable geography for greenfield robotic system deployment. Glass regenerator wall monitoring for container production fuel efficiency compliance offers an underpenetrated application segment. New entrants should pursue direct commercial relationships with plant engineering departments, bypassing refractory manufacturers' captive service arms. For Investors and Strategic Acquirers: Autonomous robotics specialists with proven crawler platforms in steel mill environments present the most attractive acquisition target archetype. Long-term viability rests on the structural shift from five-year replacement cycles to eighteen-month retrofit programs across East Asian steel complexes. Investors should monitor adoption velocity in China's Tangshan steel clusters as the inflection indicator for platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Substrates | Captive supply of indium antimonide wafers insulates margin from semiconductor-grade refining bottlenecks. |
| CBAM Documentation Automation | Automated emissions-linked furnace seal integrity records satisfy EU carbon border adjustment mechanism requirements. |
| Robotic Crawler Platform Expansion | Autonomous deployment in molten metal zones eliminates human exposure while enabling continuous monitoring. |
| Multi-Spectral Sensor Array Development | Embedded edge computing renders manual thermographic surveys obsolete during scheduled furnace cooldowns. |
| Direct Plant Engineering Channel Buildout | Bypassing refractory supply bundling captures procurement authority from independent foundries in Turkey and Mexico. |
Research Methodology
A spread of perspectives from plant maintenance directors, refractory procurement leads, robotic systems engineers, and thermal sensor R&D directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with steel mill engineering departments and glass plant operations managers. Secondary validation drew from customs trade data, SEC filings of listed refractory manufacturers, MEE emissions permit documentation, and EU ETS carbon accounting disclosures. Bottom-up unit economics triangulated with top-down sectoral spending patterns.
Demand-supply balance modeling anchored the analytical framework across the projection horizon. Segmentation dimensions included technology type, deployment architecture, end-use vertical, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, technology refresh timelines, and policy-mandated inspection frequency compression. Industry-specific forecast inputs incorporated blast furnace rebuild schedules in Hebei province and EU CBAM implementation trajectories.
Practitioners should monitor semiconductor-grade indium supply constraints, MEE permit enforcement intensity, and carbon border adjustment mechanism rollout pace for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
Automated Test Equipment Market
Test and Measurement
Global Digital Measurement Instruments Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
Field Inspection Tester Market
Test and Measurement
Semiconductor Assembly and Testing Services Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Network Tester Market
Test and Measurement
Global Video Extensometer Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Wafer Inspection Market
Test and Measurement
Global Conductivity Meters Market
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market