
 Sand Abrasion Tester Market | 2026-2036
Sand Abrasion Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Sand Abrasion Tester Market Outlook
Aerospace coating validation is restructuring procurement priorities across the sand abrasion tester value chain. Taber Industries leverages its rotary platform heritage to dominate standardized wear testing protocols in North American quality control labs. Humboldt Mfg. Co. anchors its position through deep distribution into construction materials laboratories. Proinex Instruments s.r.o competes on custom chamber configurations for Central European research institutions.
A sand abrasion tester subjects surfaces to controlled particulate impingement to quantify erosion resistance, material loss rates, and protective coating durability under simulated environmental stress. Laboratory testers with programmable particle velocity and feed rate parameters command premium positioning due to repeatability requirements in certified testing workflows. Automated Systems represent the fastest-expanding product type segment as OEMs integrate inline abrasion monitoring into coating line quality gates. Digital technology adoption is displacing purely mechanical readout systems where data logging and SPC integration drive purchasing decisions.
ASTM International governs standard test methods for abrasion resistance in North American markets, while ISO 17025 accreditation requirements shape equipment specifications for third-party testing houses. The EU Machinery Directive and CE marking obligations constrain European supplier design architectures. Stakeholders must monitor evolving EV battery enclosure coating standards and offshore wind tower protection specifications as emerging demand vectors.
Market Dynamics
ASTM International and ISO protocol convergence is compressing equipment qualification timelines while aerospace coating validation programs intensify tester throughput requirements across certification laboratories.
Growth Catalysts
- EV battery enclosure coating mandates:Electric vehicle manufacturers require validated abrasion resistance for thermal management coatings, expanding tester deployment in automotive R&D facilities.
- ISO 9227 salt-spray crossover protocols:Combined corrosion-abrasion testing specifications are driving dual-capability equipment upgrades in third-party certification houses.
- Offshore wind tower protection specifications:Marine coating qualification programs in coastal manufacturing clusters are accelerating high-velocity particulate testing demand.
Market Restraints
- Corundum and silicon carbide grit supply volatility:Abrasive media cost fluctuations constrain operational budgeting for high-throughput testing facilities dependent on standardized particle feedstocks.
- Precision nozzle manufacturing concentration:Specialized ceramic nozzle suppliers cluster in German and Japanese industrial corridors, creating single-source vulnerability for velocity-calibrated components.
- CE marking compliance overhead:EU Machinery Directive conformity assessment timelines extend equipment delivery schedules for European-bound shipments.
Strategic Opportunities
- India's PLI scheme for advanced manufacturing:Production-linked incentive programs for automotive and aerospace components are stimulating metrology infrastructure investment in Pune and Chennai testing corridors.
- Inline coating line integration:Automated quality gate deployment enables real-time abrasion monitoring during protective layer application, displacing offline batch sampling.
- Digital twin convergence with physical testing:Correlating simulated particle impingement models with empirical tester data reduces material characterization cycles for coating formulators.
Industry Challenges
- ISO 17025 auditor calibration expertise:Accredited laboratory assessors with specific abrasion testing competency remain scarce, extending certification renewal timelines for equipment operators.
- Legacy mechanical readout system integration:Retrofitting analog-era testers with digital data acquisition modules requires specialized firmware development without standardized protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sand Abrasion Tester Market |
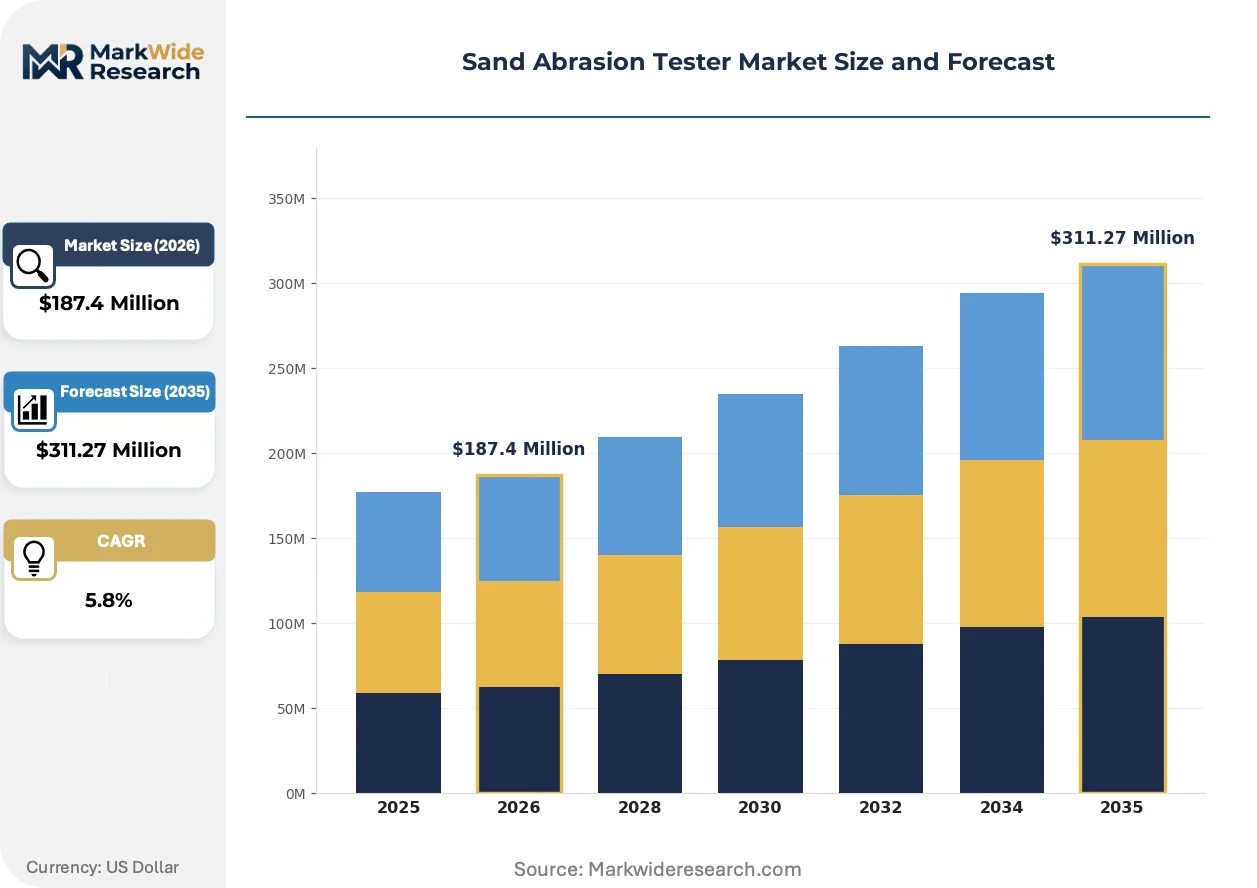
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerospace, Automotive, Construction, Electronics Product Type: Portable Testers, Laboratory Testers, Automated Systems, Custom Solutions End User: Manufacturers, Research Institutions, Quality Control Labs, OEMs Technology: Mechanical, Optical, Digital, Hybrid |
| Companies Covered | Taber Industries, Humboldt Mfg. Co., Proinex Instruments s.r.o, Gardner Company, Inc., Advance Equipment, TQC Sheen B.V., machtTechnik AG, The Tribology Company, Element Materials Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sand Abrasion Tester Market Strategic Shifts
Digital instrumentation architectures are displacing mechanical measurement systems while regulatory protocol harmonization compresses equipment design cycles. Three developments are restructuring competitive positioning.
Programmable particle velocity control with closed-loop feedback is consolidating laboratory-grade equipment specifications around repeatable impingement parameters. Aerospace coating developers in North American certification facilities are mandating digital velocity logging for ASTM G76 compliance documentation. This capability compression is marginalizing mechanical feed systems unable to deliver real-time SPC integration.
REACH substance restrictions on hexavalent chromium coatings are redirecting abrasion testing demand toward trivalent and chromium-free alternatives across European automotive supply chains. ECHA authorization requirements for legacy corrosion inhibitors are forcing coating reformulation programs that require revalidated abrasion resistance baselines. German automotive testing corridors are prioritizing multi-substrate validation capabilities to accommodate substrate-specific wear profiles.
Service-unbundling from equipment sales is restructuring vendor-customer relationships in quality control procurement. Third-party testing houses in China's coastal manufacturing zones are migrating toward calibration and maintenance contracts separate from capital acquisition. This contractual fragmentation favors suppliers with regional service infrastructure over distant manufacturers dependent on distributor networks.
Sand Abrasion Tester Market Segmentation
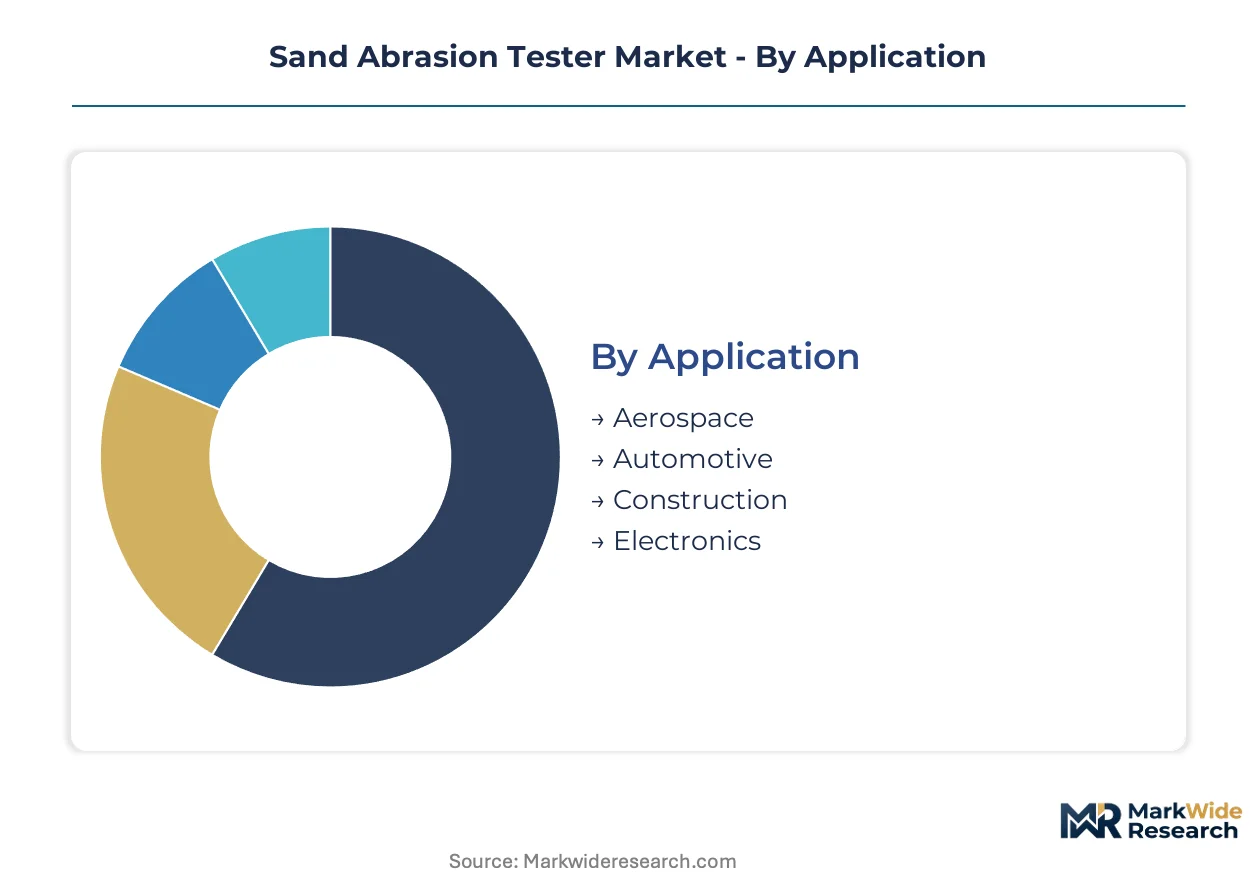
Sand abrasion tester procurement varies sharply by operational context. Certification requirements, throughput demands, and integration complexity drive divergent equipment specifications across buyer categories.
Application:
End-use certification stringency determines capital allocation priority.
- Aerospace:ASTM G76 compliance mandates programmable velocity control and digital data logging for coating validation programs. North American certification facilities and German testing corridors concentrate procurement for turbine blade and airframe protective layer qualification.
- Automotive:EV battery enclosure thermal management coatings require validated abrasion resistance under combined thermal-cycling stress. Germany's automotive testing corridor and China's coastal manufacturing zones anchor demand for multi-substrate validation capabilities.
- Construction:Concrete surface treatment and aggregate wear testing dominates materials laboratory procurement.
- Electronics:Thin-film coating durability for consumer device housings drives compact chamber specifications.
Volume sits with Automotive; growth tilts toward Aerospace.
Product Type:
Automation depth separates premium positioning from commodity procurement.
- Automated Systems:Closed-loop particle velocity feedback with real-time SPC integration commands premium positioning. Inline coating line quality gates in Chinese coastal manufacturing zones and North American automotive facilities are displacing offline batch sampling.
- Laboratory Testers:Programmable feed rate and impingement angle parameters serve certified testing workflows. Third-party certification houses prioritize ISO 17025 traceability features.
- Portable Testers:Field deployment for infrastructure coating inspection dominates construction and wind energy applications.
- Custom Solutions:Specialized chamber geometries for research institutions accommodate non-standard substrate dimensions.
Revenue concentrates in Laboratory Testers; capability investment flows fastest toward Automated Systems.
End User:
Accreditation status shapes equipment specification complexity.
- Quality Control Labs:ISO 17025 accreditation requirements mandate calibration traceability and audit documentation capabilities. Third-party certification houses in China and Central Europe drive dual-capability equipment upgrades for combined corrosion-abrasion protocols.
- Research Institutions:Custom chamber configurations and multi-parameter flexibility priority. Central European universities and North American materials science programs dominate procurement.
- Manufacturers:Inline integration and throughput optimization for production-line quality gates.
- OEMs:Supplier qualification programs and coating vendor certification requirements.
Equipment sophistication peaks in Quality Control Labs; procurement volume runs through Manufacturers.
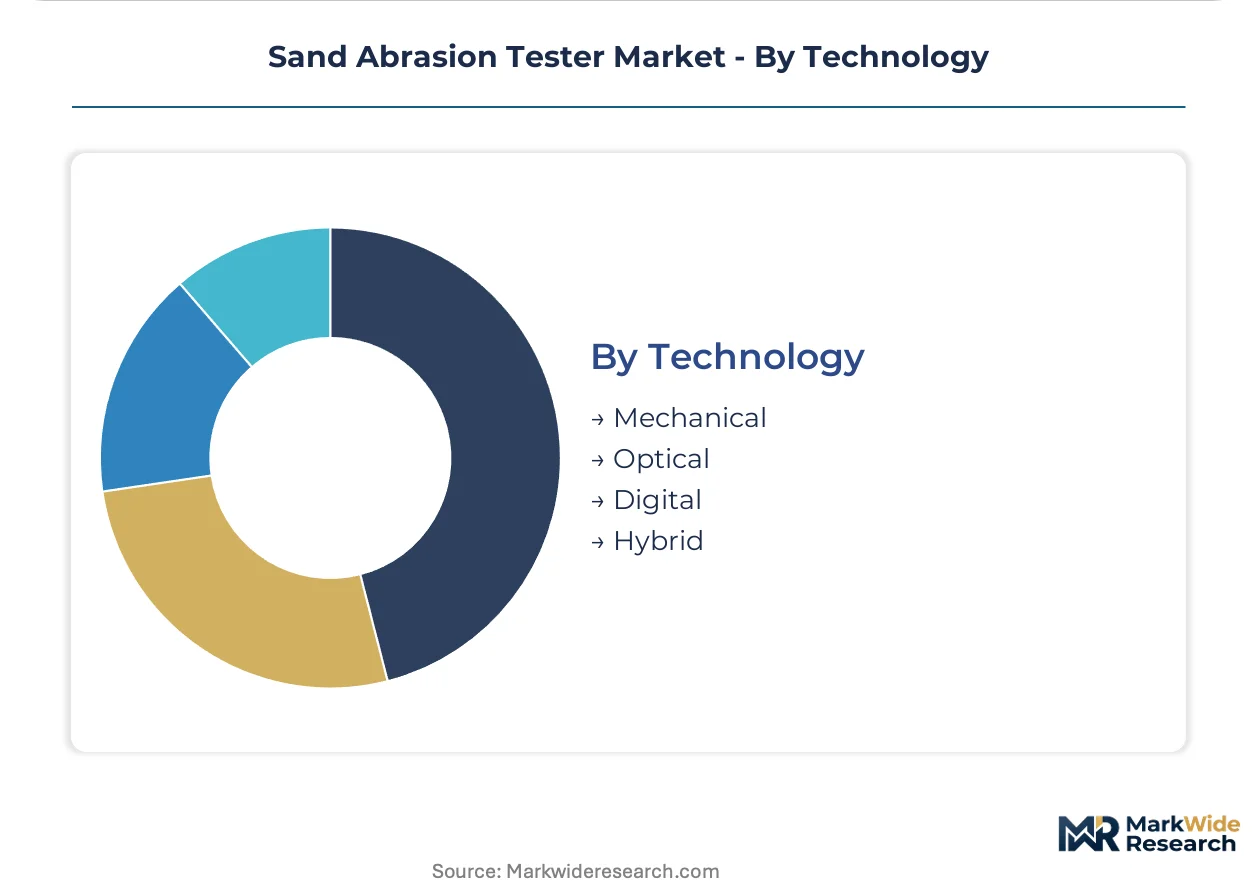
Technology:
Data architecture determines competitive viability in certified workflows.
- Digital:Real-time velocity logging, automated feed rate adjustment, and direct LIMS integration displace mechanical systems. ASTM G76 compliance documentation requirements in North American aerospace facilities mandate digital instrumentation.
- Hybrid:Mechanical impingement with digital acquisition bridges legacy infrastructure and modern data requirements.
- Optical:Non-contact wear measurement for delicate coating surfaces.
- Mechanical:Analog readout systems face displacement except in budget-constrained emerging market procurement.
Installed base remains Mechanical; replacement demand concentrates in Digital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration tilts toward coastal Asia while certification demand concentrates in Western Europe and North America. Equipment flows from German and Japanese precision fabricators toward testing facilities in China and India. Regulatory protocol divergence between ASTM and ISO jurisdictions shapes regional procurement specifications.
United States
FAA airworthiness directives and NHTSA automotive safety mandates drive aerospace and EV battery enclosure testing demand. ASTM G76 compliance documentation requirements govern coating validation workflows for turbine blade manufacturers. Certification facilities in Wichita, Kansas and Seattle, Washington anchor procurement for military and commercial aviation programs.
Germany
REACH substance restrictions on hexavalent chromium coatings redirect abrasion testing toward trivalent alternatives across automotive supply chains. KBA type-approval protocols mandate validated wear resistance for EV thermal management systems. The automotive testing corridor spanning Stuttgart, Munich, and Wolfsburg concentrates multi-substrate validation equipment deployment.
China
GB standards alignment with ISO 9227 protocols accelerates dual-capability equipment upgrades in third-party certification houses. MIIT industrial quality mandates expand metrology infrastructure investment across coastal manufacturing zones. Testing facilities in Shanghai, Shenzhen, and Tianjin prioritize inline automated systems for coating line quality gates.
India
PLI scheme incentives for automotive and aerospace component manufacturing stimulate metrology infrastructure investment in emerging industrial corridors. BIS certification requirements tighten equipment specifications for domestic testing laboratories. Pune and Chennai testing corridors anchor procurement growth as OEMs localize supplier qualification programs.
Japan
METI industrial standardization initiatives harmonize JIS abrasion testing protocols with ASTM and ISO frameworks for export-oriented manufacturers. Precision nozzle component fabrication clusters in Nagoya and Osaka supply velocity-calibrated subassemblies to global equipment integrators. Domestic automotive OEMs mandate digital instrumentation for coating vendor certification programs.
Sand Abrasion Tester Market Competitive Environment
Top-tier vendors anchor aerospace and automotive certification workflows, while mid-tier specialists serve construction materials and research institutional demand. The vendor base stratifies across precision instrumentation heritage, regional distribution depth, and custom chamber engineering capability. Three archetypes dominate: rotary platform specialists with standardized protocol dominance, construction materials laboratory suppliers with distribution breadth, and Central European custom fabricators with research institutional relationships. Competitive moves concentrate on regional service infrastructure expansion and digital instrumentation retrofit capabilities for legacy installed bases.
Within the precision instrumentation tier, Taber Industries and Humboldt Mfg. Co. exemplify divergent strategic positioning. Taber Industries occupies a position tied to rotary platform heritage and ASTM protocol standardization, while Humboldt Mfg. Co. anchors construction materials laboratory penetration through North American distribution density. Proinex Instruments s.r.o represents the Central European custom fabrication archetype, serving research institutions with specialized chamber configurations.
| Leading Market Players |
|---|
| Taber Industries |
| Humboldt Mfg. Co. |
| Proinex Instruments s.r.o |
| Gardner Company, Inc. |
| Advance Equipment |
| TQC Sheen B.V. |
| machtTechnik AG |
| The Tribology Company |
| Element Materials Technology |
| Others |
Value Chain & Pricing Dynamics
Family-owned precision instrumentation specialists in Germany and Japan anchor component fabrication for velocity-calibrated nozzles, creating supply scarcity that feeds pricing discipline across equipment tiers. Their captive control over ceramic machining expertise limits margin compression in premium laboratory-grade systems even as automated testers face cost-down pressure from Chinese coastal manufacturers.
Pricing Analysis
Margin tightening in mid-tier laboratory testers reflects corundum grit supply volatility and ISO 17025 calibration overhead transfer to buyers. Three-tier pricing structure across premium, standard, and economy levels separates ASTM G76-compliant digital systems from mechanical readout legacy units and unaccredited portable field devices. Certification grade and after-sales service bundling drive price differentiation, with third-party testing houses showing highest price sensitivity and aerospace certification facilities least willing to trade specification compliance for cost reduction.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's MIIT industrial quality programs are reshaping sourcing patterns for metrology infrastructure. Precision nozzle fabrication concentrates in Germany and Japan, while automated system assembly clusters in China's coastal manufacturing zones. Ceramic feedstock and silicon carbide abrasive media dependencies create single-source vulnerability for velocity-calibrated components. Distribution runs through regional service infrastructure rather than distant manufacturer-direct channels, favoring vendors with calibration and maintenance capabilities in proximity to end-user testing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASTM International protocol convergence with ISO frameworks erects a cost-of-compliance barrier that protects accredited equipment vendors from commodity entrants while forcing margin investment in certification documentation capabilities.
For Market Incumbents: Deepen regional service infrastructure in China's coastal manufacturing zones and India's Pune-Chennai corridors to defend against distributor-network displacement. Backward integration into ceramic nozzle fabrication mitigates German-Japanese supplier concentration risk. Prioritize digital instrumentation retrofit capabilities for legacy mechanical installed bases to capture replacement demand without ceding share to emerging automation specialists. For New Entrants and Emerging Players: Direct-to-research-institution digital channels bypass incumbent distributor lock-in across Central European university procurement. White-space concentration sits with custom chamber configurations for non-standard substrate dimensions where Proinex Instruments s.r.o archetype relationships dominate. Target inline coating line integration for automotive OEM quality gates in China's Shenzhen-Tianjin manufacturing belt as the most penetrable automated systems segment. For Investors and Strategic Acquirers: EV battery enclosure coating mandate acceleration is the leading indicator that automotive R&D facility tester deployment will outpace aerospace certification demand. Five-to-ten year viability favors vendors with dual-capability corrosion-abrasion equipment aligned to ISO 9227 crossover protocols. Acquisition target archetype: regional service-embedded mid-caps with ISO 17025 auditor relationships and firmware development capabilities for legacy system retrofit.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Service Infrastructure Expansion | Calibration proximity requirements in China's coastal zones favor local maintenance contracts over distant manufacturer support. |
| Digital Instrumentation Retrofit Development | Firmware modules bridging mechanical legacy systems to LIMS integration capture replacement cycles in North American quality control labs. |
| Ceramic Nozzle Fabrication Integration | Upstream control over velocity-calibrated components reduces German-Japanese supplier dependency and protects margin structure. |
| Inline Coating Line Partnership | Automotive OEM quality gate deployment in Germany's Stuttgart-Munich corridor displaces offline batch sampling workflows. |
| Dual-Capability Equipment Certification | Combined corrosion-abrasion testing alignment to ISO 9227 protocols opens third-party certification house upgrade demand in China. |
Study Parameters
Document review covered ASTM International and ISO protocol documentation, EU Machinery Directive regulatory filings, and customs trade data for precision instrumentation imports, complemented by interviews with laboratory accreditation officers, coating validation engineers at aerospace certification facilities, automotive OEM procurement leads, and aftermarket service heads at regional testing equipment distributors. Secondary validation drew from SEC 10-K filings of precision instrumentation manufacturers, BIS certification registries, and MIIT industrial quality mandate disclosures. Bottom-up equipment deployment estimates triangulated against top-down market sizing from manufacturing value-added projections.
Unit shipment and revenue outputs trace to a segmentation framework spanning product type automation depth, application certification stringency, end-user accreditation status, and technology architecture across the projection horizon. CAGRs derive from regression against correlated industrial capital expenditure indices and coating formulation R&D spending patterns. Modeled inputs include EV battery enclosure thermal management coating mandate timelines and offshore wind tower marine protection specification adoption curves.
The model holds under continued ASTM-ISO protocol convergence and stable abrasive media supply chains; deviation in REACH substance restriction acceleration or ceramic feedstock export controls would shift equipment qualification timelines and regional procurement patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Tube Tester Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Radiography Test Equipment Market
Test and Measurement
North America Electrical Testing Services Market
Test and Measurement
Signal Generator Market
Test and Measurement
Battery Capacity Testers Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Hardware-Assisted Verification Market
Test and Measurement
Thin Film Metrology Systems Market
Test and Measurement
Pump Testers Market
Test and Measurement
Compression Testing Machines Market
Test and Measurement
Psophometer Market
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market
Test and Measurement
Impact Testing Machine Market