
 Industrial X-Ray Inspection System Market | 2026-2036
Industrial X-Ray Inspection System Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial X-Ray Inspection System Market Intelligence
Direct sales channels to large-scale automotive and aerospace manufacturers are reconfiguring the supply chain for integrated systems. This shift favors suppliers with extensive service networks and application support. Mettler Toledo leverages its broad industrial footprint to offer comprehensive quality assurance solutions. Nordson Corporation specializes in precision dispensing and inspection for electronics manufacturing, while Viscom AG dominates the niche of automated optical and X-ray inspection for PCB assembly.
An industrial X-ray inspection system is a non-destructive testing apparatus that uses controlled X-radiation to visualize the internal structure of materials and components. These systems detect subsurface defects such as cracks, porosity, and foreign inclusions without damaging the part. Within product types, digital radiography and computed tomography systems command higher margins due to their superior imaging and analytical capabilities. Demand from electronics testing and aerospace component evaluation applications is outpacing traditional weld inspection, driving innovation in high-resolution detectors.
Regulatory frameworks like ISO 9001 for quality management and specific industry standards from bodies such as the US FDA for medical device components mandate rigorous inspection protocols. In Europe, CE marking compliance requires adherence to safety and performance directives for electronic equipment, influencing system design. Stakeholders must now decide whether to invest in advanced AI-powered defect recognition software or focus on hardware upgrades to meet next-generation inspection accuracy demands.
Market Dynamics
The central force shaping the market is the convergence of stringent quality mandates from safety-critical industries and the technological maturation of digital radiography. This combination is shifting inspection from a post-production quality check to an integrated, in-line process control function.
Growth Catalysts
- Stringent Aerospace Standards:Regulations from bodies like the US FAA mandate exhaustive inspection of critical flight components, such as turbine blades and composite structures, directly stimulating demand for high-resolution computed tomography systems.
- Additive Manufacturing Adoption:The expansion of 3D printing for metal parts in automotive and medical implants requires volumetric inspection to detect internal porosity and lack of fusion, a task for which CT is uniquely suited.
- Electronics Miniaturization:China's dominance in advanced electronics manufacturing drives demand for high-magnification X-ray systems to inspect micro-scale solder joints, BGAs, and internal semiconductor packaging for defects.
Market Restraints
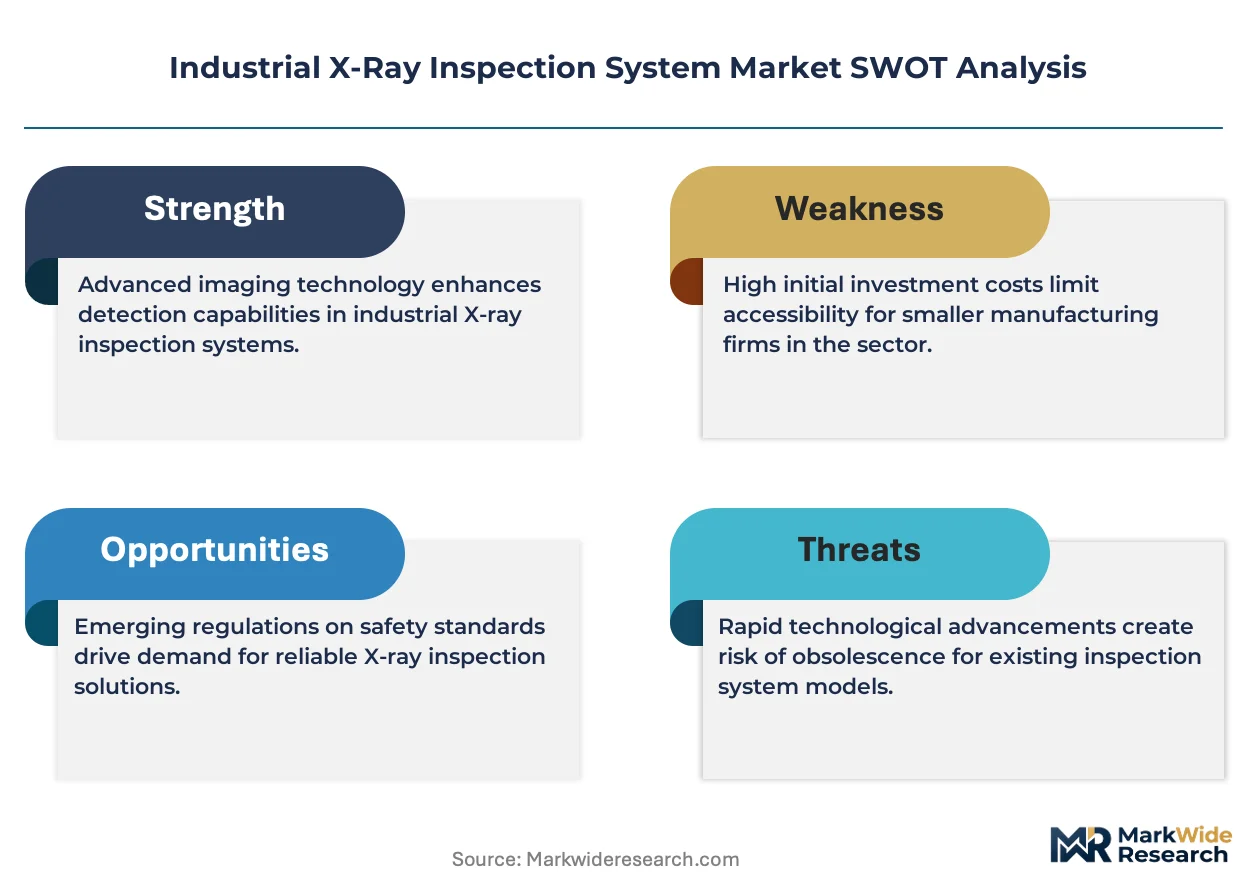
- High Capital Investment:The significant upfront cost of acquiring advanced computed tomography and high-energy digital radiography systems presents a substantial barrier for small and medium-sized enterprises.
- Material Penetration Limits:X-ray inspection is less effective for very large or dense components, as the radiation cannot penetrate the material sufficiently to produce a clear image, limiting its use in some heavy industrial applications.
- Specialized Component Supply:The supply of critical components like high-performance X-ray tubes and sensitive digital detectors is concentrated among a few global suppliers, creating potential supply chain vulnerabilities and pricing power.
Strategic Opportunities
- Electric Vehicle Battery Inspection:The imperative to ensure the safety and reliability of EV battery packs creates a major opportunity for automated X-ray systems to detect internal shorts, weld defects, and electrode misalignments.
- AI-Powered Defect Recognition:Integrating artificial intelligence and machine learning algorithms with inspection systems to automate defect detection can significantly increase throughput and reduce reliance on skilled human operators. *Service and Data Monetization: Offering inspection-as-a-service or subscription-based access to advanced systems and analytical software provides a recurring revenue stream and lowers the adoption barrier for new customers.
Industry Challenges
- Skilled Operator Scarcity:A persistent shortage of certified NDT Level II and Level III radiographers capable of operating advanced systems and interpreting complex 3D CT data slows adoption and limits operational efficiency.
- Data Integration Complexity:Integrating the large volumetric datasets generated by CT systems into existing factory Manufacturing Execution Systems (MES) and Product Lifecycle Management (PLM) platforms is a significant technical hurdle.
- Cybersecurity of Connected Systems:As inspection systems become networked for remote diagnostics and data transfer, they become vulnerable to cybersecurity threats, requiring robust security protocols to protect sensitive intellectual property.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial X-Ray Inspection System Market |
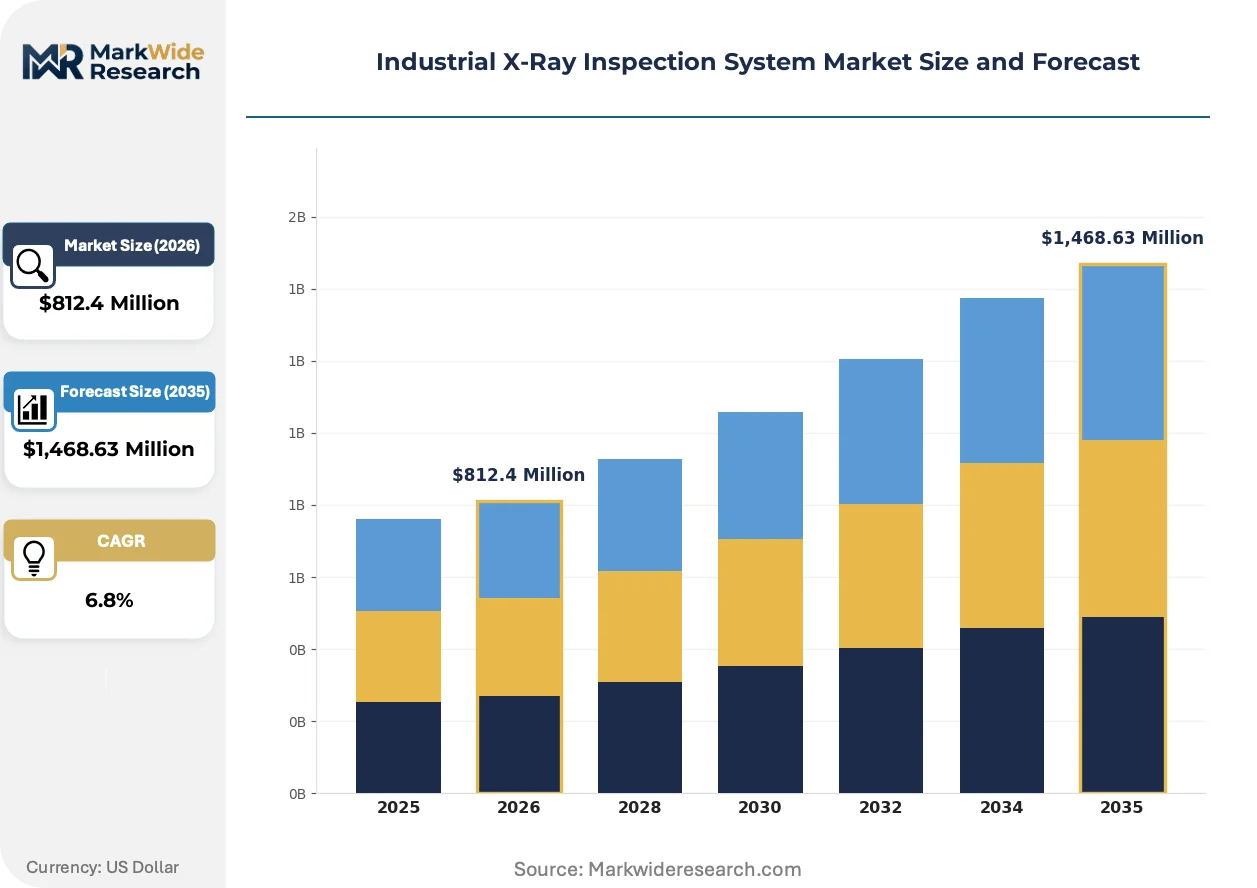
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,468.63 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog X-Ray Systems, Digital Radiography, Computed Tomography, Portable X-Ray Machines, Flat Panel Detectors Technology: Film Radiography, Computed Radiography, Direct Digital Radiography, Microfocus X-Ray, Cone Beam CT Application: Weld Inspection, Casting Analysis, Electronics Testing, Aerospace Component Evaluation, Pipeline Integrity End User: Manufacturing Plants, Quality Assurance Facilities, Maintenance Workshops, Research Laboratories |
| Companies Covered | Viscom AG, General Electric, Mettler Toledo, North Star Imaging Inc., Anritsu, Nordson Corporation, Nikon Corporation, Varex Imaging, Comet Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial X-Ray Inspection System Market Strategic Shifts & Innovations
The market's evolution is defined by the push to embed automated, data-rich inspection directly into the manufacturing workflow. This transforms X-ray systems from standalone quality gates into integral sources of real-time production intelligence, enabling faster feedback loops and process optimization.
Digital radiography (DR) and computed tomography (CT) use flat-panel detectors to capture high-resolution internal images instantly. Aerospace, electronics, and medical device manufacturers are leading the adoption for comprehensive part verification. This capability for rapid, high-fidelity data acquisition is rendering obsolete the slower, film-based radiographic methods that require chemical processing and offline manual interpretation.
European Union regulations, including the Medical Device Regulation (MDR) and directives influencing the EU Green Deal, demand greater component traceability and quality documentation. This creates an industrial requirement for immutable, digital records of internal part quality at the point of manufacture. The automotive and medical device sectors are most affected, responding by archiving digital X-ray and CT data as part of the component's digital passport.
A distinct behavioral change is emerging as some end-users move from outright equipment purchase to more flexible consumption models. This shift toward "Inspection-as-a-Service" disrupts the traditional direct sales channel by allowing smaller manufacturers to access advanced CT capabilities on a pay-per-use basis. This trend is most prominent in high-mix, low-volume contract manufacturing environments, particularly within the electronics and medical device sectors in Mexico and Eastern Europe.
Industrial X-Ray Inspection System Market Segmentation
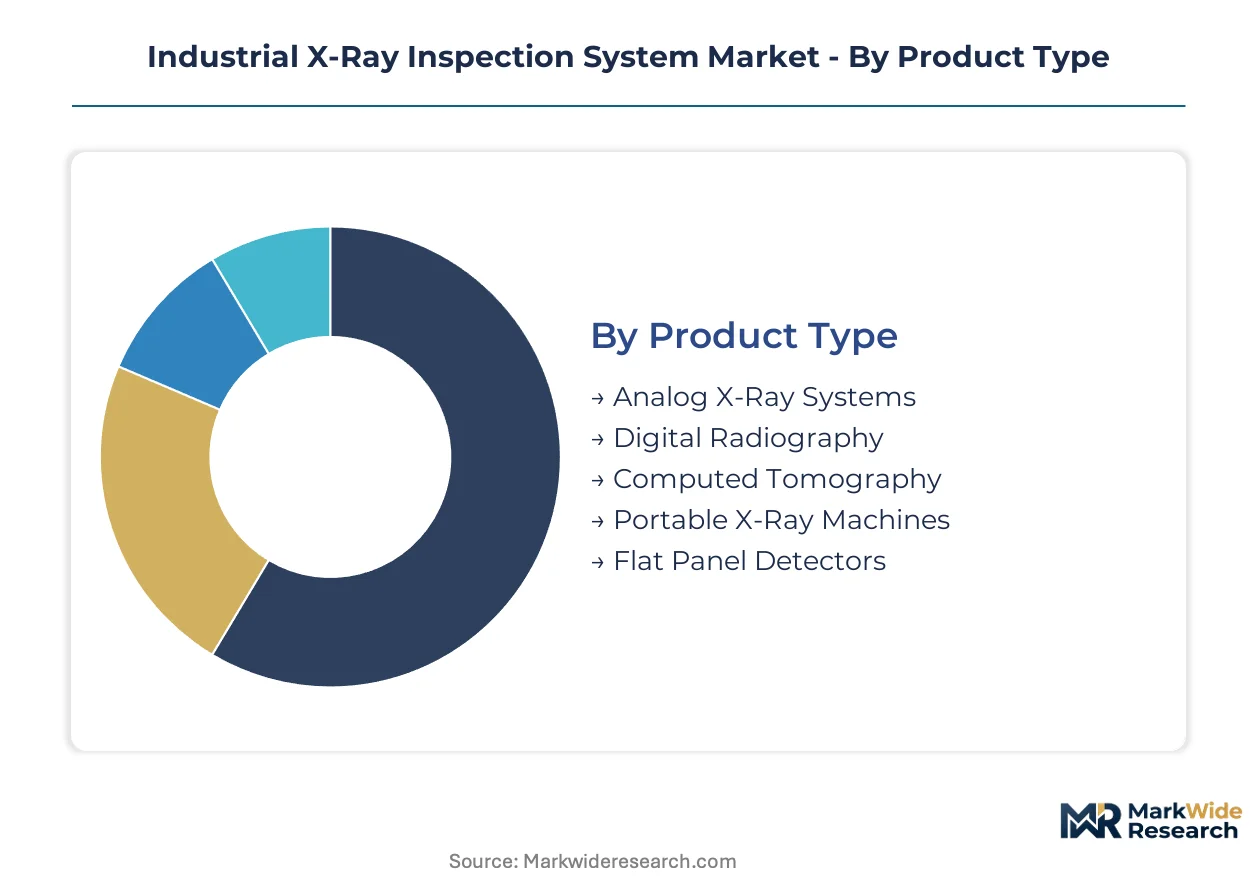
The segmentation of the industrial X-ray inspection system market provides a structured understanding of technology adoption patterns and diverse end-user requirements. Analyzing these distinct segments helps stakeholders identify high-growth areas and tailor product development to specific industry needs, from advanced electronics to critical aerospace components.
Product Type:
The product type segment reflects a maturity spectrum, from established analog systems to rapidly evolving digital and computed tomography solutions. This differentiation highlights the shift towards higher resolution and analytical capabilities across industrial applications.
- Digital Radiography:These systems capture high-resolution internal images instantly using flat-panel detectors, replacing slower film-based methods. Aerospace and electronics manufacturers lead adoption for comprehensive part verification and real-time defect detection.
- Computed Tomography:Offering full 3D volumetric data, CT systems detect complex internal porosity and lack of fusion in additively manufactured metal parts. Demand from medical implant and electric vehicle battery inspection is particularly strong.
- Analog X-Ray Systems:These traditional systems utilize film for image capture, requiring chemical processing and manual interpretation. Analog systems maintain a presence in cost-sensitive applications where immediate digital feedback is not critical.
- Portable X-Ray Machines:Designed for field use and on-site inspections, these compact units offer flexibility for pipeline integrity checks and maintenance workshops. Their mobility supports non-destructive testing in remote or hard-to-reach locations.
- Flat Panel Detectors:These advanced components are integral to modern digital radiography and computed tomography systems, enabling high-speed image acquisition. Their superior sensitivity and dynamic range drive innovation in detector technology for various industrial uses.
Digital Radiography retains volume leadership; Computed Tomography holds the steepest expansion curve.
Technology:
This category delineates the market based on the underlying imaging methodology, driven by application-specific demands for image quality, speed, and analytical depth.
- Direct Digital Radiography:This technology provides instantaneous digital X-ray images, enabling high throughput and efficient quality control in manufacturing plants. It eliminates film processing, significantly reducing inspection time for components in automotive and electronics.
- Cone Beam CT:A specialized form of computed tomography, Cone Beam CT offers rapid 3D reconstruction with high detail, particularly suited for smaller objects and intricate geometries. It is essential for internal analysis of EV battery cells and microelectronics packaging.
- Film Radiography:An older technology relying on X-ray sensitive film, it provides permanent records but requires chemical development and manual interpretation. This method is still employed in some weld inspection and casting analysis scenarios due to its established use and lower initial cost.
- Computed Radiography:Utilizing reusable imaging plates, computed radiography bridges the gap between film and direct digital methods, offering digital images from traditional X-ray sources. It provides improved contrast and dynamic range over film for various industrial components.
- Microfocus X-Ray:These systems generate extremely small X-ray spots, allowing for high-magnification imaging of very small features and defects. Electronics manufacturing relies on microfocus X-ray for inspecting fine solder joints and semiconductor components.
The shift from Film Radiography to Direct Digital Radiography and Cone Beam CT reflects industry requirements for real-time data and volumetric analysis.
Application:
The application segment highlights the diverse industrial uses of X-ray inspection, driven by critical quality and safety requirements across various sectors.
- Electronics Testing:This application involves inspecting micro-scale solder joints, BGAs, and internal semiconductor packaging for defects, ensuring reliability of electronic devices. China's advanced electronics manufacturing sector drives significant demand for high-magnification X-ray systems here.
- Aerospace Component Evaluation:Mandated by regulations like those from the US FAA, this application requires exhaustive inspection of critical flight components such as turbine blades and composite structures. High-resolution computed tomography systems are essential for detecting internal flaws.
- Weld Inspection:A traditional application, weld inspection uses X-ray systems to detect internal defects like porosity, cracks, and inclusions in welded joints. This ensures structural integrity in industries such as oil and gas, and shipbuilding.
- Casting Analysis:X-ray inspection identifies subsurface defects such as shrinkage, gas porosity, and inclusions in metal castings. This application is crucial for quality control in automotive and heavy machinery manufacturing.
- Pipeline Integrity:X-ray systems are deployed to assess the structural integrity of pipelines, detecting corrosion, cracks, and weld defects. This ensures safe operation and compliance with environmental regulations in the energy sector.
Demands from Electronics Testing are spurring innovation, while Weld Inspection maintains a stable base.
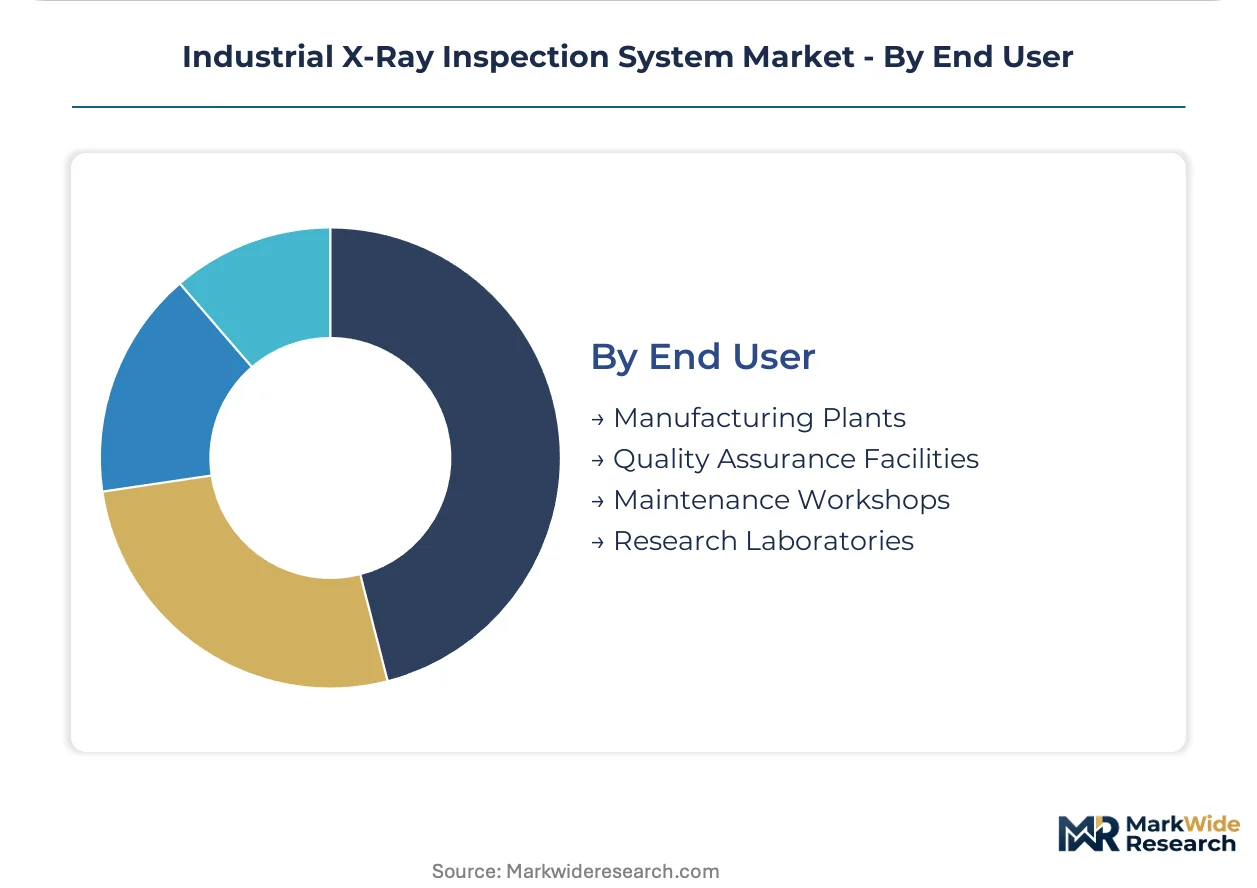
End User:
This segment categorizes the market by the type of facility employing X-ray inspection systems, reflecting their distinct operational focus and inspection needs.
- Manufacturing Plants:These facilities integrate X-ray systems into production lines for in-line process control, enabling real-time defect detection and quality assurance. This integration supports faster feedback loops and process optimization in industries like automotive and electronics.
- Quality Assurance Facilities:These dedicated centers utilize advanced X-ray systems for final product verification, compliance testing, and detailed failure analysis. They ensure adherence to stringent industry standards like ISO 9001 and specific US FDA protocols for medical devices.
- Maintenance Workshops:Workshops use portable and fixed X-ray systems for routine inspection and troubleshooting of components in service. This helps detect wear, fatigue, or damage in machinery parts before critical failures occur.
- Research Laboratories:These facilities employ high-resolution X-ray and CT systems for material science studies, new product development, and advanced defect characterization. Laboratories require versatile systems capable of detailed analysis for various experimental purposes.
While Manufacturing Plants represent a significant installed base, Quality Assurance Facilities drive demand for specialized analytical capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry between China and the United States reflects distinct manufacturing ecosystems and regulatory landscapes in the industrial X-ray inspection system market. China's volume-driven electronics sector demands cost-effective solutions, while the US aerospace industry prioritizes high-precision, high-cost systems. This divergence shapes product development and market penetration strategies across key global regions.
China
China's advanced manufacturing and electronics sectors drive substantial demand for high-magnification X-ray systems, particularly for inspecting micro-scale components. The MIIT's push for industrial modernization and the "Made in China 2025" initiative support domestic innovation in inspection technologies. Major electronics manufacturing hubs like Shenzhen and Suzhou see significant adoption of these systems for quality control.
United States
The United States aerospace and medical device industries require rigorous inspection protocols for critical components, fueling demand for high-resolution computed tomography systems. Regulations from the US FAA mandate exhaustive inspection of flight-critical parts, ensuring stringent quality standards. Defense and aerospace clusters in states like California and Washington are primary markets for advanced NDT solutions.
Germany
Germany's robust automotive and industrial machinery sectors necessitate advanced X-ray inspection for quality assurance in complex parts. CE marking compliance and the EU Green Deal's emphasis on product longevity influence system design for safety and performance. The Stuttgart and Munich regions, with their strong automotive and engineering bases, are key demand centers.
Japan
Japan's precision manufacturing and automotive industries demand high-accuracy X-ray inspection systems for defect detection in intricate components. JIS standards for industrial products reinforce the need for reliable non-destructive testing capabilities. Automotive manufacturing centers around Nagoya and electronics clusters in Tokyo drive innovation and adoption.
South Korea
South Korea's dominance in advanced electronics and battery manufacturing creates a strong market for microfocus X-ray systems and CT for defect detection. The country's national regulators emphasize product quality and safety, particularly for consumer electronics and EV batteries. Major technology hubs in Seoul and Gyeonggi Province lead the integration of these inspection technologies.
Industrial X-Ray Inspection System Market Key Industry Players
Specialized equipment providers and diversified industrial conglomerates split the market for industrial X-ray inspection systems. The competitive structure is tiered, ranging from niche players focusing on specific technologies to broad-portfolio companies serving multiple industrial sectors. Strategic partnerships and technology licensing are prevalent competitive moves, enabling faster market penetration and access to specialized expertise.
Within the specialized equipment sector, Viscom AG and Nordson Corporation exemplify companies with deep expertise in automated optical and X-ray inspection for PCB assembly and precision dispensing. These entities often concentrate on high-growth applications like electronics manufacturing, leveraging their focused R&D to deliver cutting-edge solutions. General Electric, as a diversified industrial giant, represents the broader market approach, offering a wide range of inspection technologies across aerospace and other heavy industries, often integrating these solutions into larger industrial service contracts.
| Leading Market Players |
|---|
| Viscom AG |
| General Electric |
| Mettler Toledo |
| North Star Imaging Inc. |
| Anritsu |
| Nordson Corporation |
| Nikon Corporation |
| Varex Imaging |
| Comet Group |
| Others |
Cost & Logistics Intelligence
Shenzhen's high-volume electronics manufacturing capacity drives demand for cost-effective X-ray systems, influencing price points across the global market. This dynamic creates a pricing power asymmetry, especially for component suppliers.
Pricing Analysis
Configured-to-order pricing for advanced computed tomography systems commands a premium, reflecting their specialized capabilities and integration complexity. Price differentiation stems from customization levels for high-resolution detectors and the inclusion of extensive after-sales service networks. Pricing softness affects standard digital radiography systems, particularly in cost-sensitive markets like China, due to increased volume and competition. Small and medium-sized enterprises exhibit higher price sensitivity, often preferring flexible consumption models like Inspection-as-a-Service, while large aerospace manufacturers prioritize performance over cost.
Supply Chain Analysis
Single-source vulnerability for specialized X-ray tubes and sensitive digital detectors creates a significant supply chain risk, as production concentrates among a few global suppliers primarily in Europe and Japan. This dependency on critical components, such as advanced flat-panel detectors, can lead to pricing power for these suppliers. The distribution model increasingly involves direct sales to large industrial end-users for integrated systems, while "Inspection-as-a-Service" models gain traction for smaller enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial X-ray inspection market presents a fragmentation opportunity, driven by the specialized demands of electric vehicle battery inspection. This shift creates distinct niches for automated, high-resolution systems tailored to specific material and defect types.
For Market Incumbents: Build technological moats around AI-powered defect recognition software and advanced computed tomography capabilities to counter emerging niche players. Incumbents should deepen vertical integration into flat-panel detector manufacturing to secure supply and manage costs. Expanding extensive service networks and application support strengthens customer loyalty, mitigating the threat from lower-cost, less comprehensive solutions. Investment in R&D for next-generation inspection accuracy maintains a competitive edge.
For New Entrants and Emerging Players: Pursue specialized niches in electric vehicle battery inspection or micro-scale electronics testing, leveraging advanced AI-powered defect recognition. The most penetrable segment lies within small and medium-sized enterprises in regions like Mexico, seeking flexible access to advanced CT capabilities. A key go-to-market angle involves offering Inspection-as-a-Service models, lowering capital investment barriers and providing recurring revenue streams. Focus on software-centric solutions that integrate seamlessly with existing manufacturing execution systems.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors agile software specialists and advanced component manufacturers within the X-ray inspection ecosystem. Long-term viability over the next decade is strong, driven by persistent quality mandates in safety-critical industries. Acquisition targets should include firms developing cutting-edge AI-powered defect recognition software or high-resolution flat-panel detectors. The signal to watch is the increasing integration of inspection data with factory MES and PLM platforms, indicating broader digital transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Development | Enhances defect detection accuracy and reduces reliance on skilled human operators. |
| Service Network Expansion | Provides comprehensive application support to large-scale automotive and aerospace manufacturers. |
| Advanced Detector R&D | Improves imaging capabilities for high-resolution digital radiography and computed tomography systems. |
| MES/PLM Integration | Enables real-time data flow from inspection systems into factory production intelligence. |
| Inspection-as-a-Service Rollout | Lowers adoption barriers for smaller enterprises and creates recurring revenue streams. |
Research Approach
The analysis maps industrial X-ray inspection sub-sectors, each validated through primary interviews with manufacturing plant managers and quality assurance directors. This approach combined insights from NDT Level II/III radiographers and R&D engineers with secondary data from industry association reports and regulatory filings. Technology patent databases and academic research papers further informed the market landscape. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
Assumptions regarding the pace of digital radiography adoption were held fixed, while computed tomography system penetration varied across the analysis window. The analytical framework modeled segmentation dimensions including Product Type, Technology, Application, End User, and regional regulatory clusters. Compound annual growth rates were derived by projecting technological adoption curves and evolving industry quality mandates. Key forecast inputs included electric vehicle battery production forecasts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized software firms or new component manufacturers would shift outcomes. Forecasts reflect assumptions regarding technological maturation and sustained investment in quality control. Supply chain vulnerabilities and rapid shifts in regulatory frameworks represent key risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Semiconductor Chip Test Probes Market
Test and Measurement
Receptacle Tester Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
Global Reflux Testing Products Market
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
Sound Level Meter Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
Global Source Measure Unit Market
Test and Measurement
Compression Testing Machines Market
Test and Measurement
Heat Deformation Tester Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Solid-State Battery Fast-Charge Degradation Test Systems Market
Test and Measurement
Shock Data Logger Market
Test and Measurement
Sound Level Measurement Meter Market
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
Ceramic Tester Market