
 Automated Optical Inspection Market | 2026-2036
Automated Optical Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Optical Inspection Market Analysis
Silicon photonics substrates are replacing traditional interposer materials in high-bandwidth packaging, and this substitution is expanding the addressable base for sub-micron defect detection. KLA Corporation leverages deep ultraviolet imaging architectures to sustain technology leadership in wafer-level inspection. Koh Young Technology Inc. anchors its position through dominant 3D solder paste inspection share in East Asian electronics manufacturing. Omron Corporation differentiates via embedded machine vision modules that integrate directly into SMT line controllers.
Automated optical inspection denotes machine-vision systems that capture high-resolution images of electronic assemblies, comparing them against CAD-derived golden references at throughput rates exceeding 100 cm² per second to flag dimensional, positional, and cosmetic anomalies. The primary commercial purpose centers on eliminating defective boards before functional test, thereby reducing scrap cost and warranty exposure in high-volume electronics production. 3D inspection commands the steepest growth trajectory as stacked die and micro-bump architectures proliferate, while 2D inspection retains volume dominance in mature PCB segments where cost sensitivity prevails. Semiconductor applications concentrate margin pools due to die-level resolution requirements and qualification barriers that limit vendor participation.
FDA quality system regulations for medical device producers mandate validated inspection protocols that elevate AOI from efficiency tool to compliance necessity. REACH restrictions on lead-based solders and RoHS substance thresholds reshape alloy compositions, forcing optical systems to recalibrate for altered surface reflectivity and joint geometry. The EU AI Act introduces algorithmic transparency requirements that will affect machine-learning defect classification modules deployed in European electronics facilities. Stakeholders must monitor how emerging sustainability disclosure rules under CSRD reshape capital allocation toward inspection equipment that demonstrably reduces material waste.
Market Dynamics
Silicon photonics substrates are displacing traditional interposer materials in high-bandwidth packaging, forcing inspection systems to resolve sub-micron defects on optically active surfaces that previous generations could not characterize. This materials transition concentrates investment in deep ultraviolet and structured-light architectures capable of detecting dimensional anomalies at die-level resolution.
Growth Catalysts
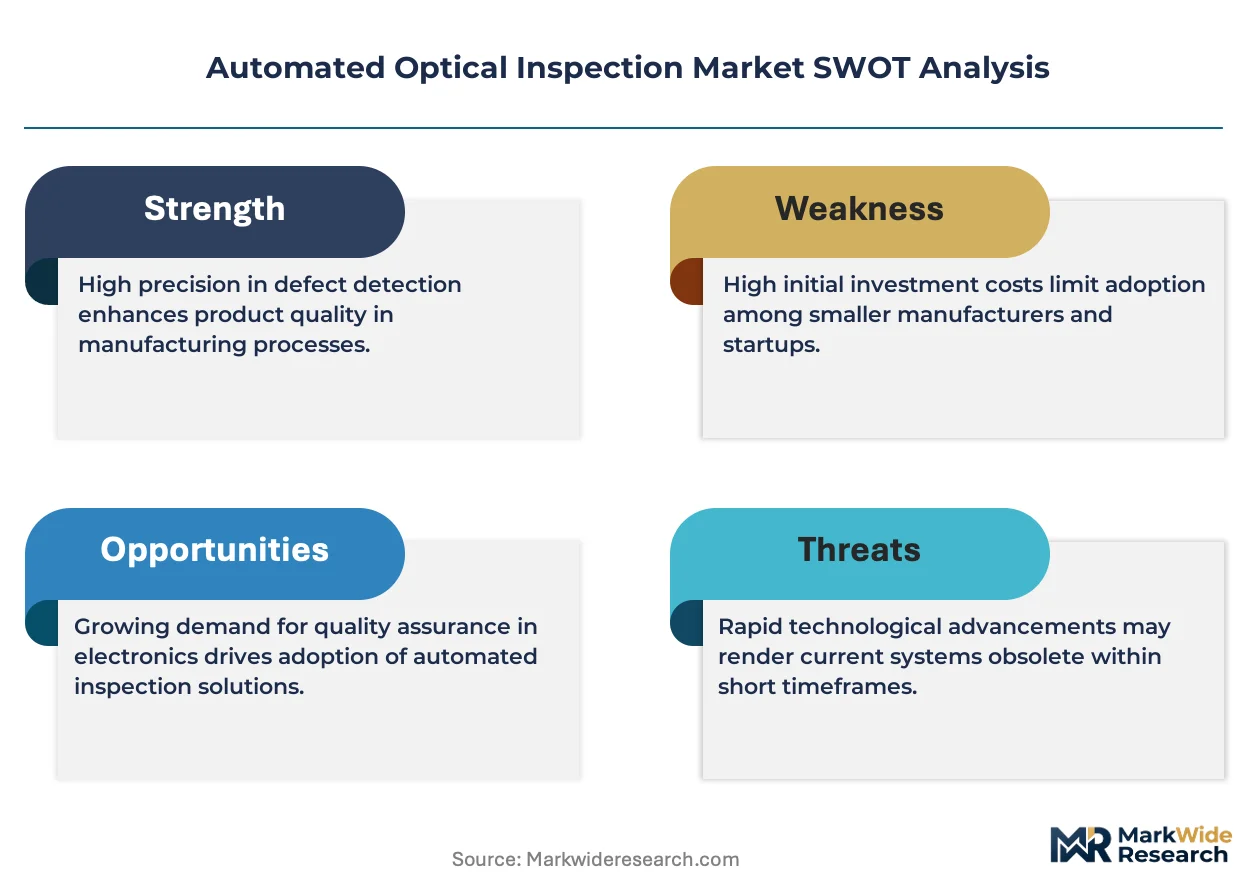
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases accelerate adoption of lead-free and low-temperature solder chemistries that demand more sensitive optical verification protocols.
- Stacked die architectures:Three-dimensional packaging in advanced semiconductors multiplies inspection points per unit area, expanding equipment utilization rates in foundry and OSAT facilities.
- Shenzhen-Suzhou manufacturing corridor:Dense clustering of contract electronics manufacturers in these Chinese cities concentrates demand for high-throughput 3D solder paste inspection systems.
Market Restraints
- Deep ultraviolet optics supply:German and Japanese suppliers dominate excimer laser and DUV objective lens production, creating single-source vulnerability for inspection tool builders.
- Algorithmic opacity:EU AI Act transparency requirements impose documentation burdens on machine-learning defect classification modules that increase validation costs.
- X-ray inspection substitution:Computed tomography systems penetrate hidden solder joints in complex assemblies, capturing applications that optical methods cannot access.
Strategic Opportunities
- Medical device validation:FDA quality system regulations mandate validated inspection protocols that elevate AOI from efficiency tool to compliance necessity in US manufacturing.
- CSRD disclosure alignment:European sustainability reporting rules reward capital allocation toward inspection equipment that demonstrably reduces material waste and scrap rates.
- Embedded machine vision convergence:Direct integration of inspection modules into SMT line controllers eliminates separate handling stages and reduces floor space requirements.
Industry Challenges
- Multi-physics calibration expertise:Simultaneous optimization of optical, thermal, and mechanical subsystems requires scarce cross-disciplinary engineering talent.
- Legacy SMT line retrofit:Integration of 3D inspection stations with existing 2D-dominant production flows demands custom mechanical interfaces and software bridges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Optical Inspection Market |
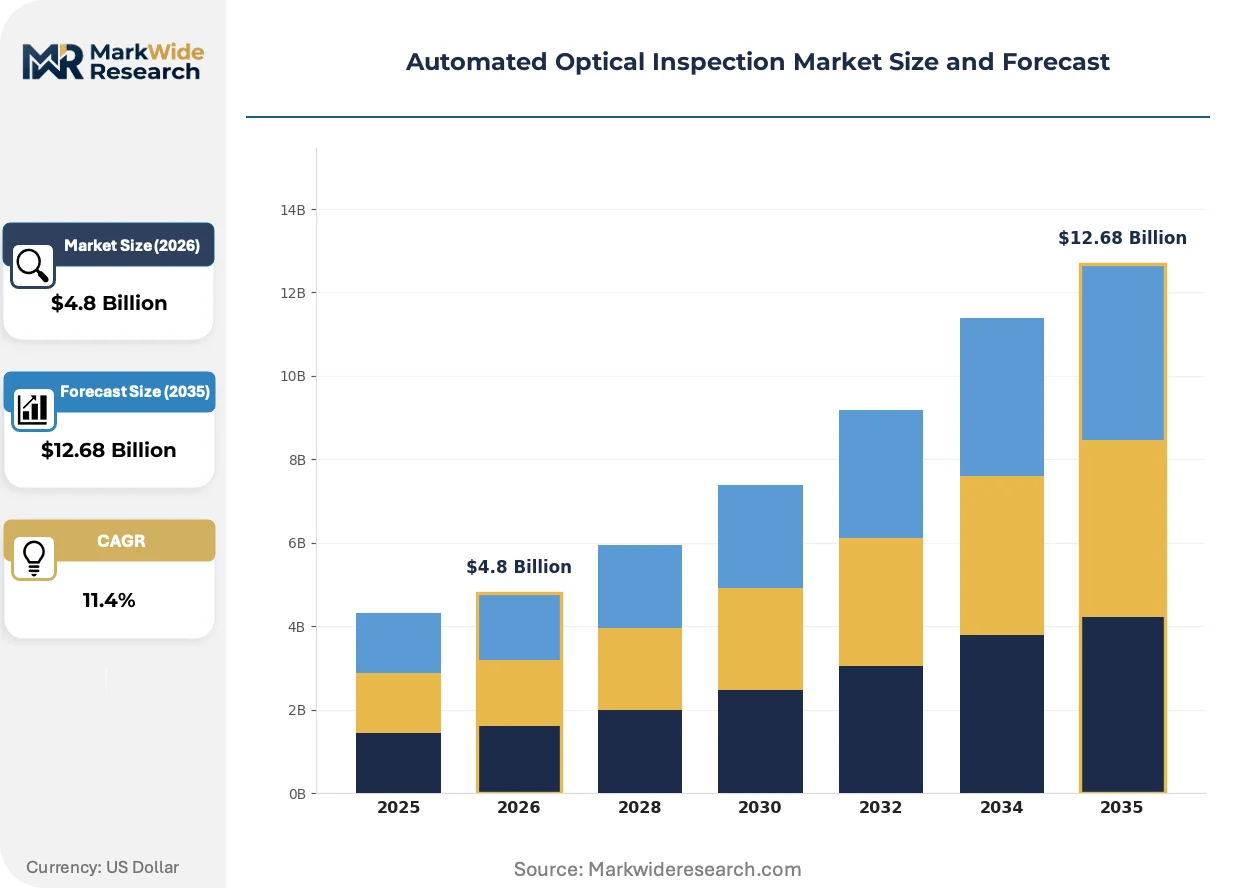
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 2D Inspection, 3D Inspection, Machine Vision, X-Ray Inspection Application: Semiconductors, PCBs, Solar Panels, Automotive Components End User: Electronics Manufacturers, Automotive OEMs, Aerospace Manufacturers, Medical Device Producers Solution: Hardware, Software, Integrated Systems, Inspection Services |
| Companies Covered | Camtek Ltd., Saki Corporation, Koh Young Technology Inc., KLA Corporation, Nordson YESTECH, Test Research, Inc. (TRI), Viscom AG, CyberOptics Corporation, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Optical Inspection Market Emerging Trajectories
Computational imaging architectures are compressing the trade-off between throughput and resolution, enabling single-pass inspection of features that previously required multiple scan modes. This technical trajectory redefines competitive differentiation away from hardware specifications toward software-defined adaptability.
Structured-light projection metrology is converging with phase-shifting interferometry in next-generation 3D AOI platforms. Semiconductor packaging houses in Taiwan and South Korea are deploying these hybrid systems for micro-bump coplanarity measurement. The convergence is collapsing the historical separation between wafer-level and board-level inspection methodologies, permitting unified qualification protocols across the packaging hierarchy.
REACH substance restrictions and RoHS thresholds continue reshaping solder alloy compositions across European electronics facilities. Altered surface reflectivity and joint geometry from tin-silver-copper formulations force optical systems to recalibrate illumination angles and spectral bands. Medical device producers in Germany and the Netherlands face the steepest compliance timelines as MDR quality system audits intensify scrutiny of inspection validation documentation.
Consolidated procurement by tier-one EMS providers is compressing vendor qualification cycles and unbundling after-sales service contracts. Foxconn and Jabil are negotiating direct software subscription models that decouple algorithm updates from hardware replacement schedules. This purchasing transformation is most advanced in East Asian contract manufacturing, where capital efficiency metrics dominate equipment selection criteria.
Automated Optical Inspection Market Segmentation
Technology choices in automated optical inspection determine capital intensity, throughput ceilings, and integration complexity across production lines. Application specificity drives resolution requirements and regulatory validation burdens. End-user verticals impose distinct procurement rhythms and qualification protocols.
Technology:
Standalone inspection stations dominate high-mix electronics environments where line reconfiguration flexibility matters, while embedded modules penetrate high-volume automotive and consumer electronics lines seeking footprint reduction.
- 2D Inspection:Conventional camera-based systems capture planar images using visible or near-infrared illumination at throughput rates exceeding 150 cm² per second. Mature PCB assembly lines in Shenzhen and Suzhou deploy these systems for cost-sensitive consumer electronics where defect tolerances remain above 50 microns.
- 3D Inspection:Structured-light and laser triangulation architectures measure height, coplanarity, and volumetric solder deposits. Taiwan and South Korea semiconductor packaging houses drive demand as micro-bump arrays proliferate in advanced chiplet designs.
- Machine Vision:Embedded camera modules integrated directly into pick-and-place or reflow equipment eliminate separate handling stages.
- X-Ray Inspection:Computed tomography penetrates hidden joints in ball grid arrays and stacked die configurations inaccessible to optical methods.
2D inspection leads volumes today; 3D inspection is gaining share fastest.
Application:
Margin concentration varies sharply by application, with semiconductor and medical device segments commanding premium pricing against commoditized PCB inspection.
- Semiconductors:Wafer-level and advanced packaging inspection demands sub-micron resolution and die-level defect classification. Taiwan foundries and South Korea memory manufacturers concentrate procurement of deep ultraviolet and electron-beam hybrid systems.
- PCBs:Board-level assembly inspection spans consumer electronics, telecommunications infrastructure, and industrial controls. Chinese contract manufacturers in the Pearl River Delta dominate equipment utilization rates.
- Solar Panels:Cell and module inspection targets micro-crack detection and metallization continuity.
- Automotive Components:Battery management systems and power electronics drive demand for high-reliability solder joint verification under AEC-Q100 stress qualification.
PCB applications anchor current installed base; semiconductor packaging shows the steepest expansion trajectory.
End User:
Procurement authority sits differently across verticals—centralized engineering groups in automotive versus distributed plant managers in electronics contract manufacturing.
- Electronics Manufacturers:Foxconn, Jabil, and Pegatron negotiate enterprise software subscriptions decoupled from hardware replacement cycles. Their consolidated procurement compresses vendor qualification timelines and unbundles service contracts.
- Automotive OEMs:Tier-one suppliers and integrated manufacturers mandate traceability systems linking individual inspection records to vehicle identification numbers. NHTSA defect reporting requirements elevate documentation standards.
- Aerospace Manufacturers:AS9100 quality system audits impose stringent validation protocols on inspection algorithm changes.
- Medical Device Producers:FDA 21 CFR Part 820 quality system regulations mandate validated inspection protocols with documented algorithm version control.
Electronics manufacturers represent the largest addressable population; medical device producers show the fastest compliance-driven upgrade cycle.
Solution:
Delivery models are fragmenting as subscription-based software and inspection-as-a-service alternatives challenge traditional capital equipment sales.
- Hardware:Optical benches, illumination subsystems, and motion stages constitute the capital-intensive foundation. German and Japanese suppliers dominate deep ultraviolet objective lens and excimer laser sources, creating single-source vulnerability.
- Software:Defect classification algorithms, machine learning model training environments, and production data analytics platforms. EU AI Act transparency requirements impose documentation burdens on neural network-based classification modules.
- Integrated Systems:Turnkey inspection stations combining mechanical, optical, and computational subsystems from single vendors.
- Inspection Services:Third-party providers operate equipment at customer facilities or centralized labs, converting capital expenditure to operating expenditure.
Integrated systems dominate current revenue; software subscriptions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Suzhou anchor procurement intensity for automated optical inspection systems, with contract electronics manufacturers in these Chinese cities operating the densest clusters of high-throughput 3D solder paste inspection lines worldwide.
China
Foxconn and Pegatron drive equipment utilization rates through consolidated procurement of embedded machine vision modules. MIIT industrial upgrading guidelines prioritize smart manufacturing investments that accelerate AOI deployment across PCB assembly lines. The Pearl River Delta manufacturing corridor concentrates demand for cost-sensitive 2D inspection systems serving consumer electronics exports.
United States
Medical device producers in Minnesota and Massachusetts mandate validated inspection protocols under FDA 21 CFR Part 820 quality system regulations. NHTSA traceability requirements for automotive electronics elevate documentation standards for solder joint verification. The Austin-San Antonio tech corridor hosts expanding semiconductor packaging facilities requiring sub-micron defect detection capabilities.
Germany
Automotive tier-one suppliers in Bavaria and Baden-Württemberg specify AEC-Q100 qualified inspection systems for battery management electronics. REACH restrictions on lead-based solders force optical recalibration for altered surface reflectivity from tin-silver-copper formulations. The Stuttgart industrial region concentrates procurement of hybrid 3D AOI platforms for power electronics manufacturing.
South Korea
Samsung and SK Hynix memory manufacturers drive demand for deep ultraviolet inspection architectures in advanced packaging applications. MFDS medical device quality audits intensify scrutiny of algorithm validation documentation for Seoul-area producers. The Suwon-Pyeongtaek semiconductor corridor deploys structured-light metrology for micro-bump coplanarity measurement in chiplet designs.
Japan
METI semiconductor revitalization policies channel investment toward domestic packaging house expansion in Kyushu and Tohoku. JIS standards for automotive electronics harmonize inspection protocols across Toyota and Honda supplier networks. The Nagoya manufacturing belt integrates embedded vision modules directly into SMT line controllers for footprint reduction.
Automated Optical Inspection Market Vendor Landscape
Global majors compete with regional champions across technology licensing and embedded integration capabilities. The vendor base organizes into three tiers: diversified industrial conglomerates with machine vision divisions, pure-play inspection specialists, and SMT equipment integrators. Strategic differentiation centers on deep ultraviolet optics sourcing security and algorithm transparency compliance under emerging regulatory frameworks. Competitive moves concentrate on strategic partnerships for DUV supply chain access and geographic expansion through localized software subscription models.
Among Asia-Pacific-based specialists, Koh Young Technology Inc. and Saki Corporation exemplify the pure-play archetype focused on solder paste inspection dominance. KLA Corporation anchors the diversified technology tier with wafer-level inspection heritage. These three entities occupy distinct competitive positions: the Korean specialist in 3D SPI market share, the Japanese precision equipment maker in automotive qualification protocols, and the US conglomerate in semiconductor front-end resolution requirements.
| Leading Market Players |
|---|
| Camtek Ltd. |
| Saki Corporation |
| Koh Young Technology Inc. |
| KLA Corporation |
| Nordson YESTECH |
| Test Research, Inc. (TRI) |
| Viscom AG |
| CyberOptics Corporation |
| Omron Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between FDA-validated medical systems and commodity PCB inspection equipment manifests in divergent pricing architectures and supply chain sourcing strategies. Premium tiers command three-to-five multiples over standard equipment due to algorithm documentation burdens and DUV optics security, while economy segments compete on throughput-per-dollar metrics that favor Chinese illumination subsystem suppliers.
Pricing Analysis
Deep ultraviolet optics and excimer laser source costs pass through directly to equipment pricing, with German and Japanese suppliers extracting margin premiums that inflate capital outlays for semiconductor-grade systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical protocols from automotive AEC-Q100 tiers and cost-sensitive consumer electronics configurations. Pricing pressure stems from Foxconn and Jabil consolidating procurement into software subscription models that decouple algorithm updates from hardware replacement cycles. Contract electronics manufacturers in Shenzhen exhibit the highest price sensitivity, while medical device producers in Minnesota and Massachusetts absorb premiums for validated inspection protocols.
Supply Chain Analysis
Dual-sourcing requirements for deep ultraviolet objective lenses mandate simultaneous qualification of German and Japanese suppliers, though true alternatives remain limited for excimer laser architectures. Optical bench manufacturing concentrates in Germany, Japan, and China, with precision motion stages drawing from Taiwanese and South Korean machine tool specialists. Supply chain risk centers on single-source vulnerability for DUV optics where Zeiss and Nikon dominate design iterations, constraining inspection tool builders' negotiation leverage. Distribution runs through direct enterprise sales for tier-one EMS providers and regional system integrators serving mid-market PCB assembly houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EU AI Act compliance costs in European facilities and MIIT smart manufacturing subsidies in Chinese contract manufacturing, creating divergent effective equipment costs for identical hardware specifications.
For Market Incumbents: Anticipate algorithmic transparency requirements under EU AI Act documentation burdens that will elevate validation costs for machine-learning defect classification modules. Secure captive supply agreements for deep ultraviolet optics through backward integration into German or Japanese lens suppliers before qualification cycles lengthen. Prioritize embedded machine vision convergence that eliminates separate handling stages and locks in SMT line controller partnerships. For New Entrants and Emerging Players: The price-point gap between premium semiconductor-grade systems and economy PCB inspection equipment creates white-space opportunity for mid-tier hybrid platforms serving automotive power electronics. Target battery management system manufacturers in Bavaria and Baden-Württemberg seeking AEC-Q100 qualified systems without wafer-level resolution premiums. Deploy inspection-as-a-service models that convert capital expenditure to operating expenditure for mid-market EMS providers. For Investors and Strategic Acquirers: Consolidation pressure builds where pure-play 3D solder paste inspection specialists lack DUV optics sourcing security and face margin compression from software unbundling trends. Position acquisition targets around embedded machine vision module developers with SMT line controller integration capabilities and existing automotive qualification protocols. Watch for inflection where EU F-Gas Regulation enforcement accelerates lead-free solder chemistry transitions that demand optical recalibration and equipment refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Deep Ultraviolet Optics Supply Security | Captive sourcing from German and Japanese lens suppliers insulates against single-source vulnerability in semiconductor-grade inspection. |
| Embedded Machine Vision Convergence | Direct integration into Omron and Siemens SMT line controllers eliminates handling stages and reduces floor space requirements. |
| FDA Validation Protocol Investment | Medical device producers in Minnesota and Massachusetts mandate documented algorithm version control under 21 CFR Part 820. |
| Software Subscription Decoupling | Foxconn and Jabil negotiate enterprise models that separate algorithm updates from hardware replacement schedules. |
| EU AI Act Transparency Compliance | Documentation burdens on neural network classification modules increase validation costs for European electronics facilities. |
Methodological Framework
Direct dialogue with SMT equipment procurement managers, semiconductor packaging engineers, FDA quality system auditors, and automotive tier-one supplier technical directors grounded qualitative insights across the primary research phase. Secondary validation drew from SEC 10-K equipment disclosures, MIIT industrial upgrading guidelines, ECHA REACH substance restriction updates, and FDA 483 inspection observation databases. Bottom-up and top-down triangulation cross-referenced vendor shipment data against end-user capital expenditure surveys.
Bottom-up modeling segmented the addressable market across 2D inspection, 3D inspection, machine vision, and X-ray architectures, with further disaggregation by semiconductor, PCB, automotive component, and medical device applications. Top-down constraints applied macroeconomic sensitivities to electronics capital expenditure cycles and foundry equipment spending patterns across the projection horizon. CAGRs derived from regression against historical equipment replacement intervals and regulatory compliance-driven upgrade cycles.
Caveats apply where EU AI Act implementation timelines or DUV optics supply disruptions could materially shift the outlook. Deviation in REACH substance restriction enforcement or MIIT smart manufacturing subsidy allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Sound Level Measurement Meter Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Compression Testing Machines Market
Test and Measurement
Shock Test Machines Market
Test and Measurement
Bend Testing Machine Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Circuit Breaker Test Devices Market
Test and Measurement
Melt Flow Tester Market
Test and Measurement
Over-The-Air (OTA) Testing Market
Test and Measurement
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market
Test and Measurement
Radiography Test Equipment Market
Test and Measurement
ESG Sensor Data Quality and Validation Test Platforms Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Flow Meter Market