
 Semiconductor Curve Tracer Market | 2026-2036
Semiconductor Curve Tracer Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Curve Tracer Market Analytics
The gap between legacy analog characterization and precision digital measurement is narrowing as node geometries shrink below 7nm. Tektronix leverages its oscilloscope heritage to anchor premium benchtop tracer portfolios for R&D labs. Keysight Technologies sustains leadership through integrated parametric test systems that span wafer-level to packaged-device workflows. Barth Electronics specializes in pulsed-IV solutions for power semiconductor qualification, occupying a defensible niche in high-voltage verification.
A semiconductor curve tracer is an electronic test instrument that applies swept voltage or current to a device under test while recording the corresponding current-voltage response, typically resolving microamp-level leakage through kilovolt breakdown regimes. Its primary commercial purpose is to extract parametric fingerprints—threshold voltage, on-resistance, transconductance—for process control and reliability screening. Automated Test Equipment commands the largest revenue pool due to throughput requirements in high-volume foundries, while Handheld Tracers represent the fastest-expanding category as field-service teams adopt portable diagnostics for power-module maintenance. Digital Tracers are displacing analog architectures in new capital expenditure, driven by software-defined measurement flexibility and tighter integration with statistical process control databases.
FCC equipment authorization rules govern electromagnetic emissions for tracer instruments sold into US-based fabs, while REACH chemical restrictions in Europe constrain lead-based solder and certain flame retardants in instrument assemblies. China's GB standards for electronic measurement equipment, administered by SAMR, mandate localized calibration protocols that shape import competitiveness. Stakeholders must monitor how dual carbon goals across East Asian manufacturing jurisdictions reshape energy-efficiency requirements for test-floor equipment.
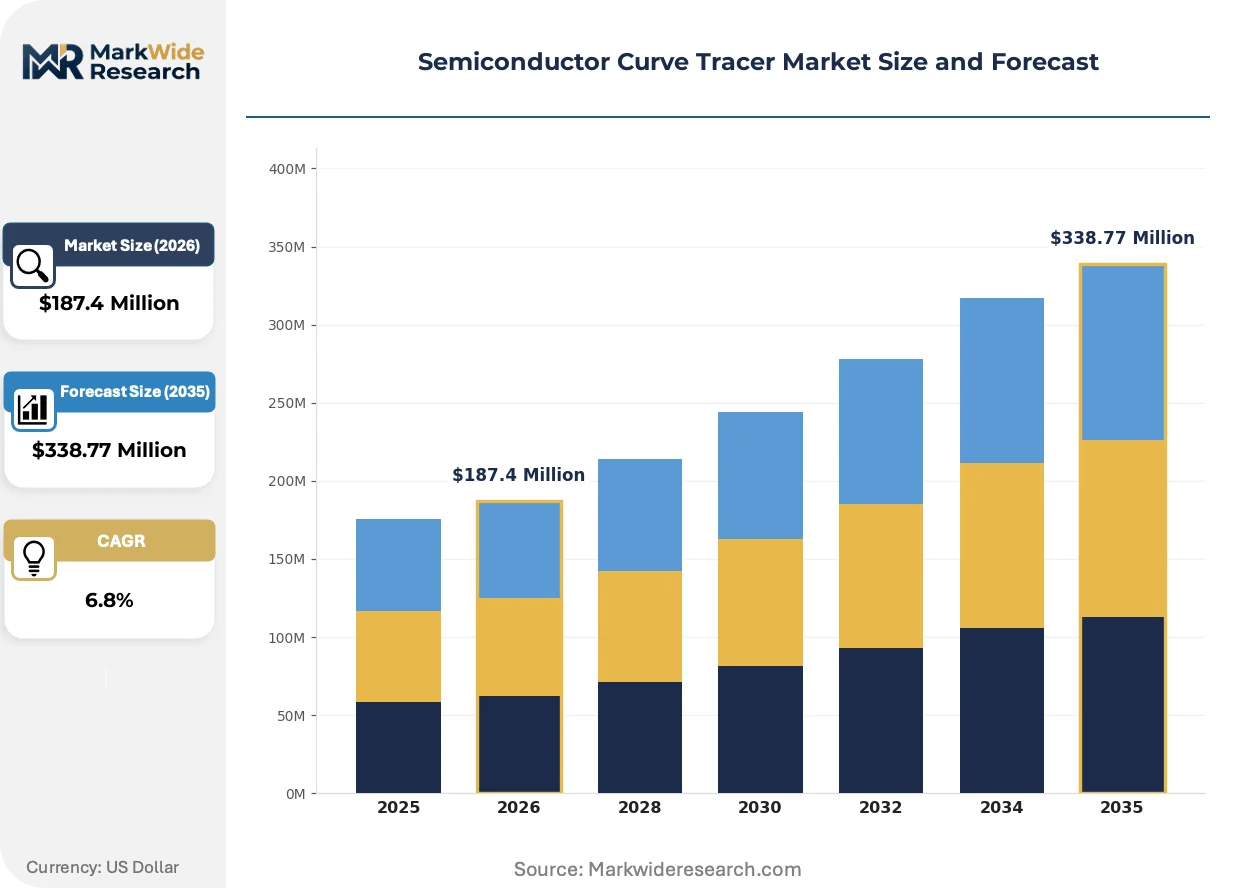
Market Dynamics
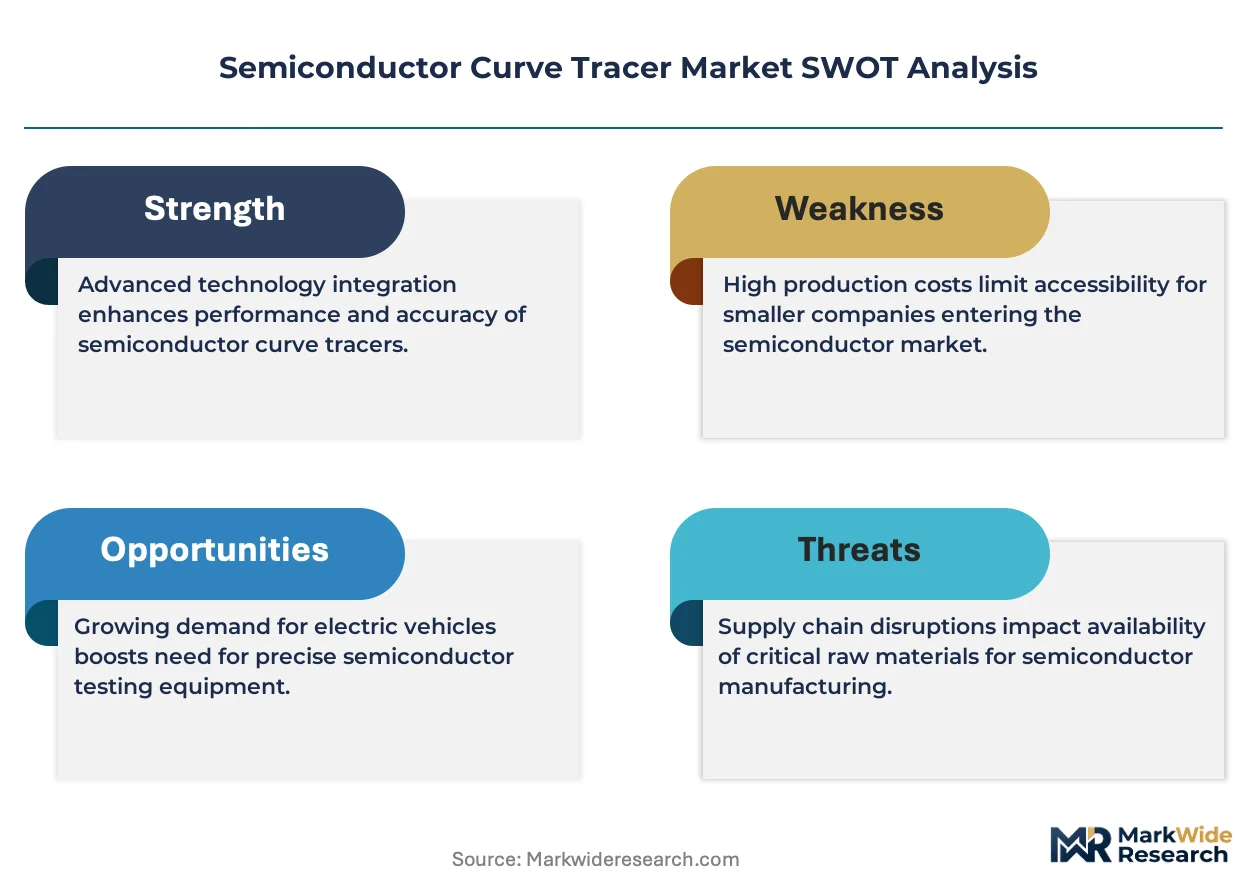
The transition to wide-bandgap semiconductors—silicon carbide and gallium nitride—is fundamentally altering parametric test requirements. Device characterization now demands higher voltage sweeps, faster pulse widths, and thermal coupling capabilities that legacy analog tracers cannot deliver. Foundries in Taiwan, South Korea, and Germany are driving capital redeployment toward software-defined measurement platforms.
Growth Catalysts
- Silicon Carbide Adoption:Electric vehicle powertrains and renewable energy inverters require precise characterization of high-voltage, high-temperature devices. Automotive qualification labs in Germany and Japan are expanding tracer procurement for SiC MOSFET validation.
- REACH Chemical Compliance:European restrictions on lead-based solder and halogenated flame retardants are accelerating replacement cycles for aging benchtop equipment. Instrument vendors must redesign chassis and probe assemblies to maintain CE marking access.
- East Asian Fab Concentration:Taiwan and South Korea collectively host the majority of advanced logic and memory capacity. Local procurement by TSMC, Samsung, and SK Hynix concentrates demand for automated wafer-level parametric test systems.
Market Restraints
- Specialized Component Supply:Precision ADCs and high-voltage isolation amplifiers rely on concentrated semiconductor foundry capacity. Disruptions at TSMC or GlobalFoundries directly constrain tracer production timelines.
- Capital Intensity Barrier:Fully automated parametric test cells require seven-figure capital commitments. Mid-tier foundries in Malaysia and Vietnam face financing constraints that limit adoption of integrated tracer-prober systems.
- Technical Talent Scarcity:Operation of pulsed-IV systems for wide-bandgap device characterization demands expertise in thermal management and measurement artifact suppression. Universities in the US and Europe produce insufficient graduates with this hybrid skill set.
Strategic Opportunities
- India Semiconductor Mission:The country's PLI scheme for fabs and assembly-test-mark-pack facilities creates first-mover positioning for tracer vendors. Gujarat and Tamil Nadu greenfield sites require complete metrology infrastructure buildouts.
- Cloud-Native Data Pipelines:Integration of curve tracer outputs with statistical process control databases enables predictive yield management. Foundries in Taiwan are piloting API-connected measurement architectures that bypass traditional file-based data transfer.
- Field Service Diagnostics:Wind turbine and railway traction system operators in Germany and China require portable IV characterization for power module health monitoring. Handheld tracer adoption is accelerating in these heavy-industry maintenance workflows.
Industry Challenges
- Calibration Protocol Divergence:China's SAMR mandates localized metrological traceability for electronic measurement equipment. Foreign vendors must establish in-country calibration laboratories or cede public-sector procurement eligibility to domestic competitors.
- Legacy System Integration:Decades-old analog tracers persist in university research labs and small-scale fabrication facilities. Software-defined replacements must replicate obsolete GPIB command sets to avoid disrupting established test scripts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Curve Tracer Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Tracers, Digital Tracers, Automated Test Equipment, Handheld Tracers End User: Research Laboratories, Semiconductor Manufacturers, Educational Institutions, Testing Facilities Technology: Current Supply Measurement, Voltage Supply Measurement, Advanced Analysis Software, Multi-Channel Configuration Application: Device Characterization, Parametric Testing, Quality Assurance, R&D |
| Companies Covered | Barth Electronics, Teradyne, Tektronix, FormFactor, LTX-Credence Corporation, Scientific Test, Keysight Technologies, Xcerra Corporation, Koyo Electronics Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Curve Tracer Market Evolving Landscape
Measurement architectures are converging around software-defined instrumentation that decouples hardware acquisition from analysis algorithms. This shift enables remote diagnostics, cloud-based correlation analytics, and rapid reconfiguration for emerging device technologies without hardware replacement.
Wide-bandgap semiconductor characterization is migrating from static DC measurement to nanosecond-scale pulsed-IV techniques. Power device manufacturers in Germany and Japan require sub-microsecond pulse widths to suppress self-heating artifacts in SiC and GaN devices. Tektronix and Keysight are advancing source-measure unit architectures that integrate arbitrary waveform generation with real-time thermal compensation algorithms.
REACH and RoHS compliance deadlines in Europe are mandating redesign of instrument assemblies by 2026. Vendors must eliminate hexavalent chromium platings and transition to lead-free solder alloys that withstand thermal cycling in 24/7 production environments. German automotive qualification labs are prioritizing suppliers with certified sustainable supply chains for their capital equipment procurement.
After-sales service models are fragmenting as foundries unbundle maintenance contracts from initial equipment purchases. Taiwanese memory manufacturers now negotiate separate agreements for probe card refurbishment, software subscription renewals, and on-site calibration services. This unbundling compresses vendor margins while creating openings for specialized third-party service providers in Taichung and Hsinchu science parks.
Semiconductor Curve Tracer Market Segmentation
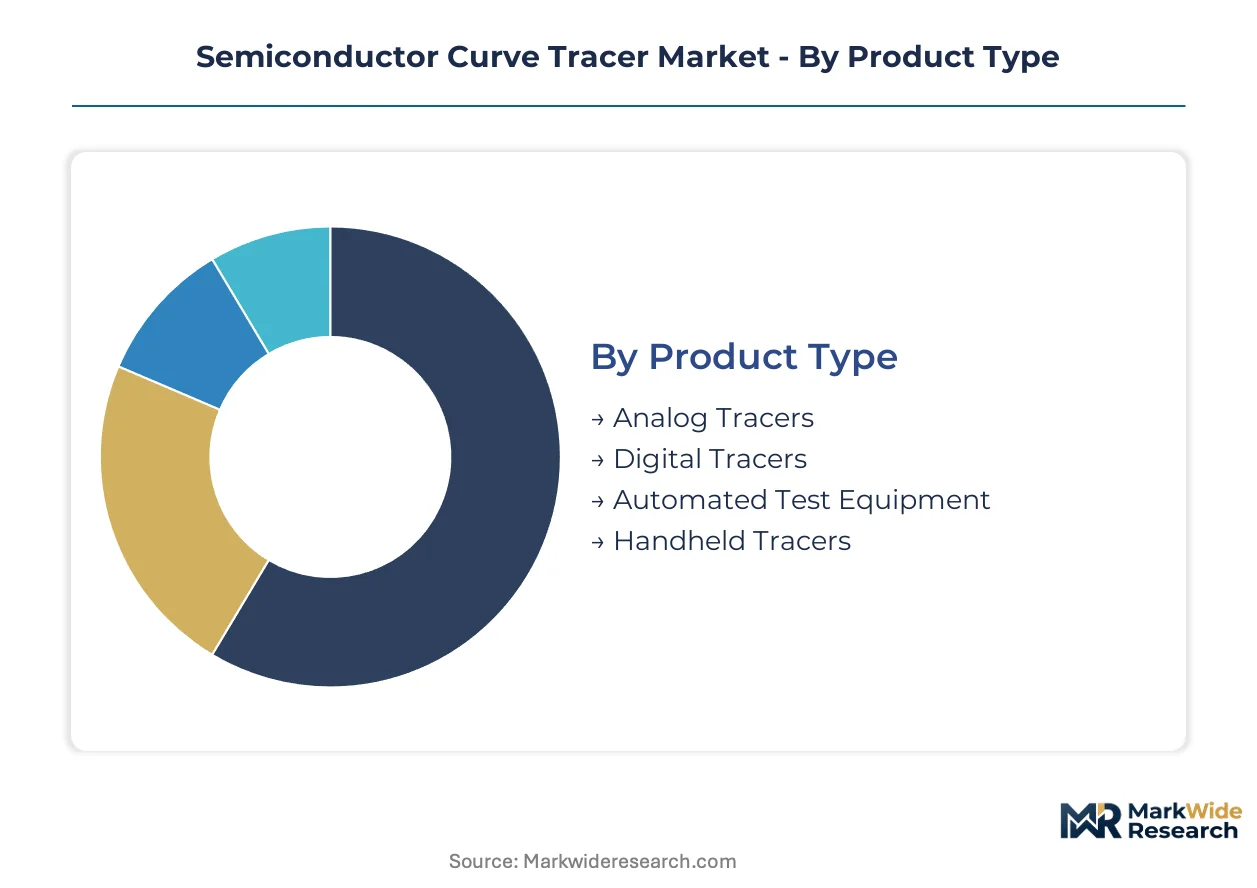
Segmentation of the semiconductor curve tracer market reveals divergent service intensity requirements across product tiers. After-sales calibration contracts and probe refurbishment cycles vary dramatically between automated production systems and portable field units.
Product Type:
After-sales-service intensity escalates from benchtop units to fully automated wafer-level systems, with annual maintenance contracts consuming 12-18% of initial capital outlay for high-throughput equipment.
- Automated Test Equipment:Integrated parametric test cells combine precision source-measure units with robotic wafer handling for 24/7 foundry operations. TSMC and Samsung fabs in Taiwan and South Korea anchor procurement for these seven-figure systems, driven by throughput requirements for advanced node validation.
- Digital Tracers:Software-defined architectures decouple hardware acquisition from analysis algorithms, enabling remote diagnostics and cloud-based correlation analytics. German automotive qualification labs and Japanese power device manufacturers are migrating capital expenditure from analog legacy systems to these programmable platforms.
- Analog Tracers:Legacy architectures persist in university research settings where established GPIB command scripts resist disruption.
- Handheld Tracers:Portable IV characterization tools serve wind turbine and railway traction maintenance crews in Germany and China.
By volume, Automated Test Equipment leads. By growth pace, Handheld Tracers are climbing the fastest.
End User:
Customer procurement authority concentrates in semiconductor manufacturers with dedicated metrology engineering teams, while educational institutions prioritize capital cost over measurement precision.
- Semiconductor Manufacturers:Foundries and IDMs operate integrated parametric test cells for process control and reliability screening. East Asian fabrication clusters in Taiwan, South Korea, and Japan command the dominant share of capital deployment for wafer-level characterization systems.
- Research Laboratories:R&D facilities at Fraunhofer Institute in Germany and IMEC in Belgium require premium benchtop tracers with arbitrary waveform generation for emerging device physics investigation.
- Testing Facilities:Third-party qualification labs serve fabless designers without in-house parametric test capacity.
- Educational Institutions:Universities prioritize entry-level analog units for undergraduate instruction in microelectronics curricula.
By revenue concentration, Semiconductor Manufacturers dominate. By expansion trajectory, Testing Facilities are gaining share fastest as outsourcing of qualification grows.
Technology:
Technology selection determines measurement fidelity boundaries, with advanced software layers commanding premium pricing multiples over hardware-only configurations.
- Advanced Analysis Software:Algorithmic layers extract parametric fingerprints from raw IV data and integrate with statistical process control databases. Foundries in Taiwan are piloting API-connected architectures that bypass traditional file-based transfer for predictive yield management.
- Multi-Channel Configuration:Parallel test heads accelerate throughput for memory array characterization. SK Hynix and Micron facilities deploy these architectures for high-volume DRAM and NAND validation.
- Current Supply Measurement:Precision sourcing resolves microamp-level leakage regimes for low-power IoT device qualification.
- Voltage Supply Measurement:High-voltage sweeps address silicon carbide and gallium nitride breakdown characterization requirements.
By installed base, Voltage Supply Measurement leads. By technology refresh rate, Advanced Analysis Software is expanding most quickly.
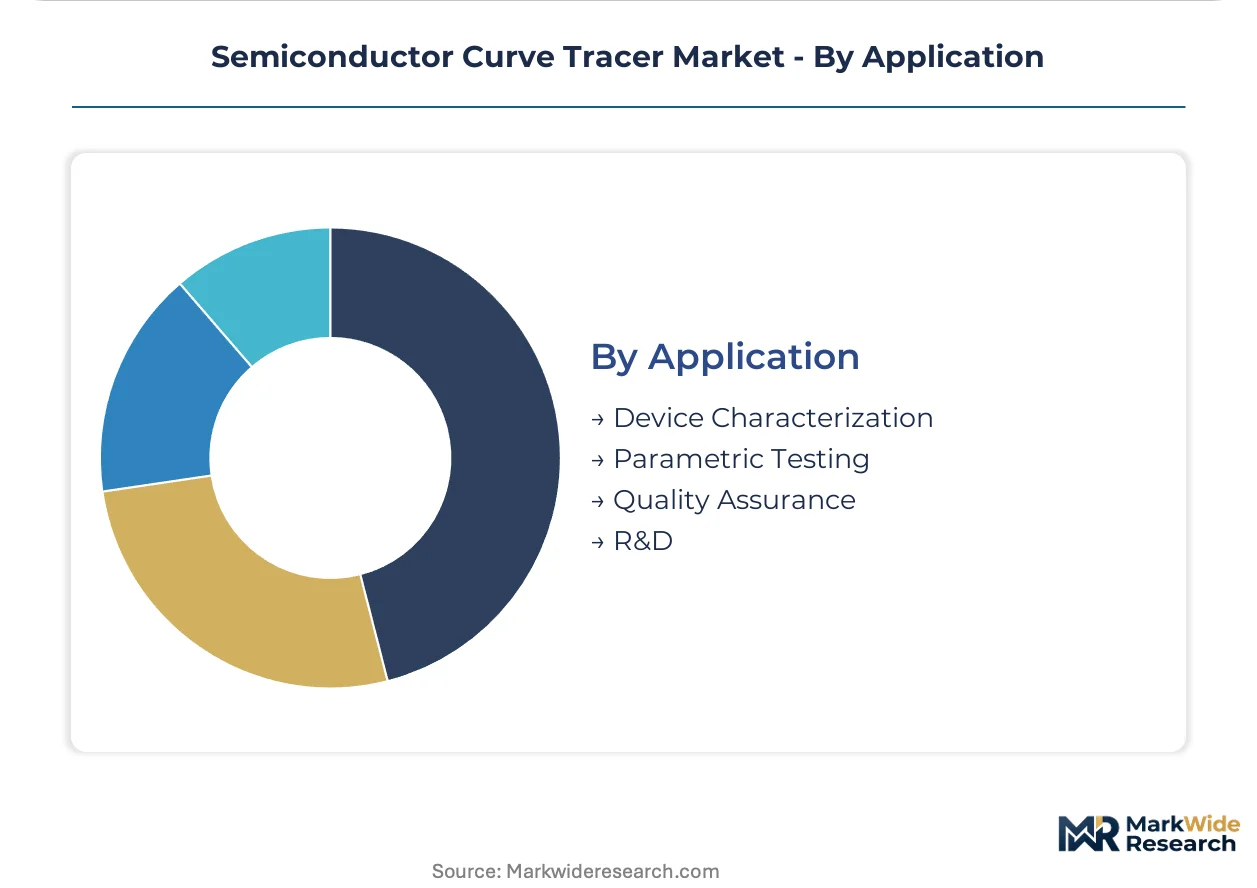
Application:
Application focus shifts measurement specification priorities, with production screening demanding speed where research prioritizes flexibility.
- Parametric Testing:Production-line extraction of threshold voltage, on-resistance, and transconductance fingerprints for process control. Automotive qualification labs in Germany and Japan are expanding procurement for silicon carbide MOSFET parametric validation.
- R&D:exploratory device physics investigation requires programmable stimulus patterns and thermal coupling capabilities. Barth Electronics pulsed-IV solutions serve this niche for wide-bandgap semiconductor development.
- Device Characterization:Comprehensive IV curve mapping for datasheet generation and model extraction.
- Quality Assurance:Incoming inspection and outgoing screening for reliability-critical applications.
By capital deployment, Parametric Testing leads. By growth momentum, R&D is accelerating fastest with wide-bandgap material transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive qualification labs export SiC validation services to Japanese power device manufacturers, creating a trans-Eurasian trade corridor in high-voltage characterization expertise.
Taiwan
TSMC's advanced node expansion drives wafer-level parametric test procurement for sub-7nm process control. SAMR calibration mandates shape import competitiveness for foreign tracer vendors. Hsinchu Science Park hosts concentrated automated test equipment deployment for memory and logic foundry operations.
Germany
Automotive OEM qualification labs demand pulsed-IV systems for SiC MOSFET validation in EV powertrains. REACH chemical restrictions accelerate replacement cycles for aging benchtop equipment. Dresden and Munich clusters anchor power semiconductor R&D with integrated metrology infrastructure.
United States
FCC equipment authorization governs electromagnetic emissions for tracer instruments sold into domestic fabs. Precision ADC supply constraints at concentrated foundry capacity directly constrain production timelines. Silicon Valley and Austin fabrication facilities drive software-defined measurement platform adoption.
South Korea
Samsung and SK Hynix procurement concentrates demand for multi-channel parametric test architectures. Dual carbon goals reshape energy-efficiency requirements for test-floor equipment. Pyeongtaek and Yongin memory fabrication complexes deploy automated wafer-level characterization systems.
Japan
Power device manufacturers require sub-microsecond pulse widths for GaN characterization. METI industrial policy supports domestic test equipment supply chain resilience. Yokohama and Kyoto R&D centers advance thermal compensation algorithms for wide-bandgap device validation.
Semiconductor Curve Tracer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The market structure consolidates around integrated parametric test system vendors with foundry-direct relationships, while niche specialists occupy defensible positions in pulsed-IV and high-voltage verification. Strategic archetypes span full-stack platform providers, component-specialist instrument makers, and regional service-integrated distributors. Dominant competitive moves include geographic expansion into East Asian fabrication clusters and portfolio diversification toward software-defined measurement architectures.
Within the precision instrumentation tier, Tektronix and Keysight Technologies exemplify platform-scale competitors with oscilloscope heritage and integrated parametric test system portfolios respectively. Barth Electronics occupies a specialist position in pulsed-IV solutions for power semiconductor qualification.
| Leading Market Players |
|---|
| Barth Electronics |
| Teradyne |
| Tektronix |
| FormFactor |
| LTX-Credence Corporation |
| Scientific Test |
| Keysight Technologies |
| Xcerra Corporation |
| Koyo Electronics Industries |
| Others |
Value Network & Pricing Analysis
Undercapacity in precision ADC and high-voltage isolation amplifier foundries tightens component availability, pushing instrument vendors toward long-term offtake commitments and compressing margins on mid-tier benchtop systems.
Pricing Analysis
Current-generation software-defined tracers command substantial premiums over prior-generation analog architectures, while next-generation pulsed-IV platforms with thermal compensation algorithms sit at the apex of the pricing hierarchy. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from foundry-direct procurement concentration in Taiwan and South Korea, where volume scale negotiations compress vendor margins. Educational institutions exhibit highest price sensitivity, prioritizing capital cost over measurement precision, whereas automotive qualification labs demonstrate lowest sensitivity due to reliability-critical application requirements.
Supply Chain Analysis
Contract manufacturing for tracer instrument assemblies concentrates with Foxconn and Jabil in Taiwan and Mexico, supplemented by specialized EMS providers in Malaysia for probe card fabrication. Precision ADCs draw from TSMC and GlobalFoundries capacity in Taiwan and the USA, while high-voltage isolation amplifiers source from Renesas and Texas Instruments facilities in Japan and the USA. Single-source vulnerability in advanced node semiconductor components poses structural risk, particularly for pulsed-IV source-measure units. Distribution runs through direct foundry sales teams for automated test equipment, with regional distributors serving research laboratory and educational segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through foundry procurement consolidation, with TSMC, Samsung, and SK Hynix commanding disproportionate leverage in seven-figure parametric test system negotiations.
For Market Incumbents: Entrench foundry-direct relationships in Hsinchu and Pyeongtaek through co-development agreements for next-node characterization requirements. Deepen backward integration into precision probe card manufacturing to defend margin position against unbundled service competitors. The threat of cloud-native measurement platforms displacing traditional hardware architectures demands accelerated software subscription revenue streams. For New Entrants and Emerging Players: Portable diagnostics for wind turbine and railway traction maintenance in Germany and China represent the most penetrable entry point, with handheld tracer demand outpacing automated equipment growth. India's Gujarat and Tamil Nadu greenfield fab sites require complete metrology infrastructure buildouts, creating first-mover positioning for vendors with localized calibration capabilities. A service-integrated go-to-market approach bundling hardware with predictive maintenance analytics penetrates price-sensitive mid-tier foundries in Vietnam and Malaysia. For Investors and Strategic Acquirers: Long-term, this sits as a semiconductor capital equipment cyclical play because wide-bandgap material transitions sustain R&D characterization demand through node geometry maturation. Acquisition targets should emphasize pulsed-IV specialists with automotive qualification lab relationships and software-defined architecture IP. The signal to watch is capital expenditure announcements from silicon carbide power device manufacturers, which precede tracer procurement cycles by 12-18 months.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Platform Migration | Decouples hardware acquisition from analysis algorithms, enabling remote diagnostics for TSMC and Samsung foundries. |
| Pulsed-IV Capability Expansion | Addresses sub-microsecond pulse width requirements for SiC and GaN device validation in German automotive labs. |
| Localized Calibration Infrastructure | Satisfies SAMR metrological traceability mandates for public-sector procurement eligibility in China. |
| REACH Compliance Redesign | Eliminates hexavalent chromium and lead-based solder to maintain CE marking access for European sales. |
| Cloud-Native Data Pipeline Integration | Connects tracer outputs directly to statistical process control databases via API for predictive yield management. |
Research Methodology
A spread of perspectives from parametric test engineers at foundry operations, metrology equipment procurement managers, wide-bandgap device R&D directors, and aftermarket service providers converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings of instrument vendors, SEMI capital equipment databases, and SAMR calibration protocol documentation. Bottom-up unit demand modeling and top-down semiconductor capital expenditure allocation triangulated market sizing across product tiers.
Demand-supply balance framing anchored the analytical approach, with foundry capacity expansion schedules and wide-bandgap device qualification timelines driving instrument procurement forecasts across the projection horizon. Segmentation dimensions modeled include product type, end user category, technology layer, and application focus, with regional regulatory cluster differentiation for calibration compliance requirements. CAGRs derived from weighted average of historical equipment procurement cycles and emerging technology adoption curves, incorporating precision ADC supply constraints and REACH compliance deadlines as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or electric vehicle production forecasts would shift the trajectory. Forecasts reflect documented assumptions regarding wide-bandgap material transition pace and foundry concentration trends. Quarterly review of silicon carbide device qualification announcements and SAMR regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Video Test Equipment Market
Test and Measurement
Inline Metrology Market
Test and Measurement
Product Design Verification and Validation Solution Market
Test and Measurement
Hour Meter Market
Test and Measurement
Durometer Calibration Service Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Industrial Direct Radiography Market
Test and Measurement
Receptacle Tester Market
Test and Measurement
Automated Calibration-as-a-Service Platforms for Test and Measurement Assets Market
Test and Measurement
High Voltage Testing Market
Test and Measurement
Global Source Measure Unit Market
Test and Measurement
Bit Error Rate Tester Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Electronic Test Instrument Market
Test and Measurement
Non-Destructive Testing Market
Test and Measurement
Battery Testing and Inspection Equipment Market