
 Metrology Software Market | 2026-2036
Metrology Software Market Size, Share, and Industry Trends Forecast 2026-2036
Metrology Software Market Outlook
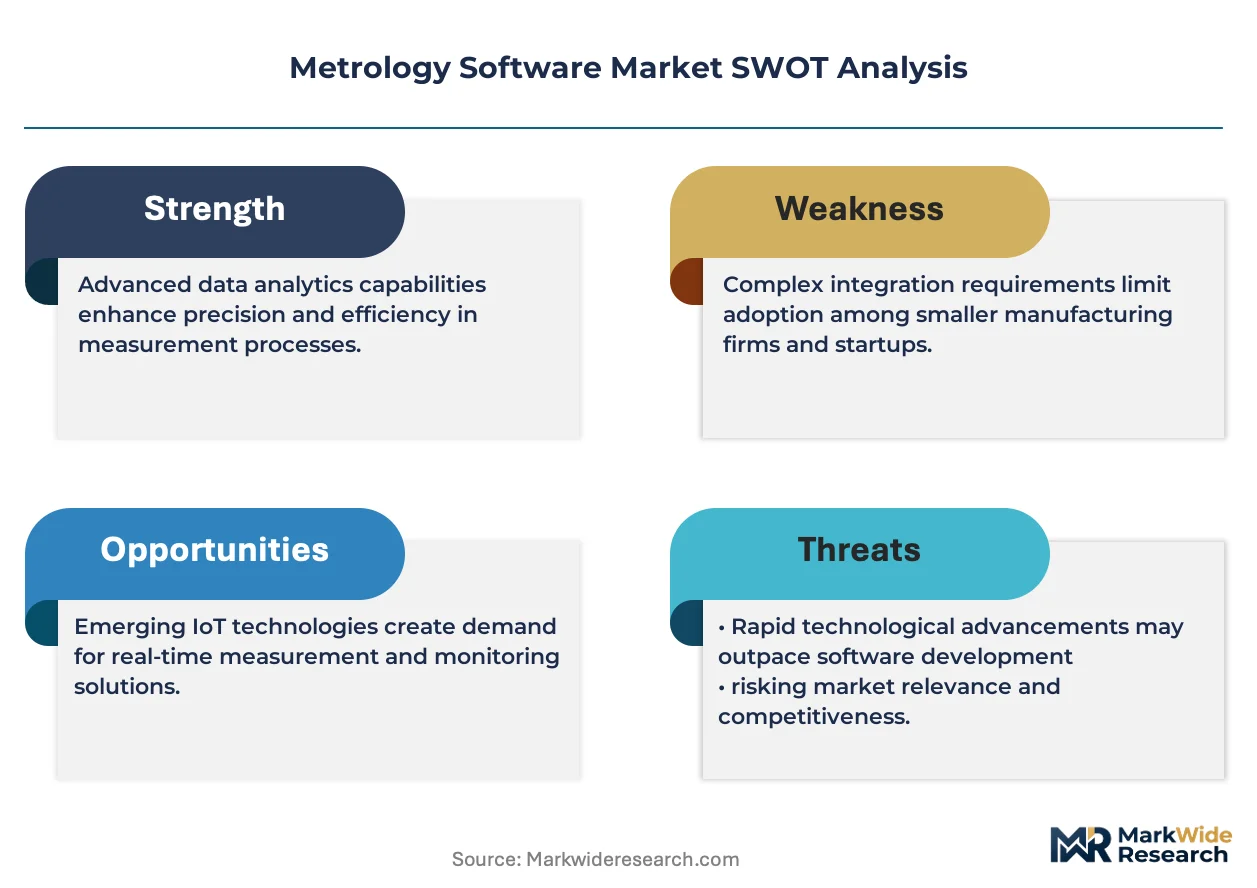
Subscription-based SaaS licensing is reconfiguring capital allocation across the metrology software value chain, allowing mid-sized manufacturers to access enterprise-grade inspection tools without upfront perpetual-license commitments. Hexagon AB leverages its hardware-software bundling strength to lock in recurring revenue from installed coordinate measuring machine bases. Carl Zeiss AG anchors its competitive position through deep integration between optical sensors and proprietary analytics engines. FARO Technologies competes aggressively on portable-arm software bundles, targeting job-shop environments where capital constraints historically blocked adoption.
Metrology software encompasses programs that process dimensional measurement data from coordinate measuring machines, laser trackers, and structured-light scanners, executing geometric dimensioning and tolerancing calculations against CAD nominal models to verify part conformance. The software interprets point-cloud data, applies least-squares fitting algorithms, and generates inspection reports traceable to ISO 14253 decision rules for measurement uncertainty. Cloud-based Solutions are expanding fastest among automotive and aerospace supply chains seeking centralized quality dashboards across distributed plants. Embedded Systems dominate unit volume through tight coupling with shop-floor gauging stations, though margin pools concentrate in Software Packages serving high-mix, low-volume metrology labs requiring customizable inspection routines.
FDA 21 CFR Part 11 electronic records requirements shape software validation protocols for medical-device manufacturers deploying metrology tools in production-quality systems. ISO 17025 accreditation standards force calibration software vendors to document measurement traceability chains and uncertainty budgets for laboratory customers. The EU AI Act's risk-classification framework for automated decision systems will soon extend to machine-learning-enhanced defect detection modules within metrology platforms. Stakeholders must decide whether to build compliant algorithmic transparency layers internally or outsource certification to specialized software testing houses.
Market Dynamics
The shift toward ISO 10303 STEP-compliant digital thread architectures is forcing legacy vendors to rewrite their data interoperability layers, compressing competitive timelines for established players while opening procurement access for mid-sized manufacturers.
Growth Catalysts
- Automotive inline CMM expansion:OEMs and Tier-1 suppliers are scaling software licenses for coordinate measuring machines integrated directly into production lines, eliminating offline inspection bottlenecks.
- FDA 21 CFR Part 11 validation:Medical-device manufacturers require electronic records compliance in production-quality systems, mandating validated metrology software deployments.
- Cloud-based quality dashboards:Automotive and aerospace supply chains are centralizing inspection data across distributed plants, driving SaaS adoption for enterprise-grade analytics.
Market Restraints
- Perpetual-license sunk costs:Manufacturers with existing perpetual-license investments face stranded-asset friction when transitioning to subscription models.
- German supplier concentration:Premium software procurement concentrates in automotive and machine tool clusters around Stuttgart and Munich, limiting price competition.
- Optical-CMM interoperability gaps:Structured-light scanner data formats lack universal compatibility with legacy coordinate measuring machine software stacks.
Strategic Opportunities
- Job-shop portable-arm penetration:Capital-constrained smaller manufacturers represent an underserved segment for software-bundled portable measurement arms.
- EU AI Act algorithmic transparency:Machine-learning defect detection modules will require certified compliance layers, creating service revenue for testing houses.
- Embedded shop-floor integration:Tight coupling between gauging station firmware and inspection routines offers margin expansion in high-volume manufacturing.
Industry Challenges
- GDPR cloud-data residency:European automotive suppliers must architect quality-dashboard deployments that satisfy cross-border data localization requirements.
- ISO 17025 uncertainty documentation:Calibration software vendors face rising documentation burdens for measurement traceability chains demanded by laboratory accreditation bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metrology Software Market |
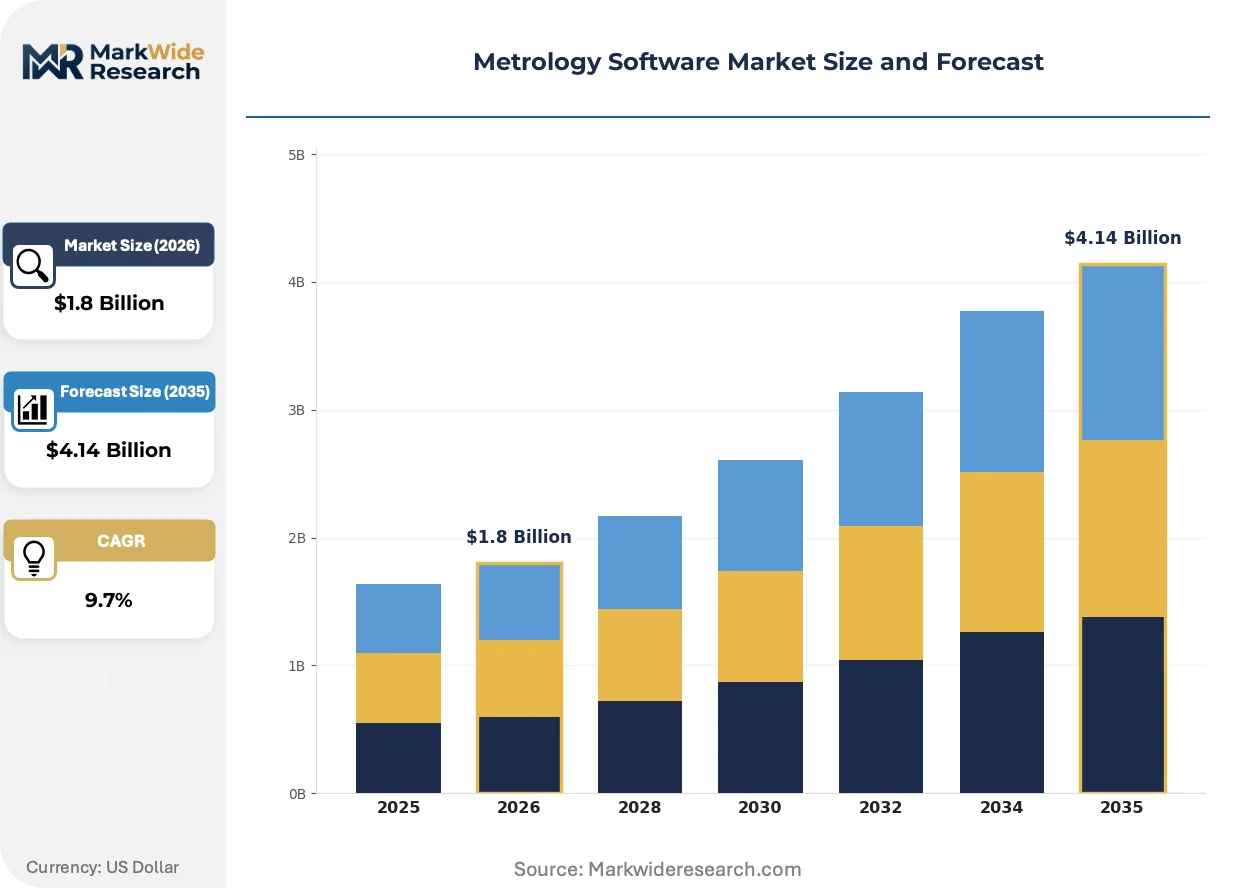
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Packages, Cloud-based Solutions, Embedded Systems, Calibration Software Application: Aerospace, Automotive Testing, Industrial Automation, Electronics Manufacturing Deployment Model: On-premises, SaaS, Hybrid, Open-source End User: Manufacturers, Quality Control Labs, Research Institutions, Academic Organizations |
| Companies Covered | Hexagon AB, Carl Zeiss AG, FARO Technologies, Nikon Metrology NV, Renishaw plc, Quality Vision International, InnovMetric Software, Mitutoyo Corporation, 3D Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metrology Software Market Strategic Shifts
Three intersecting developments are restructuring how dimensional measurement data flows from shop-floor sensors to enterprise quality systems, altering both vendor business models and buyer procurement patterns.
Real-time point-cloud processing engines are digitizing how geometric dimensioning and tolerancing calculations execute against CAD nominal models. Automotive first-tier suppliers in Germany are deploying these engines at scale for inline part conformance verification. The technology is digitizing inspection report generation, compressing the gap between measurement capture and traceable ISO 14253 decision documentation.
REACH substance restrictions on certain optical coating materials are forcing structured-light scanner manufacturers to reformulate sensor specifications. The regulation is accelerating R&D timelines for alternative optical path designs. Medical-device metrology labs in Ireland and the Netherlands are experiencing the longest certification delays as they await revised equipment qualification protocols.
Mid-sized manufacturers are unbundling after-sales service contracts from perpetual software licenses, negotiating standalone technical support agreements. This pattern disrupts traditional vendor lock-in strategies and favors SaaS providers with transparent pricing. The shift is most visible among aerospace component suppliers in the UK and France seeking operational expenditure flexibility.
Metrology Software Market Segmentation
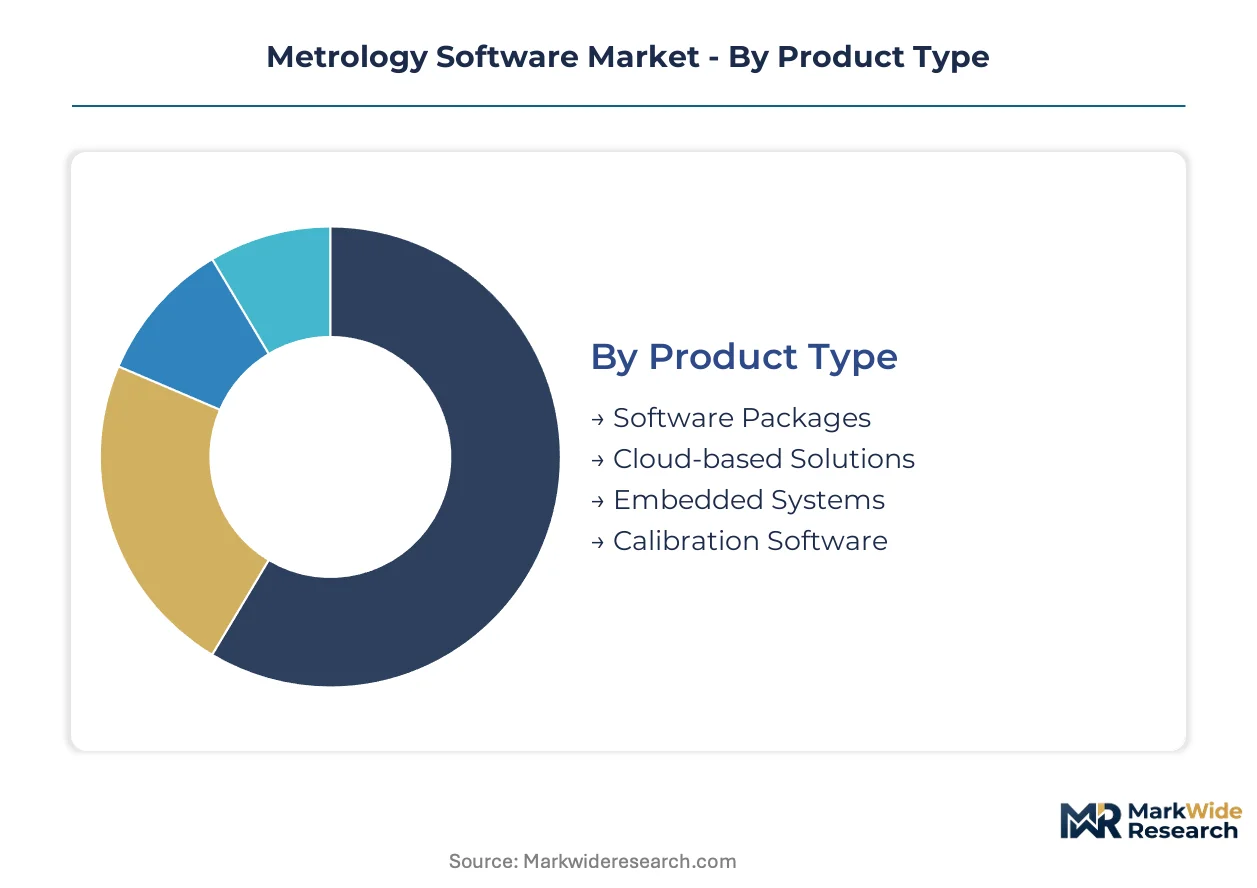
Segmentation in metrology software reveals how procurement patterns diverge between capital-intensive automotive OEMs and flexible job-shop environments. Understanding these splits illuminates why SaaS adoption concentrates in aerospace supply chains while embedded systems dominate high-volume electronics manufacturing.
Product Type:
After-sales service intensity varies sharply across product architectures, with perpetual-license vendors bundling multi-year support contracts while cloud-native players monetize through usage-based tiers.
- Software Packages:Comprehensive inspection suites execute geometric dimensioning and tolerancing calculations against CAD nominal models. German automotive testing departments at OEMs and Tier-1 suppliers are expanding licenses for inline coordinate measuring machines, driven by ISO 10303 STEP-compliant digital thread mandates.
- Cloud-based Solutions:Centralized quality dashboards aggregate inspection data across distributed plants through browser-native interfaces. Automotive and aerospace supply chains in France and the UK are adopting these fastest as mid-sized manufacturers unbundle service contracts from perpetual licenses.
- Embedded Systems:Firmware-tight gauging station software dominates unit volume in high-volume manufacturing environments.
- Calibration Software:ISO 17025-compliant tools document measurement traceability chains for laboratory accreditation.
Software Packages hold the largest share; momentum sits with Cloud-based Solutions.
Application:
Cost tier stratification separates aerospace validation protocols from electronics manufacturing's throughput-driven economics.
- Automotive Testing:Inline CMM integration eliminates offline inspection bottlenecks at production lines. OEMs and Tier-1 suppliers in Germany's Stuttgart and Munich clusters drive premium software procurement, with STEP-compliant data interoperability now mandatory.
- Aerospace:FAA and EASA traceability requirements mandate validated inspection routines for flight-critical components. UK and French aerospace component suppliers are shifting toward SaaS models for operational expenditure flexibility.
- Industrial Automation:Shop-floor gauging stations require real-time point-cloud processing engines.
- Electronics Manufacturing:High-volume PCB inspection favors embedded firmware solutions with minimal customization.
Automotive Testing commands the revenue base; Aerospace climbs the fastest on regulatory compliance spending.
Deployment Model:
Volume concentration favors on-premises installations in regulated medical-device manufacturing, while SaaS expands among distributed supply chains.
- SaaS:Subscription licensing removes upfront capital barriers for mid-sized manufacturers. GDPR data-residency requirements are forcing European automotive suppliers to architect quality-dashboard deployments with cross-border localization safeguards.
- On-premises:Perpetual licenses persist where FDA 21 CFR Part 11 electronic records validation is mandatory. Medical-device manufacturers face stranded-asset friction when transitioning to subscription models.
- Hybrid:Edge-processing with cloud-analytics combinations serve multi-site quality operations.
- Open-source:Community-developed inspection routines attract academic and research customization.
On-premises retains the installed base; SaaS gains share fastest on procurement flexibility.
End User:
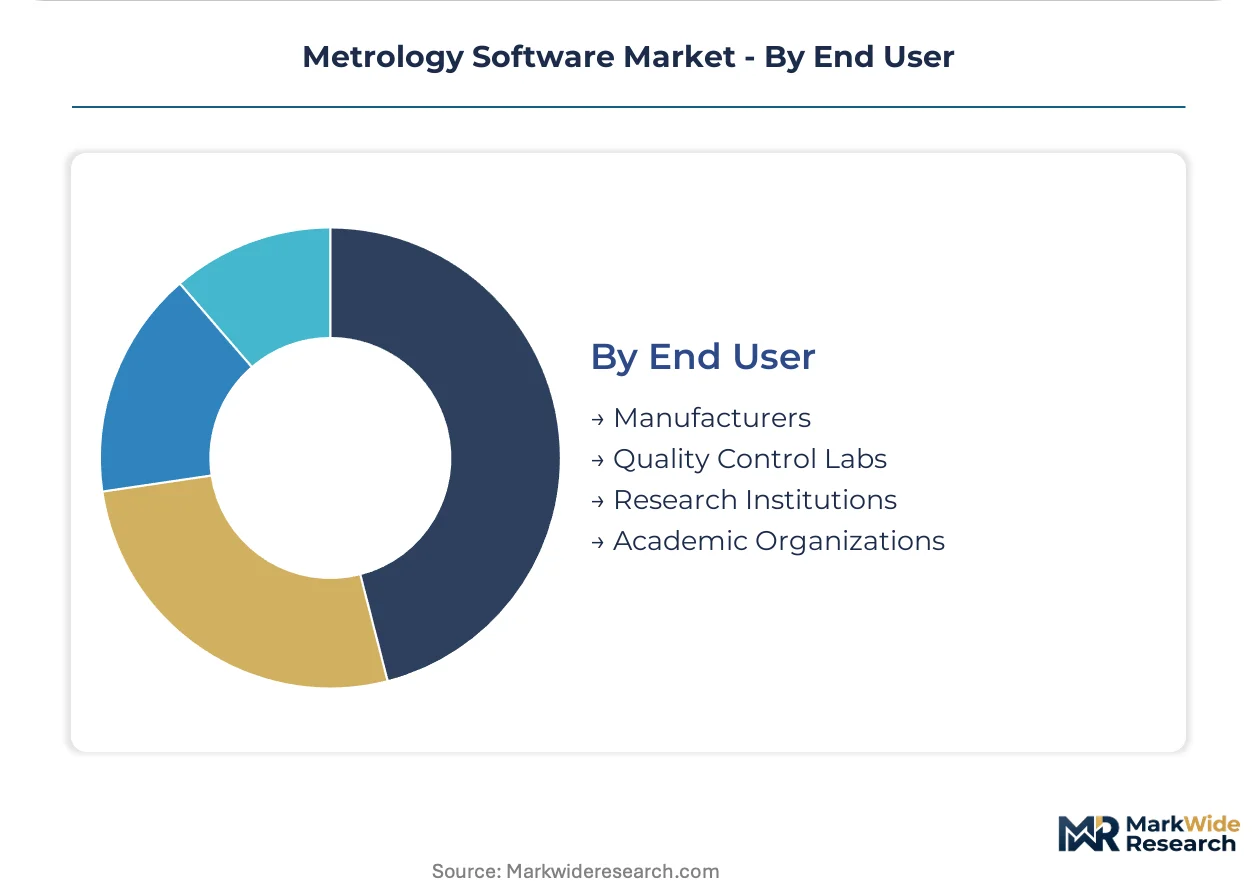
Customer type determines pricing power, with quality control labs demanding ISO 17025 uncertainty documentation and manufacturers prioritizing throughput integration.
- Quality Control Labs:ISO 17025 accreditation standards force calibration software vendors to document measurement traceability chains. Laboratories in Ireland and the Netherlands are experiencing certification delays as they await revised equipment qualification protocols under REACH substance restrictions.
- Manufacturers:Production-quality systems require validated software deployments for FDA 21 CFR Part 11 compliance. Job-shop environments with capital constraints represent an underserved segment for portable-arm software bundles.
- Research Institutions:Customizable inspection routines support non-standard measurement protocols.
- Academic Organizations:Training licenses and open-source contributions shape early-stage talent pipelines.
Manufacturers represent the largest addressable pool; Quality Control Labs show the steepest expansion trajectory on accreditation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive clusters drive premium procurement through ISO 10303 STEP mandates, while REACH substance restrictions delay equipment qualification across European metrology labs. France and the UK accelerate SaaS adoption among aerospace suppliers seeking operational expenditure flexibility.
United States
FDA 21 CFR Part 11 electronic records requirements shape validation protocols for medical-device manufacturers deploying metrology tools in production-quality systems. The FAA mandates traceability requirements for flight-critical aerospace components, driving validated inspection routine deployments. California's medical-device manufacturing corridor and Washington State's aerospace clusters concentrate software procurement for compliant quality systems.
Germany
Automotive OEMs and Tier-1 suppliers scale software licenses for inline coordinate measuring machines integrated directly into production lines. The EU AI Act's risk-classification framework for automated decision systems will extend to machine-learning-enhanced defect detection modules within metrology platforms. Stuttgart and Munich automotive clusters anchor premium software procurement, with STEP-compliant data interoperability now mandatory for digital thread architectures.
United Kingdom
Aerospace component suppliers shift toward SaaS models for operational expenditure flexibility, unbundling after-sales service contracts from perpetual licenses. GDPR data-residency requirements force quality-dashboard deployments with cross-border localization safeguards. Midlands aerospace manufacturing and Southeast England precision engineering clusters drive cloud-native inspection tool adoption.
France
Mid-sized manufacturers negotiate standalone technical support agreements, disrupting traditional vendor lock-in strategies. EASA traceability requirements mandate validated inspection routines for aerospace supply chains. Toulouse aerospace manufacturing and Lyon precision machinery clusters concentrate procurement for flexible deployment models.
China
Industrial automation investments accelerate demand for real-time point-cloud processing engines in high-volume manufacturing environments. GB standards and MIIT industrial digitization programs shape software interoperability requirements. Yangtze River Delta electronics manufacturing and Pearl River Delta automotive clusters drive embedded gauging station firmware adoption.
Metrology Software Market Competitive Environment
Channel-controlling players compete with product-specialist players across hardware-software bundling and pure-play analytics vectors. The vendor base organizes around three strategic archetypes: precision measurement conglomerates leveraging installed equipment bases, optical sensor specialists integrating proprietary analytics engines, and portable-arm vendors targeting capital-constrained job-shop environments. Dominant competitive moves include hardware-software bundling to lock in recurring revenue and SaaS licensing transitions to capture mid-sized manufacturer procurement.
Among precision measurement conglomerates, Hexagon AB and Carl Zeiss AG exemplify the hardware-software integration archetype, occupying positions where equipment installed bases generate captive software demand. FARO Technologies represents the portable measurement specialist tier, sitting within job-shop market segments where bundled software-hardware offerings address capital accessibility constraints.
| Leading Market Players |
|---|
| Hexagon AB |
| Carl Zeiss AG |
| FARO Technologies |
| Nikon Metrology NV |
| Renishaw plc |
| Quality Vision International |
| InnovMetric Software |
| Mitutoyo Corporation |
| 3D Systems Corporation |
| Others |
Value Chain & Pricing Dynamics
German automotive clusters around Stuttgart and Munich concentrate premium software procurement, anchoring margin pools in ISO 10303 STEP-compliant digital thread architectures while compressing price competition in adjacent European markets. This upstream concentration forces mid-sized manufacturers toward SaaS tiers that unbundle after-sales service from perpetual licenses.
Pricing Analysis
Certification level creates the primary spread across the metrology software market, with FDA 21 CFR Part 11-validated suites commanding substantial premiums over standard ISO 17025 laboratory tiers. Three-tier pricing structure across premium, standard, and economy levels reflects this compliance stratification, though SaaS licensing is displacing perpetual models and intensifying cost compression in the economy tier. Tier-1 automotive suppliers in Germany show the lowest price sensitivity due to mandated digital thread investments, while capital-constrained job shops in France and the UK drive demand for portable-arm software bundles with transparent subscription terms.
Supply Chain Analysis
Contract manufacturing for metrology hardware concentrates with Foxconn, Jabil, and Benchmark Electronics holding substantial EMS capacity for coordinate measuring machine and optical sensor production. Software development draws from engineering talent pools in Germany, the United States, and India, with cloud infrastructure resting on AWS, Azure, and regional European providers subject to GDPR data-residency constraints. Single-source vulnerability runs through specialized optical coating suppliers facing REACH substance restriction delays. Distribution runs through direct OEM sales teams for enterprise accounts and specialized metrology distributors serving mid-market job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metrology software market represents a high-growth disruption as EU AI Act risk-classification frameworks extend compliance burdens to machine-learning defect detection modules, forcing algorithmic transparency investments across vendor tiers.
For Market Incumbents: Pre-empt SaaS-native challengers by accelerating hardware-software bundling transitions that lock in recurring revenue from installed CMM bases. Incumbents must absorb ISO 10303 STEP interoperability rewrite costs before mid-sized manufacturers complete unbundling of after-sales service contracts, which would erode traditional lock-in strategies. Vertical integration into cloud analytics engines offers defensive margin protection against pure-play software entrants. For New Entrants and Emerging Players: Build out portable-arm software bundles targeting capital-constrained job-shop environments in France and the UK, where operational expenditure flexibility outweighs upfront perpetual-license commitments. The aerospace component supplier segment shows the deepest white-space penetration potential given EASA traceability mandates and shifting procurement patterns toward SaaS models. A channel partnership strategy with specialized metrology distributors accelerates reach without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision measurement conglomerates holding mature CMM installed bases but lagging cloud-native analytics capabilities. Long-term viability across the analysis window favors targets with embedded shop-floor gauging station firmware exposure in high-volume manufacturing. Watch for EU AI Act certification delays at structured-light scanner manufacturers as an inflection signal for distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10303 STEP Interoperability Rewrite | Legacy vendors must rebuild data layers to retain German automotive procurement access under digital thread mandates. |
| SaaS Licensing Transition | Subscription models capture mid-sized manufacturers in France and UK seeking operational expenditure flexibility. |
| EU AI Act Compliance Layer Development | Machine-learning defect detection modules require certified algorithmic transparency for European market access. |
| Portable-Arm Software Bundle Expansion | Capital-constrained job shops represent underserved penetration targets with bundled hardware-software offerings. |
| Cloud Analytics Engine Acquisition | Pure-play analytics capabilities deepen recurring revenue streams beyond traditional perpetual-license models. |
Study Parameters
Operator-level perspectives from quality control lab directors, automotive testing engineers, aerospace component procurement leads, and medical-device regulatory affairs managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews across these stakeholder tiers with secondary validation drawing from FDA 21 CFR Part 11 guidance documents, EASA traceability directives, ISO 17025 accreditation standards, and EU AI Act regulatory texts. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed the forecast framework, with volume and value outputs reflecting modeled projections across product type, deployment model, application vertical, and regional adoption pattern dimensions. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology substitution curves. Industry-specific inputs included automotive inline CMM license expansion rates, cloud dashboard adoption velocity in aerospace supply chains, and REACH substance restriction impacts on equipment qualification timelines.
The forecast holds incumbent behavior within observed patterns; aggressive SaaS transitions by precision measurement conglomerates or accelerated EU AI Act enforcement would shift outcomes substantially. Cross-checking against German automotive OEM capex disclosures and medical-device FDA warning letter trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
Air Leak Testing Market
Test and Measurement
Industrial Metrology Market
Test and Measurement
Fluorometers Market
Test and Measurement
Advanced Node Wafer Defect Inspection Systems Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Shock Testing System Market
Test and Measurement
Brightness Meter Market
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Digital Battery Internal Resistance Tester Market
Test and Measurement
Melt Flow Tester Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
Bit Error Rate Tester Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
Tube Tester Market