
 Four-Quadrant Battery Simulator Market | 2026-2036
Four-Quadrant Battery Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Four-Quadrant Battery Simulator Market Insights
Automotive test labs is consolidating as the dominant end-use vertical for four-quadrant battery simulators, displacing slower-growing consumer electronics qualification channels. Keysight Technologies leverages its instrumentation heritage to anchor premium positioning in high-fidelity power cycling applications. Chroma ATE Inc. competes through manufacturing scale in medium-power test systems serving Asian EV supply chains.
A four-quadrant battery simulator is an electronic test instrument capable of both sourcing and sinking power across positive and negative voltage and current polarities, typically operating with microsecond-level transient response and better than 0.1% measurement accuracy to replicate real-world charge-discharge profiles. Its primary purpose is to validate battery management systems, cell chemistries, and pack architectures under dynamic load conditions without requiring physical battery cycling. Battery test system configurations command the deepest margin pools where integrated thermal chambers and automation layers justify premium pricing. Programmable load segments dominate unit volumes in research institutions running parametric studies across cell formats.
FCC equipment authorization requirements shape electromagnetic compatibility thresholds for simulator exports into the United States, while CE marking under the EU's Low Voltage Directive governs European market access for instruments above 50V operating potential. Japan's METI enforces JIS standards on power measurement precision that filter supplier eligibility for domestic automotive programs. Stakeholders must monitor how evolving ISO 6469 electric vehicle safety standards recast test protocol requirements for abuse simulation and thermal runaway characterization.
Market Dynamics
Automotive OEMs are internalizing battery validation workflows to compress development cycles and satisfy tightening homologation timelines for next-generation electric architectures.
Growth Catalysts
- EU Battery Regulation sustainability mandates:Circularity requirements and carbon footprint declarations force manufacturers to expand in-house testing capacity for lifecycle validation.
- Solid-state cell chemistry maturation:Next-generation formats demand expanded voltage and current ranges that obsolete legacy two-quadrant equipment.
- Germany:Dense clustering of automotive R&D centers and national metrology institutes anchors procurement of high-precision instrumentation.
Market Restraints
- Gallium nitride semiconductor supply:Disruption in wide-bandgap device fabrication concentrates in Taiwanese foundries, constraining high-frequency power stage availability.
- CE marking complexity:Low Voltage Directive compliance for instruments exceeding 50V operating potential extends certification timelines and fragments supplier eligibility.
- Physical battery cycling:Established validation protocols in conservative test labs resist displacement despite superior speed and repeatability of electronic simulation.
Strategic Opportunities
- India:PLI scheme incentives for domestic cell manufacturing create greenfield demand for qualification infrastructure as production capacity scales.
- Grid-scale storage integration:Megawatt-hour pack architectures for utility applications require novel high-power, high-voltage test configurations.
- Digital twin convergence:Real-time hardware-in-the-loop coupling with cloud-based degradation models enables predictive validation workflows.
Industry Challenges
- Power electronics expertise scarcity:Recruitment bottlenecks for engineers proficient in magnetic design and thermal management constrain R&D throughput.
- ISO 6469 abuse protocol evolution:Draft amendments to electric vehicle safety standards mandate expanded thermal runaway characterization, requiring simulator hardware upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Four-Quadrant Battery Simulator Market |
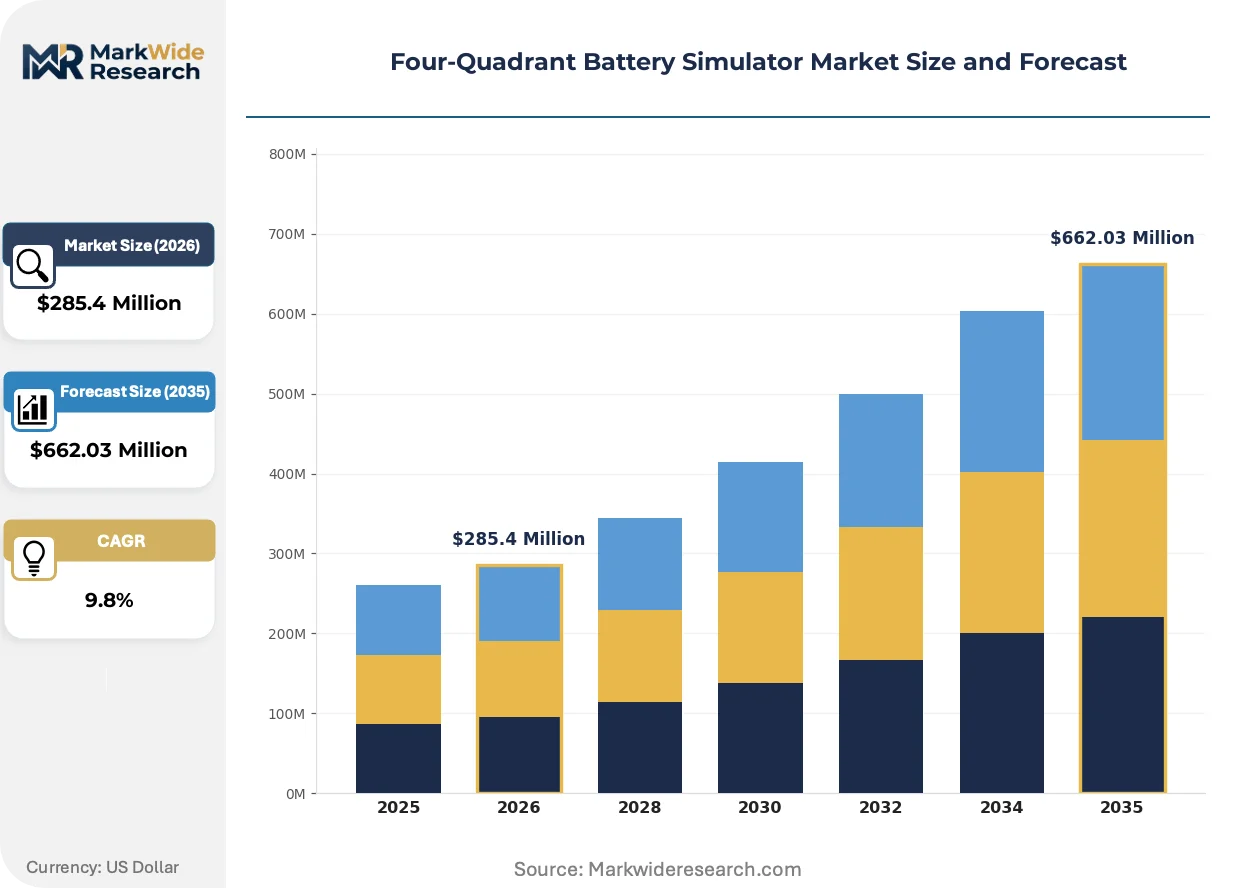
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $662.03 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Programmable Load, Battery Test System, Electronic Load, Power Analyzer End User: Automotive Test Labs, Research Institutions, Aerospace, Consumer Electronics Connectivity: USB, Ethernet, GPIB, RS-232 Power Rating: Low Power, Medium Power, High Power, Ultra-High Power |
| Companies Covered | Rohde & Schwarz, Yokogawa Electric Corporation, Chroma ATE Inc., Keysight Technologies, Regatron AG, Keithley Instruments, Bitrode Corporation, Itech Electronics, AMETEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Four-Quadrant Battery Simulator Market Trends and Innovations
Synthetic battery modeling is compressing physical test cycles while regulatory pressure on validation rigor intensifies procurement specifications across automotive and stationary storage verticals.
Silicon carbide power semiconductors are rewriting thermal and switching performance boundaries in four-quadrant architectures. Tier 1 automotive suppliers are adopting 800V-class systems within eighteen-month procurement windows. This transition is rewriting margin structures as legacy IGBT-based platforms face accelerated obsolescence.
Japan's METI enforcement of JIS power measurement precision standards is filtering supplier eligibility for domestic automotive programs. The regulation mandates traceable calibration chains that exclude non-accredited instrumentation vendors. European and North American test labs are voluntarily adopting equivalent specifications to align with Japanese OEM qualification requirements.
Automotive OEMs are consolidating vendor relationships around integrated test system providers capable of delivering thermal chamber coupling and automation layers. Standalone programmable load suppliers are losing share to turnkey configuration specialists. This consolidation is most pronounced in Germany and the United States where in-house battery center buildouts concentrate procurement authority.
Four-Quadrant Battery Simulator Market Segmentation
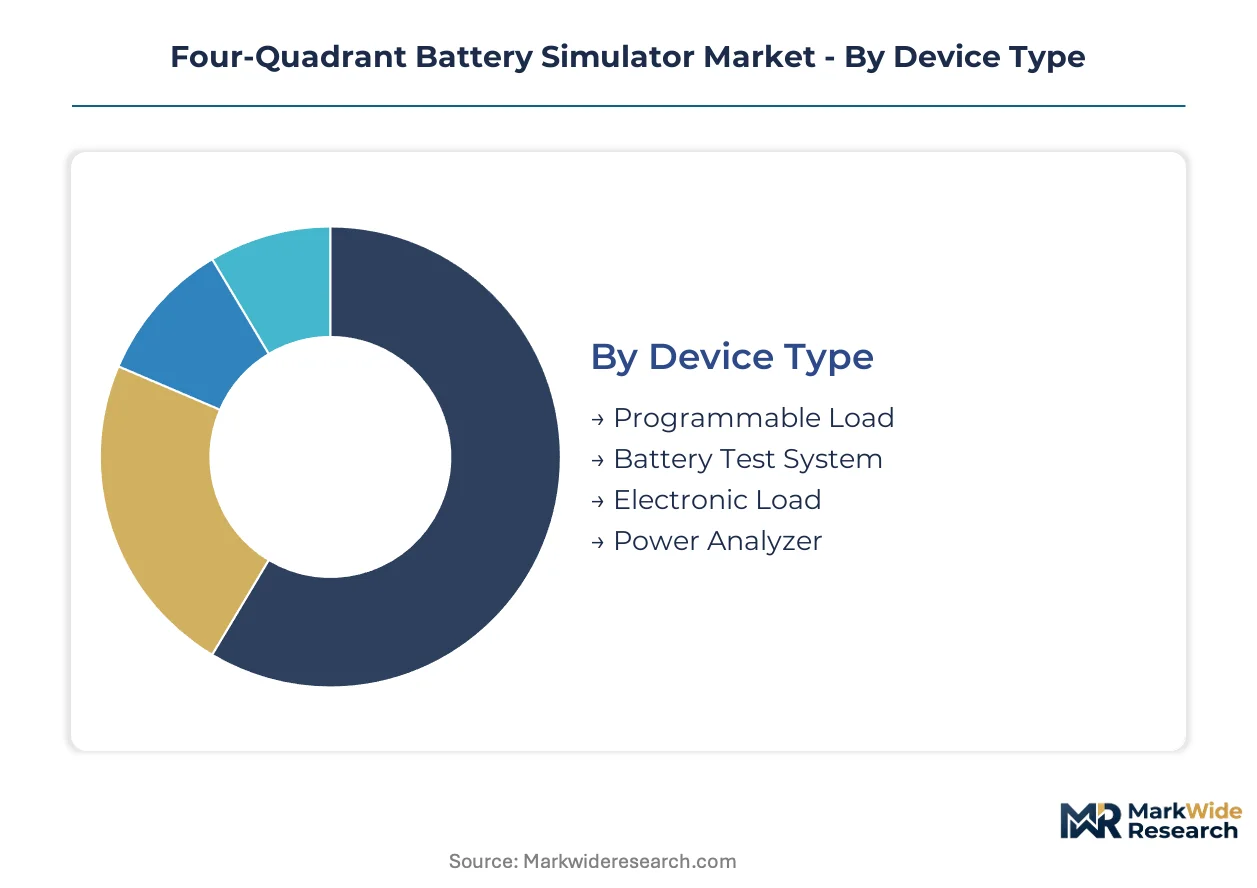
Four-quadrant battery simulators fragment across power architectures, end-use workflows, and interface protocols. Each dimension carries distinct margin structures and supplier qualification barriers that reshape procurement patterns.
Device Type:
Supply concentration in high-fidelity instrumentation clusters around integrated system providers with thermal chamber coupling capabilities.
- Battery Test System:Integrated configurations combine four-quadrant power stages with environmental chambers and automation software. Automotive OEMs in Germany and the United States prioritize these turnkey systems for 800V-class validation cycles.
- Programmable Load:Modular sink-source units serve parametric studies across cell formats with microsecond transient response. Research institutions in Japan drive procurement under METI-enforced JIS calibration standards.
- Electronic Load:Standalone sink-only instruments face share erosion as integrated systems absorb qualification workflows.
- Power Analyzer:Precision measurement subsystems support metrology-grade validation at national institutes.
Today's leader: Battery Test System. Tomorrow's challenger: Programmable Load.
End User:
Cost tier stratification separates capital-intensive automotive validation from budget-constrained academic research.
- Automotive Test Labs:In-house battery centers at OEMs compress development cycles under tightening EU Battery Regulation timelines. Procurement concentrates in Germany, the United States, and Japan.
- Research Institutions:Universities and national labs run parametric studies across solid-state cell chemistries. Funding cycles and shared facility models constrain per-lab equipment budgets.
- Aerospace:Satellite and aviation battery qualification demands radiation-hardened specifications with extended temperature ranges.
- Consumer Electronics:Smartphone and laptop cell validation represents a shrinking channel as automotive applications absorb supplier capacity.
Volume gravity centers on Automotive Test Labs. Margin expansion follows Research Institutions.
Connectivity:
Interface standard maturity determines integration friction with existing lab automation infrastructure.
- Ethernet:LXI-compliant instruments enable remote monitoring and cloud-based degradation model coupling. Modern automotive test benches standardize on this protocol for distributed data acquisition.
- USB:Plug-and-play convenience dominates benchtop configurations in research settings with limited IT support.
- GPIB:Legacy IEEE-488 bus persists in upgraded facilities with decades-old test codebases.
- RS-232:Serial interfaces survive in cost-optimized portable units for field diagnostics.
Adoption momentum favors Ethernet. Replacement cycles sustain USB.
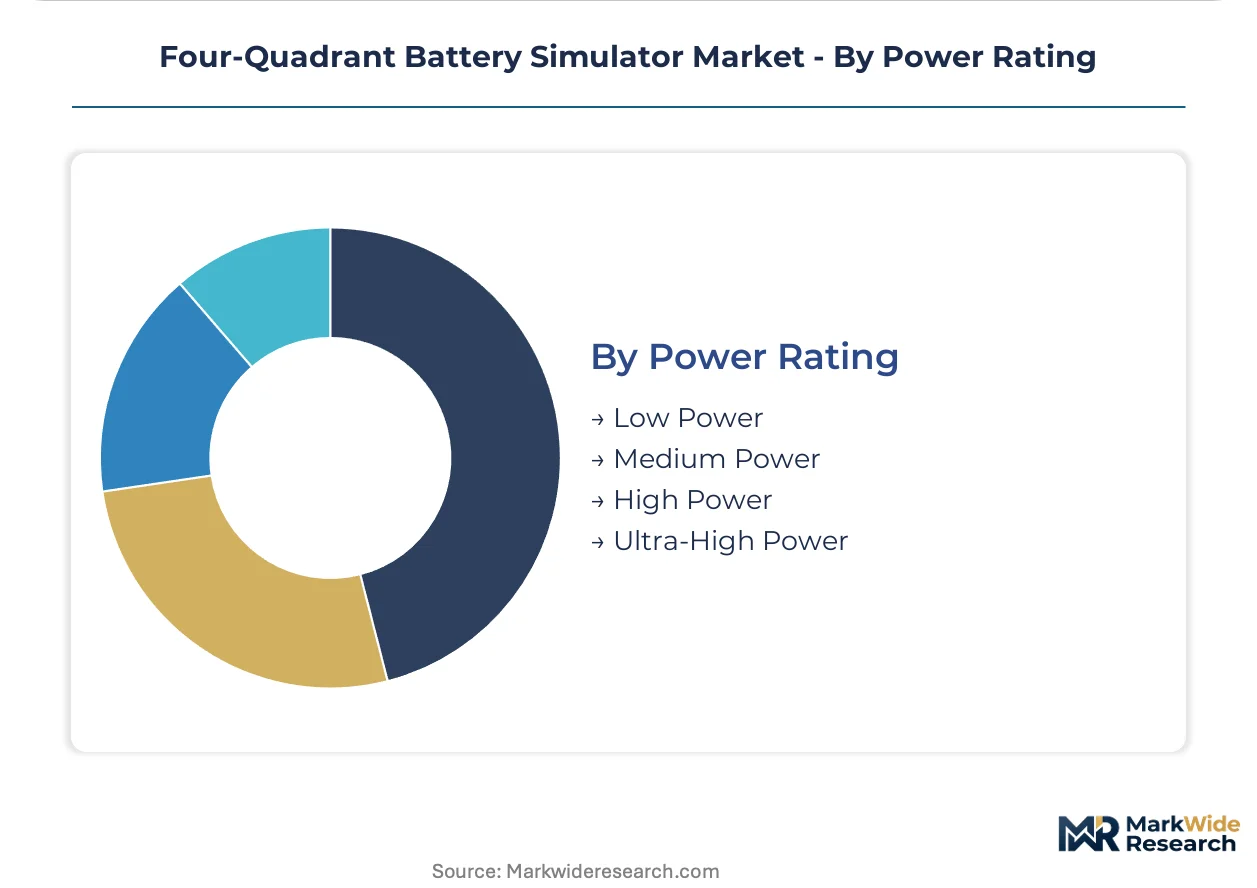
Power Rating:
Application voltage class dictates semiconductor technology choices and thermal management complexity.
- High Power:Silicon carbide-based stages handle 800V automotive pack validation with reduced switching losses. Gallium nitride supply constraints from Taiwanese foundries limit availability.
- Medium Power:IGBT platforms serve Asian EV supply chain qualification with manufacturing scale advantages from Chroma ATE and comparable suppliers.
- Ultra-High Power:Megawatt-hour grid storage test configurations require novel parallel architectures still in commercialization.
- Low Power:Consumer electronics cell cycling represents a commoditized segment with compressed margins.
Technology leadership sits with High Power. Steepest expansion trajectory: Ultra-High Power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting procurement toward jurisdictions with streamlined CE marking pathways and consolidated metrology accreditation, compressing supplier qualification timelines for automotive test labs.
Germany
Automotive OEMs in Stuttgart and Munich are expanding in-house battery validation centers under EU Battery Regulation circularity mandates. The KBA enforces homologation timelines that compress equipment procurement cycles. Dense R&D clustering in Baden-Württemberg anchors high-precision instrumentation demand from national metrology institutes.
United States
FCC equipment authorization requirements shape electromagnetic compatibility thresholds for simulator imports, filtering supplier eligibility. The EPA's tightening emissions benchmarks force Detroit-based OEMs to accelerate EV validation workflows. Michigan and California test lab buildouts concentrate procurement authority around integrated system providers.
Japan
METI enforcement of JIS power measurement precision standards excludes non-accredited instrumentation vendors from domestic automotive programs. Toyota and Honda supplier qualification protocols demand traceable calibration chains. Nagoya-based Tier 1 suppliers are adopting 800V-class validation systems within compressed procurement windows.
China
MIIT's GB standards for electric vehicle safety recast test protocol requirements for abuse simulation and thermal runaway characterization. Ningbo and Shenzhen battery manufacturing clusters are scaling qualification infrastructure under dual carbon goals. Domestic cell producers are internalizing validation workflows to reduce reliance on imported test equipment.
India
PLI scheme incentives for domestic cell manufacturing create greenfield demand for qualification infrastructure as Tamil Nadu and Gujarat production capacity scales. The BIS is harmonizing power measurement standards with JIS and IEC frameworks. Automotive test labs in Pune and Chennai are absorbing supplier capacity previously directed toward consumer electronics channels.
Four-Quadrant Battery Simulator Market Competitive Landscape
Capacity expansion dominates the current landscape as tiered competition separates integrated system architects from modular component suppliers. The vendor base stratifies across three archetypes: precision instrumentation heritage players, manufacturing-scale Asian fabricators, and specialized power electronics boutiques. Consolidation pressures favor turnkey providers with thermal chamber coupling capabilities over standalone programmable load vendors. M&A activity and strategic partnerships represent the dominant competitive moves as OEMs consolidate vendor relationships.
Among German precision instrumentation specialists, Rohde & Schwarz and Regatron AG occupy positions within the heritage-driven tier, exemplifying engineering cultures anchored in metrology-grade validation protocols. Keysight Technologies, with its instrumentation legacy, represents the integrated system archetype where automation layers and software ecosystems justify premium positioning. Chroma ATE Inc. sits within the manufacturing-scale tier, leveraging production volume advantages to serve Asian EV supply chain qualification demands. These three anchors illustrate how geographic origin and corporate structure correlate with strategic positioning across power rating and end-use segments.
| Leading Market Players |
|---|
| Rohde & Schwarz |
| Yokogawa Electric Corporation |
| Chroma ATE Inc. |
| Keysight Technologies |
| Regatron AG |
| Keithley Instruments |
| Bitrode Corporation |
| Itech Electronics |
| AMETEK |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide power semiconductor adoption is compressing thermal management costs while concentrating procurement leverage among 800V-class system architects. This technology transition simultaneously elevates R&D amortization burdens for IGBT legacy platforms and rewards accredited suppliers with METI-traceable calibration chains.
Pricing Analysis
Distributor margin layers in European automotive test lab procurement compress 12-18 points under direct OEM contracting arrangements. Three-tier pricing structure across premium, standard, and economy levels separates turnkey battery test systems with thermal chamber coupling from modular programmable loads and standalone electronic loads. Cost compression in medium-power IGBT segments is intensifying because Chroma ATE manufacturing scale advantages feed price competition across Asian EV supply chains. Research institutions exhibit highest price sensitivity due to shared-facility funding models, while German automotive OEMs absorb premium tiers for homologation-critical instrumentation.
Supply Chain Analysis
Refurbishment flows for legacy GPIB-equipped instruments extend equipment lifecycles in budget-constrained academic settings, delaying replacement demand. Wide-bandgap device fabrication concentrates in Taiwanese foundries, Japanese precision component suppliers, and German metrology-grade subsystem providers. Raw material dependencies span silicon carbide substrates, gallium nitride epitaxial wafers, and high-precision current shunt resistors. Single-source vulnerability in Taiwanese gallium nitride foundry capacity constrains high-frequency power stage availability for ultra-high-power configurations. Distribution runs through authorized instrumentation distributors serving automotive R&D clusters, direct OEM contracting for integrated systems, and academic procurement cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor suppliers mastering silicon carbide thermal design and JIS-traceable calibration chains, as OEM consolidation around turnkey providers compresses pricing power for modular component vendors.
For Market Incumbents: Hedge against gallium nitride supply disruption by securing dual-source semiconductor procurement agreements with Japanese and European foundry alternatives. Deepen backward integration into silicon carbide substrate sourcing to defend margin position against emerging power electronics boutiques. Prioritize certification investment for EU Battery Regulation abuse protocol compliance ahead of ISO 6469 amendment finalization. For New Entrants and Emerging Players: Authorized distributors serving mid-tier automotive test labs represent the most accessible channel partner type for bypassing incumbent OEM direct relationships. White-space concentration sits with India PLI-scheme cell manufacturing qualification infrastructure and grid-scale storage megawatt-hour test configurations. Target acquisition of regional calibration service providers to accelerate METI accreditation timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among programmable load specialists losing share to integrated system consolidation. Long-term viability over the next decade hinges on silicon carbide design capability and thermal chamber coupling expertise. Acquisition target archetype: precision power electronics boutiques with automotive OEM qualification history. Monitor JIS calibration standard harmonization progress across European test labs as inflection indicator for premium-tier pricing power migration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Platform Migration | 800V-class validation capability secures procurement preference from Stuttgart and Munich OEM battery centers. |
| METI Calibration Accreditation | Traceable measurement chains unlock Toyota and Honda supplier qualification protocols. |
| India PLI Infrastructure Partnership | Tamil Nadu and Gujarat cell manufacturing buildouts create greenfield demand for qualification systems. |
| Thermal Chamber Integration | Environmental coupling capabilities defend against standalone programmable load commoditization. |
| Digital Twin Hardware Coupling | Real-time cloud degradation model integration enables predictive validation workflow premiums. |
Research Methodology
Direct dialogue with automotive test lab directors, power electronics procurement managers, metrology institute calibration officers, and battery management system validation engineers grounded qualitative findings. Secondary validation drew from SEC 10-K instrument segment disclosures, MIIT GB standard publication records, KBA homologation timeline documentation, and IHS Markit EV production databases. Bottom-up and top-down triangulation reconciled equipment shipment volumes against OEM battery center buildout announcements.
Bottom-up modeling aggregated segment-level demand across power rating tiers, device configurations, and end-user verticals; top-down verification cross-checked against automotive R&D capital expenditure patterns. Segmentation dimensions spanned device type, power architecture, connectivity protocol, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and technology transition elasticity parameters, with silicon carbide adoption curves and EU Battery Regulation compliance deadlines as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to wide-bandgap semiconductor supply constraints and ISO 6469 abuse protocol amendment timing. Practitioners should monitor gallium nitride foundry utilization rates and JIS calibration standard voluntary adoption trends across North American test labs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Printed Circuit Board Inspection Equipment Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Hybrid Supercapacitor Lifetime and Safety Test Equipment Market
Test and Measurement
3D Automatic Optical Inspection Machine Market
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market
Test and Measurement
Advanced Probe Card and Wafer Probing Test Systems Market
Test and Measurement
Over-The-Air (OTA) Testing Market
Test and Measurement
Fingertip Pulse Oximeter Electronic Testers Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Radiation Tester Market
Test and Measurement
High-Aspect-Ratio 3D NAND Metrology Equipment Market
Test and Measurement
Data Center Testing Market
Test and Measurement
Whiteness Meter Market
Test and Measurement
Tube Tester Market
Test and Measurement
North America Electrical Testing Services Market
Test and Measurement
Brightness Meter Market