
 Global Touchable Holographic Display Market | 2026-2036
Global Touchable Holographic Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Touchable Holographic Display Market Foresight
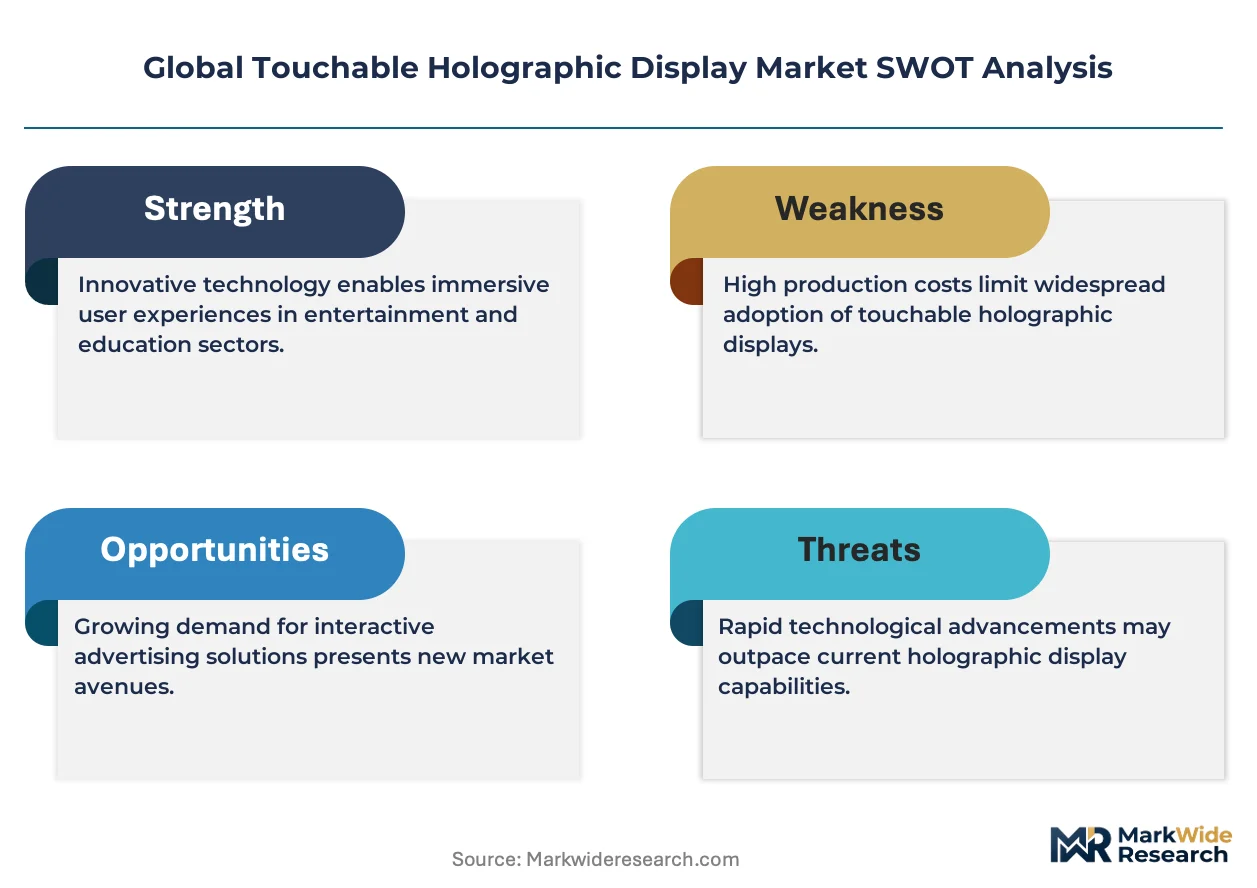
The gap between laboratory-grade retinal projection systems and mass-market digital holography kits is realigning vendor priorities. RealView Imaging Ltd leverages clinical validation to anchor its position in medical visualization. Zebra Imaging Inc sustains defense contracts through proprietary light field printing. MicroCloud Hologram Inc competes on software-defined hologram rendering for enterprise conferencing.
A touchable holographic display projects three-dimensional imagery into physical space and permits direct manual interaction without wearable interfaces, typically employing spatial light modulators with refresh rates exceeding 60 Hz to maintain image stability during contact. Its primary commercial purpose spans surgical planning, immersive training, and volumetric design review where depth perception reduces cognitive load. Volume holography currently leads in medical and defense installations owing to superior spatial fidelity, while digital holography segments expand fastest in consumer electronics as photopolymer costs decline. Electro-holography occupies narrow but high-margin niches in research institutes requiring real-time interference pattern manipulation.
FDA clearance pathways shape medical deployment timelines in the United States, while EMA's Medical Device Regulation governs clinical adoption across European hospitals. Japan's METI funds holographic interface development through national digitization initiatives, and IEC electromagnetic compatibility standards constrain hardware export configurations. Stakeholders must monitor which regulatory body first establishes touch-force safety thresholds for direct-contact volumetric displays, as this precedent will cascade into procurement specifications across all major jurisdictions.
Market Dynamics
The transition from laboratory prototypes to clinical-grade retinal projection systems is compressing development cycles and forcing capital reallocation toward FDA-compliant manufacturing lines.
Growth Catalysts
- Defense simulation budgets:The United States, Japan, and Germany maintain dedicated aerospace procurement streams for volumetric training environments, insulating hardware vendors from consumer electronics volatility.
- Spatial light modulator resolution advances:Refresh rates exceeding 60 Hz now stabilize imagery during manual contact, unlocking surgical planning applications previously limited to non-interactive holography.
- METI digitization initiatives:Japan's Ministry of Economy, Trade and Industry directly funds holographic interface development, accelerating domestic hospital pilot programs and component supplier scaling.
Market Restraints
- Photopolymer cost volatility:Digital holography segments remain exposed to specialty polymer supply constraints, compressing margins in consumer electronics applications.
- Electromagnetic compatibility certification:IEC 61000 series compliance adds twelve to eighteen months to hardware export timelines, particularly constraining Asian manufacturers targeting European medical markets.
- Retinal projection safety thresholds:Absence of established touch-force limits across FDA, EMA, and PMDA jurisdictions creates procurement uncertainty for hospital capital committees.
Strategic Opportunities
- Enterprise conferencing white space:Software-defined hologram rendering enables remote volumetric collaboration, with Germany's automotive design studios piloting supplier review workflows.
- Light field printing defense exports:Proprietary volumetric hardcopy technology addresses classified briefing requirements in allied nations lacking domestic holographic infrastructure.
- EMA Medical Device Regulation alignment:Early compliance with MDR clinical evidence requirements positions vendors for streamlined European hospital tender participation.
Industry Challenges
- Interference pattern manipulation expertise:Electro-holography research institutes face acute shortages of physicists capable of real-time optical computation at sub-millisecond latencies.
- Legacy PACS integration:Hospital IT departments struggle to route volumetric imagery into existing radiology archiving systems without proprietary middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Touchable Holographic Display Market |
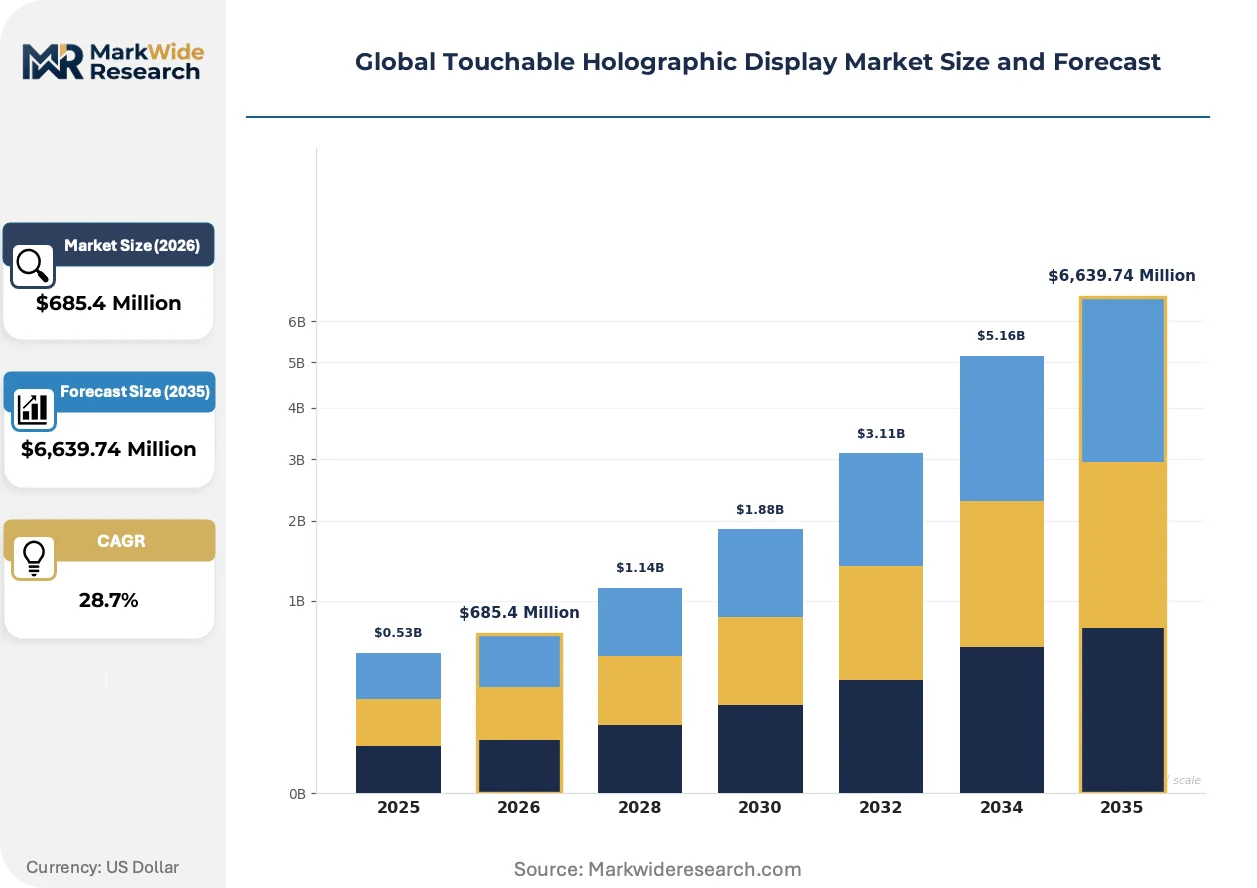
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $6,639.74 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retinal Projection, Light Field Display, Volume Holography, Digital Holography Technology: Laser Scanning, Interferometry, Electro-Holography, Spatial Light Modulator, Photopolymer Use Case: Augmented Reality, Virtual Conferencing, Interactive Advertising, 3D Modeling, Education End User: Consumer Electronics, Aerospace Simulation, Defense Training, Architecture Firms, Research Institutes |
| Companies Covered | RealView Imaging Ltd, Zebra Imaging Inc, MicroCloud Hologram Inc, Envisics Ltd, Kino-mo Ltd, Eon Reality Inc, Displair Inc, Proto Hologram, Holoxica Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Touchable Holographic Display Market Shifts & Advancements
Competitive positioning is fragmenting along the fault line between volume holography's spatial fidelity and digital holography's cost trajectory, with regulatory validation becoming the primary sorting mechanism for vendor survival.
Photopolymer-based digital holography is overtaking laser-etched volume holography in consumer electronics prototyping. Smartphone peripheral manufacturers in South Korea and Taiwan are adopting photopolymer film stacks for augmented reality accessories. The cost compression is forcing volume holography vendors to retreat into premium medical and defense niches where spatial precision commands procurement priority.
REACH substance restrictions are tightening feedstock availability for holographic recording materials across European manufacturing. The European Chemicals Agency's candidate list expansion targets halogenated photoinitiators used in high-resolution film emulsions. German and French display component suppliers are accelerating reformulation programs to maintain CE marking eligibility for medical device integration.
Hospital procurement committees are unbundling hardware acquisition from service contracts, shifting risk to vendors through performance-based maintenance agreements. Medical imaging departments in the United States now demand guaranteed uptime thresholds with penalty clauses for retinal projection system downtime. This compression of the traditional capital equipment sales cycle is favoring vendors with captive field service networks over pure-play hardware manufacturers.
Global Touchable Holographic Display Market Segmentation
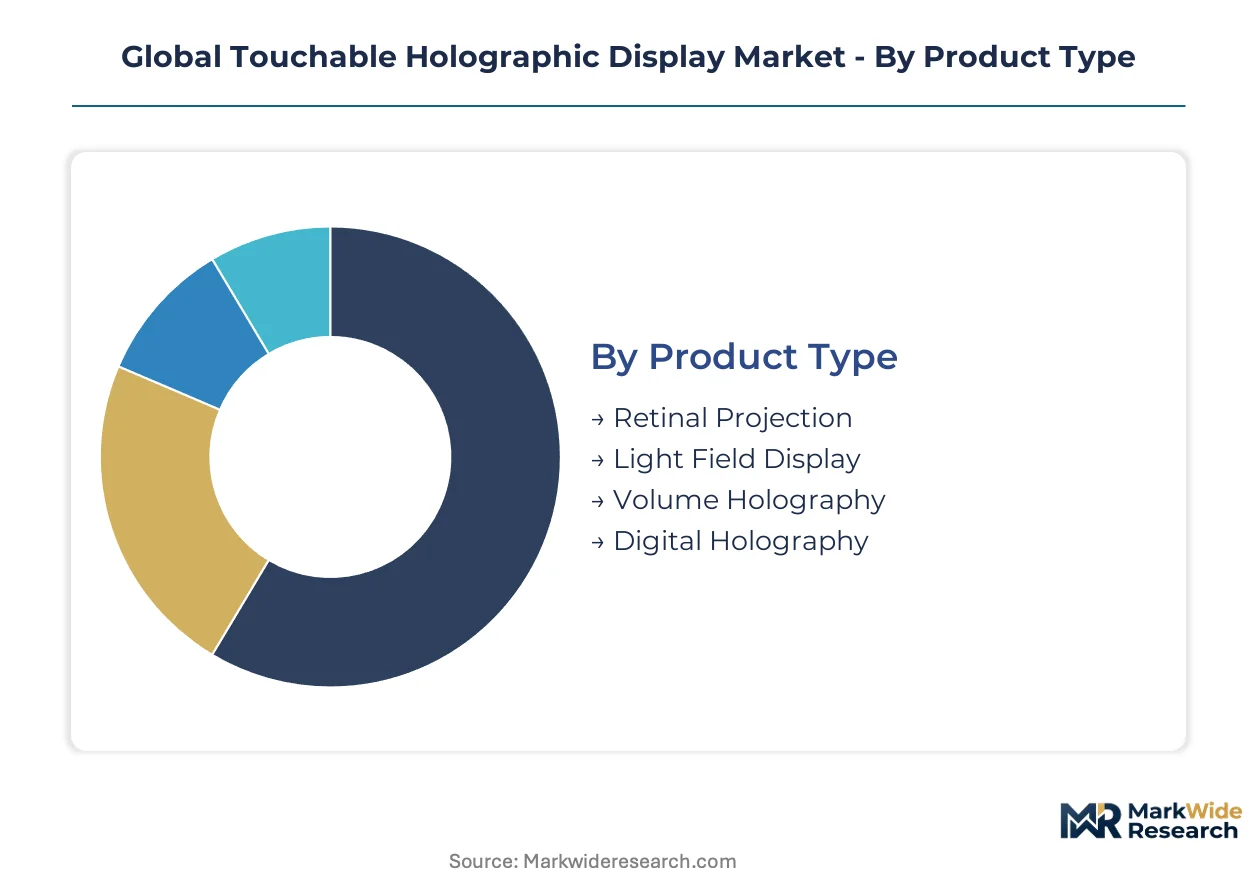
Product architecture in touchable holographic displays determines certification pathways and manufacturing scale. Segmentation reveals which technical configurations command premium pricing versus which face commoditization pressure from photopolymer cost volatility.
Product Type:
FDA 510(k) clearance requirements apply to retinal projection and volume holography installations in surgical settings, while digital holography faces lighter electromagnetic compatibility scrutiny for consumer electronics deployment.
- Retinal Projection:Projects imagery directly onto the viewer's retina through coherent light sources, eliminating physical display surfaces. United States hospital systems concentrate procurement in academic medical centers performing complex neurosurgical planning, where depth precision reduces operative time. FDA validation timelines stretch eighteen to twenty-four months for these installations.
- Volume Holography:Records interference patterns in photosensitive media to reconstruct full-parallax 3D imagery with superior spatial fidelity. Defense ministries in Japan and Germany fund fixed installations for volumetric mission rehearsal, insulating this segment from consumer electronics margin compression. Photopolymer supply constraints limit production scaling.
- Light Field Display:Arrays microlenses or pinholes to capture and reproduce directional light rays, enabling view-dependent perspective shifts without eyewear.
- Digital Holography:Computes interference patterns in real-time using spatial light modulators, trading spatial resolution for refresh rate flexibility and lower material costs.
Volume Holography sits at the top of the volume ranking, with Digital Holography climbing the fastest.
Technology:
Component selection dictates supply chain geography and intellectual property licensing burdens, with laser scanning and spatial light modulator sourcing concentrated in East Asian manufacturing clusters.
- Spatial Light Modulator:Liquid-crystal or micro-mirror arrays that modulate light phase and amplitude to generate dynamic holograms. Refresh rates exceeding 60 Hz stabilize imagery during manual contact, unlocking surgical applications previously limited to static holography. Japanese component suppliers dominate high-resolution device fabrication.
- Photopolymer:Light-sensitive organic matrices that record holographic interference patterns through refractive index changes. South Korean and Taiwanese smartphone peripheral manufacturers drive demand compression for augmented reality accessories. REACH substance restrictions in Europe constrain halogenated photoinitiator formulations.
- Laser Scanning:Rapidly steers coherent beams to construct volumetric imagery through persistence of vision in spinning or oscillating diffuse screens.
- Interferometry:Measures optical path differences to encode depth information, foundational to laboratory-grade hologram recording systems.
- Electro-Holography:Manipulates interference patterns through electrical signal processing for real-time computational holography.
Spatial Light Modulator captures the dominant revenue share, while Photopolymer expands most quickly in consumer-facing applications.
Use Case:
Application selection determines customer procurement authority and contract structure, with medical and defense buyers demanding performance-based maintenance agreements unavailable in consumer channels.
- 3D Modeling:Volumetric visualization enables direct manipulation of architectural and industrial designs in physical space without 2D interface abstraction. Germany's automotive design studios pilot supplier review workflows using software-defined hologram rendering. Procurement committees unbundle hardware from service contracts, shifting uptime risk to vendors.
- Virtual Conferencing:Remote participants appear as manipulable volumetric presences, reducing cognitive load from flat-screen video fatigue. Enterprise IT budgets in United States technology firms fund pilot deployments for executive briefing rooms. Bandwidth requirements constrain deployment to fiber-connected facilities.
- Augmented Reality:Overlays holographic information onto physical environments for maintenance guidance and spatial annotation.
- Interactive Advertising:Deploys touchable product visualizations in retail environments to extend dwell time and purchase conversion.
- Education:Presents manipulable molecular, anatomical, or mechanical models in classroom and museum settings.
3D Modeling leads in contract value per installation, with Virtual Conferencing gaining share fastest among enterprise buyers.
End User:
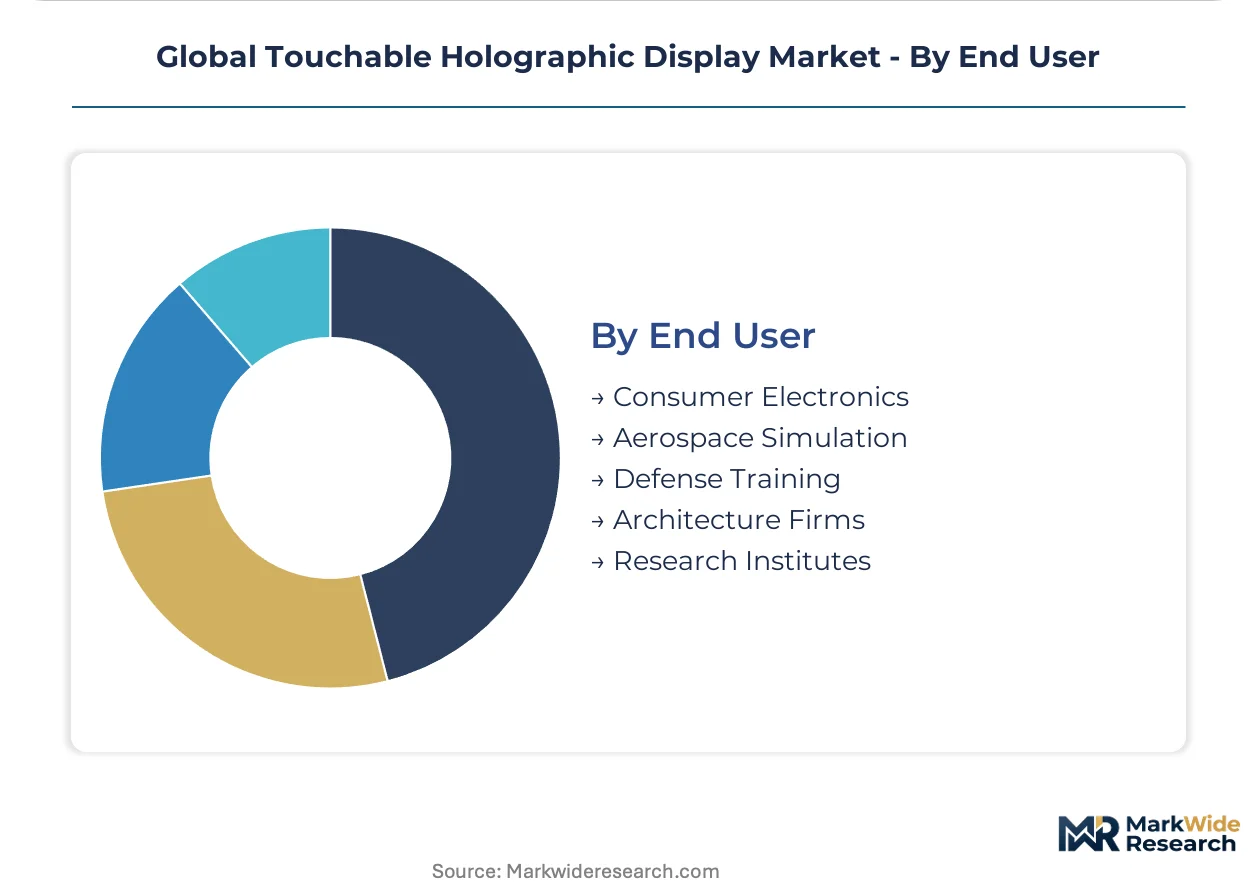
Customer category determines funding source stability and replacement cycle length, with defense and aerospace budgets insulating vendors from consumer electronics demand volatility.
- Defense Training:Volumetric mission rehearsal systems simulate operational environments for tactical decision-making without physical range constraints. United States, Japan, and Germany maintain dedicated procurement streams for classified simulation infrastructure. Light field printing technology addresses briefing requirements in allied nations lacking domestic holographic capability.
- Research Institutes:Electro-holography installations enable real-time interference pattern manipulation for optical physics and computational imaging research. Acute shortages of physicists capable of sub-millisecond optical computation constrain system utilization. Funding cycles align with national science foundation grant schedules.
- Consumer Electronics:Smartphone peripherals and home entertainment systems target mass-market price points through photopolymer cost reduction.
- Aerospace Simulation:Cockpit and maintenance training environments replicate instrument panels and mechanical systems in manipulable volumetric space.
- Architecture Firms:Design review and client presentation workflows substitute physical scale models with editable holographic alternatives.
Defense Training commands the highest average selling prices, with Research Institutes expanding most quickly through national digitization initiative funding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical physicists and computational imaging specialists concentrate in Boston, Stuttgart, and Osaka, anchoring regional R&D clusters where sub-millisecond holographic computation expertise commands premium compensation.
United States
Academic medical centers in Boston and Baltimore drive retinal projection procurement for neurosurgical planning. FDA 510(k) clearance timelines stretch eighteen to twenty-four months for these installations. The Greater Boston cluster hosts concentrated electro-holography research talent migrating from legacy display engineering.
Germany
Automotive design studios in Munich and Stuttgart pilot software-defined hologram rendering for supplier review workflows. EMA Medical Device Regulation compliance requirements shape hospital tender specifications across Bavaria and Baden-Württemberg. REACH substance restrictions are accelerating photopolymer reformulation programs in display component supply chains.
Japan
METI digitization initiatives directly fund holographic interface development, accelerating domestic hospital pilot programs in Tokyo and Osaka. PMDA consultation pathways for touch-force safety thresholds remain under development. The Kansai region concentrates spatial light modulator fabrication expertise from legacy consumer electronics supply chains.
South Korea
Smartphone peripheral manufacturers in Seoul and Suwon drive photopolymer demand compression for augmented reality accessories. The country's national technology regulator coordinates electromagnetic compatibility pre-certification with IEC standards. Display panel engineering talent from liquid-crystal manufacturing transitions into holographic component development.
United Kingdom
Research institutes in Cambridge and Oxford pursue real-time interference pattern manipulation for computational imaging applications. MHRA alignment with EMA Medical Device Regulation creates streamlined dual-market approval pathways. The Cambridge cluster attracts venture funding for holographic conferencing software ventures.
Global Touchable Holographic Display Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the touchable holographic display landscape. The vendor base organizes around three strategic archetypes: clinical-validated medical imaging specialists, defense-contracting volumetric hardcopy providers, and software-centric enterprise conferencing platforms. Consolidation pressure concentrates in the medical segment where FDA-compliant manufacturing lines require capital commitments exceeding pure-play hardware models. Dominant competitive moves include strategic partnerships with hospital procurement committees and technology licensing agreements for spatial light modulator intellectual property.
Within the clinical-validation tier, RealView Imaging Ltd exemplifies the medical imaging specialist archetype, while Zebra Imaging Inc occupies a position among defense-contracting providers of proprietary light field systems. MicroCloud Hologram Inc sits within the software-defined rendering segment, representing the asset-light platform approach. These three entities collectively illustrate the competitive fragmentation between hardware-intensive and software-centric market positions.
| Leading Market Players |
|---|
| RealView Imaging Ltd |
| Zebra Imaging Inc |
| MicroCloud Hologram Inc |
| Envisics Ltd |
| Kino-mo Ltd |
| Eon Reality Inc |
| Displair Inc |
| Proto Hologram |
| Holoxica Ltd |
| Others |
Supply & Pricing Matrix
Photopolymer feedstock costs cascade through three distinct pricing tiers, with halogenated photoinitiator formulations commanding premium positioning in European medical device integrations while photopolymer film stacks for augmented reality accessories compress toward commodity economics in South Korean smartphone peripheral manufacturing.
Pricing Analysis
The bundled-vs-unbundled service split separates capital equipment vendors from pure-play hardware manufacturers. Hospital procurement committees now unbundle retinal projection system acquisition from performance-based maintenance agreements, shifting uptime risk to vendors through penalty clauses for system downtime. Price differentiation centers on FDA 510(k) certification tier and captive field service network coverage. Pricing pressure stems from photopolymer cost volatility in consumer electronics segments. Defense training buyers exhibit lowest price sensitivity due to dedicated procurement streams, while consumer electronics manufacturers face acute margin compression.
Supply Chain Analysis
Workforce availability constraints in Japanese spatial light modulator fabrication and German photopolymer reformulation programs constrain component scaling. Supply concentration centers on Japan for liquid-crystal spatial light modulators, South Korea for photopolymer film stack manufacturing, and Taiwan for micro-mirror array production. Raw material dependencies include halogenated photoinitiators, specialty liquid-crystal polymers, and coherent light source diodes. Single-source vulnerability in high-resolution spatial light modulator devices creates procurement bottlenecks. Distribution runs through direct hospital procurement committees in medical segments and OEM channel partnerships in consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The touchable holographic display market compounds steadily as defense and medical budgets insulate hardware vendors from consumer electronics demand volatility.
For Market Incumbents: Extend clinical validation moats through FDA-compliant manufacturing line investments that emerging players cannot replicate. Deepen captive field service networks to capture performance-based maintenance contracts that hospital procurement committees now demand. Vertical integration into spatial light modulator fabrication reduces exposure to Japanese component supplier bottlenecks. Certification investment in EMA Medical Device Regulation alignment streamlines European hospital tender participation. For New Entrants and Emerging Players: Enterprise conferencing system integrators represent the most penetrable channel partner type for software-defined hologram rendering platforms. White-space targets include Germany's automotive design studios piloting supplier review workflows and United States technology firms funding executive briefing room deployments. A direct-to-hospital-IT go-to-market angle bypasses incumbent capital equipment sales cycles for digital holography segments. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA-compliant manufacturing lines require capital commitments exceeding pure-play hardware models. Long-term viability favors vendors with clinical validation moats and defense contract insulation. Acquisition target archetypes include electro-holography research institutes with sub-millisecond optical computation expertise. The signal to watch is which regulatory body first establishes touch-force safety thresholds for direct-contact volumetric displays.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Validates retinal projection systems for neurosurgical planning in academic medical centers. |
| Spatial Light Modulator Backward Integration | Captures Japanese liquid-crystal fabrication expertise within captive component supply. |
| Defense Contract Diversification | Insulates volume holography vendors from photopolymer cost volatility in consumer segments. |
| Software-Defined Rendering Platform | Enables remote volumetric collaboration for Germany's automotive design workflows. |
| EMA MDR Compliance Investment | Positions vendors for streamlined European hospital tender participation across Bavaria. |
Research Methodology
Coverage spans the United States, Japan, Germany, South Korea, and the United Kingdom, with primary inputs from each market cluster. The research combines primary interviews with hospital procurement managers, defense simulation officers, biomedical engineers, holographic display component suppliers, and enterprise IT directors with secondary validation. Secondary sources include FDA 510(k) filings, EMA Medical Device Regulation submissions, METI digitization initiative documentation, IEC electromagnetic compatibility standards, and hospital procurement database records. Bottom-up and top-down triangulation cross-validates segment sizing against component supplier shipment data and end-user installation tracking.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. The analytical framework models segmentation dimensions including product architecture, component technology, use case application, and end-user category alongside regional regulatory cluster differentiation. CAGRs derive from installed base growth rates, replacement cycle compression, and average selling price trajectory analysis. Industry-specific forecast inputs include spatial light modulator refresh rate advancement curves and photopolymer cost compression trajectories in consumer electronics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory touch-force safety threshold establishment and REACH substance restriction expansion. Forecasts reflect documented assumptions regarding defense budget continuity, hospital capital equipment replacement cycles, and electromagnetic compatibility certification timeline stability. Material deviation in FDA, EMA, or PMDA regulatory precedent warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Thin Display Technology Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
TPU Hydrogel Screen Protectors Market
Display Technologies
Display Material Market
Display Technologies
Global OLED Market
Display Technologies
Transparent Digital Signage Market
Display Technologies
Global Medical Display Market
Display Technologies
Portable Video Wall Market
Display Technologies
United States Microdisplay Market
Display Technologies
Quantum Dot Display Market
Display Technologies
Computer Monitor Market
Display Technologies
Global Display Market
Display Technologies
Seven Segment Display Market
Display Technologies
Electroluminescent Display Market
Display Technologies
PMOLED Display Market
Display Technologies
Paper-Thin Display Market