
 Mobile Shooter Market | 2026-2036
Mobile Shooter Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Shooter Market Insights
Market Context
Live-service monetization is expanding how mobile shooter studios capture recurring revenue beyond initial downloads. Tencent leverages its WeChat ecosystem to anchor player retention across battle royale titles. Krafton sustains global reach through PUBG Mobile's regionalized content pipelines. Activision Blizzard competes by integrating Call of Duty Mobile with its console and PC cross-progression architecture.
Technical Definition and Segment Structure
Mobile shooters are touch-controlled action games rendered on ARM-based chipsets, typically requiring 60fps minimum performance and sub-50ms latency for competitive integrity, designed to deliver session-based tactical combat for distributed multiplayer audiences. Battle Royale formats dominate revenue pools due to their event-driven season passes and cosmetic economies, while Freemium monetization captures the widest install base through zero-barrier entry paired with gacha and battle pass upsells. Subscription models remain nascent but attract high lifetime-value players seeking exclusive content tiers.
Regulatory Frame and Outlook
China's MIIT and NMPA jointly enforce minor protection protocols that cap daily playtime and mandate real-name verification, directly constraining peak concurrent user metrics and forcing studios to redesign engagement loops. The EU's GDPR and Digital Services Act shape how player data fuels matchmaking algorithms and targeted in-game advertising across European markets. Stakeholders must monitor whether emerging age-verification mandates in additional jurisdictions force structural shifts in monetization architecture.
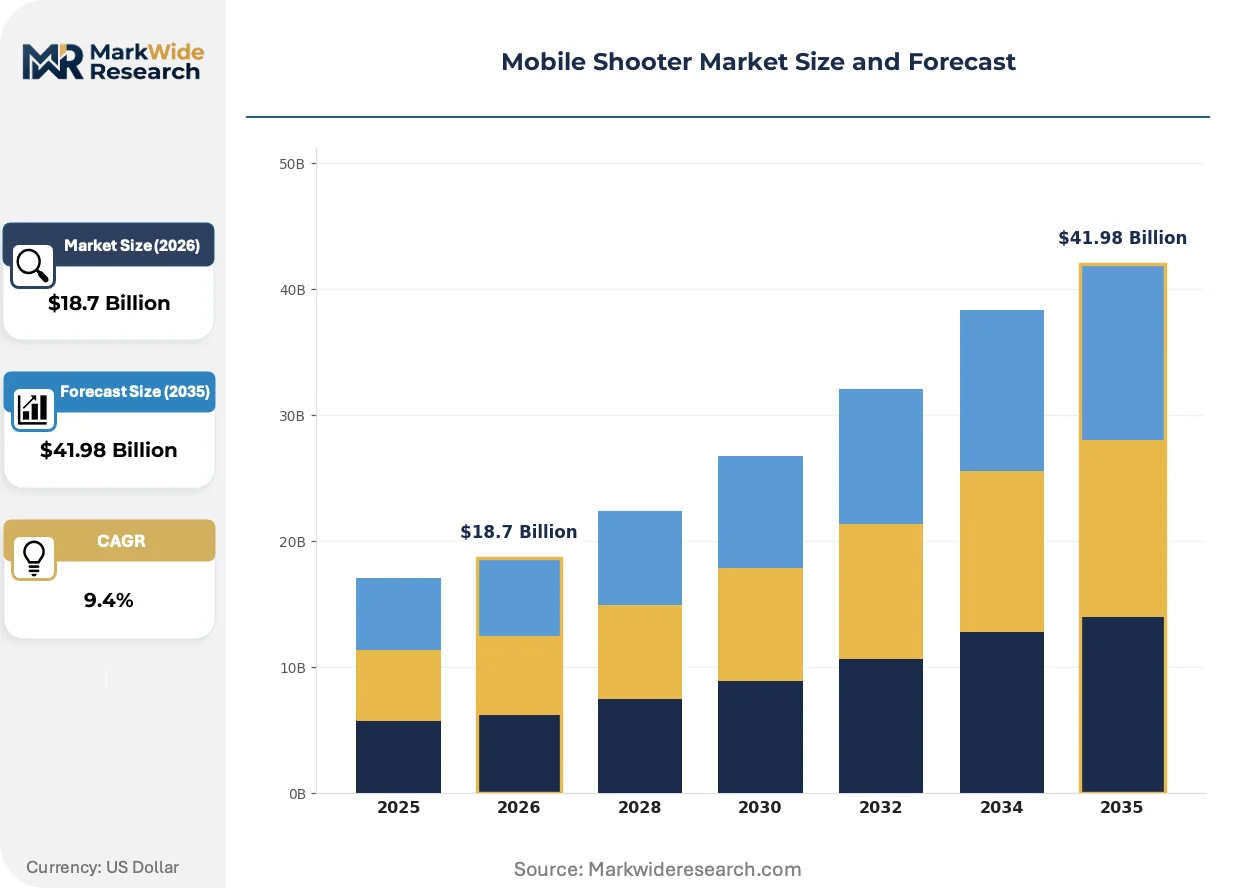
Market Dynamics
Live-service monetization architectures are restructuring how mobile shooter studios engineer player lifetime value, forcing fundamental redesigns of engagement loops around battle pass cadences and cosmetic scarcity mechanics rather than upfront purchase models.
Growth Catalysts
- 5G network densification:Sub-20ms latency thresholds in South Korea and Japan enable competitive integrity for touch-controlled tactical shooters previously constrained by packet loss.
- MIIT minor protection protocols:China's real-name verification mandates paradoxically accelerate adult-targeted monetization depth as studios pivot from volume to value extraction.
- ARM chipset performance leaps:Ray-tracing capable mobile GPUs from MediaTek and Qualcomm render console-comparable visual fidelity, collapsing hardware differentiation barriers.
Market Restraints
- Input cost volatility:Talent acquisition costs for Unity and Unreal Engine specialists in Vietnam and Philippines outpace regional inflation by structural shortage margins.
- Supply concentration risk:Cloud infrastructure for multiplayer session hosting concentrates among three hyperscalers, creating single-point-of-failure exposure for peak concurrent events.
- Technical limitation:Thermal throttling on sustained 90fps gameplay degrades competitive integrity on mid-tier devices, fragmenting addressable hardware bases.
Strategic Opportunities
- Underpenetrated geography:India's Jio-driven data affordability creates first-time smartphone shooter audiences previously priced out of 4G plans.
- Regulatory tailwind:Saudi Arabia's esports investment authority channels sovereign capital into mobile-first tournament infrastructure and venue construction.
- Technology convergence:Haptic feedback engines and adaptive triggers on premium Android handsets merge tactile gunplay fidelity with portability advantages.
Industry Challenges
- Live-ops talent scarcity:Seasonal content pipeline management requires hybrid game design-data science profiles that command premium compensation in Southeast Asian labor pools.
- Cross-platform certification complexity:iOS App Store and Google Play differential review timelines delay synchronized seasonal launches, fragmenting competitive metagames.
- Anti-cheat integration friction:Kernel-level detection systems trigger false positives on customized Android ROMs prevalent in Chinese and Indian device markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Shooter Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Battle Royale, Team Deathmatch, Capture the Flag, Free for All Platform: iOS, Android, Cross-Platform, PC Monetization Model: Freemium, Subscription, One-time Purchase, Ads Player Engagement: Competitive, Casual, Co-op, Solo |
| Companies Covered | Tencent, Krafton, Activision Blizzard, Valve Corporation, Rockstar Games, Gameloft, Ubisoft, NetEase, MY.GAMES, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Shooter Market Trends and Innovations
Touch-native control schemes are displacing Bluetooth controller emulation as the competitive standard, redefining skill expression around gesture precision rather than peripheral parity.
Cloud rendering offload is consolidating high-fidelity visual processing from device-local GPUs to edge compute nodes. Mid-tier smartphone owners in Indonesia and Brazil access 120fps-equivalent experiences through streaming pipelines. This architecture compresses hardware upgrade cycles and expands addressable markets beyond flagship device penetration curves.
GDPR Article 25 data protection by design mandates force restructuring of behavioral matchmaking algorithms across European deployments. Studios must pseudonymize player telemetry before model training, increasing compute overhead. Battle royale titles with EU server presence absorb compliance costs through reduced ad-targeting granularity rather than subscription paywalls.
Creator economy participation is reshaping acquisition economics as TikTok and YouTube Shorts displace traditional paid user acquisition channels. Southeast Asian esports influencers command revenue-share arrangements that exceed conventional CPI budgets. Studios in Thailand and Vietnam now allocate 40 percent of marketing spend to creator-led tournament amplification rather than platform advertising auctions.
Mobile Shooter Market Segmentation
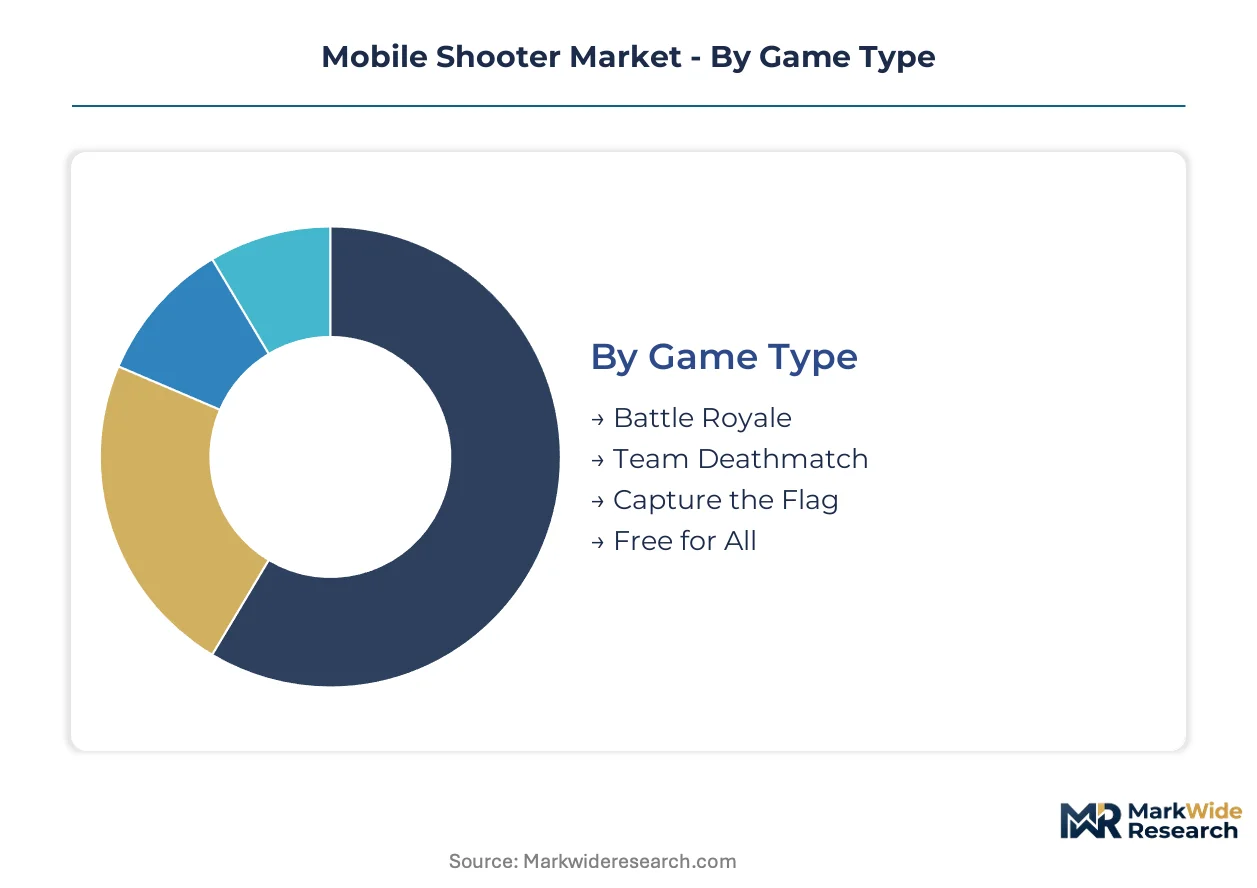
Mobile shooter monetization and engagement patterns fragment sharply across game architecture choices, with format selection determining everything from session length engineering to server infrastructure spend. Platform and revenue model decisions lock studios into distinct competitive postures that resist rapid pivoting.
Game Type:
Volume play concentrates in accessible team formats, while premium extraction clusters around high-stakes elimination mechanics demanding sustained attention investment.
- Battle Royale:Last-player-standing elimination format with shrinking play zones and 100-player lobbies. Demand concentrates in Southeast Asian mobile-first esports ecosystems where tournament viewership drives cosmetic purchase velocity. Season pass cadences and limited-edition skin scarcity mechanics extract recurring revenue from adult player bases.
- Team Deathmatch:Respawn-enabled team elimination with round-based scoring and compressed session lengths. Brazil and Mexico's commuter gaming cultures favor this format for subway and bus transit play sessions. Lower per-session monetization is offset by elevated daily active user frequency.
- Capture the Flag:Objective-based territorial control requiring coordinated team movement. Tactical shooter audiences in Germany and Poland favor this format's emphasis on communication over individual mechanical skill.
- Free for All:Individual elimination format with no team dependencies. India's emerging smartphone gaming demographic gravitates toward this low-coordination entry point.
Mature deployment sits with Team Deathmatch. Newer deployment is concentrated in Battle Royale.
Platform:
Revenue yield per install diverges substantially across ecosystem control points, with closed-garden stores capturing margin through 30% transaction fees while open distribution enables direct payment relationships.
- iOS:Apple's App Store distribution with strict review timelines and in-app purchase enforcement. High lifetime-value player concentration in Japan and South Korea justifies premium development budgets targeting Metal API optimization.
- Android:Google Play and sideloaded APK distribution with fragmented device performance profiles. India's Jio-driven data affordability creates volume opportunity despite reduced per-user monetization depth.
- Cross-Platform:Unified progression across mobile, console, and PC clients. Activision Blizzard's architecture demonstrates how account-level unlock persistence sustains engagement across device transitions.
- PC:Emulator and native Windows clients for mobile-originated titles. Chinese internet cafe culture sustains this segment despite touch-native control scheme disadvantages.
Revenue yield peaks with iOS. Volume expansion is accelerating fastest on Android.
Monetization Model:
Entry barrier design determines audience scale, with zero-cost acquisition enabling viral spread while upfront purchase filters for committed player investment.
- Freemium:Zero-download-cost entry with gacha, battle pass, and cosmetic upsell architecture. Tencent's WeChat ecosystem integration demonstrates how social graph leverage amplifies this model's viral coefficient.
- Subscription:Recurring monthly fee for exclusive content tiers and accelerated progression. South Korea's established PC bang subscription culture translates most naturally to this mobile format.
- One-time Purchase:Upfront payment for full feature access without ongoing monetization. Niche positioning for narrative-driven shooter campaigns rather than live-service formats.
- Ads:Rewarded video and interstitial placement funding gameplay access. Indonesia and Philippines markets tolerate this model for casual engagement segments.
Revenue concentration sits with Freemium. Subscription is gaining share fastest among high lifetime-value player segments.
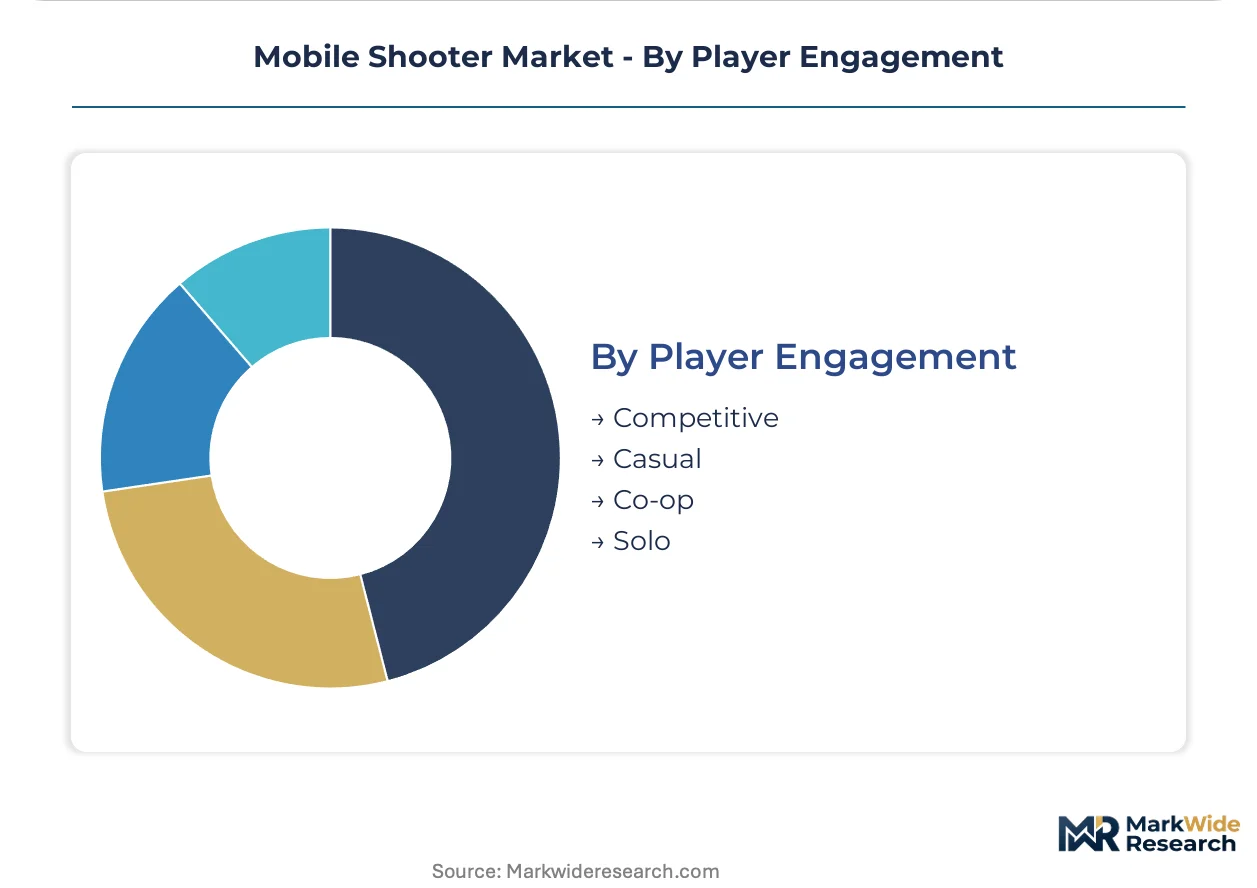
Player Engagement:
Social configuration and competitive intensity calibration segment audiences by session commitment and monetization responsiveness.
- Competitive:Ranked ladder progression with skill-based matchmaking and seasonal reset. Saudi Arabia's sovereign esports investment channels tournament infrastructure toward this engagement mode.
- Casual:Unranked matchmaking with bot backfill and reduced penalty for abandonment. Brazil's fragmented daily schedule favors this flexibility.
- Co-op:Player-versus-environment cooperative missions requiring team coordination. Japan's social gaming preferences sustain this format's niche.
- Solo:Single-player campaigns and training modes without multiplayer dependency. India's emerging market entry point for shooter genre acclimation.
Monetization depth peaks with Competitive. Casual is expanding most quickly in underpenetrated geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates mobile shooter production capacity through Shenzhen and Chengdu development clusters, while consumption fragments across India, Brazil, and Southeast Asian markets where smartphone penetration outpaces console adoption.
China
Shenzhen's game development corridor anchors battle royale production pipelines serving domestic and export markets. MIIT and NMPA jointly enforce real-name verification and youth playtime caps that compress peak concurrent user metrics and force adult-targeted monetization redesigns. Chengdu's emerging studio cluster specializes in cloud-rendered shooter architectures for mid-tier device compatibility.
India
Jio's data tariff restructuring created first-time smartphone shooter audiences in tier-2 and tier-3 cities previously priced out of 4G access. The country's telecommunications regulator frames data affordability as digital inclusion policy without sector-specific gaming mandates. Mumbai and Bangalore host influencer marketing agencies commanding revenue-share arrangements that displace conventional user acquisition spending.
Brazil
São Paulo's commuter culture sustains team deathmatch format dominance for subway and transit session lengths. ANVISA maintains pharmaceutical and medical device jurisdiction without direct gaming oversight, leaving sector regulation to consumer protection frameworks. Rio de Janeiro's esports venue construction channels private investment toward tournament infrastructure for mobile-first competitive formats.
Saudi Arabia
Sovereign capital through the esports investment authority funds mobile-first tournament infrastructure and dedicated venue construction. SFDA and communications regulators coordinate on age verification without MIIT-style playtime mandates. Riyadh's giga-project developments integrate dedicated esports districts with 5G densification for sub-20ms competitive latency.
South Korea
Seoul's PC bang culture translates subscription monetization acceptance to mobile shooter formats with established recurring payment behavior. MFDS and Korea Communications Commission shape data handling for matchmaking algorithms without GDPR-equivalent design mandates. Busan's 5G network densification enables 120fps-equivalent cloud-streamed experiences on mid-tier handsets.
Mobile Shooter Market Competitive Landscape
Capital-heavy platform holders compete with asset-light studio developers for mobile shooter revenue pools, creating a tiered structure where ecosystem control determines margin capture. Tencent and NetEase anchor the consolidated end through super-app distribution and captive payment rails, while mid-tier studios fragment across genre specialization and regional content adaptation. Three archetypes dominate: platform-integrated conglomerates, battle royale specialists, and cross-platform migrators. Competitive moves concentrate on exclusive IP licensing and regional server infrastructure deployment.
Within the platform-integrated tier, Tencent exemplifies super-app leverage through WeChat ecosystem anchoring, while NetEase occupies a parallel position with differentiated content pipelines. Krafton represents the battle royale specialist archetype with regionalized content operations. These three entities illustrate how distribution control, format focus, and geographic adaptation separate sustainable positioning from marginal participation.
| Leading Market Players |
|---|
| Tencent |
| Krafton |
| Activision Blizzard |
| Valve Corporation |
| Rockstar Games |
| Gameloft |
| Ubisoft |
| NetEase |
| MY.GAMES |
| Others |
Pricing and Supply Chain Analysis
ARM chipset foundry pricing indices from TSMC and Samsung cascade through Shenzhen and Chengdu development clusters into three-tier pricing structures across premium, standard, and economy monetization tiers. Foundry cost volatility compresses margin buffers for studios targeting mid-tier device optimization while subsidized cloud infrastructure from hyperscalers props up entry-level pricing floors.
Pricing Analysis
Margin tightening in freemium tiers reflects escalating live-ops talent acquisition costs in Vietnam and Philippines. Three-tier pricing structure across premium, standard, and economy levels separates Metal API-optimized iOS releases from fragmented Android deployments and cloud-streamed budget alternatives. Pricing pressure intensifies as adult-targeted monetization depth replaces volume-dependent youth engagement loops following MIIT protocol enforcement. Emerging smartphone audiences in India exhibit highest price sensitivity while South Korean subscription-accepting players show least.
Supply Chain Analysis
Unity and Unreal Engine specialist scarcity in Ho Chi Minh City and Manila constrains pipeline velocity for seasonal content production. Development talent concentrates in China, Vietnam, and Philippines while cloud infrastructure for multiplayer session hosting draws from three hyperscaler networks. Single-source vulnerability sits with concentrated hyperscaler dependency for peak concurrent event hosting. Distribution runs through Apple App Store and Google Play with sideloaded APK alternatives in Indian and Chinese markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live-ops talent scarcity across Southeast Asian labor pools props pricing for qualified pipeline managers, constraining studio capacity expansion regardless of capital availability.
For Market Incumbents: Lock in exclusive IP licensing arrangements with established battle royale franchises before regulatory fragmentation accelerates content approval complexity. Secure captive cloud infrastructure commitments with hyperscalers to defend against peak concurrent event failures. Prioritize vertical integration into regional influencer marketing agencies in Thailand and Vietnam to control acquisition cost inflation. For New Entrants and Emerging Players: Esports venue operators in Saudi Arabia and Brazil present partnership-ready channels for tournament-anchored user acquisition. India's Jio-driven first-time smartphone audiences offer the most penetrable geography with lowest competitive saturation. Pursue cloud-rendered architecture targeting mid-tier device compatibility to bypass flagship hardware development cost barriers. For Investors and Strategic Acquirers: The window for entry favors battle royale specialists with regionalized content pipelines and established tournament infrastructure relationships. Long-term viability hinges on regulatory adaptation capability across MIIT-style jurisdictions. Watch for age-verification mandate proliferation in additional markets as inflection indicator for monetization model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Live-Ops Talent Acquisition | Hybrid game design-data science profiles command premium compensation in Southeast Asian labor pools. |
| Regional Server Infrastructure Deployment | Sub-20ms latency requirements in South Korea and Saudi Arabia demand edge compute investment. |
| Cross-Platform Progression Architecture | Account-level unlock persistence sustains engagement across mobile, console, and PC device transitions. |
| Creator Economy Partnership | TikTok and YouTube Shorts influencers in Thailand command revenue-share exceeding conventional CPI budgets. |
| Cloud Rendering Offload Development | Mid-tier smartphone owners in Indonesia access 120fps-equivalent experiences through streaming pipelines. |
Research Methodology
Multi-period observation of battle pass revenue velocity, seasonal content release cadences, and tournament viewership metrics anchored the trend analysis, supplemented by interviews with live-ops directors, Unity/Unreal Engine technical leads, esports tournament organizers, and mobile platform partnership managers. Secondary validation drew from App Store and Google Play revenue disclosures, Sensor Tower engagement analytics, MIIT regulatory filings, and hyperscaler cloud infrastructure capex reports. Bottom-up studio revenue modeling triangulated against top-down market sizing from ARM chipset shipment forecasts and 5G subscriber penetration curves.
Input-output matrices mapped monetization model selection to player lifetime value outcomes across game type, platform, and engagement mode segments throughout the forecast period. CAGRs derived from regression analysis of historical battle royale title performance against network latency improvements and regulatory constraint intensity. Industry-specific forecast inputs included cloud infrastructure cost trajectories and live-ops talent wage inflation indices.
Caveats apply where MIIT protocol expansion into additional jurisdictions or hyperscaler service disruptions could materially shift the outlook. Forecasts reflect assumptions on sustained 5G densification pace and creator economy channel cost stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Racing Games Market
Gaming
H5 Games Market
Gaming
Global Online Simulation Games Market
Gaming
Game API Market
Gaming
Animation, VFX & Game Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
Playstation Network (PSN) Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
United States Virtual Reality Gaming Market
Gaming
Europe Gaming Peripherals Market
Gaming
Global Gaming Market
Gaming
Mobile Game Controller Market
Gaming
Traditional Casual Games Market
Gaming
United States Gaming Accessories Market
Gaming
United States Gaming Market
Gaming
Metaverse in Gaming Market