
 Japan Virtual Reality Gaming Market | 2026-2036
Japan Virtual Reality Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Virtual Reality Gaming Market Intelligence
Multi-source content development is consolidating around Japan's established game publishers. Sony Interactive Entertainment leverages its PlayStation VR ecosystem to anchor hardware-software integration. Bandai Namco Holdings Inc. specializes in location-based VR attractions across Tokyo and Osaka entertainment districts. Nintendo Co., Ltd. competes through its hybrid platform strategy, though its VR exposure remains more selective than peers.
Japan Virtual Reality Gaming encompasses immersive digital entertainment delivered through head-mounted displays with stereoscopic rendering, motion tracking, and haptic feedback systems operating at 90-120 Hz refresh rates to minimize latency-induced discomfort. The technology serves commercial entertainment venues, residential consumers, and enterprise simulation applications requiring spatial presence. Standalone headsets lead volume adoption by eliminating PC tethering complexity for casual users. PC-based systems capture the premium performance tier where developer studios demand higher fidelity rendering for competitive esports and simulation training. Software represents the fastest-expanding margin pool as recurring content monetization outpaces hardware replacement cycles.
METI's digital transformation subsidies shape domestic studio investment in VR content pipelines. JIS standards for electromagnetic compatibility and eye safety govern headset certification requirements for consumer sale. PMDA oversight applies where medical-grade VR applications blur into wellness gaming categories. Stakeholders must monitor how METI's next funding rounds allocate between hardware manufacturing incentives and pure content creation grants.
Market Dynamics
METI's digital transformation subsidies are concentrating investment around Osaka and Tokyo developer clusters, pulling procurement decisions toward domestic content pipelines rather than imported hardware ecosystems.
Growth Catalysts
- Enterprise Training Demand:Corporate simulation programs in Osaka and Tokyo are accelerating headset procurement for safety and technical skill development.
- METI Subsidy Framework:Domestic content production grants are channeling studio investment toward location-based entertainment systems.
- Standalone Headset Technology:Wireless form factors eliminating PC tethering are expanding the casual user base beyond enthusiast segments.
Market Restraints
- Display Panel Supply Concentration:Premium OLED microdisplay sourcing depends on concentrated Asian manufacturing clusters, creating input volatility.
- JIS Certification Friction:Electromagnetic compatibility and eye safety standards extend hardware approval timelines for consumer launch.
- Motion Sickness Technical Limitation:Latency-induced discomfort persists below 90 Hz refresh thresholds, constraining session duration for sensitive users.
Strategic Opportunities
- Fukuoka-Nagoya Corridor:Underpenetrated regional entertainment districts offer white space for location-based VR attraction deployment.
- Medical-Wellness Convergence:PMDA oversight boundaries create regulatory clarity for therapeutic gaming applications targeting rehabilitation centers.
- Cloud Rendering Integration:Edge computing infrastructure is absorbing computational load from local hardware, enabling lighter headset designs.
Industry Challenges
- Spatial Computing Talent Gap:Developer studios face scarcity of engineers proficient in stereoscopic rendering and haptic feedback integration.
- Legacy Arcade Infrastructure:Existing location-based entertainment venues require substantial capex for motion platform and tracking system retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Virtual Reality Gaming Market |
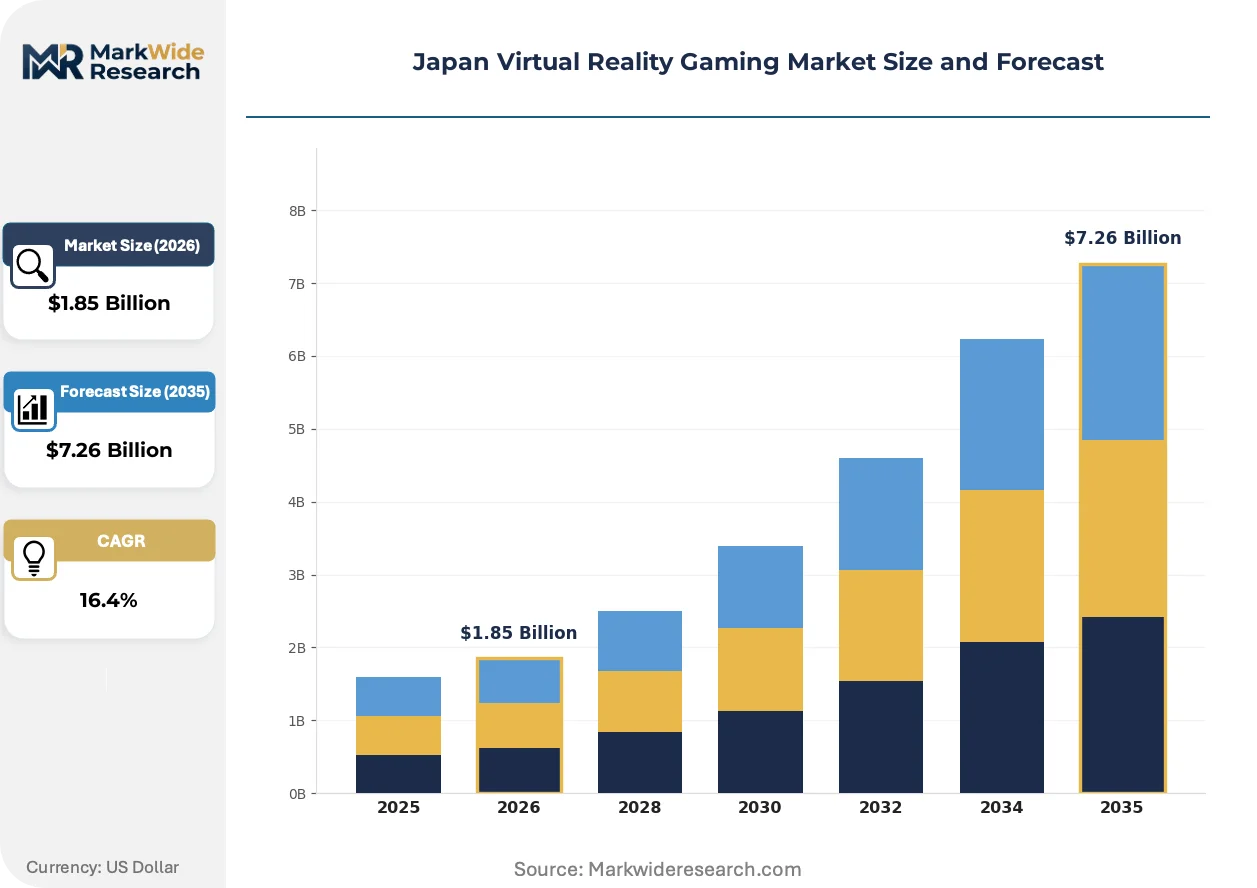
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Standalone, PC-based, Console-based, Mobile Product Type: Headsets, Controllers, Accessories, Software End User: Gamers, Enterprises, Educators, Developers Distribution Channel: Online Retail, Offline Retail, Direct Sales, B2B |
| Companies Covered | Capcom Co., Ltd., Sega Sammy Holdings Inc., Sony Interactive Entertainment, Koei Tecmo Holdings Co., Ltd., Konami Holdings Corporation, Nintendo Co., Ltd., Square Enix Holdings Co., Ltd., Cygames, Bandai Namco Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Virtual Reality Gaming Market Strategic Shifts & Innovations
Japanese VR gaming is absorbing three concurrent shifts: hardware untethering, regulatory clarity around wellness applications, and enterprise procurement displacing consumer-led demand cycles.
Foveated rendering is absorbing GPU computational load by reducing peripheral pixel density. Developer studios in Tokyo are adopting this technique to maintain visual fidelity on standalone chipsets. The technology is absorbing the historical trade-off between portability and performance, compressing the premium-performance tier toward mid-range price points.
METI's funding allocation criteria are tightening around domestic content IP ownership. Studios must demonstrate in-house narrative development to qualify for production grants. The policy is concentrating investment around established publishers with captive creative teams, disadvantaging pure-hardware import distributors.
Enterprise procurement committees are displacing individual consumer purchases as the dominant demand signal. Corporate training divisions in Osaka are issuing multi-year headset leases with bundled content subscriptions. This pattern is most visible in manufacturing and logistics verticals where simulation training reduces physical equipment wear.
Japan Virtual Reality Gaming Market Segmentation
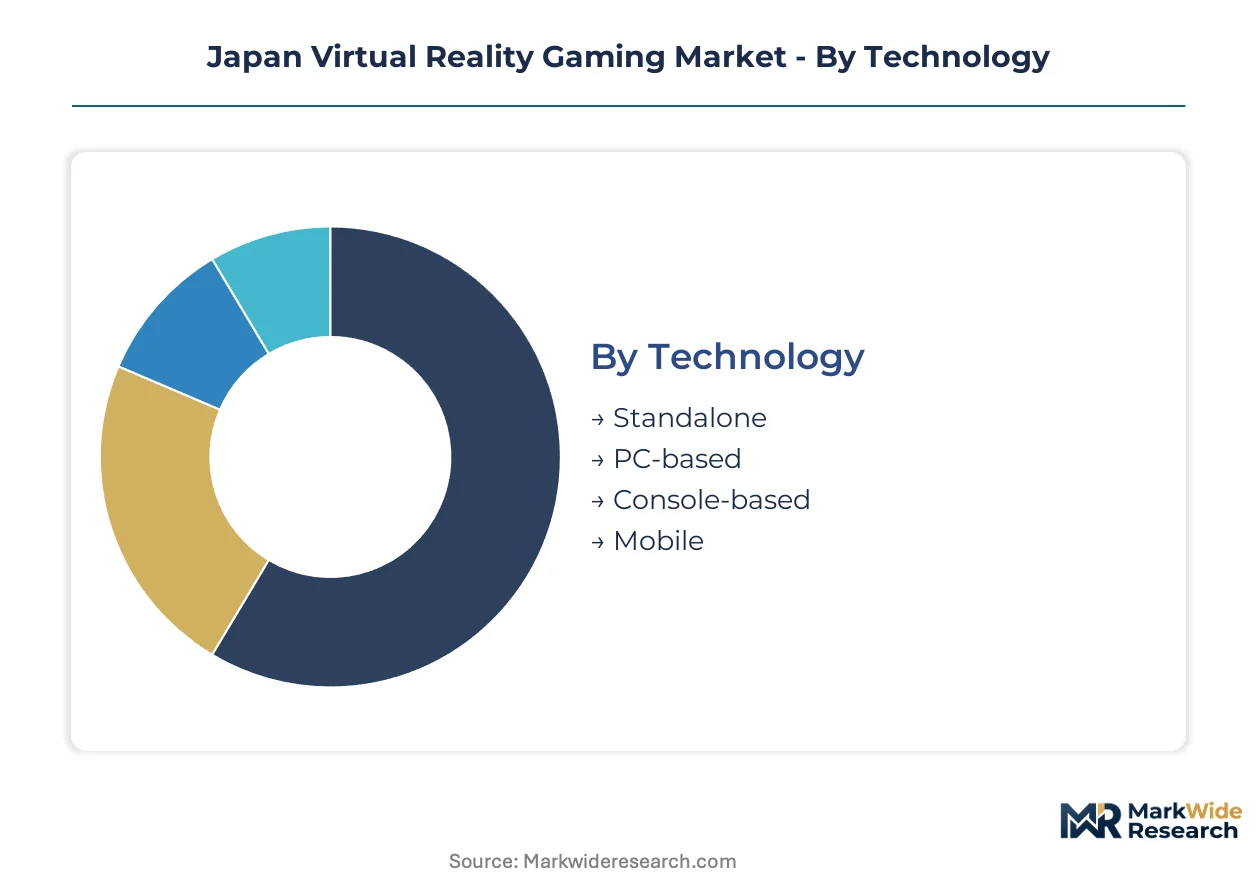
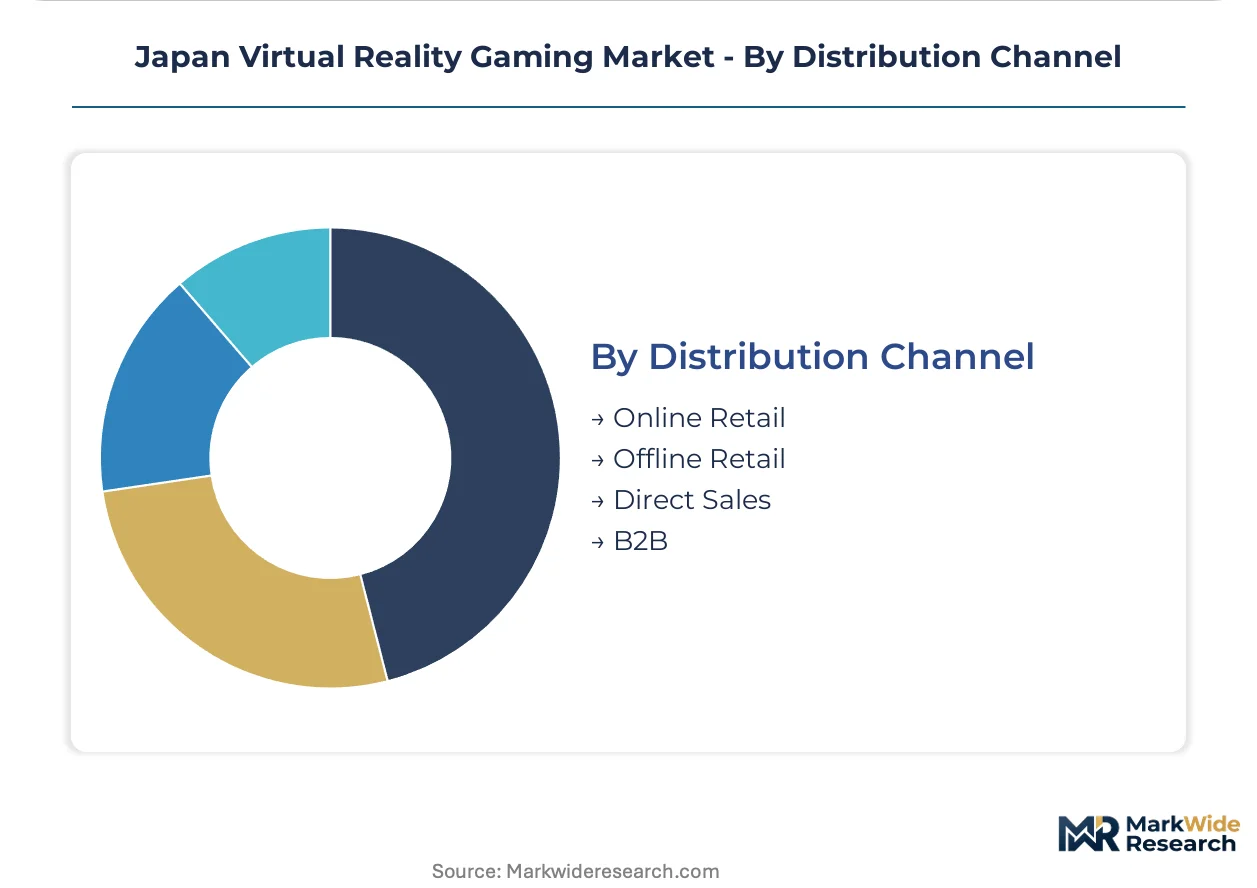
Segmentation in Japan's VR gaming market reveals how procurement authority shifts between consumer retail channels and enterprise B2B contracts. Technology choices determine whether studios target location-based venues or residential users. Product mix and distribution strategy together dictate margin capture and customer lifetime value.
Technology:
Capital intensity varies sharply across technology tiers, with PC-based systems demanding the highest upfront hardware investment while standalone units minimize peripheral ecosystem costs.
- Standalone:Wireless headsets integrate processing, display, and battery into a single wearable unit operating on Qualcomm Snapdragon XR platforms. Demand concentrates among casual consumers in Tokyo residential districts where space constraints eliminate PC setup requirements; METI subsidies for domestic content production indirectly support this segment through software ecosystem investment.
- PC-based:Tethered configurations leverage discrete GPUs for 90-120 Hz rendering with sub-20ms motion-to-photon latency. Osaka enterprise training centers and competitive esports venues absorb the bulk of procurement volume; the segment commands premium pricing where simulation fidelity determines training outcomes.
- Console-based:PlayStation VR ecosystem anchors this tier with proprietary hardware-software integration.
- Mobile:Smartphone-dependent viewers represent the lowest entry cost tier with limited immersion depth.
PC-based systems absorb the bulk of installed capacity in enterprise settings; standalone is expanding most quickly among residential consumers.
Product Type:
Margin structure inverts between hardware replacement cycles and recurring software monetization, with accessories capturing aftermarket upgrade spending.
- Headsets:Optical systems combine Fresnel or pancake lenses with OLED microdisplays achieving 110-degree field-of-view. Location-based entertainment operators in Osaka and Tokyo prioritize durability-rated units for high-frequency commercial use; JIS eye safety certification extends approval timelines for consumer launches.
- Software:Content spans native applications, cloud-rendered streaming titles, and enterprise training modules. Developer studios building location-based attractions in Fukuoka-Nagoya corridor cities drive demand; METI digital transformation grants channel investment toward domestically-owned IP.
- Controllers:Hand-tracking peripherals with haptic feedback enable spatial interaction.
- Accessories:Charging docks, carrying cases, and lens protection films complete the ecosystem.
Headsets dominate current revenue volume; software claims the steepest expansion trajectory as subscription models displace perpetual licenses.
End User:
Procurement decision-making authority separates individual purchasers from committee-driven enterprise acquisitions with multi-year contract horizons.
- Enterprises:Corporate training divisions in manufacturing and logistics verticals issue multi-year headset leases with bundled content subscriptions. Osaka-based heavy industry firms drive safety simulation demand; procurement committees prioritize total cost of ownership over hardware specifications alone.
- Developers:Content creation studios require dev-kit hardware, middleware licenses, and testing environments. Tokyo clusters concentrate investment where METI subsidies require demonstrated in-house narrative capability; talent scarcity in stereoscopic rendering constrains studio scaling.
- Gamers:Individual consumers purchasing for residential entertainment use.
- Educators:Schools and vocational institutions deploying VR for immersive instruction.
Enterprises absorb the bulk of current procurement volume; developers are climbing the fastest as METI funding concentrates around domestic content pipelines.
Distribution Channel:
Channel selection determines whether vendors capture end-user relationships directly or cede margin to retail intermediaries with localized inventory risk.
- B2B:Direct enterprise sales with dedicated account management and field engineering support. Manufacturing and logistics training programs in Osaka procure through multi-year equipment leases; bundled content subscriptions extend vendor relationships beyond hardware replacement cycles.
- Online Retail:E-commerce platforms with nationwide fulfillment and comparison shopping functionality. Residential consumers in Tokyo peripheral wards favor this channel for standalone headset purchases; return policies mitigate motion sickness compatibility risk for first-time buyers.
- Direct Sales:Manufacturer-owned channels for flagship product launches.
- Offline Retail:Electronics retailers and specialty gaming stores with demonstration stations.
B2B channels absorb the bulk of contract value; online retail is gaining share fastest as standalone form factors reduce pre-purchase demonstration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display panel fabrication clusters in Kyushu and semiconductor packaging facilities in the Tohoku region supply critical headset components for Japan's VR gaming hardware ecosystem.
Kanto/Tokyo
Corporate training divisions in Tokyo's Minato and Shibuya wards drive enterprise headset procurement for safety simulation programs. METI's digital transformation subsidies channel studio investment toward domestic content pipelines. Developer clusters in Shinjuku and Akihabara concentrate location-based entertainment system production.
Kansai/Osaka
Heavy industry firms in Osaka's manufacturing belt absorb PC-based systems for technical skill development simulations. JIS certification requirements for electromagnetic compatibility govern hardware approval timelines for consumer launches. Entertainment districts in Dotonbori and Umeda anchor location-based VR attraction deployment.
Chubu/Nagoya
Automotive supply chain companies in Aichi Prefecture procure standalone headsets for logistics training applications. PMDA oversight boundaries create regulatory clarity where medical-grade VR applications intersect with wellness gaming categories. Nagoya's industrial engineering base supports motion platform retrofitting for legacy arcade infrastructure.
Kyushu
OLED microdisplay manufacturing facilities in Kumamoto and Fukuoka Prefectures supply premium panel components for high-refresh-rate headsets. The country's national industrial standards body governs eye safety specifications for consumer sale. Fukuoka's startup ecosystem is absorbing cloud rendering infrastructure investment for lighter headset designs.
Hokkaido
Tourism operators in Sapporo and Niseko test seasonal VR entertainment installations for winter resort visitors. METI regional development grants support content studios expanding beyond Tokyo-Osaka corridors. Sapporo's emerging tech cluster faces spatial computing talent scarcity constraining studio scaling.
Japan Virtual Reality Gaming Market Key Industry Players
Strategic partnerships dominate the current landscape as publishers anchor hardware-software integration. The market structure concentrates around established game publishers with captive creative teams and proprietary platform ecosystems. Three archetypes define competitive positioning: platform-integrated publishers controlling hardware-software stacks, location-based entertainment specialists deploying physical attractions, and hybrid platform strategists with selective VR exposure. Portfolio diversification and technology licensing represent the dominant competitive moves as studios defend margin positions against hardware import distributors.
Within the platform-integrated tier, Sony Interactive Entertainment exemplifies hardware-software ecosystem control. Among diversified entertainment conglomerates, Sega Sammy Holdings Inc. and Bandai Namco Holdings Inc. occupy positions spanning location-based attractions and residential software. Nintendo Co., Ltd. represents the hybrid platform archetype with selective VR engagement relative to peers. These entities anchor competitive dynamics as METI subsidy criteria tighten around domestic IP ownership requirements.
| Leading Market Players |
|---|
| Capcom Co., Ltd. |
| Sega Sammy Holdings Inc. |
| Sony Interactive Entertainment |
| Koei Tecmo Holdings Co., Ltd. |
| Konami Holdings Corporation |
| Nintendo Co., Ltd. |
| Square Enix Holdings Co., Ltd. |
| Cygames |
| Bandai Namco Holdings Inc. |
| Others |
Cost & Logistics Intelligence
Enterprise training committees in Osaka and Tokyo dominate procurement volume, locking in multi-year equipment leases with bundled content subscriptions that compress upfront hardware margins while extending vendor relationships across replacement cycles.
Pricing Analysis
Warranty and field engineering support bundles separate enterprise B2B contracts from stripped-down consumer retail transactions. Three-tier pricing structure across premium PC-tethered systems, mid-range standalone units, and entry-level mobile viewers reflects performance fidelity and certification grade. Cost compression in the standalone tier is intensifying because Qualcomm Snapdragon XR platform commoditization erodes chipset differentiation. Residential consumers in Tokyo peripheral wards exhibit highest price sensitivity, while Osaka manufacturing training divisions prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Reverse-logistics flows for enterprise headset refurbishment and motion platform component remanufacturing create secondary supply channels extending hardware lifecycles. OLED microdisplay fabrication concentrates in South Korea and Japan, with semiconductor packaging feeding from Taiwan and USA facilities. Premium lens assemblies and haptic feedback actuators draw from established Japanese precision manufacturing clusters. Single-source vulnerability in OLED microdisplay supply creates procurement risk for high-refresh-rate headset production. Distribution runs through direct B2B enterprise sales with dedicated account management, supplemented by online retail for residential standalone purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OLED microdisplay foundry capacity constraints prop pricing power for premium headset tiers, creating supply-constrained conditions that favor vendors with captive component sourcing or long-term foundry agreements.
For Market Incumbents: Hedge against standalone chipset commoditization by deepening backward integration into optical system design and motion tracking sensor production. Secure multi-year enterprise training contracts in Osaka manufacturing verticals before competitive esports venues absorb available PC-based system capacity. METI subsidy criteria tightening around domestic IP ownership threatens pure-hardware import distributors with margin compression. For New Entrants and Emerging Players: Begin with location-based entertainment deployment in the Fukuoka-Nagoya corridor where legacy arcade infrastructure retrofit demand outpaces established publisher capacity. Target automotive supply chain training applications in Aichi Prefecture with standalone headset solutions bundled to logistics simulation content. Pursue direct B2B sales with field engineering support rather than retail channel competition against Sony and Bandai Namco ecosystems. For Investors and Strategic Acquirers: The window for entry favors developer studios with demonstrated in-house narrative capability qualifying for METI production grants. Long-term viability hinges on content IP ownership rather than hardware distribution rights. Monitor PMDA regulatory clarity boundaries around medical-wellness convergence applications as inflection signal for therapeutic gaming category expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content IP Development | METI subsidy qualification requires in-house narrative capability, concentrating investment around established publishers. |
| Enterprise Training Partnership | Osaka manufacturing and logistics verticals issue multi-year headset leases with bundled content subscriptions. |
| Location-Based Entertainment Deployment | Fukuoka-Nagoya corridor cities offer white space for VR attraction deployment beyond Tokyo-Osaka saturation. |
| Cloud Rendering Infrastructure Investment | Fukuoka startup ecosystem absorbs edge computing investment enabling lighter standalone headset designs. |
| Medical-Wellness Regulatory Navigation | PMDA oversight boundaries create clarity for therapeutic gaming applications targeting rehabilitation centers. |
Research Approach
Multi-period observation of headset procurement volumes, content studio investment flows, and METI subsidy allocation patterns anchored the trend analysis, supplemented by interviews with developer studio technical directors, enterprise training procurement managers, location-based entertainment operators, optical system engineers, and METI policy officers. Secondary validation drew from JIS certification databases, PMDA device filings, hyperscaler edge computing capex disclosures, and regional industrial cluster development reports. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-weighting approaches distributed value across technology tiers, product type mix, end-user procurement authority, and distribution channel structure. Modeled dimensions spanned standalone versus PC-tethered versus console-based deployment, hardware versus software versus accessories revenue, enterprise versus residential versus developer end-use, and B2B direct versus online retail versus offline retail channel. CAGRs derived from fitted growth curves applied to base-year estimates, incorporating OLED microdisplay supply constraints, METI funding round timing, and enterprise training contract renewal cycles as industry-specific inputs.
Underlying measurement precision varies by segment; enterprise B2B contract values carry tighter precision than residential consumer estimates where online retail return rates introduce volatility. Forecasts reflect assumptions around METI subsidy continuity, OLED foundry capacity expansion, and motion sickness technical thresholds. Practitioners should monitor JIS certification timeline shifts, PMDA wellness gaming rulings, and cloud rendering infrastructure buildout for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Global Online Adventure Games Market
Gaming
Europe Video Game Software Market
Gaming
Global NFT Gaming Market
Gaming
Online Casual Games Market
Gaming
Mobile Gaming Market
Gaming
3D Gaming Technology Market
Gaming
SLG Game Market
Gaming
Latin America Mobile Gaming Market
Gaming
VR Racing Gaming Market
Gaming
North America Gaming Hardware and Accessories Market
Gaming
Gaming Peripheral Market
Gaming
Global Gaming Market
Gaming
Gaming Accessories Market
Gaming
Mobile and Handheld Gaming Market
Gaming
Middle East and Africa Gaming Headsets Market
Gaming
Galgames Market